
 Electric Trolling Motors Market | 2026-2036
Electric Trolling Motors Market Size, Share, and Industry Trends Forecast 2026-2036
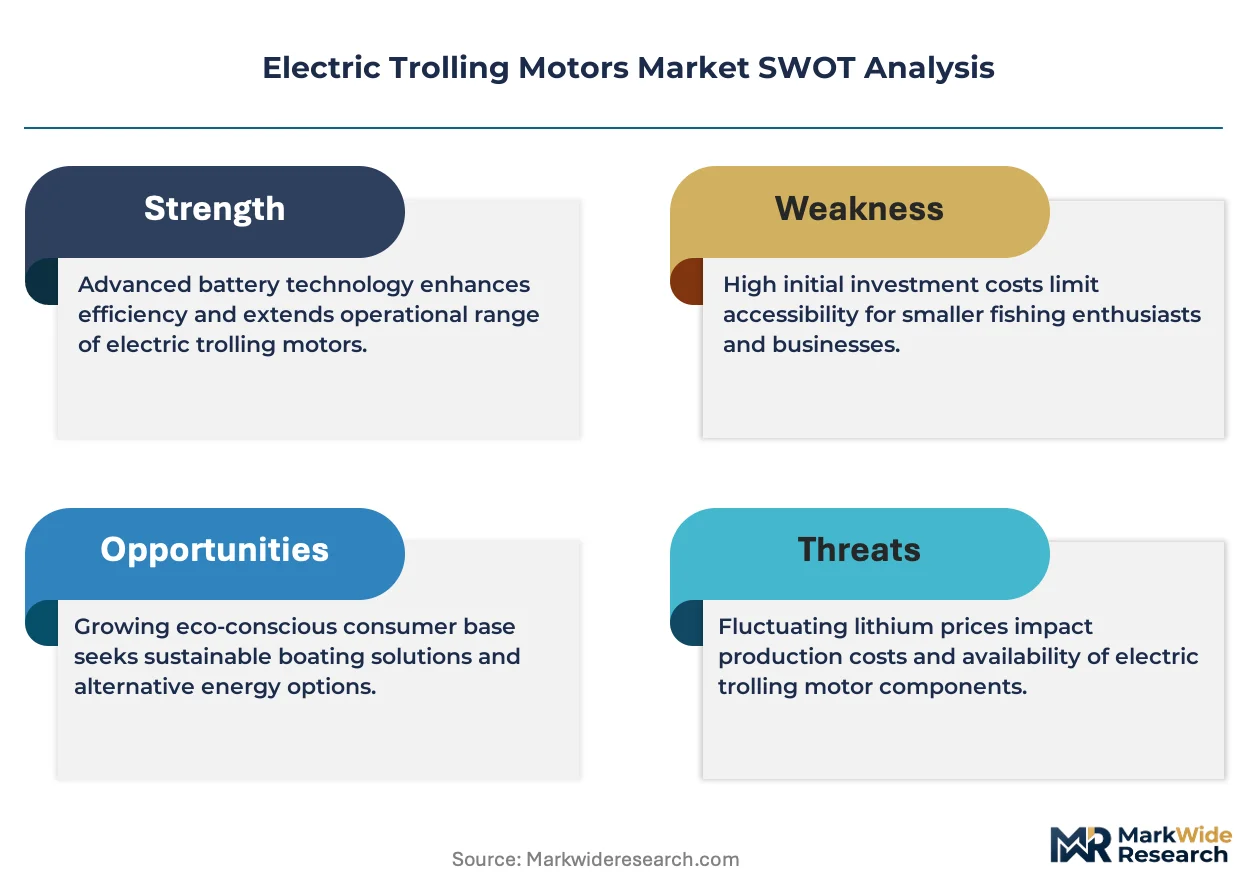
Electric Trolling Motors Market Analysis
Chinese brushless motor manufacturing capacity is hardening as domestic producers scale permanent-magnet rotor output for marine propulsion. Minn Kota leverages integrated sonar-GPS trolling systems to sustain brand loyalty among tournament anglers across North American freshwater circuits. Torqeedo anchors its position through deep-cell lithium battery architecture optimized for saltwater corrosion resistance in European and Australian cruising markets.
Electric trolling motors are sub-thrust marine propulsion units, typically delivering 30 to 112 pounds of thrust through 12V to 48V DC brushless or brushed motor architectures, designed for precise low-speed boat positioning and silent maneuvering during fishing operations. Bow mount configurations dominate margin pools due to integrated pedal-steer and wireless remote demand from competitive bass anglers, while smartphone-controlled interfaces represent the fastest-growing control type as younger demographics replace legacy cable-steer systems. The 36V power rating tier is gaining share as lithium battery packs displace lead-acid banks in mid-size fishing vessels, reducing overall system weight by substantial margins.
The US Coast Guard enforces electrical system safety standards for small craft under 65 feet, while the EPA administers Clean Vessel Act grants that subsidize electric propulsion adoption in designated no-combustion zones. The EU Marine Equipment Directive and ISO 8846 ignition protection standards constrain product design for saltwater export markets, filtering out uncertified manufacturers from European distribution channels. Stakeholders must monitor battery recycling mandates and rare-earth supply chain disclosures as regulatory scope widens from product safety to full lifecycle accountability.
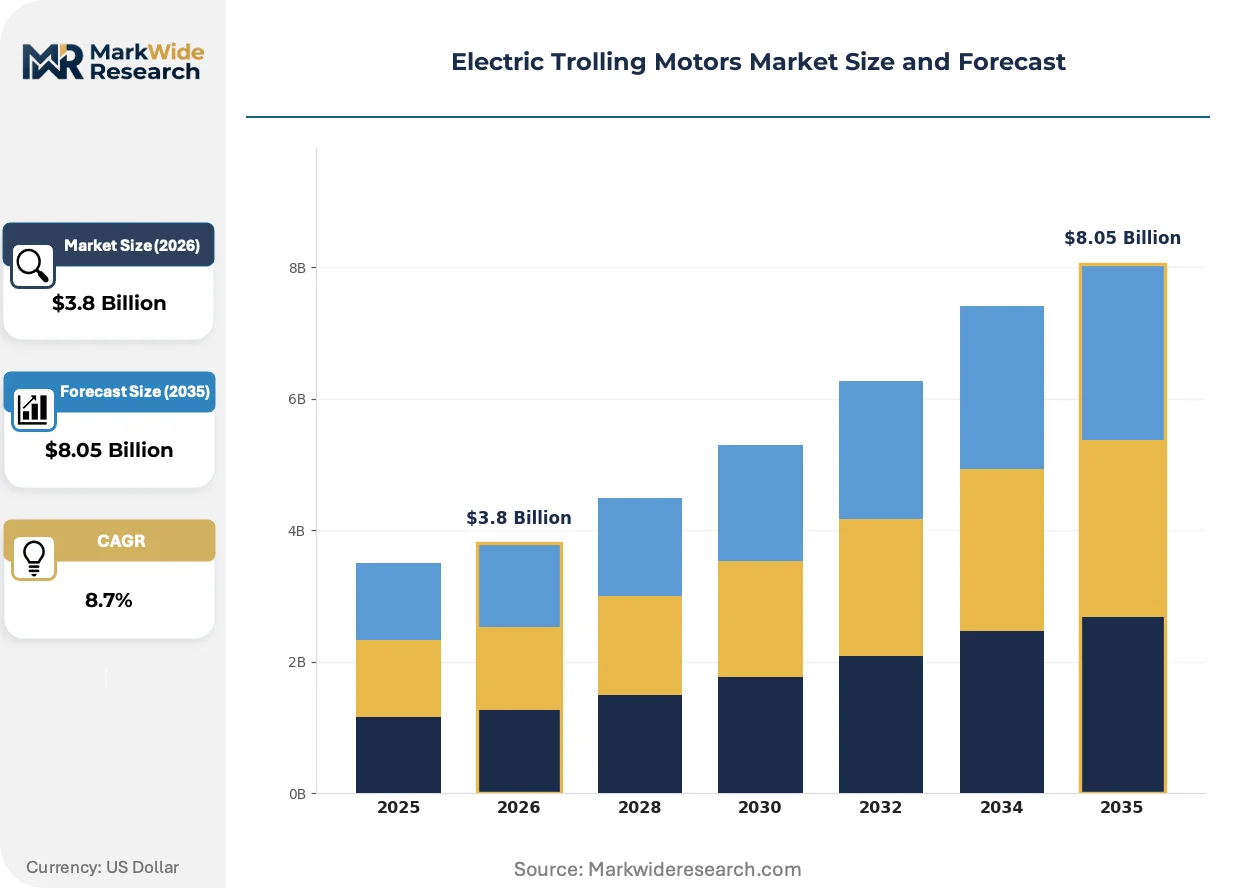
Market Dynamics
Lithium-ion battery chemistry improvements are compressing replacement cycles across freshwater and saltwater angling fleets, while brushless motor efficiency gains redistribute power-to-weight ratios across voltage tiers. Tournament anglers now demand integrated sonar-GPS positioning systems that eliminate manual boat control.
Growth Catalysts
- Clean Vessel Act grants:EPA subsidies for electric propulsion in no-combustion zones accelerate municipal procurement across designated US waterways.
- Brushless permanent-magnet rotors:Chinese manufacturing scale reduces unit costs for 36V and 48V motor architectures serving mid-size vessels.
- Bass tournament circuits:Competitive angling fleets in the Great Lakes and Southeastern coastal states standardize GPS-guided bow-mount systems for precise positioning.
Market Restraints
- Rare-earth magnet supply:Neodymium price volatility constrains permanent-motor production cost predictability for manufacturers dependent on Chinese raw material flows.
- ISO 8846 certification barriers:Ignition protection standards filter uncertified producers from European saltwater distribution channels, limiting market entry.
- Lead-acid battery substitution:Price-sensitive leisure anglers in price-tier segments delay lithium conversion, extending legacy system lifecycles.
Strategic Opportunities
- Kayak angling expansion:Compact 12V trolling motor demand from paddle-craft anglers creates new volume tiers in US inland waterway recreation.
- EU Marine Equipment Directive alignment:Saltwater corrosion-resistant product lines open cruising market penetration in Mediterranean and Baltic boating corridors.
- Smartphone control convergence:Wireless remote integration with mobile mapping applications displaces cable-steer legacy systems among demographic replacements.
Industry Challenges
- Deep-cell lithium engineering talent:Battery thermal management and saltwater corrosion expertise scarcity constrains R&D velocity for integrated system manufacturers.
- US Coast Guard electrical safety compliance:Small craft certification timelines extend product launch cycles, compressing margin recovery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Trolling Motors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transom Mount, Bow Mount, Engine Mount, Hand-Controlled Power Rating: 12V, 24V, 36V, 48V Control Type: Remote Control, Foot Control, Hand Control, Smartphone-Controlled Boat Type: Small Boats, Fishing Vessels, Sailboats, Pontoon Boats |
| Companies Covered | Minn Kota, MotorGuide, Garmin, Lowrance, Torqeedo, Newport Vessels, Power-Pole, Rhino, Mercury Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Trolling Motors Market Emerging Trajectories
Silent maneuvering requirements from competitive anglers are compressing control system architectures toward wireless integration. Battery management systems and motor controllers now merge into unified power electronics platforms.
Brushless DC motor controllers with integrated battery management are decentralizing power system architecture across fishing vessel designs. Tournament anglers in Florida and Texas circuits adopt these integrated units at accelerated replacement cycles. This convergence is decentralizing the traditional separation between motor manufacturers and battery suppliers, collapsing subsystem procurement decisions into single-vendor relationships.
REACH substance restrictions and RoHS compliance deadlines are forcing redesigns of electronic housing materials and potting compounds used in saltwater motor assemblies. European distributors now require full material disclosure documentation before listing new products. Saltwater-rated product lines face the tightest compliance timelines, with manufacturers accelerating fluoropolymer seal testing to maintain market access.
Angler purchasing behavior is fragmenting across direct-to-consumer channels and specialty marine retailers, with younger demographics bypassing traditional dealer networks for manufacturer-direct smartphone app configuration. Specialty bass pro shops in Alabama and Tennessee retain loyalty among older cable-steer replacement buyers. This channel split is most pronounced in the Southeastern United States, where tournament participation rates concentrate purchasing influence among digitally native competitors.
Electric Trolling Motors Market Segmentation
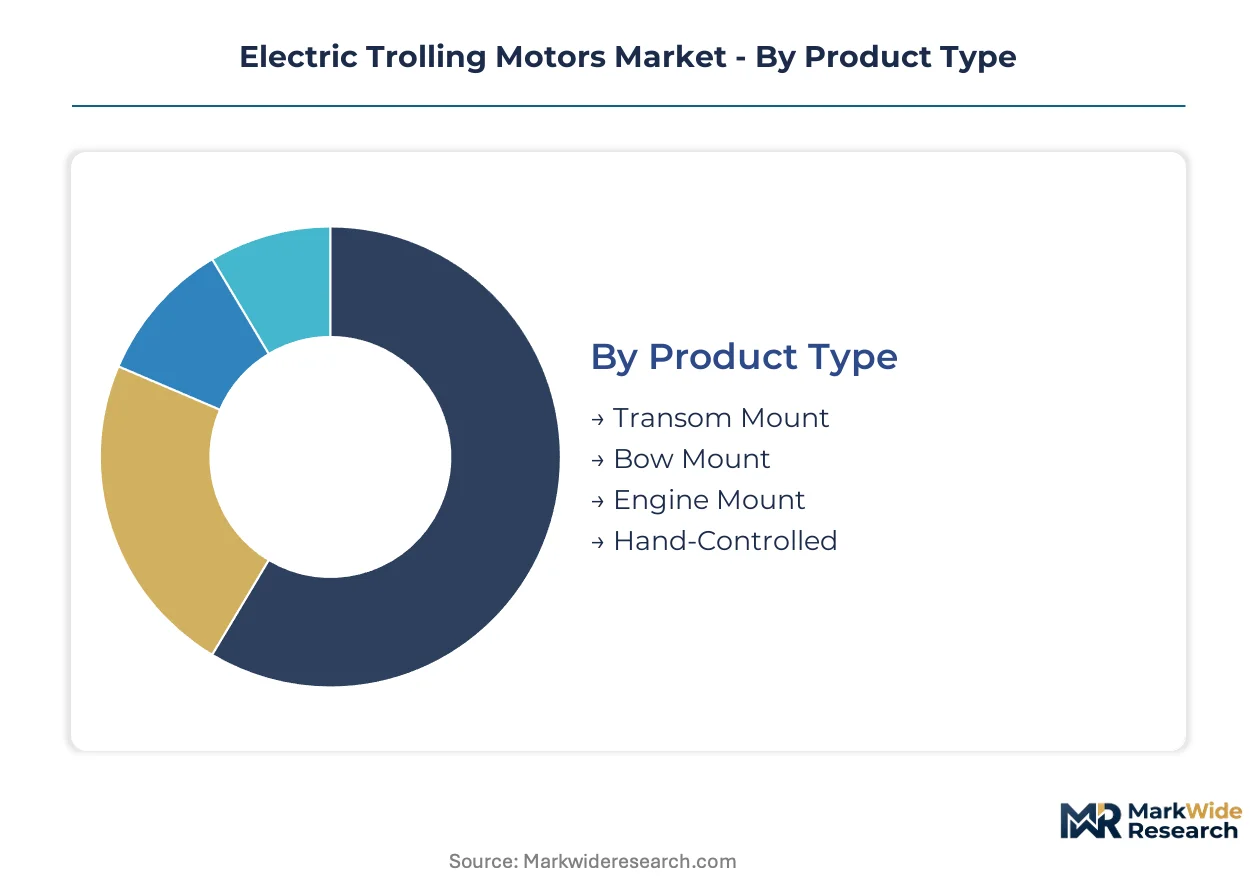
Segmentation in electric trolling motors reflects divergent replacement cycles across angling disciplines. Voltage tier migrations and control interface preferences now drive procurement timing more than hull compatibility alone.
Product Type:
Bow-mount systems command replacement priority among competitive anglers upgrading from cable-steer legacy units.
- Bow Mount:Integrated pedal-steer and GPS anchor-lock architectures dominate tournament bass circuits. Demand clusters in Great Lakes states and Florida where precise boat positioning determines competitive outcomes.
- Transom Mount:Clamp-on brackets serve utility anglers and secondary propulsion needs on multi-purpose hulls. Saltwater inshore fleets in Texas and Louisiana favor these for backup maneuvering in skinny water.
- Engine Mount:Kicker-motor integration suits sailboat auxiliaries and displacement cruisers requiring minimal cockpit intrusion.
- Hand-Controlled:Tiller-steer units persist among price-tier kayak anglers and rental fleet operators prioritizing mechanical simplicity.
Volume placements concentrate in Bow Mount; the faster expansion belongs to Engine Mount as auxiliary electrification spreads beyond fishing applications.
Power Rating:
Voltage tier selection tracks lithium battery conversion timing among mid-size vessel owners shedding lead-acid weight.
- 36V:Three-bank lithium configurations now displace 24V lead-acid systems in 18-22 foot bass boats. Runtime extension and weight reduction drive replacement decisions across Alabama and Tennessee tournament circuits.
- 48V:High-thrust architectures serve offshore-capable center consoles and catamarans where dual-motor redundancy matters. Saltwater corrosion-resistant housings add cost but open Australian and Mediterranean cruising markets.
- 12V:Single-bank systems anchor kayak and small jon-boat segments where portability trumps endurance.
- 24V:Transitional voltage tier retains installed base among legacy hulls not yet rewired for higher-amperage battery management.
Procurement volume tilts toward 36V; 48V climbs the fastest as lithium cell costs compress high-voltage accessibility.
Control Type:
Interface selection separates demographic cohorts more sharply than hull type or fishing discipline.
- Smartphone-Controlled:Wireless Bluetooth integration with mapping applications attracts digitally native competitors under 40. Manufacturers now bundle app-based route recording and waypoint sharing as standard.
- Foot Control:Pedal-steer mechanisms retain loyalty among tournament veterans in Southeastern circuits where hands-free operation enables simultaneous casting and boat positioning.
- Remote Control:Wireless fobs suit pontoon and family fishing configurations where multiple anglers rotate steering duties.
- Hand Control:Tiller-mounted switches persist in rental fleets and price-sensitive freshwater segments.
Foot Control maintains placement density; Smartphone-Controlled gains share fastest as OEMs sunset cable-steer production lines.
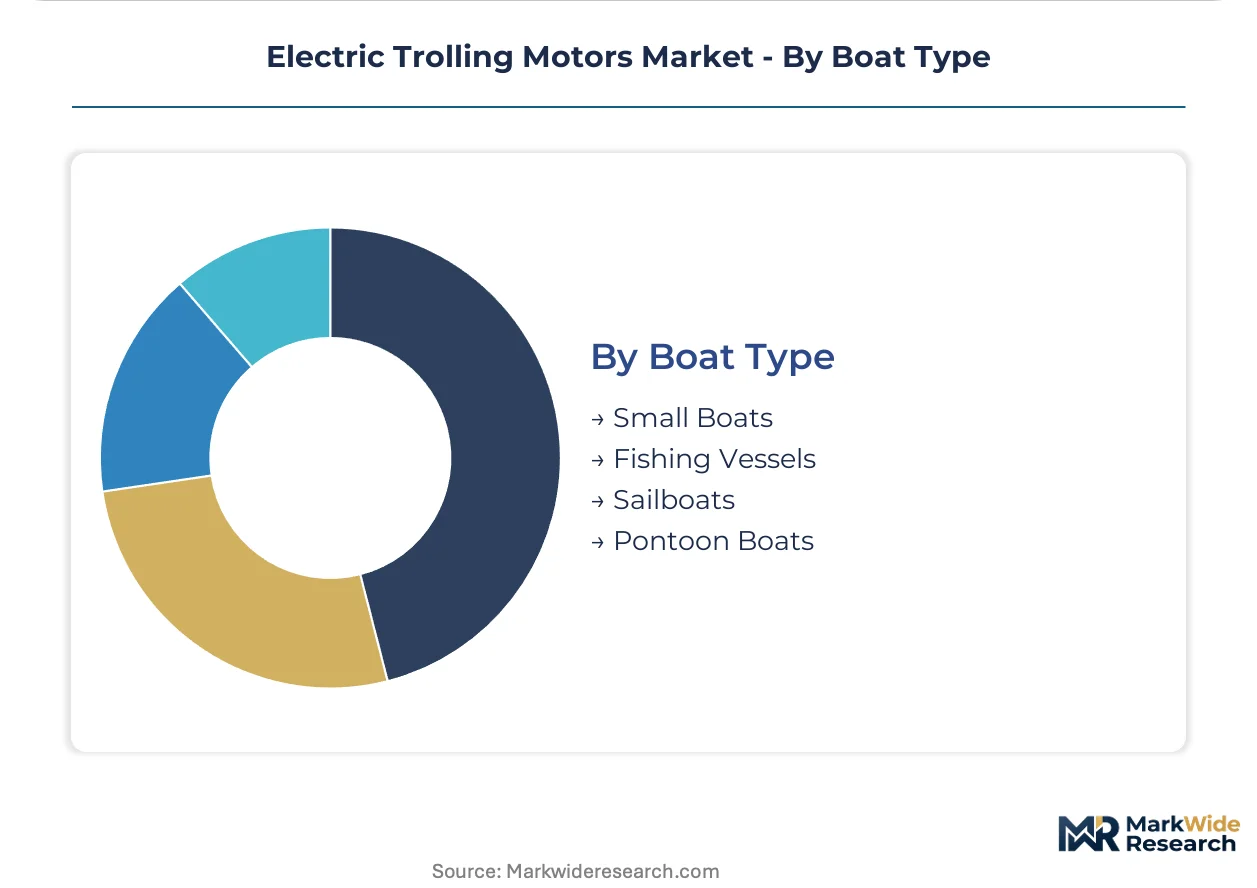
Boat Type:
Hull-specific motor sizing reflects regional waterway characteristics and species-targeting behaviors.
- Fishing Vessels:Bass boats and bay boats drive premium bow-mount penetration. Tournament anglers in Texas and Florida standardize integrated sonar-motor systems for competitive advantage.
- Small Boats:Jon boats, skiffs, and utility hulls populate inland waterway recreation across the Midwest. Transom-mount electrification spreads as Clean Vessel Act grants subsidize municipal fleet conversions.
- Pontoon Boats:Deck-boat anglers favor dual-motor configurations combining trolling precision with main-engine efficiency.
- Sailboats:Auxiliary propulsion requirements favor engine-mount and low-thrust transom options for marina maneuvering.
Fishing Vessels anchor procurement volume; Small Boats show steepest expansion as kayak angling participation broadens the addressable hull base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium mining corridors in China's Inner Mongolia and Jiangxi provinces anchor permanent-magnet supply chains for brushless motor manufacturing. Battery cell production clusters in South Korea and Japan shape voltage tier availability across export markets. Tournament angling circuits and coastal cruising regulations then determine regional demand intensity.
United States
Bass tournament circuits in Alabama and Tennessee drive 36V bow-mount procurement cycles. EPA Clean Vessel Act grants subsidize electric propulsion conversions in Florida's no-combustion zones. The Great Lakes region concentrates freshwater angling fleet replacements around integrated sonar-GPS systems.
China
Brushless motor manufacturing scales in Guangdong and Zhejiang provinces serve global OEM supply chains. MIIT industrial standards govern permanent-magnet rotor efficiency certifications for marine applications. Shenzhen-based electronics clusters export smartphone-control modules to North American and European assemblers.
Germany
Inland cruising on the Baltic Sea and Mediterranean corridors sustains demand for corrosion-resistant 48V architectures. REACH substance restrictions and RoHS compliance deadlines force housing material redesigns for saltwater-rated product lines. Hamburg marine equipment distributors require full material disclosure documentation before listing new motors.
Australia
Offshore-capable center console fleets in Queensland and New South Wales favor high-thrust 48V systems with dual-motor redundancy. The country's national maritime safety regulator enforces electrical system standards for small craft under 24 meters. Sydney and Melbourne boating clusters show accelerated lithium battery conversion timelines among cruising demographics.
Japan
Compact 12V and 24V systems serve aging leisure angler populations in inland reservoir fisheries. METI energy efficiency guidelines influence motor controller design specifications for domestic manufacturers. Nagoya industrial corridors host precision machining suppliers for permanent-magnet rotor assemblies.
Electric Trolling Motors Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue smartphone-control integration and lithium battery system convergence. The vendor base stratifies across three tiers: integrated system specialists bundling motor-battery-sonar architectures; component-focused manufacturers supplying brushless motors and controllers to third-party assemblers; and regional fabricators serving price-sensitive freshwater segments. Dominant competitive moves include strategic partnerships between motor manufacturers and battery cell suppliers, plus geographic expansion through EU Marine Equipment Directive certification investments.
Among North American-based integrated system specialists, Minn Kota and MotorGuide exemplify the tournament-angling tier with established freshwater circuit presence. Torqeedo anchors the European premium segment through deep-cell lithium architecture positioning. Garmin and Lowrance represent electronics convergence archetypes, leveraging sonar-GPS integration to collapse subsystem procurement decisions into unified vendor relationships.
| Leading Market Players |
|---|
| Minn Kota |
| MotorGuide |
| Garmin |
| Lowrance |
| Torqeedo |
| Newport Vessels |
| Power-Pole |
| Rhino |
| Mercury Marine |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between ISO 8846 saltwater-rated systems and freshwater-only units manifests in both pricing power and supply chain sourcing strategies. Premium corrosion-resistant architectures command substantial markups while tethering manufacturers to specialized Japanese and German sealant suppliers; commodity freshwater tiers compete on brushless motor unit costs anchored in Chinese permanent-magnet rotor output.
Pricing Analysis
Warranty bundling separates premium from standard tiers, with saltwater-rated systems including five-year corrosion coverage against freshwater units carrying limited mechanical guarantees. Three-tier pricing structure across premium, standard, and economy levels tracks voltage architecture and control interface sophistication, with smartphone-integrated 48V systems at the apex. Pricing pressure stems from lithium cell cost compression enabling mid-tier buyers to access previously premium voltage configurations. Tournament anglers show lowest price sensitivity, prioritizing GPS-anchor precision over acquisition cost; rental fleet operators and casual kayak anglers drive volume at economy tiers.
Supply Chain Analysis
Neodymium permanent-magnet supply rests on Chinese mining corridors in Inner Mongolia and Jiangxi provinces, with secondary processing clusters in South Korea and Japan. Brushless motor controllers draw from Shenzhen electronics manufacturing, while deep-cell lithium battery cells source primarily from South Korean and Japanese chemistry specialists. Single-source vulnerability concentrates in rare-earth magnet refining, where Chinese export licensing creates tariff exposure for non-domestic assemblers. Distribution runs through specialty marine retailers in the Southeastern United States and Hamburg-based European distributors requiring REACH documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent-magnet rotor manufacturing capacity constraints in compliant supply chains prop pricing stability for certified producers, insulating premium tiers from commodity erosion.
For Market Incumbents: Lock in long-term offtake agreements with Jiangxi and Inner Mongolia rare-earth processors before export licensing tightens. Prioritize backward integration into battery management system firmware to defend against electronics convergence threats from sonar-GPS OEMs. Accelerate EU Marine Equipment Directive certification investments to filter price-competitive Chinese challengers from Mediterranean distribution channels. For New Entrants and Emerging Players: Direct-to-consumer smartphone app configuration routes bypass entrenched dealer networks in the Great Lakes region, where younger demographics already disintermediate legacy cable-steer replacement cycles. Target kayak angling segments in Alabama and Tennessee inland waterways with compact 12V systems, where tournament infrastructure is sparse and price elasticity permits margin capture. Pursue white-label supply contracts with Shenzhen controller specialists to compress R&D timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated marine electronics platforms seeking motor-battery-sonar convergence. Five-to-ten year viability favors manufacturers with captive lithium thermal management expertise and saltwater corrosion engineering depth. Monitor EPA Clean Vessel Act grant allocation velocity as inflection signal for municipal fleet procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Management System Integration | Unifies motor controller and cell monitoring into single-vendor procurement relationships. |
| EU Marine Equipment Directive Certification | Opens Baltic and Mediterranean cruising corridors to saltwater-rated product lines. |
| Direct-to-Consumer Channel Launch | Bypasses Alabama and Tennessee dealer networks for digitally native competitor segments. |
| Rare-Earth Magnet Supply Agreement | Secures neodymium rotor output from Jiangxi processors against export restriction risk. |
| Smartphone Control Platform Development | Displaces cable-steer legacy systems through Bluetooth waypoint sharing and route recording. |
Methodological Framework
Multi-period observation of tournament angler procurement cycles, lithium battery conversion timing, and EPA grant allocation velocity anchored the trend analysis, supplemented by interviews with bass circuit competitors, marine electronics distributors, brushless motor procurement leads at OEMs, and lithium cell thermal management engineers. Secondary validation drew from US Coast Guard small craft electrical safety filings, EPA Clean Vessel Act grant disbursement records, EU Marine Equipment Directive certification databases, and customs trade data on permanent-magnet rotor imports. Bottom-up hull-type demand modeling and top-down voltage tier penetration rates underwent cross-triangulation.
Segment-weighting across product type, power rating, control interface, and boat hull configuration determined value distribution through the projection horizon. CAGRs derived from replacement cycle compression rates and lithium cost curve trajectories, with tournament participation growth and municipal fleet electrification grant velocity as marine-specific forecast inputs. Bass boat and bay boat penetration assumptions calibrated against Great Lakes and Southeastern state registration data.
The model holds under stable rare-earth export licensing and continued lithium cell cost compression; deviation in neodymium price volatility or EPA grant suspension would shift replacement timing assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Electric Motor Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Voice Coil Motor Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Car Charger Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market
Electric Motor
Automotive in-Wheel Motors Market
Electric Motor
Implant Motors Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
E-Bike Motor Market
Electric Motor
Kayak Trolling Motor Market