
 UK Hair Transplant Market | 2026-2036
UK Hair Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
UK Hair Transplant Market Insights
CQC registration for surgical premises is rotating the competitive landscape toward accredited operators. The Maitland Clinic leverages its Hampshire base to sustain a reputation for large-session FUE work. Harley Street Hair Transplant Clinics anchors premium positioning through central London accessibility and consultant-led protocols. KSL Clinic competes via multi-site coverage across the Midlands and northern England.
UK hair transplant services involve the surgical redistribution of autologous follicular units from donor-stable scalp zones to recipient areas of androgenetic or traumatic alopecia, typically performed under local anaesthesia with graft survival rates contingent on extraction technique, ischaemia time, and implanter instrumentation. Follicular Unit Extraction dominates procedure volume due to reduced linear scarring and faster recovery trajectories, while Robotic Hair Transplant occupies a narrower but expanding premium tier where precision mapping justifies higher price points. Direct Hair Implantation differentiates select operators through immediate graft placement without pre-made incisions, though its adoption remains concentrated among clinics with dedicated Choi implanter training pipelines.
The Care Quality Commission regulates clinic premises and surgical governance in England, while Healthcare Improvement Scotland and Healthcare Inspectorate Wales perform equivalent oversight functions, collectively mandating infection control protocols and surgeon credentialing that filter substandard entrants. MHRA guidance on medical device standards for automated extraction systems further shapes equipment procurement decisions. Stakeholders must monitor whether CQC enforcement intensity tightens further and how that reshapes consolidation incentives among independent clinic groups.
Market Dynamics
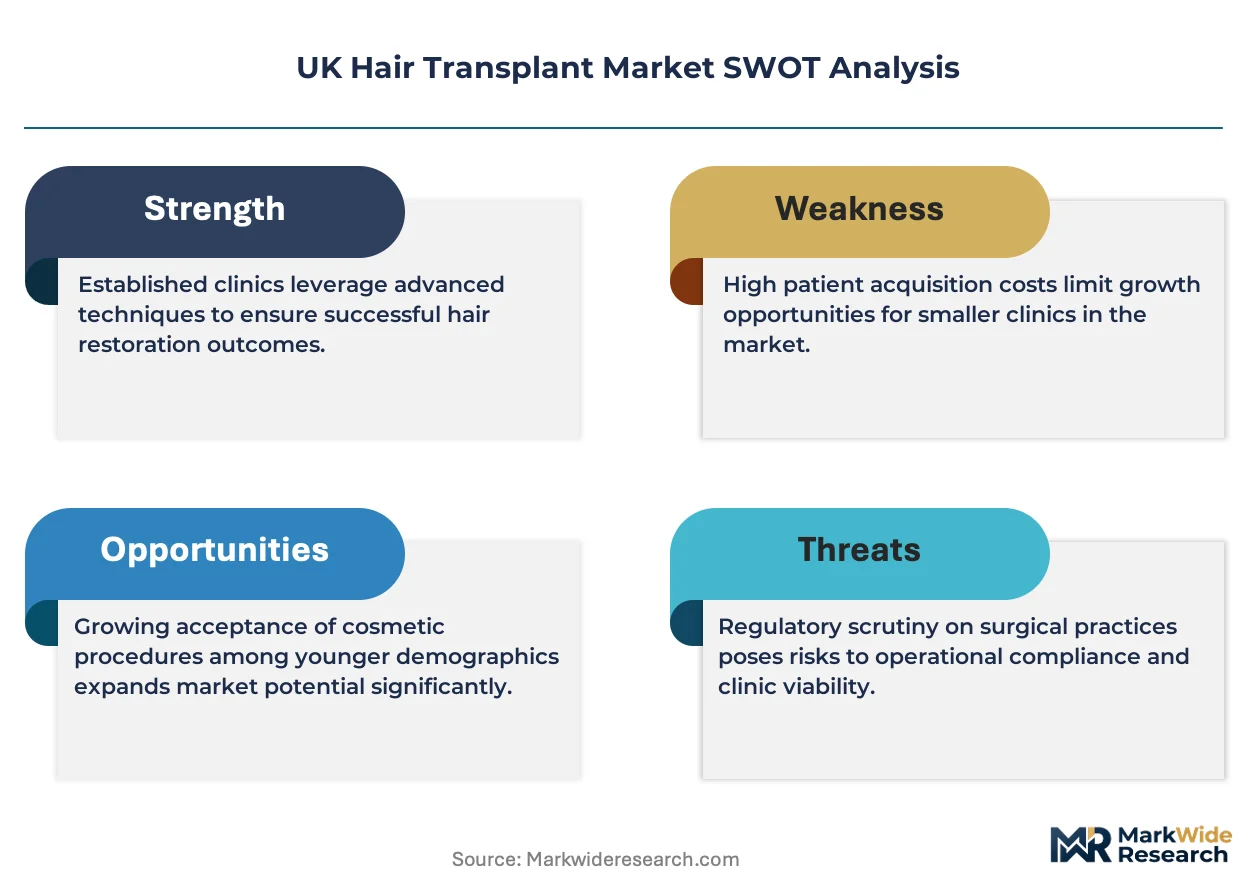
Care Quality Commission enforcement intensity is compressing the operator base toward accredited surgical premises, filtering substandard entrants while elevating compliance costs for independents seeking registration renewal.
Growth Catalysts
- FUE Technique Maturation:Follicular Unit Extraction protocols now deliver reduced linear scarring and faster recovery trajectories, pulling younger male demographics into surgical candidacy.
- Cross-Border Patient Flows:Greater London and Manchester clinic clusters capture European patients seeking English-speaking surgical environments with CQC-governed safety standards.
- Choi Implanter Training Pipelines:Direct Hair Implantation certification programs at select UK academies are expanding operator pools capable of immediate graft placement without pre-made incisions.
Market Restraints
- Donor Scarcity Constraints:Finite occipital scalp reserves limit graft yields for advanced Norwood-stage patients, capping revenue per procedure.
- MHRA Device Compliance Burden:Automated extraction systems face extended approval timelines, delaying robotic platform adoption.
- Non-Surgical Substitution:Oral 5-alpha-reductase inhibitors and topical minoxidil formulations retain first-line status for early-stage androgenetic alopecia.
Strategic Opportunities
- Scotland and Wales Expansion:Healthcare Improvement Scotland and Healthcare Inspectorate Wales oversight frameworks create parallel accreditation pathways with less saturated competitive density.
- Female Pattern Hair Loss:Diffuse thinning presentations in peri-menopausal demographics remain underserved relative to male-focused marketing.
- Telemedicine Consultation Channels:Remote trichoscopic assessment protocols reduce geographic friction for initial patient qualification.
Industry Challenges
- Surgeon Credentialing Bottlenecks:CQC-mandated surgical governance standards strain training capacity for follicular unit dissection and implantation.
- Graft Ischaemia Management:Extended extraction-to-implantation windows compromise survival rates in high-volume sessions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Hair Transplant Market |
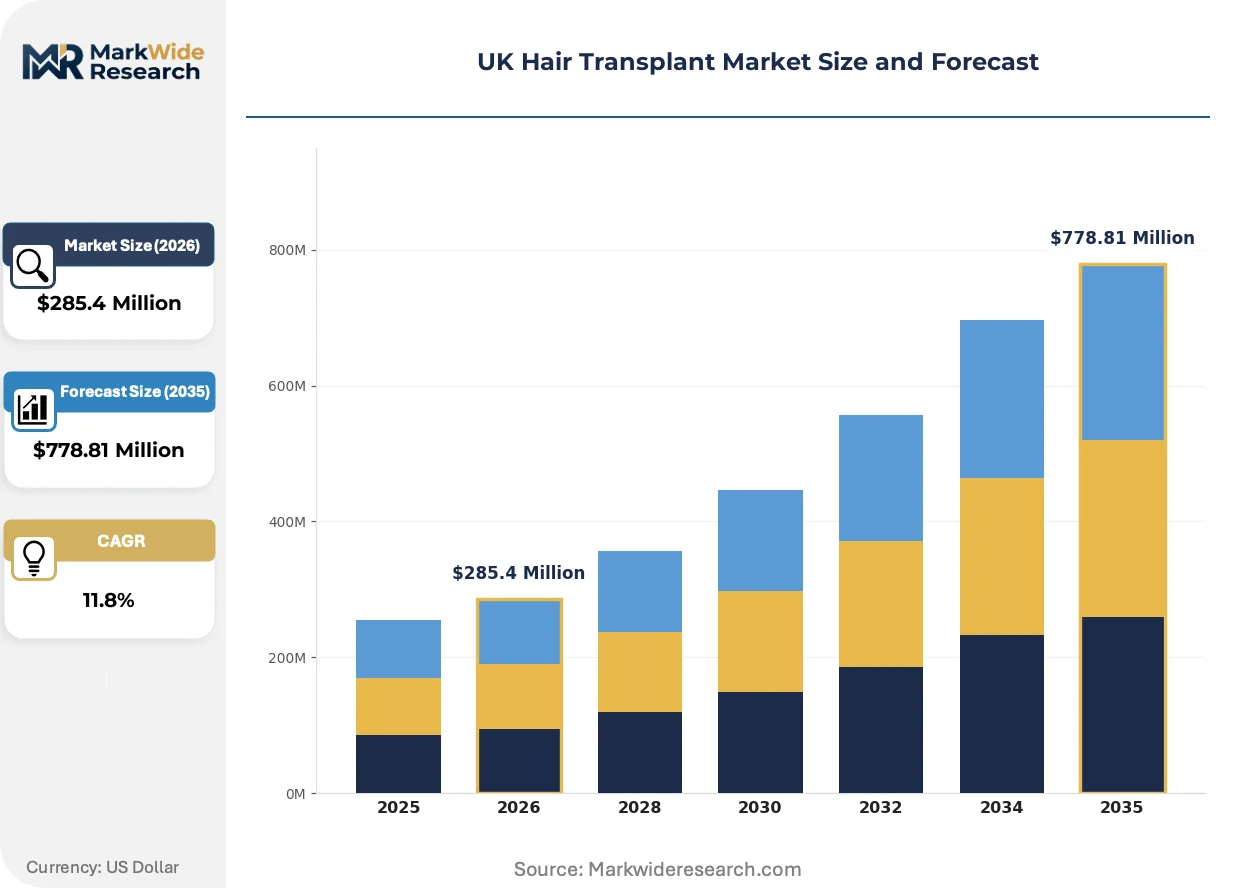
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $778.81 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Follicular Unit Extraction, Follicular Unit Transplantation, Direct Hair Implantation, Scalp Micropigmentation, Robotic Hair Transplant Hair Loss Cause: Androgenetic Alopecia, Alopecia Areata, Traction Alopecia, Telogen Effluvium, Scarring Alopecia End User: Specialty Clinics, Cosmetic Surgeons, Dermatology Centers, Private Hospitals, Medical Spas Service Model: Outpatient Surgery, Day Care Procedure, Minimally Invasive Treatment, Conventional Surgery, Non-Surgical Therapy |
| Companies Covered | The Maitland Clinic, Harley Street Hair Transplant Clinics, KSL Clinic, Farjo Hair Institute, Wimpole Clinic, British Hair Clinic, Manchester Hair Transplant Clinic, Harley Street Hair Clinic, HHC Clinics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Hair Transplant Market Trends and Innovations
Precision instrumentation and regulatory digitization are reshaping how UK clinics compete on outcomes and transparency. Three developments merit particular attention.
Robotic hair transplant platforms are fragmenting the premium tier. ARTAS and comparable systems enable precision mapping of donor zones with reduced transection rates. High-net-worth patients in Harley Street and Manchester clusters are selecting robot-assisted protocols despite price premiums of forty to sixty percent above manual FUE. This technology is fragmenting the market into precision-branded and artisan-branded operator segments.
CQC digital inspection frameworks are tightening real-time compliance documentation. Surgical premises must now maintain electronic patient safety incident logs accessible to inspectors within forty-eight hours. Greater London clinics with established quality management systems absorb these requirements with minimal friction, while smaller independents in the Midlands face operational reconfiguration costs.
After-care service unbundling is altering patient lifetime value calculations. Traditional inclusive packages covering twelve-month follow-up are giving way to modular pricing where platelet-rich plasma adjuncts and trichology maintenance carry separate fees. This shift is most visible among South East corridor operators targeting younger patients with lower initial surgical budgets but higher willingness to purchase ongoing maintenance.
UK Hair Transplant Market Segmentation
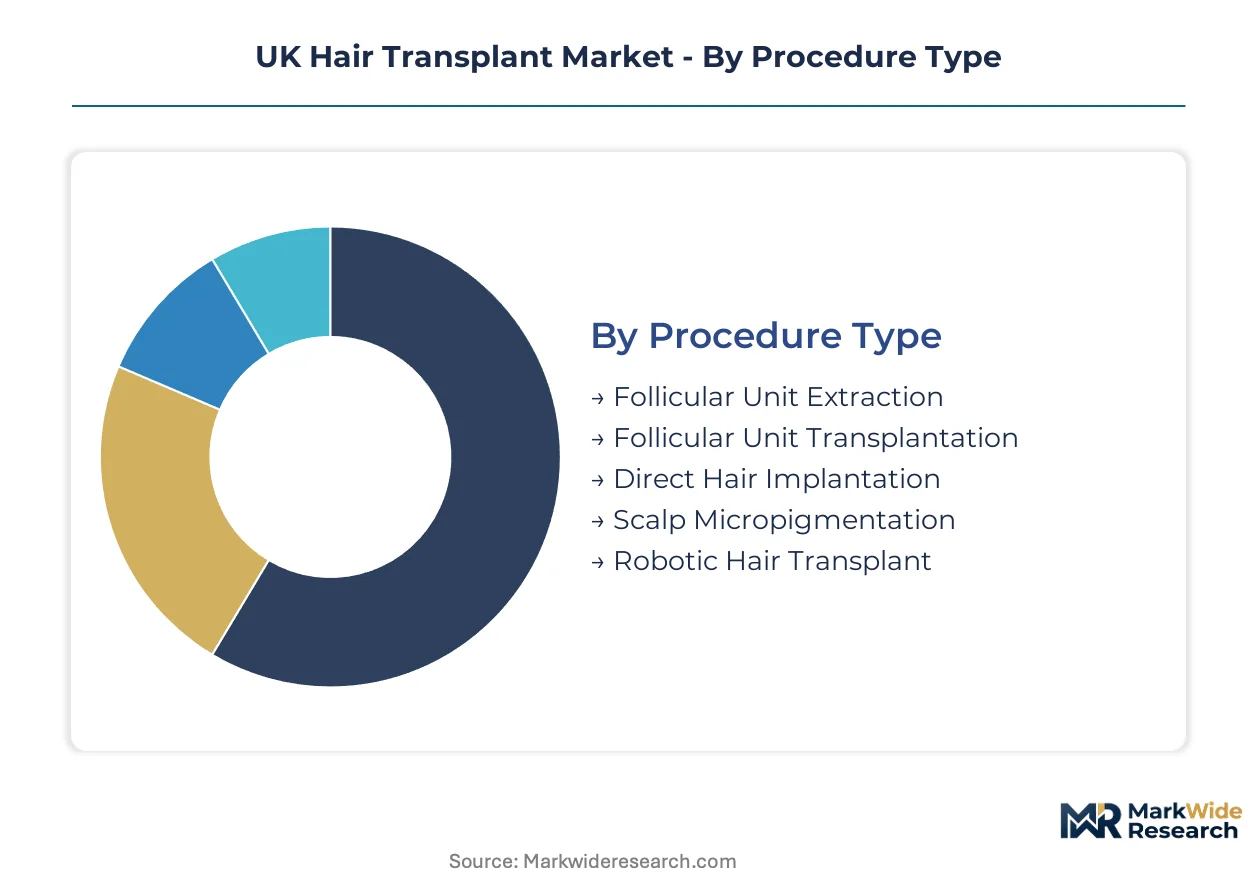
Segmentation in the UK hair transplant market reveals how procedure economics, patient demographics, and facility licensing interact to shape operator strategies. Understanding these divisions clarifies where CQC compliance costs concentrate and which service models attract cross-border patient flows.
Procedure Type:
Geographic demand patterns split sharply between domestic NHS-referred patients seeking cost-contained solutions and private Harley Street clientele pursuing premium techniques with minimal downtime.
- Follicular Unit Extraction:Manual punch extraction of individual follicular units from donor zones leaves no linear scar and permits shorter recovery windows. Demand concentrates among men aged 25-35 in Greater London and Manchester who prioritize discreet healing over graft yield maximization. FUE protocols now dominate UK procedure volume due to reduced social downtime.
- Robotic Hair Transplant:ARTAS and comparable platforms execute precision donor mapping with sub-millimeter accuracy and reduced transection rates. Harley Street and Manchester premium clusters capture high-net-worth patients accepting forty to sixty percent price premiums for algorithm-guided extraction consistency.
- Follicular Unit Transplantation:Strip harvesting from occipital scalp enables higher graft yields per session through microscopic dissection of follicular units.
- Direct Hair Implantation:Choi implanter pens permit immediate graft placement without pre-made recipient incisions, requiring specialized operator training pipelines.
- Scalp Micropigmentation:Cosmetic tattooing creates shaved-head illusion for patients with insufficient donor reserves or those rejecting surgical candidacy.
Follicular Unit Extraction commands the established base. The steepest expansion runs through Robotic Hair Transplant.
Hair Loss Cause:
Cost tier stratification emerges clearly: androgenetic pattern baldness attracts premium surgical intervention while diffuse thinning conditions default to pharmaceutical first-line therapy.
- Androgenetic Alopecia:Dihydrotestosterone-driven miniaturization of terminal follicles produces patterned recession and vertex thinning. Male patients aged 25-45 in South East England and Greater London drive surgical candidacy, though oral 5-alpha-reductase inhibitors retain first-line status for early Norwood stages.
- Traction Alopecia:Mechanical follicle damage from tight hairstyles or extensions creates frontal and temporal hairline recession. Demand clusters among female patients of African and Afro-Caribbean descent in London and Birmingham seeking hairline restoration.
- Alopecia Areata:Autoimmune-mediated patchy hair loss responds poorly to transplantation due to ongoing inflammatory activity in recipient zones.
- Telogen Effluvium:Stress or metabolic-triggered diffuse shedding typically self-resolves, limiting surgical intervention to persistent chronic cases.
- Scarring Alopecia:Primary cicatricial disorders destroy follicular stem cells, rendering transplantation viable only in burned-out stable phases with dermatology clearance.
Androgenetic Alopecia commands the established base. The steepest expansion trajectory runs through Traction Alopecia.
End User:
Volume concentration follows CQC registration density: standalone surgical premises absorb the majority of high-session procedures while hospital-based operators handle complex reconstruction cases.
- Specialty Clinics:Dedicated hair restoration facilities maintain surgical governance protocols and specialized nursing teams for large-session FUE. The Maitland Clinic in Hampshire and Harley Street Hair Transplant Clinics exemplify this model, drawing domestic and European cross-border patients.
- Private Hospitals:Full surgical infrastructure supports complex cases combining hair transplantation with scalp reconstruction or prior failed procedure correction. These settings absorb patients requiring general anaesthesia or extended monitoring.
- Cosmetic Surgeons:Individual practitioners operating CQC-registered premises compete on consultant-led protocols and personalized continuity of care.
- Dermatology Centers:Trichology-focused practices prioritize medical management and refer surgical candidates to accredited transplant operators.
- Medical Spas:Non-surgical aesthetic venues concentrate on PRP adjuncts and low-level laser therapy rather than surgical grafting.
Specialty Clinics command the established base. The steepest expansion runs through Private Hospitals.
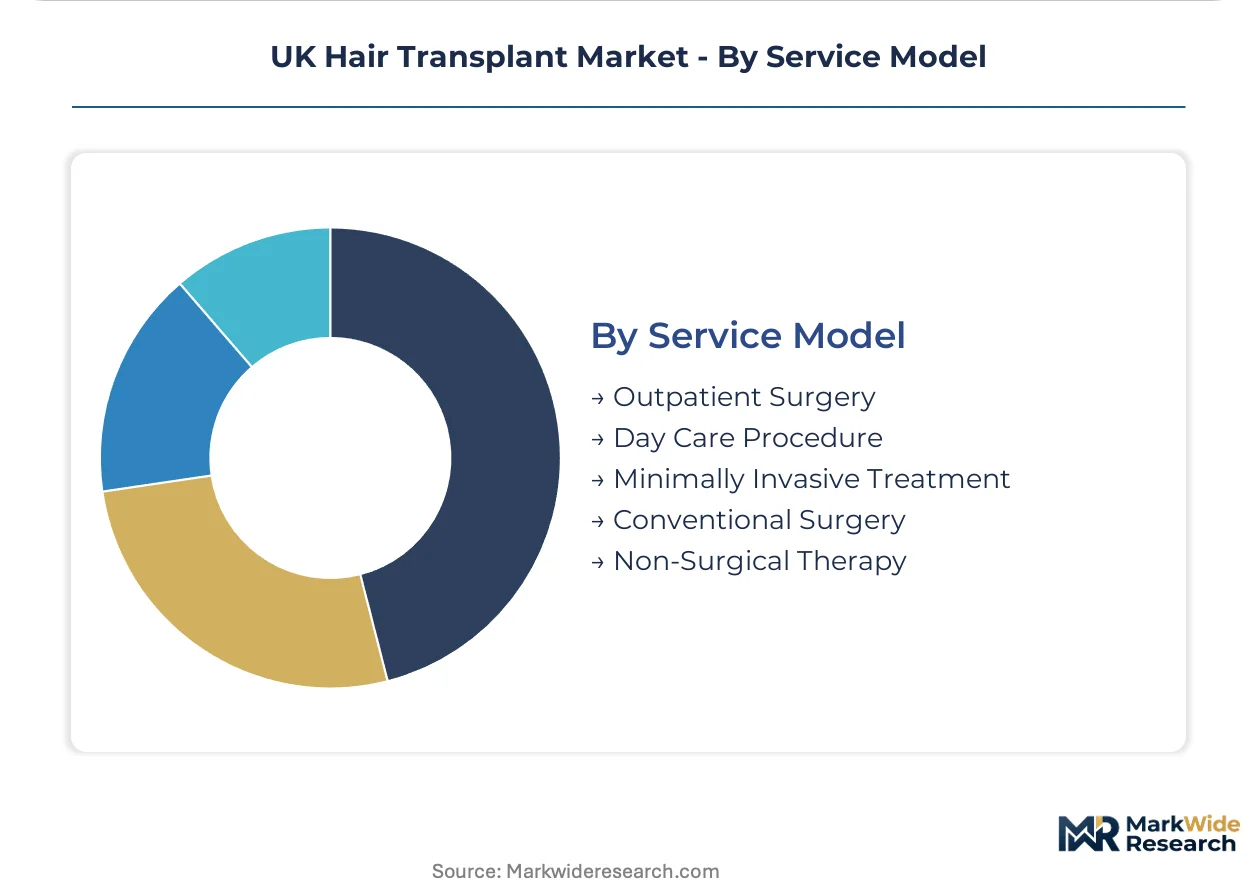
Service Model:
Margin structures diverge dramatically: outpatient protocols maximize throughput and facility utilization while conventional surgery carries anaesthetist and overnight staffing costs.
- Outpatient Surgery:Local anaesthesia protocols with same-day discharge dominate UK hair transplant economics. South East corridor operators have refined four-to-eight-hour sessions permitting immediate return to accommodation, minimizing hotel costs for international patients.
- Minimally Invasive Treatment:Reduced-punch-diameter FUE and DHI techniques emphasize rapid healing and minimal social downtime. Younger demographics in London and Manchester select these protocols despite per-graft price premiums.
- Day Care Procedure:Extended monitoring for high-volume sessions or combined procedures requires four-to-six-hour post-operative observation.
- Conventional Surgery:Strip harvesting under sedation or general anaesthesia retains relevance for maximal graft yield in advanced Norwood stages.
- Non-Surgical Therapy:Pharmaceutical regimens, PRP injections, and laser devices capture patients below surgical candidacy thresholds or those deferring invasive intervention.
Outpatient Surgery commands the established base. The steepest expansion runs through Minimally Invasive Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Care Quality Commission registration requirements have concentrated surgical capacity in England's metropolitan corridors while creating parallel accreditation pathways in Scotland and Wales. This regulatory geography shapes where domestic and cross-border patients access restoration services.
Greater London and South East
Harley Street clinic clusters draw high-net-worth patients seeking consultant-led protocols with minimal social downtime. CQC digital inspection frameworks mandate forty-eight-hour electronic incident log accessibility, elevating operational costs for independent operators. The South East corridor sustains the highest procedure density per capita, with Manchester satellite clusters capturing northern demand.
Midlands
KSL Clinic's multi-site coverage exploits lower facility costs while maintaining CQC surgical governance standards. Birmingham and Leicester absorb patients from surrounding counties seeking shorter travel distances than London alternatives. The region's competitive density remains below southern England, permitting price positioning fifteen to twenty percent below Harley Street benchmarks.
North England
Manchester anchors the northern surgical corridor with dedicated hair restoration facilities competing on large-session FUE capacity. Leeds and Liverpool satellite operations capture Yorkshire and Merseyside patient flows. Northern clinics increasingly market to Scottish patients facing longer waits for NHS-referred procedures.
Scotland
Healthcare Improvement Scotland oversight frameworks create parallel accreditation pathways with less saturated competitive density than England. Edinburgh and Glasgow clinic clusters serve domestic demand while attracting cross-border patients from northern England. Scottish operators benefit from lower commercial property costs while matching English CQC-equivalent safety standards.
Wales
Healthcare Inspectorate Wales regulates a smaller surgical premises base with concentration in Cardiff and Swansea. Welsh clinics capture patients from Bristol and western England corridors seeking shorter appointment lead times. The regulatory environment filters substandard entrants while permitting faster registration timelines for accredited operators expanding from England.
UK Hair Transplant Market Competitive Landscape
Listed leaders compete with private specialists across geographic coverage and session scale. The operator base fragments between premium central London premises and regional volume players, with CQC registration intensity accelerating consolidation among mid-sized independents. Three archetypes dominate: Harley Street premium-positioned facilities, multi-site regional chains, and single-location high-volume specialists. Competitive moves concentrate on geographic expansion into underserved northern and Scottish markets, plus technology differentiation through robotic platform adoption.
Within the premium-tier vector, Harley Street Hair Transplant Clinics and Harley Street Hair Clinic occupy positions defined by central London accessibility and consultant-led protocols. The Maitland Clinic exemplifies the single-location high-volume archetype, leveraging its Hampshire base to sustain reputation for large-session FUE work. KSL Clinic represents multi-site regional expansion, competing via coverage density across Midlands and northern England rather than metropolitan premium positioning.
| Leading Market Players |
|---|
| The Maitland Clinic |
| Harley Street Hair Transplant Clinics |
| KSL Clinic |
| Farjo Hair Institute |
| Wimpole Clinic |
| British Hair Clinic |
| Manchester Hair Transplant Clinic |
| Harley Street Hair Clinic |
| HHC Clinics |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with CQC-registered surgical premises lock in both graft supply access and price visibility for multi-session operators across Greater London and Manchester clusters. These contractual structures insulate premium-tier clinics from spot-market volatility in surgeon availability while compressing margins for independents unable to secure equivalent facility commitments.
Pricing Analysis
Certification level creates the primary spread between Harley Street premium positioning and regional volume operators. Three-tier pricing structure across premium, standard, and economy levels reflects CQC registration status, robotic platform access, and consultant-led protocol differentiation. Cost compression in the economy tier intensifies as Midlands independents absorb compliance reconfiguration expenses. NHS-referred patients exhibit highest price sensitivity, while self-pay Harley Street clientele demonstrate minimal elasticity to forty-to-sixty percent robot-assisted premiums.
Supply Chain Analysis
Inventory cycles for Choi implanter pens and automated extraction platforms extend lead times to eight-to-fourteen weeks for UK operators. Equipment procurement draws from German precision manufacturers, South Korean medical device specialists, and US robotic platform developers. Single-source vulnerability concentrates in ARTAS system maintenance contracts and specialized punch instrumentation. Distribution runs through authorized medical device distributors with CQC-mandated traceability documentation rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. CQC registration requirements create switching costs that protect accredited operators from unlicensed competitors while elevating barriers for new market entrants.
For Market Incumbents: Compound CQC compliance advantages through multi-site accreditation across Scotland and Wales expansion corridors. Deepen surgeon training pipelines to address credentialing bottlenecks threatening session scalability. Acquire distressed Midlands independents facing renewal cost pressures to consolidate regional volume share.
For New Entrants and Emerging Players: Anchor in telemedicine consultation channels to reduce geographic friction for initial patient qualification. Target female pattern hair loss segments underserved by male-focused marketing archetypes. Pursue DHI certification partnerships with UK academies to differentiate immediate graft placement capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward CQC-registered regional chains with established surgeon governance protocols and cross-border patient capture mechanisms. Long-term viability hinges on consolidation runway among mid-sized independents facing compliance cost escalation. Monitor Healthcare Improvement Scotland enforcement intensity as signal for Scottish expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CQC Multi-Site Accreditation | Expands addressable patient base across England, Wales, and Scotland under unified governance standards. |
| Robotic Platform Deployment | Captures high-net-worth segments in Harley Street and Manchester willing to pay precision premiums. |
| Choi Implanter Training Pipeline | Builds operator capacity for DHI protocols that command per-graft price premiums over manual FUE. |
| Telemedicine Consultation Launch | Reduces geographic friction for European cross-border patients seeking English-speaking surgical environments. |
| Female Pattern Hair Loss Service Line | Addresses peri-menopausal demographic currently underserved relative to male-focused marketing investment. |
Research Methodology
A spread of perspectives from clinic directors, CQC compliance officers, biomedical equipment procurement managers, and trichology referral networks converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against Care Quality Commission inspection reports, MHRA device registration databases, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated against top-down market sizing derived from registered surgical premises capacity.
Segmentation dimensions modeled include procedure type, hair loss etiology, end-user facility category, and service model intensity across the projection horizon. CAGRs were derived from patient flow analysis, demographic penetration curves, and regulatory enforcement trajectory assumptions. Forecast inputs incorporated surgeon training pipeline capacity, robotic platform adoption rates, and cross-border patient mobility patterns.
Material uncertainties — CQC enforcement intensity escalations, MHRA device approval delays, and non-surgical substitution advances — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these structural triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Australia Laser Hair Removal Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Facial Bone Contouring Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market