
 Europe Non-Surgical Procedures Market | 2026-2036
Europe Non-Surgical Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Surgical Procedures Market Foresight
Subscription-based maintenance programs for laser and energy-based platforms is realigning capital deployment across European aesthetic practices. Lumenis leverages its installed base of multi-platform systems to secure recurring service revenue streams. Galderma anchors its position through vertical integration spanning toxin production to direct clinic partnerships. Alma Lasers competes on modular hardware architectures that reduce upgrade costs for mid-sized dermatology clinics.
Europe non-surgical procedures encompass minimally invasive aesthetic interventions delivered without incision, primarily utilizing injectable neuromodulators, dermal fillers, and energy-based devices operating at wavelengths between 532 nm and 10,600 nm depending on tissue target. These procedures serve commercial purposes of facial rejuvenation, body contouring, and skin quality improvement with minimal recovery intervals. Botulinum toxin and dermal fillers constitute the mature revenue core where pricing pressure intensifies from commoditization, while laser treatments capture expanding margin pools as fractional and picosecond technologies command premium positioning. Radiofrequency and ultrasound modalities represent the fastest-growing technology cluster as non-invasive tissue tightening protocols gain protocol adoption in cosmetic surgery centers.
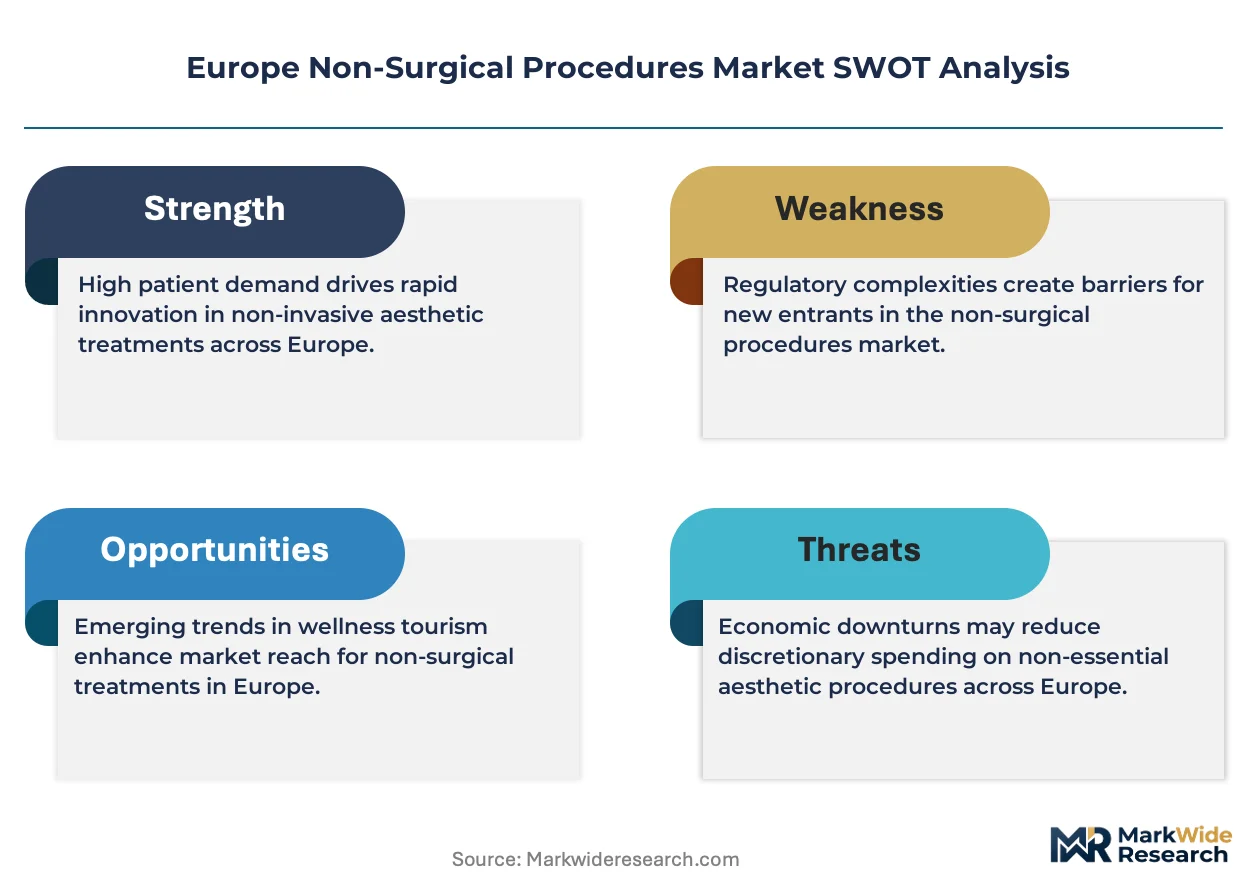
EMA oversight of botulinum toxin products and the EU MDR framework for energy-based devices establish dual compliance pathways that elevate barriers for new entrants. REACH chemical safety requirements and national advertising restrictions under GDPR-informed consumer protection rules further constrain promotional strategies. Stakeholders must monitor evolving notified body capacity constraints and anticipate how MDR transition deadlines reshape competitive dynamics across member states.
Market Dynamics
The EU Medical Device Regulation reclassification of energy-based devices is compressing product registration timelines and forcing manufacturers to accelerate clinical evidence generation for legacy platform recertification.
Growth Catalysts
- EU MDR transition deadlines:The phased implementation of stricter conformity assessment requirements is creating temporary demand surges as clinics accelerate capital equipment purchases ahead of certification expiration dates.
- Injectable neuromodulator protocol expansion:Dermatology practices across France and Italy are broadening toxin indications beyond glabellar lines to masseter reduction and hyperhidrosis, driving procedure volume multiplication per patient.
- Metropolitan disposable income concentration:Private aesthetic clinics in London, Munich, and Madrid are capturing premium pricing power from high-net-worth patient segments seeking concierge service models.
Market Restraints
- Notified body capacity constraints:The limited number of designated EU MDR assessment organizations is extending certification timelines for radiofrequency and ultrasound device manufacturers by 12-18 months.
- Botulinum toxin raw material concentration:Active pharmaceutical ingredient production clusters in a single non-European geography, exposing European formulators to supply interruption risks and import dependency.
- Energy-based device technical limitations:Current fractional laser systems cannot safely treat Fitzpatrick skin types V-VI without post-inflammatory hyperpigmentation risk, excluding significant patient demographics.
Strategic Opportunities
- Eastern European clinic network expansion:Poland and Czech Republic metropolitan markets show procedure penetration rates at 40% of Western European levels, presenting first-mover expansion potential for mid-tier device manufacturers.
- Combination protocol service bundling:Sequential toxin-filler-laser treatment packages are commanding 35% price premiums over standalone procedures in Swiss and Belgian cosmetic surgery centers.
- GDPR-informed teleconsultation frameworks:Digital patient intake and remote follow-up protocols compliant with EU data protection rules are reducing clinical overhead and expanding geographic catchment areas for established practices.
Industry Challenges
- Specialized injector talent scarcity:Advanced cannula technique certification programs face 6-12 month waitlists across German and UK training institutions, constraining clinic capacity expansion.
- Legacy laser platform integration complexity:Multi-wavelength treatment rooms require electrical infrastructure upgrades and spatial reconfiguration that disrupt cash-flow-positive operations during renovation periods.
- CE marking documentation burden:Technical file preparation for picosecond and Q-switched devices demands specialized regulatory affairs personnel that smaller manufacturers struggle to recruit and retain.
Report Scope
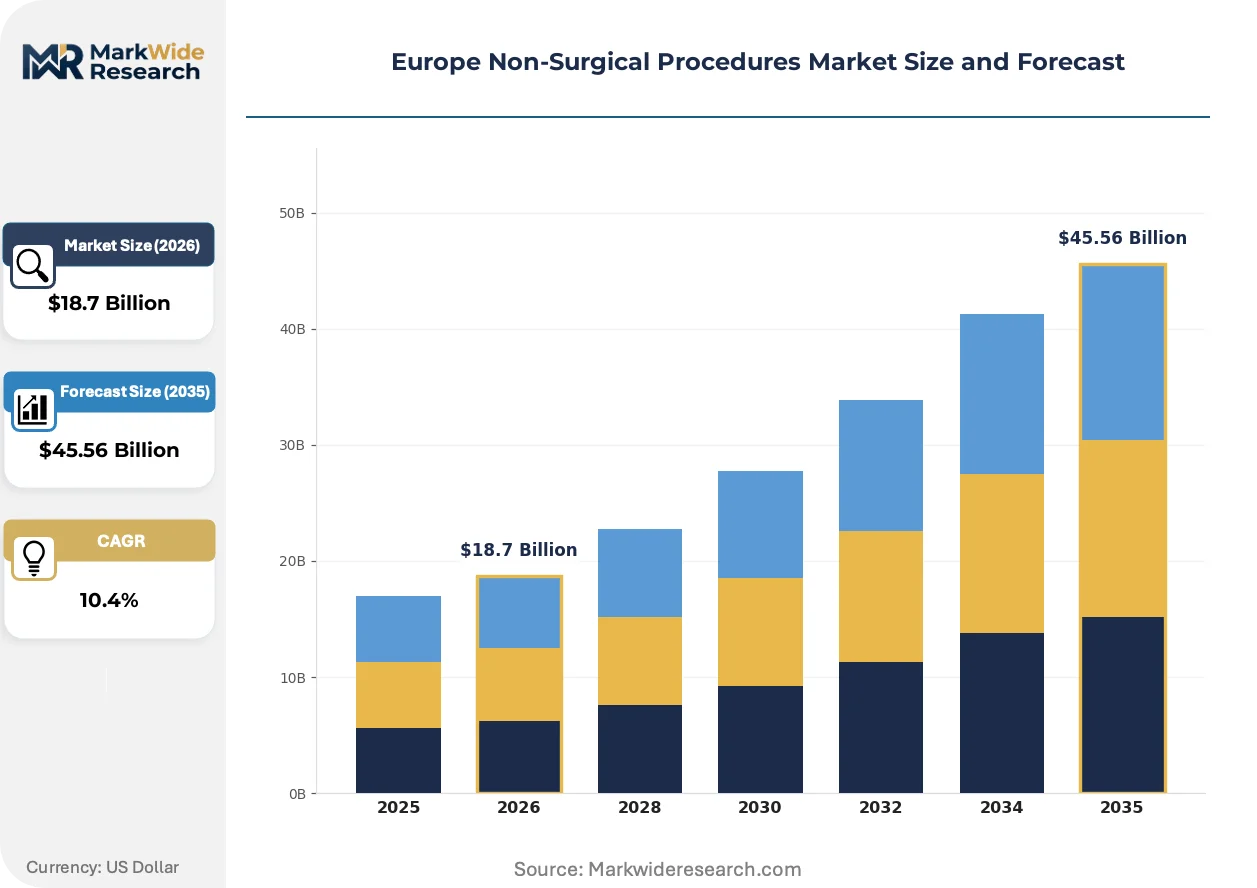
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Surgical Procedures Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $45.56 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Botulinum Toxin, Dermal Fillers, Chemical Peels, Laser Treatments Technology: Radiofrequency, Ultrasound, IPL, Cryotherapy End User: Dermatology Clinics, Cosmetic Surgery Centers, Spas, Home Care Application: Aesthetic Enhancement, Skin Rejuvenation, Hair Removal, Body Contouring |
| Companies Covered | Koninklijke Philips, Lumenis, AbbVie, Alma Lasers, Candela Medical, Galderma, Cynosure, Cutera, Merz Aesthetics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Surgical Procedures Market Shifts & Advancements
Technology convergence and regulatory compression are simultaneously expanding treatment possibilities while constraining how those capabilities reach European aesthetic practices.
Picosecond laser platforms with dual-wavelength 532 nm and 1064 nm outputs are unifying pigment and tattoo removal protocols into single-device footprints. Mid-sized dermatology clinics in the Netherlands and Belgium are prioritizing these systems to maximize room utilization rates. The technology is unifying previously separate capital equipment budgets into consolidated procurement decisions, pressuring standalone nanosecond laser manufacturers.
REACH chemical safety requirements for dermal filler cross-linking agents are mandating expanded toxicological dossiers for hyaluronic acid raw material suppliers. The regulation is extending new substance notification timelines and elevating compliance costs for novel filler formulations. Premium toxin and filler manufacturers with established European manufacturing footprints are capturing market position from import-dependent competitors facing documentation gaps.
Subscription-based maintenance programs for capital equipment are displacing traditional break-fix service arrangements across Spanish and Portuguese aesthetic clinic networks. Device manufacturers are unbundling hardware warranties from software update entitlements, creating recurring revenue streams that alter total cost of ownership calculations. This model is most visible in German-speaking markets where precision-engineering expectations sustain premium service pricing.
Europe Non-Surgical Procedures Market Segmentation
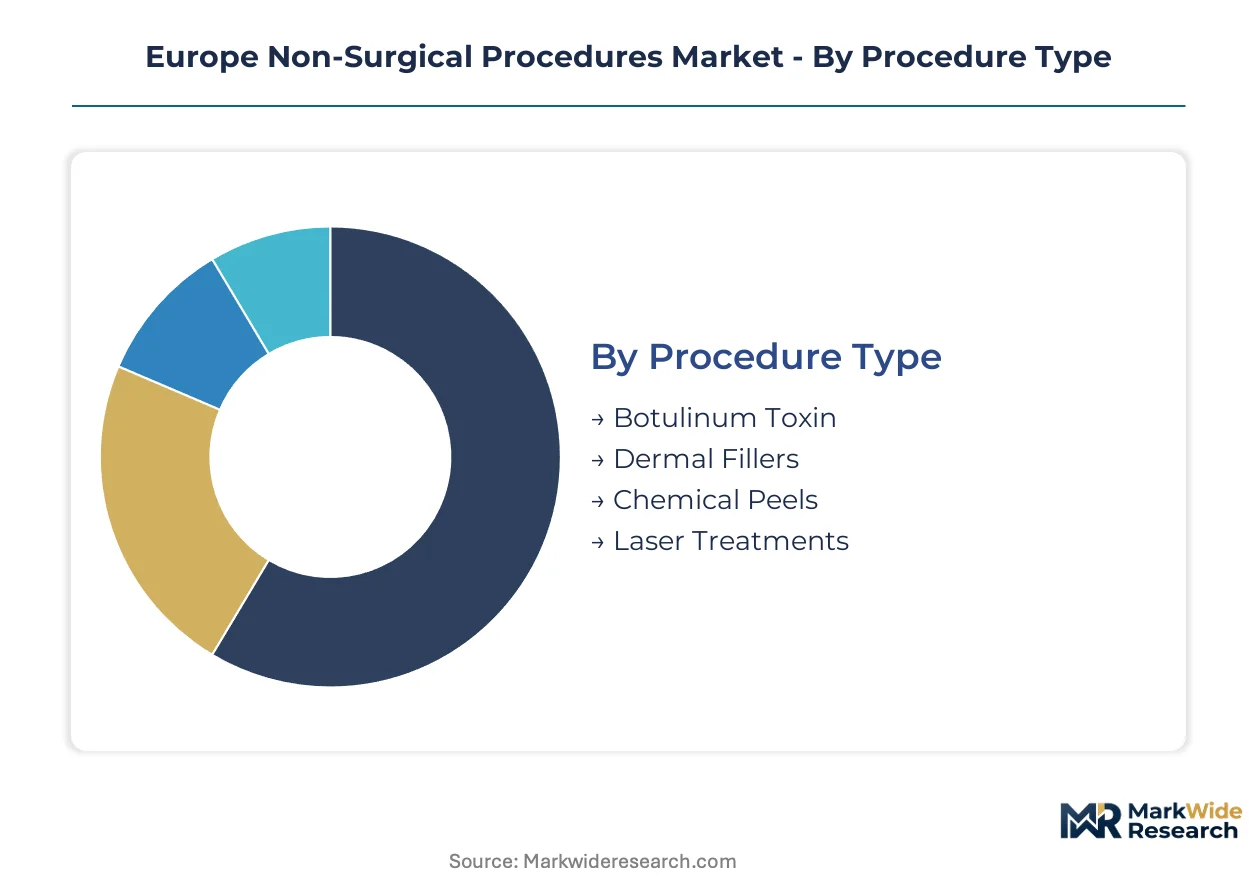
Europe's non-surgical procedures market fragments across regulatory boundaries that dictate reimbursement pathways and clinic investment priorities. EMA oversight of injectable biologics and EU MDR classification of energy-based devices create divergent compliance burdens across segment categories.
Procedure Type:
EMA centralized marketing authorization applies to botulinum toxin products, while dermal fillers and chemical peels navigate national competent authority routes; laser treatments face the steepest MDR conformity assessment requirements.
- Botulinum Toxin:Purified neurotoxin formulations require cold-chain distribution and specialized injector certification under national medical board protocols. Demand concentrates in German and French metropolitan clinics where masseter reduction and hyperhidrosis protocols multiply revenue per patient visit.
- Dermal Fillers:Cross-linked hyaluronic acid and calcium hydroxylapatite formulations dominate volume. REACH documentation burdens for novel cross-linking agents favor established European manufacturers with toxicological dossiers already on file with ECHA.
- Chemical Peels:Acid-based exfoliation solutions ranging from superficial glycolic to deep phenol formulations. Spanish and Italian clinics favor medium-depth trichloroacetic acid protocols for photodamage correction.
- Laser Treatments:Fractional ablative and non-ablative platforms operating across 532 nm to 10,600 nm wavelengths. MDR recertification deadlines are compressing procurement timelines for legacy CO2 and erbium systems.
Leading the category by volume: Botulinum Toxin. Expanding most quickly: Laser Treatments.
Technology:
Capital equipment procurement decisions weigh total cost of ownership against treatment versatility, with subscription maintenance models altering lifecycle economics for mid-sized clinic operators.
- Radiofrequency:Monopolar and bipolar energy delivery systems for dermal heating and collagen remodeling. Netherlands and Belgian cosmetic surgery centers prioritize multi-depth platforms that combine microneedling with thermal energy delivery.
- Ultrasound:Microfocused and high-intensity focused modalities for non-invasive tissue lifting. Swiss clinics command premium pricing for combination ultrasound-rf protocols targeting submental contouring.
- IPL:Broad-spectrum intense pulsed light systems for pigment and vascular indications. Polish aesthetic clinics favor IPL for entry-level hair removal service expansion.
- Cryotherapy:Controlled cooling applications for fat reduction and skin lesion treatment. Portuguese spa networks adopt cryolipolysis as a non-technical staff deliverable.
Radiofrequency captures the largest installed base. Ultrasound gains share fastest among premium-positioned devices.
End User:
Facility type determines staffing requirements, insurance liability profiles, and permissible procedure scope under national healthcare regulations.
- Dermatology Clinics:Physician-led practices with diagnostic capabilities and medical-grade device procurement authority. UK and German dermatology chains are consolidating through acquisition of independent practices.
- Cosmetic Surgery Centers:Hospital-affiliated or standalone surgical facilities expanding into minimally invasive service lines. French centers bundle toxin-filler-laser sequences at 35% price premiums.
- Spas:Non-medical aesthetic venues limited to superficial peels and IPL hair removal in most jurisdictions. Czech Republic regulatory ambiguity permits broader service menus than Western European counterparts.
- Home Care:Consumer-grade devices for LED therapy and microcurrent applications. GDPR-informed teleconsultation frameworks enable remote supervision by licensed practitioners.
Dermatology Clinics lead procedure volume concentration. Cosmetic Surgery Centers show the steepest service expansion trajectory.
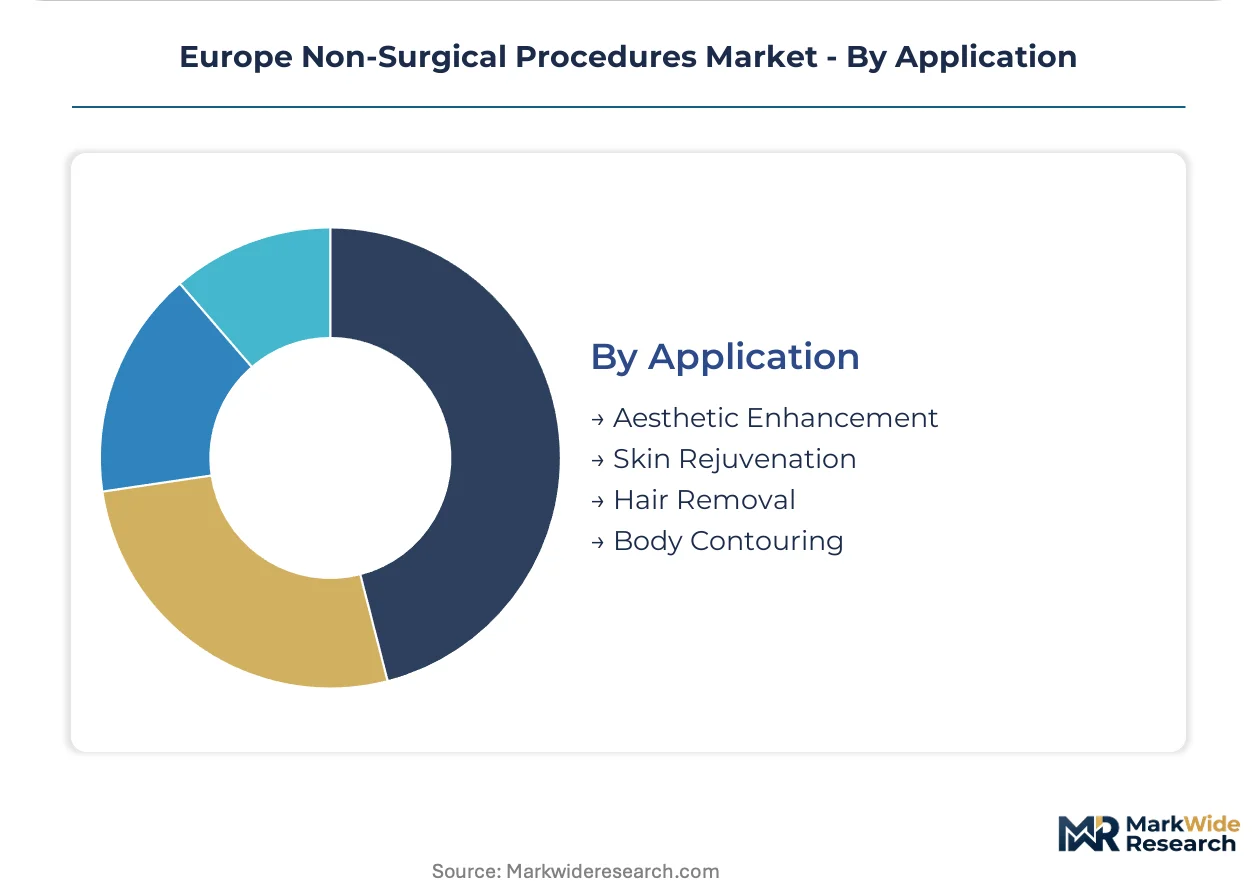
Application:
Clinical indication drives device wavelength selection, injector technique requirements, and treatment protocol standardization across European training institutions.
- Aesthetic Enhancement:Facial volumization and wrinkle modification using injectable products. London and Munich concierge clinics target high-net-worth segments with personalized treatment planning.
- Skin Rejuvenation:Texture improvement and photodamage correction through fractional laser and chemical resurfacing. Italian practices emphasize sequential peel-laser protocols for Mediterranean skin phototypes.
- Hair Removal:Permanent reduction using alexandrite, diode, and Nd:YAG laser platforms. Madrid aesthetic networks compete on package pricing for full-body treatment courses.
- Body Contouring:Non-invasive fat reduction and skin tightening across abdomen, flank, and thigh indications. Belgian centers combine cryotherapy with radiofrequency for comprehensive treatment outcomes.
Aesthetic Enhancement generates the highest revenue per procedure. Body Contouring climbs fastest as device manufacturers expand treatable anatomical zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European consumption of non-surgical aesthetic procedures outpaces indigenous device manufacturing capacity, creating import dependency for energy-based platforms and concentrated API sourcing for injectable products. Germany and the United Kingdom absorb disproportionate procedure volumes while production clusters concentrate in Switzerland and select Israeli manufacturing sites.
Germany
Metropolitan dermatology chains in Munich and Hamburg drive demand for multi-wavelength laser platforms and advanced toxin protocols including masseter reduction. BfArM oversight of medical device advertising enforces strict efficacy claims substantiation. The North Rhine-Westphalia corridor hosts concentrated procurement authority for hospital-affiliated cosmetic surgery centers upgrading to EU MDR-compliant equipment.
United Kingdom
London's concierge aesthetic clinics command premium pricing for combination toxin-filler-laser sequences targeting high-net-worth patient segments. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR timelines while preserving separate conformity assessment pathways. The Harley Street medical district concentrates specialized injector talent with advanced cannula technique certification.
France
Parisian cosmetic surgery centers bundle sequential rejuvenation protocols at price premiums exceeding standalone procedures. ANSM pharmacovigilance requirements for botulinum toxin products mandate enhanced adverse event reporting infrastructure. The Île-de-France region anchors national training institution capacity for next-generation injector certification programs.
Italy
Milan and Rome aesthetic practices emphasize sequential peel-laser protocols calibrated for Mediterranean skin phototypes. Ministry of Health notification requirements for Class IIb energy-based devices compress product registration timelines for fractional platform manufacturers. Northern Italian dermatology networks consolidate through acquisition of independent practices in Veneto and Lombardy.
Switzerland
Swiss cosmetic surgery centers pioneer combination ultrasound-radiofrequency protocols for submental contouring at premium positioning. Swissmedic medical device surveillance maintains stringent post-market clinical follow-up requirements for novel energy delivery systems. The Lake Geneva corridor concentrates manufacturing operations for hyaluronic acid raw materials serving European formulators.
Europe Non-Surgical Procedures Market Competitive Landscape
Capital-heavy device manufacturers compete with asset-light formulation specialists across divergent investment intensity models. The vendor base stratifies between integrated platform developers bearing full EU MDR certification burdens and injectable product marketers leveraging contract manufacturing relationships. Three archetypes dominate: precision-engineering conglomerates with multi-modality portfolios, specialized energy-device pure-plays, and vertically integrated toxin-filler houses controlling captive supply chains. Competitive positioning hardens around MDR transition readiness and installed base service contract penetration.
Among diversified health technology conglomerates, Koninklijke Philips occupies a position exemplifying capital-intensive platform development with cross-clinical application reach. Lumenis and Alma Lasers represent the specialized device manufacturer archetype, anchoring competitive dynamics through modular hardware architectures and subscription-based maintenance program penetration. Galderma exemplifies the integrated formulation house model with backward integration into active pharmaceutical ingredient sourcing.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Lumenis |
| AbbVie |
| Alma Lasers |
| Candela Medical |
| Galderma |
| Cynosure |
| Cutera |
| Merz Aesthetics |
| Others |
Supply & Pricing Matrix
Mid-sized dermatology clinic procurement clusters in the Netherlands and Belgium anchor European pricing power through consolidated multi-device purchasing agreements. Their buying concentration forces manufacturers to unbundle hardware from software entitlements, shifting revenue toward recurring maintenance streams under EU MDR compliance pressure.
Pricing Analysis
Margin tightening in premium laser platforms reflects REACH documentation burdens and notified body recertification costs passed through to buyers. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified multi-wavelength systems from legacy single-modality devices and entry-level IPL units. Pricing pressure stems from commoditization in botulinum toxin and hyaluronic acid formulations where European manufacturing footprints command premiums over import-dependent competitors. Cosmetic surgery centers show least price sensitivity for combination protocol bundles, while Polish and Czech spa networks drive hardest bargain on standalone hair removal systems.
Supply Chain Analysis
Dual-sourcing mandates from German hospital-affiliated cosmetic surgery centers compel device manufacturers to qualify backup component suppliers across Switzerland and Israel. Active pharmaceutical ingredient production for botulinum toxin concentrates in single non-European geography, exposing European formulators to import dependency and cold-chain interruption risks. Hyaluronic acid raw materials feed from Lake Geneva corridor manufacturing clusters serving cross-linked filler formulators. Single-source vulnerability in picosecond laser crystal supply creates bottleneck exposure for fractional platform builders. Distribution runs through authorized dealer networks with direct clinic relationships in German-speaking markets and distributor-led models in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification deadlines construct a cost-of-compliance moat that rewards prepared incumbents while filtering undercapitalized entrants from energy-based device competition.
For Market Incumbents: Cement installed base loyalty through subscription maintenance program penetration ahead of legacy platform certification expirations. Accelerate clinical evidence generation for picosecond and radiofrequency modalities to secure notified body queue priority. Defend against modular hardware competitors by bundling software update entitlements with hardware warranties in German-speaking markets. For New Entrants and Emerging Players: Capture Eastern European white space in Poland and Czech Republic metropolitan markets where procedure penetration trails Western European levels by significant margin. Target mid-tier device positioning for dermatology clinics seeking MDR-compliant upgrade paths without full platform replacement costs. Pursue partnership-based entry with established service networks rather than direct sales buildout. For Investors and Strategic Acquirers: The window for entry favors vertically integrated toxin-filler houses with backward integration into API sourcing and European manufacturing footprints. Long-term viability hinges on MDR transition readiness and recurring revenue attachment rates rather than hardware shipment volumes. Watch notified body capacity expansion announcements as signal for certification timeline normalization and competitive re-entry opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Acceleration | Notified body queue priority secures market access continuity for legacy laser platforms ahead of deadline compression. |
| Subscription Maintenance Program Expansion | Recurring revenue streams from German clinic networks alter total cost of ownership calculations and customer lock-in. |
| Eastern European Clinic Network Buildout | First-mover positioning in Polish metropolitan markets captures procedure penetration gap versus Western European benchmarks. |
| Combination Protocol Service Bundling | Swiss and Belgian cosmetic surgery centers command price premiums for sequential toxin-filler-laser treatment sequences. |
| GDPR-Compliant Teleconsultation Framework Deployment | Remote patient intake protocols reduce clinical overhead and expand geographic catchment for established practices. |
Research Methodology
Independent corroboration across aesthetic device procurement managers, dermatology clinic operators, and regulatory affairs specialists at notified bodies underwrites the qualitative findings. Primary interviews with biomedical engineers, GPO contracts managers, and hospital purchasing committee members combined with secondary validation from EMA centralized marketing authorization records, EU MDR technical file databases, and national competent authority submission logs. Bottom-up procedure volume estimates triangulate against top-down manufacturer shipment data across the analysis window.
Comparable-period anchoring to historical certification timelines and procedure penetration benchmarks structures the forecast framework across the modeling period. Segmentation dimensions include procedure type, technology modality, end-user facility category, and application indication with regional regulatory cluster overlays. CAGRs derive from installed base growth rates, replacement cycle compression under MDR deadlines, and per-procedure revenue trajectories. Forecast inputs incorporate notified body capacity constraints and REACH documentation timeline extensions for novel filler formulations.
The model holds under stable MDR transition timelines and notified body designation continuity; deviation in regulatory deadline extensions or geopolitical API supply interruptions would shift the outlook materially. Forecasts reflect documented assumptions regarding procedure adoption curves and capital equipment procurement patterns. Deviation in Eastern European market liberalization pace or reimbursement pathway changes would revise volume projections significantly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Germany Hair Transplant Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
Non-Surgical Rhinoplasty Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
India Hair Transplant Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Lip Augmentation Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Tattoo Removal Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Australia Laser Hair Removal Market