
 Facial Bone Contouring Market | 2026-2036
Facial Bone Contouring Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Bone Contouring Market Foresight
Cosmetic tourism is decoupling from traditional hospital channels as independent aesthetic centers capture preference share. Lumenis Ltd. leverages its laser-integrated surgical platforms to anchor premium positioning in Asian markets. Cynosure LLC competes through energy-based device portfolios that complement osteotomy workflows. AbbVie Inc. sustains R&D intensity across facial implant biomaterials, extending its therapeutic aesthetics footprint without direct device manufacturing.
Facial bone contouring encompasses surgical and non-surgical modification of the mandible, zygoma, maxilla, and frontal bone to alter facial skeletal architecture, typically employing titanium plates, porous polyethylene, or resorbable fixation systems with sub-millimeter precision requirements. The primary purpose centers on aesthetic proportion correction, congenital deformity repair, and post-traumatic reconstruction across craniofacial practice. Osteotomy procedures command the deepest margin pools due to OR time and implant bundling, while augmentation with hydroxyapatite represents the fastest-growing material trajectory as biocompatibility standards intensify. Revision procedures concentrate demand among middle-aged adults seeking correction of prior surgical outcomes, creating a distinct secondary market dynamic.
FDA 510(k) pathways and the EU Medical Device Regulation shape implant material approval timelines and post-market surveillance obligations for manufacturers seeking multi-territory distribution. South Korea's Ministry of Food and Drug Safety imposes stricter advertising controls on before-and-after imagery, directly constraining clinic marketing spend and patient acquisition economics. Stakeholders must monitor evolving biocompatibility testing protocols and reimbursement classification shifts for craniofacial procedures across their priority markets.
Market Dynamics
Biocompatibility testing protocols for craniofacial implants are tightening material compliance requirements faster than manufacturers can reformulate, compressing product development cycles and raising R&D intensity across the supply base.
Growth Catalysts
- MFDS advertising controls:South Korea's Ministry of Food and Drug Safety restrictions on before-and-after imagery are forcing clinics toward outcome-verification systems, indirectly driving demand for precision surgical planning technologies.
- Hydroxyapatite resorption profiles:Next-generation synthetic bone substitutes with tunable degradation rates are expanding revision procedure candidacy among middle-aged patient cohorts.
- Seoul-Los Angeles corridor demand:Zygoma reduction volumes among young professionals in these metropolitan clusters are normalizing facial bone contouring as career-adjacent aesthetic investment.
Market Restraints
- Titanium plate cost volatility:Aerospace and medical-grade titanium supply competition concentrates pricing power with a handful of Japanese and Chinese smelters, compressing implant margins.
- EU MDR post-market surveillance:Extended clinical follow-up obligations for porous polyethylene implants are lengthening approval timelines and freezing smaller manufacturers out of European distribution.
- Non-surgical filler substitution:Hyaluronic acid and calcium hydroxylapatite injectables are capturing mild-to-moderate contouring cases that previously flowed to osteotomy procedures.
Strategic Opportunities
- Secondary revision market:Correction demand from aging prior surgical recipients represents an underpenetrated patient pool with distinct biomaterial and fixation requirements.
- Laser-osteotomy convergence:Integration of erbium-doped fiber lasers with navigated cutting guides is enabling sub-millimeter precision in mandible reshaping workflows.
- Independent aesthetic center channel:Cosmetic tourism is decoupling from hospital systems, creating direct procurement relationships with device and implant suppliers.
Industry Challenges
- Craniomaxillofacial surgical fellowship scarcity:The specialized training pipeline produces fewer qualified osteotomy surgeons annually than procedure volume growth requires, creating regional access bottlenecks.
- FDA 510(k) biomaterial equivalence:Demonstrating substantial equivalence for novel resorbable fixation systems against legacy titanium predicates demands extensive mechanical testing protocols that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Bone Contouring Market |
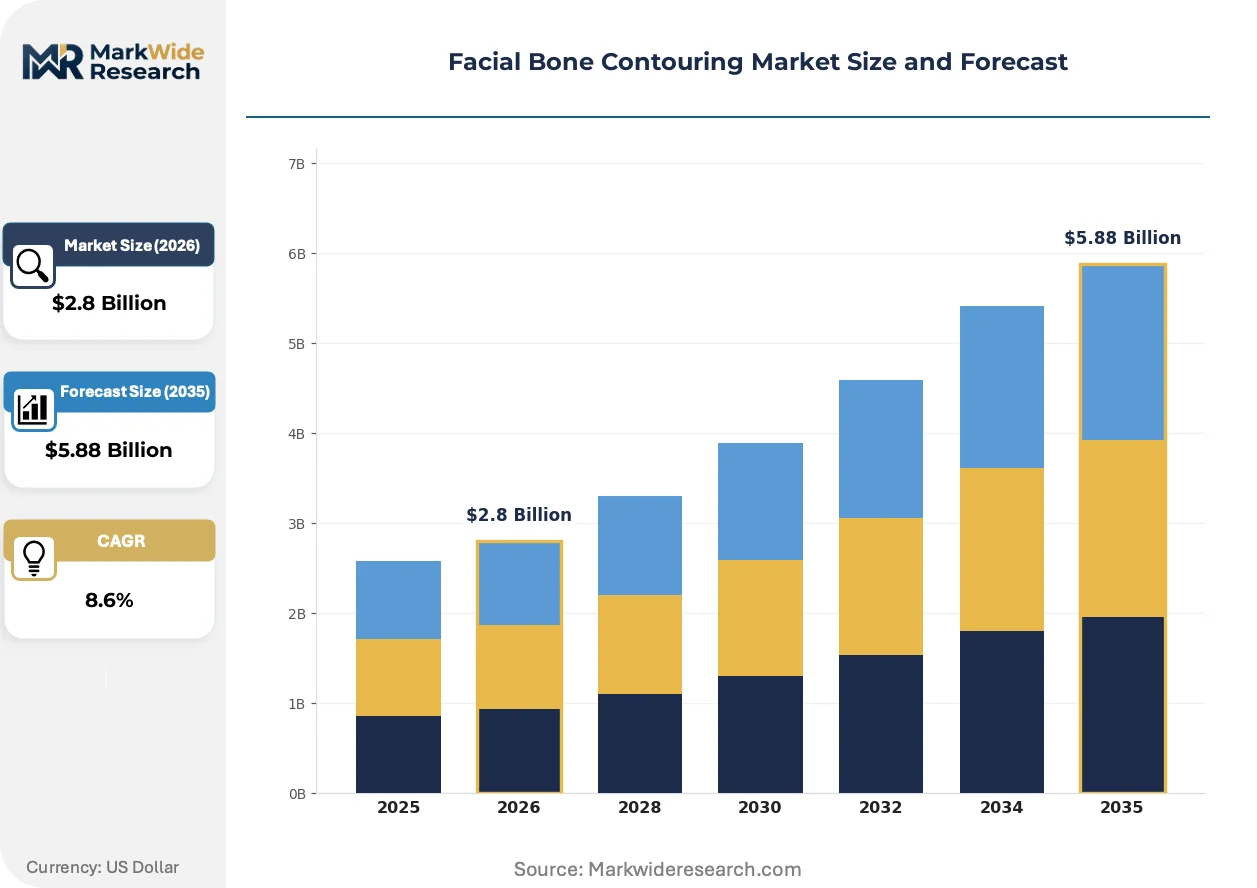
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Osteotomy, Reduction, Augmentation, Revision Material Type: Silicone, Hydroxyapatite, Mesh, Polymers End User: Plastic Surgeons, Hospitals, Clinics, Dermatologists Age Group: Adults, Teenagers, Seniors, Middle-Aged |
| Companies Covered | Lumenis Ltd., Cynosure LLC, AbbVie Inc., Asclepion Laser Technologies GmbH, Candela Corporation, Merz Pharma GmbH & Co. KGaA, Alma Lasers Ltd., Cutera Inc., Galderma S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Bone Contouring Market Shifts & Advancements
Digital surgical planning ecosystems are compressing the gap between preoperative simulation and intraoperative execution, reshaping how craniofacial specialists approach complex osteotomies and implant positioning.
Patient-specific titanium implants fabricated through electron beam melting are unifying anatomical reconstruction with aesthetic contouring in single-procedure workflows. Academic medical centers in South Korea and Germany are adopting these platforms at accelerating cadence. The technology is unifying what were historically separate reconstructive and cosmetic practice lines into integrated craniofacial service offerings.
REACH substance restrictions on certain polymer additives are forcing reformulation of porous polyethylene implant substrates used in malar and chin augmentation. European manufacturers face supply chain requalification costs that favor larger device portfolios with dedicated regulatory affairs infrastructure. Mid-sized suppliers are responding by concentrating European distribution through established partners rather than direct market presence.
Young professionals are compressing decision cycles for facial bone contouring, treating these procedures as discrete project investments with defined recovery windows rather than open-ended lifestyle commitments. Independent aesthetic centers in Seoul and Los Angeles are capturing this demand through bundled pricing and accelerated scheduling. The pattern is most visible among technology and entertainment industry workers seeking proportion adjustments ahead of career inflection points.
Facial Bone Contouring Market Segmentation
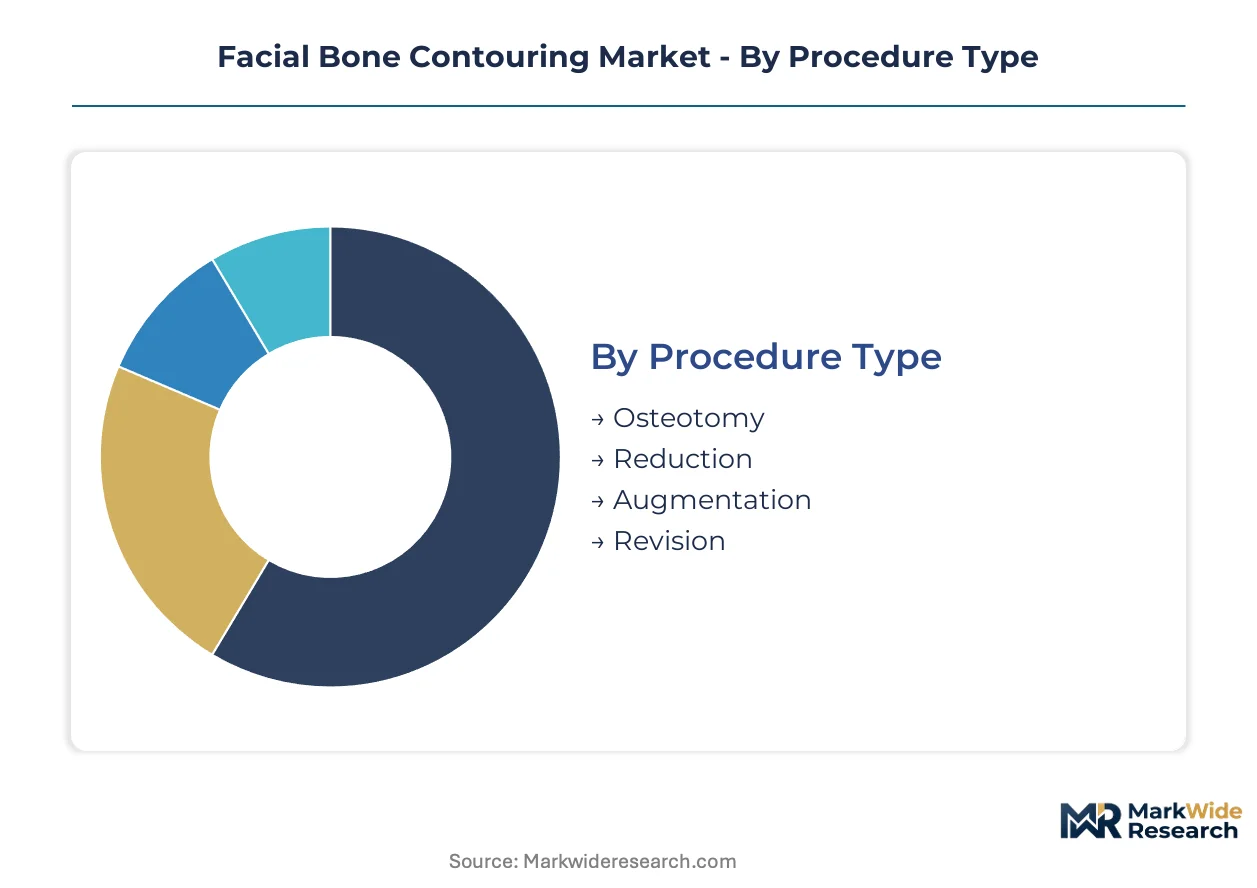
Facial bone contouring demand fragments across surgical intensity, biomaterial preference, and provider channel, with each axis carrying distinct margin profiles and regulatory exposure. Understanding these divisions reveals where procurement power concentrates and which patient cohorts drive technology substitution.
Procedure Type:
Cost tier separates patients seeking one-time structural correction from those managing prior surgical outcomes or incremental refinements.
- Osteotomy:Surgical cutting and repositioning of mandible, zygoma, or maxilla using oscillating saws and rigid fixation. Seoul and Los Angeles aesthetic clusters absorb the deepest volume pools as young professionals treat facial proportion as career capital.
- Revision:Secondary correction of prior contouring outcomes, often requiring custom implant fabrication and scar tissue management. Middle-aged adults with aging initial procedures are expanding this segment fastest as biocompatibility standards disqualify earlier materials.
- Reduction:Selective bone removal to narrow facial width, particularly malar and mandibular angles.
- Augmentation:Implant or graft placement to enhance projection in chin, cheek, or forehead regions.
Osteotomy leads volumes today; Revision is gaining share fastest.
Material Type:
Application context dictates material selection, with resorbable synthetics displacing permanent implants in specific anatomical zones.
- Hydroxyapatite:Synthetic calcium phosphate ceramic with tunable resorption profiles that integrate with native bone. Revision procedures among aging prior recipients favor this material as permanent implant complications accumulate.
- Silicone:Elastomer implants for chin and malar augmentation offering reversible placement. South Korean clinics prefer silicone for predictable explantability under MFDS advertising scrutiny.
- Mesh:Titanium or resorbable polymer screens for structural support in complex reconstructions.
- Polymers:Porous polyethylene and PMMA substrates shaped for patient-specific anatomical matching.
Silicone leads volumes today; Hydroxyapatite is expanding most quickly.
End User:
Volume concentration varies sharply between institutional procurement and independent aesthetic center purchasing.
- Clinics:Independent aesthetic centers in cosmetic tourism corridors that bundle imaging, planning, and procedure in accelerated workflows. Seoul and Los Angeles independents are decoupling from hospital systems and negotiating direct implant supply contracts.
- Plastic Surgeons:Board-certified specialists performing osteotomy and revision procedures in academic or private settings. Fellowship-trained craniomaxillofacial surgeons command premium positioning for complex mandible reshaping.
- Hospitals:Institutional settings handling trauma reconstruction and congenital deformity cases.
- Dermatologists:Non-surgical contouring using injectables that capture mild cases outside surgical channels.
Plastic Surgeons lead volumes today; Clinics are climbing the fastest.
Age Group:
Customer type determines decision velocity, recovery tolerance, and whether motivation is primary aesthetic investment or secondary correction.
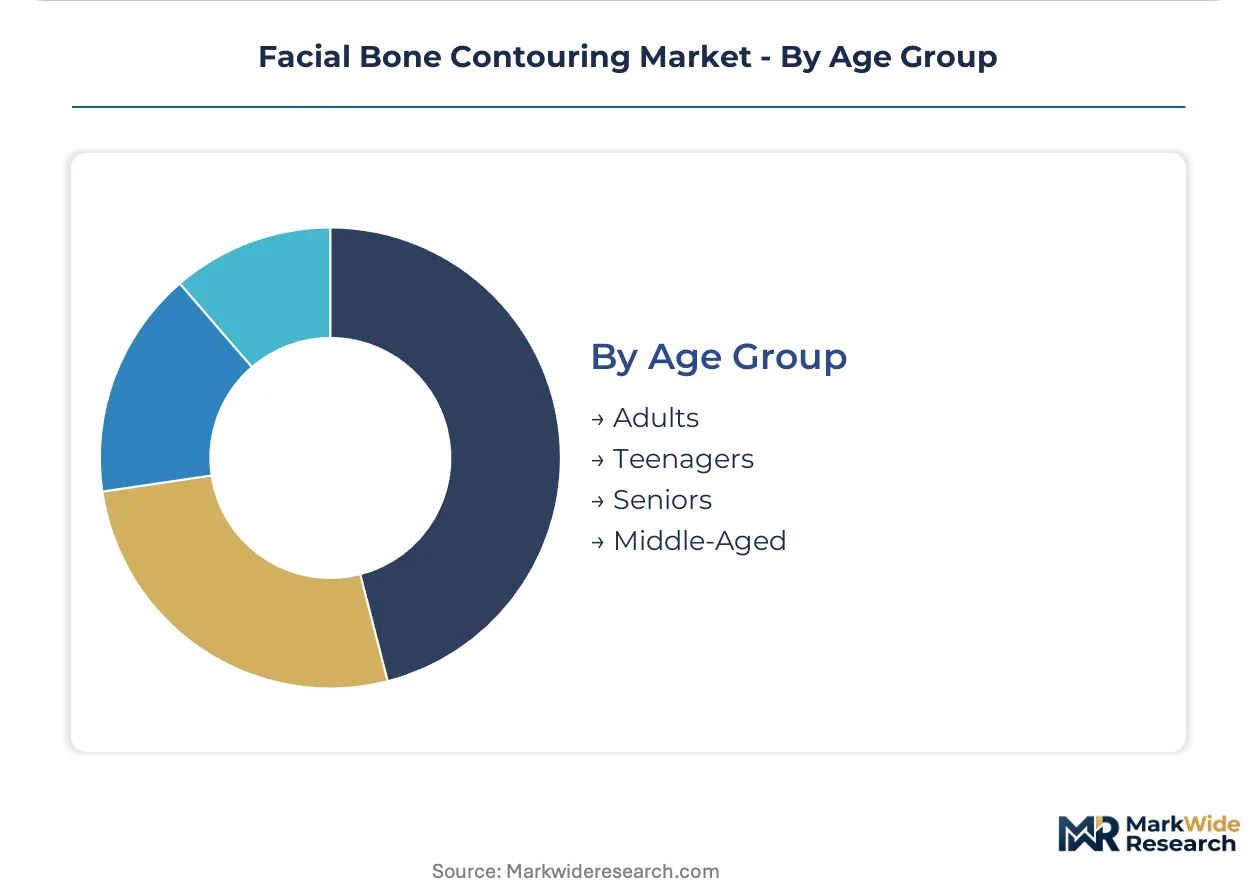
- Young Professionals:Adults aged 25-35 treating zygoma reduction and mandible contouring as discrete career-phase investments with defined recovery windows. Technology and entertainment industry workers in Seoul and Los Angeles compress scheduling and payment cycles.
- Middle-Aged:Patients aged 45-60 seeking revision of prior procedures or addressing age-related skeletal changes. This cohort expands implant demand as earlier materials reach end-of-life.
- Teenagers:Congenital deformity correction and post-traumatic reconstruction under parental consent frameworks.
- Seniors:Functional restoration and post-oncologic reconstruction with lower aesthetic priority.
Young Professionals lead volumes today; Middle-Aged is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing device manufacturing capacity toward jurisdictions with streamlined biomaterial approval pathways, while demand concentration remains anchored in metropolitan aesthetic clusters with established surgeon training pipelines.
South Korea
Seoul's Gangnam district absorbs the deepest zygoma reduction volumes globally as young technology workers treat facial proportion as career-phase investment. MFDS advertising restrictions on before-and-after imagery are forcing clinics toward outcome-verification systems and precision surgical planning technologies. The Seoul Capital Area concentrates over half of national procedure volume within a 30-kilometer radius.
United States
FDA 510(k) pathway tightening for polymethylmethacrylate implants is extending time-to-market for novel resorbable fixation systems against titanium predicates. Los Angeles aesthetic clusters mirror Seoul's professional-cohort demand patterns, with entertainment industry workers driving mandible contouring volumes. The Beverly Hills and West Hollywood sub-markets command premium pricing tiers.
Germany
EU MDR post-market surveillance obligations for porous polyethylene implants are lengthening approval timelines and freezing smaller manufacturers out of European distribution. Academic medical centers in Munich and Hamburg are adopting patient-specific titanium implants fabricated through electron beam melting at accelerating cadence. Bavaria anchors reconstructive-cosmetic integration workflows.
Japan
PMDA biocompatibility testing protocols for craniofacial implants are compressing product development cycles faster than manufacturers can reformulate. Tokyo and Osaka metropolitan clusters concentrate demand for revision procedures among middle-aged adults seeking correction of prior surgical outcomes. METI industrial policy supports domestic precision manufacturing for surgical device components.
Brazil
ANVISA regulatory harmonization with FDA pathways is attracting multinational device manufacturers seeking Latin American market entry through São Paulo distribution hubs. Rio de Janeiro aesthetic centers are capturing regional cosmetic tourism flows previously directed toward Miami. The Southeast region concentrates both surgical training capacity and private clinic infrastructure.
Facial Bone Contouring Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier device suppliers commanding margin pools through laser-osteotomy convergence while mid-tier implant fabricators compete on material compliance velocity. The vendor base organizes around three strategic archetypes: energy-based surgical platform developers, biomaterial specialists navigating regulatory reformulation cycles, and diversified aesthetics portfolios extending therapeutic footprints without direct device manufacturing. Consolidation pressure concentrates among mid-sized porous polyethylene suppliers facing EU MDR requalification costs. Dominant competitive moves include strategic partnerships with independent aesthetic center channels and technology licensing for navigated cutting guide integration.
Within the energy-based platform tier, Lumenis Ltd. and Cynosure LLC exemplify premium positioning through laser-integrated surgical systems, while AbbVie Inc. occupies a distinct position extending therapeutic aesthetics R&D intensity across facial implant biomaterials without captive device manufacturing. These three companies represent divergent strategic paths: hardware-centric platform development, energy-based device portfolio breadth, and pharmaceutical-aesthetics convergence through biomaterial innovation rather than direct surgical tool production.
| Leading Market Players |
|---|
| Lumenis Ltd. |
| Cynosure LLC |
| AbbVie Inc. |
| Asclepion Laser Technologies GmbH |
| Candela Corporation |
| Merz Pharma GmbH & Co. KGaA |
| Alma Lasers Ltd. |
| Cutera Inc. |
| Galderma S.A. |
| Others |
Supply & Pricing Matrix
REACH substance restrictions on polymer additives in porous polyethylene implants gate qualified European supply and premium-tier pricing access, compressing margins for mid-sized manufacturers while concentrating procurement power with larger portfolios bearing dedicated regulatory infrastructure.
Pricing Analysis
Distributor margin layers in South Korea and Los Angeles aesthetic corridors absorb 15-25% of implant landed costs, with direct-to-clinic contracts commanding steeper discounts for volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates patient-specific titanium implants from stock silicone geometries and resorbable fixation systems. Cost compression in titanium plate supply intensifies because aerospace-grade material competition concentrates smelter pricing power with Japanese and Chinese suppliers. Young professionals in Seoul's Gangnam district show lowest price sensitivity, treating procedures as career capital investments, while middle-aged revision patients in secondary markets exhibit highest elasticity.
Supply Chain Analysis
Explant and implant return flows from revision procedures in Tokyo and Seoul feed refurbishment channels for titanium components, though porous polyethylene substrates face single-use constraints under biocompatibility protocols. Manufacturing concentration centers on South Korea, Germany, and Japan for electron beam melting fabrication, precision osteotomy devices, and bioresorbable polymer synthesis. Raw material dependencies rest on medical-grade titanium sponge from Japanese smelters, synthetic hydroxyapatite from German chemical processors, and high-purity PMMA resin from specialized European polymer suppliers. Single-source vulnerability in titanium supply creates procurement risk for implant fabricators lacking long-term offtake agreements. Distribution runs through independent aesthetic center channels decoupling from hospital procurement systems in Seoul and Los Angeles corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA 510(k) pathway tightening in the United States extends approval timelines against South Korea's MFDS framework, creating cost and speed differentials for manufacturers selecting initial market entry.
For Market Incumbents: Deepen laser-osteotomy platform integration with navigated cutting guides to defend premium positioning against energy-based device competitors. Anchor capacity expansion in South Korea's Seoul Capital Area to capture Gangnam district volume concentration and direct clinic procurement relationships. Fortify regulatory affairs infrastructure to navigate EU MDR post-market surveillance obligations that freeze smaller porous polyethylene suppliers from European distribution.
For New Entrants and Emerging Players: Digital surgical planning ecosystems with AI-assisted osteotomy simulation offer the most penetrable technology-first wedge into independent aesthetic center procurement channels. Target the secondary revision market among middle-aged adults in Japan and Germany where aging prior procedures create biomaterial replacement demand. Pursue white-label manufacturing partnerships with established implant fabricators to bypass titanium supply bottlenecks and accelerate MFDS registration timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized porous polyethylene suppliers facing REACH reformulation costs and EU MDR requalification burdens that favor acquisition by larger device portfolios. Long-term viability over the projection horizon hinges on biomaterial innovation velocity and regulatory compliance infrastructure scale. Monitor FDA biomaterial equivalence determinations for novel resorbable fixation systems as the inflection signal indicating which platform technologies will capture revision procedure share.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Osteotomy Platform Integration | Erbium-doped fiber laser convergence with navigated guides enables sub-millimeter mandible reshaping precision in Seoul academic centers. |
| Patient-Specific Implant Fabrication | Electron beam melting unifies reconstructive and cosmetic workflows in Munich and Hamburg craniofacial service lines. |
| Independent Aesthetic Center Partnership | Direct procurement relationships with Seoul and Los Angeles clinics bypass hospital system margin layers and accelerate scheduling. |
| Biomaterial Compliance Investment | REACH reformulation and EU MDR surveillance infrastructure separates viable European suppliers from frozen market participants. |
| Revision Market Service Development | Secondary correction workflows for aging prior recipients expand addressable patient pools with distinct fixation and explant requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with craniofacial surgeons, biomedical engineers at implant manufacturers, GPO contracts managers, and clinic procurement officers in Seoul and Los Angeles with secondary validation against FDA 510(k) filings, MFDS registration databases, EU MDR technical documentation, hospital procurement records, and trade data for medical-grade titanium and synthetic hydroxyapatite. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions.
Segment-weighting approaches distributed value across procedure type, material category, end-user channel, and age cohort dimensions, with osteotomy-revision splits and hydroxyapatite-silicone trajectories modeled separately across the analysis window. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and surgeon training pipeline constraints. Forecast inputs incorporated MFDS advertising control enforcement intensity, titanium spot price volatility indices, and EU MDR approval timeline distributions for porous polyethylene predicates.
The model holds under stable regulatory enforcement and titanium supply continuity; deviation in FDA biomaterial equivalence determinations or Japanese smelter export restrictions would shift volume and value trajectories. Practitioners should monitor PMDA biocompatibility testing protocol updates and REACH substance restriction expansion schedules for early signals of supply chain compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Germany Facial Aesthetics Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market
Medical Aesthetics
Laser Scar Removal Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Tattoo Removal Market