
 North America Public Infrastructure Safety Market | 2026-2036
North America Public Infrastructure Safety Market Size, Share, and Industry Trends Forecast 2026-2036
North America Public Infrastructure Safety Market Insights
Public-private partnership financing and availability-based contracting is fragmenting vendor access to long-dated infrastructure projects. Motorola Solutions leverages its command-center software footprint to anchor state-level emergency communications contracts. Honeywell International Inc. competes through building-automation integration that extends from fire safety into broader facility management. Cisco Systems differentiates by controlling the network layer that binds IoT sensor arrays to cloud analytics platforms.
North America public infrastructure safety encompasses the engineered systems, protocols, and monitoring technologies that protect critical physical assets—bridges, tunnels, water treatment plants, power grids, and transit networks—from structural failure, unauthorized intrusion, fire, and operational hazards. These systems typically integrate vibration sensors rated to detect micro-strains below 0.1 millistrain, thermal imaging with sub-50-millikelvin resolution, and redundant communication pathways to ensure continuity during emergencies. Surveillance systems dominate current procurement volumes as municipalities replace analog CCTV with AI-enabled video analytics, while emergency response solutions represent the fastest-expanding margin pool as agencies demand interoperable platforms linking dispatch, field units, and hospital networks. Access control maintains steady replacement demand across federal buildings and utilities, though growth rates trail sensor-heavy categories.
The Federal Highway Administration mandates National Bridge Inspection Standards that force state departments of transportation to deploy structural health monitoring or risk federal funding penalties. EPA lead-and-copper rules and OSHA confined-space entry standards shape water utility investment in worker-safety equipment and real-time contaminant detection. The Cybersecurity and Infrastructure Security Agency issues binding operational directives that accelerate procurement of network-hardened control systems. Stakeholders must weigh the capital efficiency of permanent sensor installations against the flexibility of temporary deployments as climate resilience funding cycles shorten project planning horizons.
Market Dynamics
The Infrastructure Investment and Jobs Act has triggered a funding acceleration that compresses vendor qualification timelines while fragmenting project ownership across state transportation authorities and municipal water districts. Federal mandates now tie capital access to real-time monitoring compliance, forcing procurement teams to prioritize interoperable sensor architectures over proprietary point solutions.
Growth Catalysts
- Federal funding mandates:The Infrastructure Investment and Jobs Act channels billions toward resilient system upgrades, requiring state departments of transportation to deploy structural health monitoring or risk penalty. Bridge retrofit programs in Texas and California exemplify this enforcement mechanism.
- EPA regulatory tightening:Lead-and-copper rules and confined-space entry standards compel water utilities to invest in worker-safety equipment and real-time contaminant detection arrays across the Great Lakes corridor.
- AI-enabled video analytics:Municipalities are replacing analog CCTV with machine-vision surveillance, creating replacement demand that concentrates in federal buildings and transit networks.
Market Restraints
- Semiconductor supply concentration:Vibration sensors and thermal imaging modules depend on concentrated Asian foundry capacity, exposing lead-time volatility for microstrain-rated components.
- Copper and rare-earth input costs:Sensor cabling and magnet assemblies face commodity price swings that compress hardware margins on fixed-price infrastructure contracts.
- Interoperability standards gaps:The absence of unified IoT communication protocols forces redundant integration layers, inflating deployment costs for multi-vendor environments.
Strategic Opportunities
- Canadian provincial water infrastructure:Ontario and Quebec treatment facilities lag US sensor penetration rates, presenting retrofit white space for vibration and thermal monitoring vendors.
- 5G private network convergence:The pairing of cellular edge computing with legacy SCADA systems enables sub-50-millisecond emergency response coordination across distributed transit networks.
- Cybersecurity-hardened procurement:Binding operational directives from the Cybersecurity and Infrastructure Security Agency accelerate replacement of network-exposed control systems with zero-trust architectures.
Industry Challenges
- Field engineering talent scarcity:Deployment of microstrain-rated structural sensors requires certified technicians familiar with confined-space entry protocols, creating recruitment bottlenecks in the Great Lakes region.
- Legacy SCADA integration friction:Water utilities operate decades-old control platforms that resist API-based data extraction, forcing costly middleware development for cloud analytics connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Public Infrastructure Safety Market |
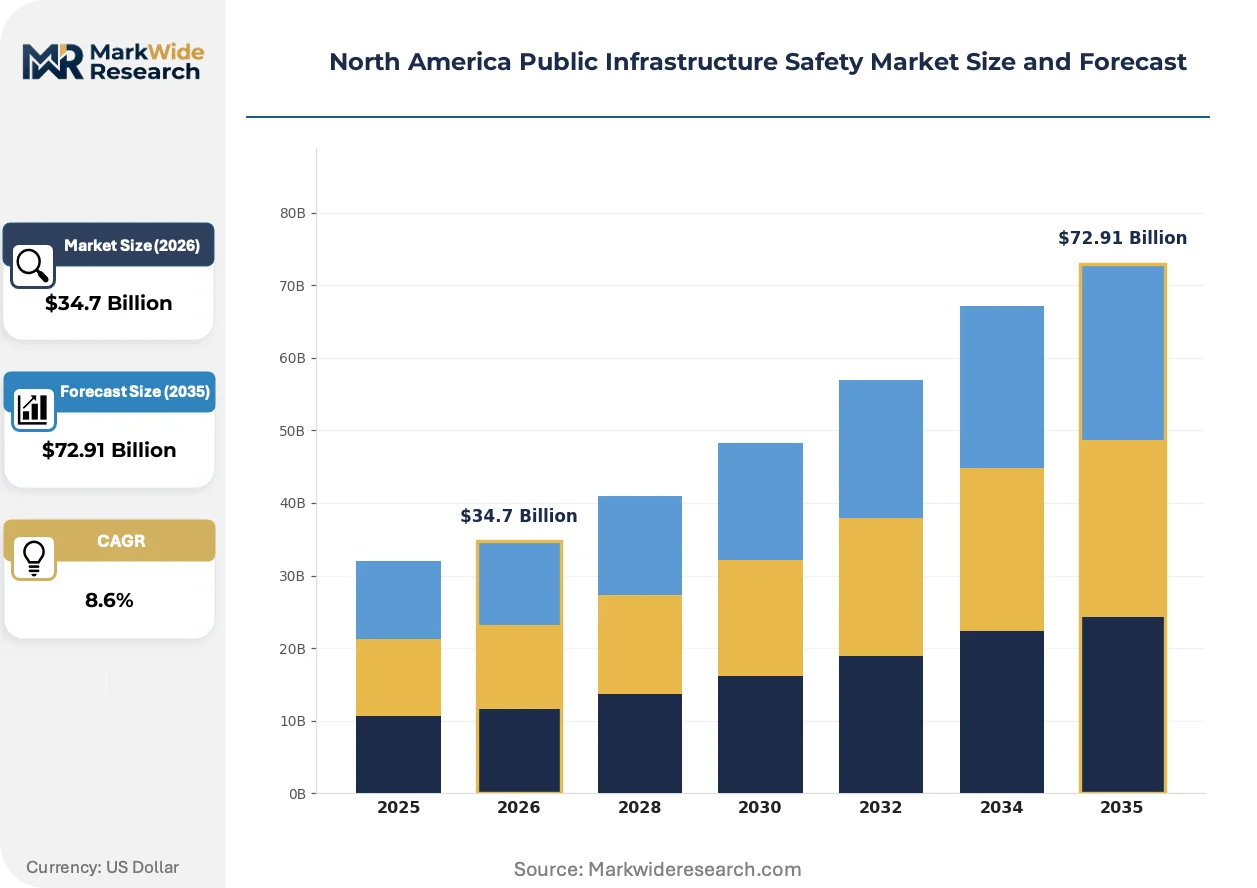
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Access Control, Fire Safety Equipment, Emergency Response Solutions End User: Government Agencies, Construction Firms, Transportation Authorities, Utilities Technology: IoT Sensors, CCTV, Drones, AI Analytics Installation Type: Permanent Installations, Temporary Deployments, Integrated Systems, Standalone Solutions |
| Companies Covered | Honeywell International Inc., Motorola Solutions, BAE Systems, Lockheed Martin, General Dynamics, Northrop Grumman, Cisco Systems, Thales, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Public Infrastructure Safety Market Trends and Innovations
Edge computing architectures are displacing centralized processing models across distributed infrastructure networks. Sensor arrays now preprocess vibration and thermal data locally, reducing bandwidth load while enabling sub-second anomaly detection.
Digital-twin technology is hybridizing physical asset management with predictive simulation. State bridge authorities in California deploy finite-element models fed by live strain-gauge streams, compressing inspection cycles from biennial to continuous. The technology is hybridizing capital planning by letting engineers stress-test retrofit scenarios before physical intervention, reducing design iteration costs for aging steel truss structures.
The Cybersecurity and Infrastructure Security Agency's binding operational directives are hardening procurement specifications for control-system vendors. Water treatment operators must now demonstrate network segmentation and encrypted telemetry or forfeit federal resilience grants. Municipal utilities in Texas are responding by pre-qualifying only vendors with FedRAMP-authorized cloud platforms, narrowing the supplier pool for SCADA modernization.
Availability-based contracting is fragmenting traditional equipment-sales relationships. State transportation departments now pay per functional bridge-mile monitored rather than capitalizing sensor hardware, transferring operational risk to integrators. This model concentrates in the Southwest where extreme temperature cycling accelerates sensor degradation, forcing vendors to price maintenance reserves into long-term service agreements.
North America Public Infrastructure Safety Market Segmentation
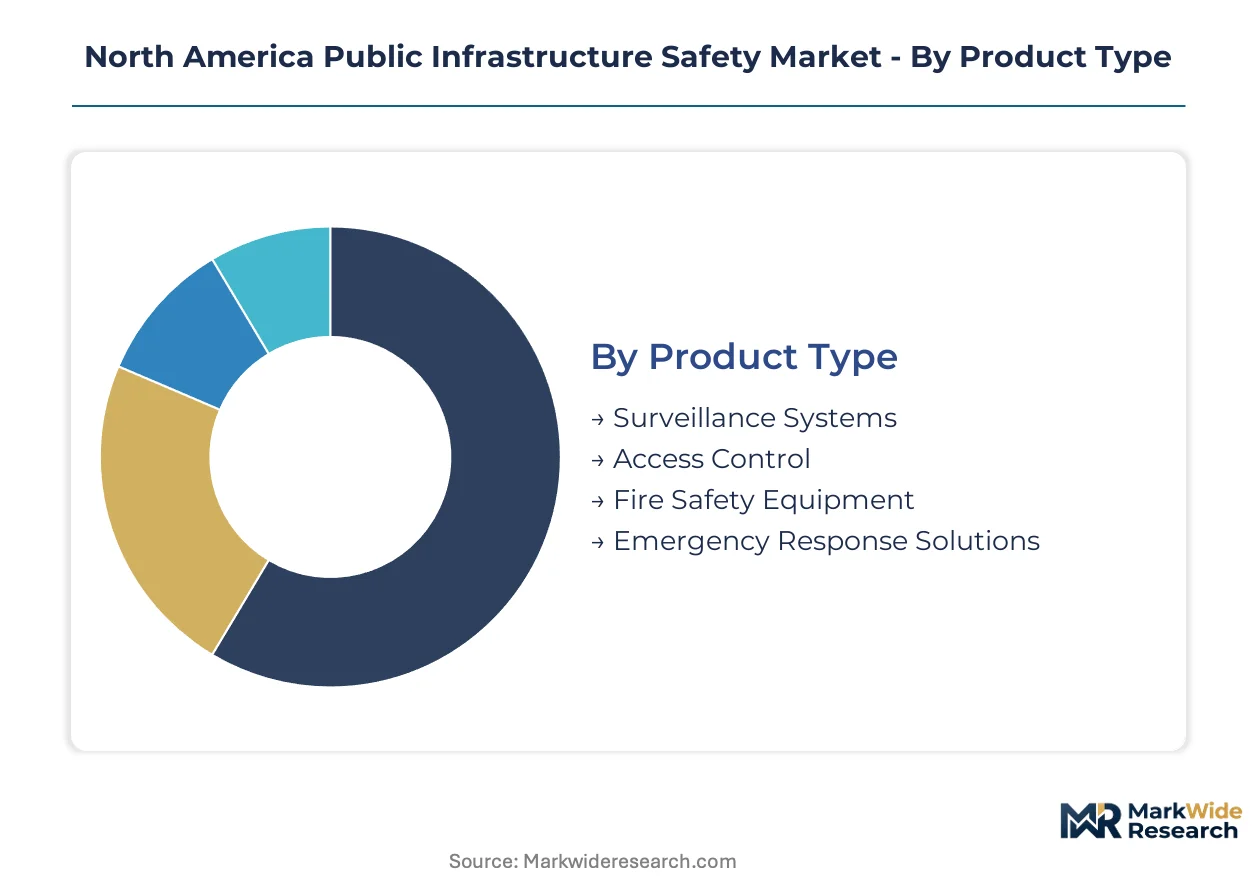
Segmentation in public infrastructure safety reveals how procurement priorities diverge across asset types and operational models. Federal funding mandates and state-level compliance requirements create distinct demand profiles that vendors must address through specialized product architectures.
Product Type:
Cost tiers in hardware procurement separate capital-intensive sensor networks from software-centric monitoring platforms, with replacement cycles and margin structures varying sharply across the spectrum.
- Surveillance Systems:AI-enabled video analytics platforms process real-time feeds from thousands of endpoints across transit networks and federal facilities. Municipalities in Texas and California are replacing analog CCTV with machine-vision infrastructure, driven by federal resilience grants that require interoperable emergency coordination capabilities.
- Access Control:Biometric and credential-based entry systems protect utility substations and government buildings through multi-factor authentication protocols. Demand concentrates in Great Lakes corridor water treatment facilities where EPA lead-and-copper compliance mandates restrict unauthorized physical access to sampling points.
- Fire Safety Equipment:Suppression and detection arrays for tunnels and transit stations.
- Emergency Response Solutions:Dispatch platforms linking field units, hospitals, and command centers.
Surveillance Systems commands the established base. The steepest expansion runs through Emergency Response Solutions.
End User:
Application contexts range from regulatory enforcement to capital construction, with each end user imposing distinct technical specifications and procurement timelines on vendor relationships.
- Government Agencies:Federal buildings and military installations require FedRAMP-authorized platforms with zero-trust network architectures. CISA binding operational directives now disqualify vendors lacking demonstrated network segmentation, compressing the qualified supplier pool for SCADA modernization contracts.
- Transportation Authorities:State departments of transportation deploy structural health monitoring on bridge inventories to satisfy Federal Highway Administration inspection standards. California and Texas authorities are expanding smart bridge programs that integrate vibration sensors with cloud-based finite-element modeling.
- Utilities:Water and power operators managing aging distribution infrastructure.
- Construction Firms:Project-phase safety systems for active worksites.
Transportation Authorities anchor current procurement volumes. Government Agencies are climbing the fastest as cybersecurity hardening accelerates replacement cycles.
Technology:
Technical maturity separates legacy analog systems from digitally native architectures, with integration complexity and data throughput requirements determining deployment feasibility across infrastructure asset classes.
- IoT Sensors:Microstrain-rated vibration gauges and sub-50-millikelvin thermal imagers feed edge-computing nodes that preprocess structural data locally. Bridge authorities in California deploy these arrays to compress inspection cycles from biennial to continuous, reducing reliance on manual confined-space entry.
- AI Analytics:Machine-vision algorithms detect anomalies in video feeds and sensor streams without human-in-the-loop review. Water utilities in the Great Lakes corridor apply these tools to real-time contaminant detection arrays, satisfying EPA worker-safety standards while reducing laboratory confirmation delays.
- CCTV:Transitioning analog infrastructure to IP-based digital networks.
- Drones:Aerial inspection platforms for hard-to-reach structural elements.
CCTV retains the largest installed base. AI Analytics is gaining share fastest as municipalities replace reactive monitoring with predictive platforms.
Installation Type:
Customer risk preferences and project funding horizons determine whether agencies favor capital ownership or operational expenditure models, with availability-based contracting fragmenting traditional equipment sales relationships.
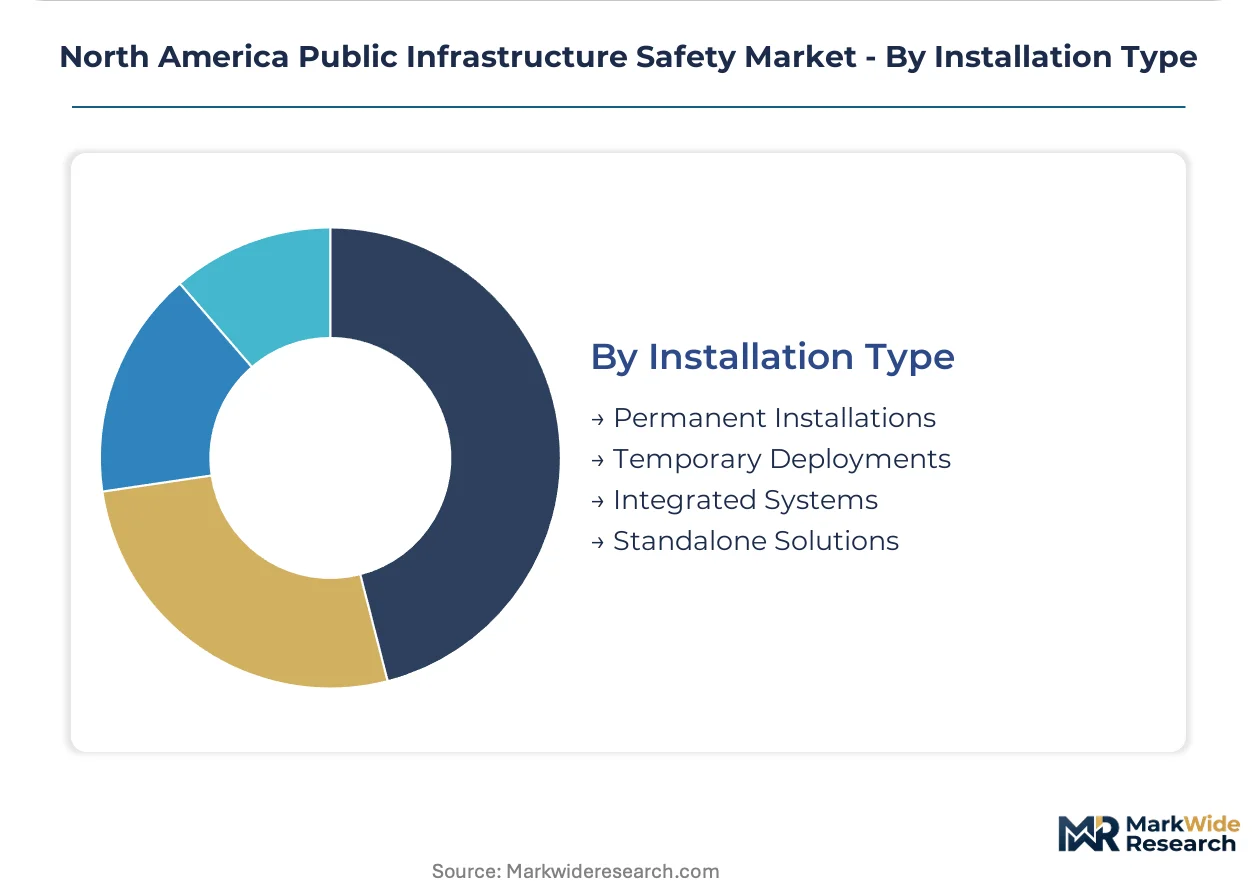
- Permanent Installations:Hardened sensor networks with decade-long service life expectations anchor bridge monitoring and water treatment safety systems. Southwest state transportation departments now procure these through per-functional-mile contracts that transfer sensor degradation risk to integrators.
- Temporary Deployments:Rapidly deployable monitoring for construction phases or emergency response. Climate resilience funding cycles that shorten planning horizons favor this flexibility, though unit economics suffer from repeated mobilization costs.
- Integrated Systems:Multi-vendor architectures requiring middleware development for legacy SCADA connectivity.
- Standalone Solutions:Point applications without broader network integration requirements.
Permanent Installations dominate capital budgets. Temporary Deployments are expanding most quickly as federal infrastructure funding accelerates project starts without multi-year planning horizons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Infrastructure Investment and Jobs Act channels federal capital toward resilient system upgrades across the continent, compressing vendor qualification timelines while fragmenting project ownership across state transportation authorities and municipal water districts. Federal mandates now tie capital access to real-time monitoring compliance, forcing procurement teams to prioritize interoperable sensor architectures over proprietary point solutions.
United States
State transportation authorities in Texas and California are expanding smart bridge monitoring programs that integrate vibration sensors with cloud-based finite-element modeling. The Federal Highway Administration mandates National Bridge Inspection Standards that force state departments of transportation to deploy structural health monitoring or risk federal funding penalties. The Great Lakes corridor concentrates demand where aging water treatment facilities require sensor retrofits to satisfy EPA lead-and-copper rules.
Canada
Ontario and Quebec treatment facilities lag US sensor penetration rates, presenting retrofit white space for vibration and thermal monitoring vendors. Health Canada and provincial environmental regulators are tightening oversight of drinking water infrastructure, accelerating procurement timelines for real-time contaminant detection arrays. Toronto and Montreal municipal utilities are responding by pre-qualifying vendors with FedRAMP-authorized cloud platforms for SCADA modernization.
Mexico
Federal infrastructure spending under the current administration emphasizes water distribution network rehabilitation in the Mexico City metro area and northern industrial corridors. SEMARNAT environmental standards are converging toward US EPA frameworks, creating compliance-driven demand for worker-safety equipment in confined-space applications. Monterrey and Guadalajara are emerging as concentration points for smart city pilot programs that test IoT sensor integration in transit networks.
North America Public Infrastructure Safety Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where public-private partnership financing fragments vendor access to long-dated infrastructure projects. The market structure tiers between diversified conglomerates with cross-portfolio bundling power and focused specialists with vertical technology depth. Three archetypes dominate: network-layer platform providers, integrated building-automation vendors, and command-center software specialists. Competitive moves concentrate on strategic partnerships for interoperability certification and geographic expansion through state-level emergency communications contracts.
Among US-based diversified technology conglomerates, Honeywell International Inc. and Cisco Systems occupy positions that exemplify contrasting strategic anchors. Honeywell represents the building-automation integrator archetype, competing through facility management extension from fire safety into broader operational control. Cisco anchors the network-infrastructure specialist tier, differentiating by controlling the connectivity layer that binds IoT sensor arrays to cloud analytics platforms. Motorola Solutions sits within the command-center software specialist category, leveraging state-level relationships to secure emergency communications contracts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Motorola Solutions |
| BAE Systems |
| Lockheed Martin |
| General Dynamics |
| Northrop Grumman |
| Cisco Systems |
| Thales |
| IBM |
| Others |
Pricing and Supply Chain Analysis
Asian foundry concentration for microstrain-rated vibration sensors and thermal imaging modules concentrates margin capture with semiconductor vendors, forcing infrastructure integrators to absorb lead-time volatility through buffer inventory or premium sourcing contracts.
Pricing Analysis
Certification level creates the primary spread between FedRAMP-authorized platforms and uncertified alternatives, with three-tier pricing structure across premium, standard, and economy levels. Project-based contracting dominates for permanent bridge installations, while availability-based per-mile models transfer operational risk to vendors in extreme-climate states. Price differentiation hinges on cybersecurity hardening depth and after-sales maintenance bundling. Municipal water districts in the Great Lakes corridor exhibit highest price sensitivity due to fragmented ownership, whereas federal agencies prioritize certification compliance over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced thermal imaging sensors and precision accelerometers limit flows from US and allied suppliers to critical infrastructure operators, forcing procurement teams toward qualified vendor lists. Component sourcing draws from Taiwan for edge-computing processors, South Korea for memory modules, and domestic US facilities for hardened communication chipsets. Rare-earth magnet assemblies and copper sensor cabling face commodity price swings that compress hardware margins. Distribution runs through state-procurement frameworks and federal GSA schedules, with integrators managing multi-vendor integration complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified field engineering capacity for confined-space sensor deployment represents the binding constraint across North American infrastructure markets, with technician scarcity compressing project velocity more than capital availability.
For Market Incumbents: Harden cybersecurity certification portfolios to maintain access to CISA-mandated procurement channels as zero-trust architectures become disqualifying filters. Deepen backward integration into edge-computing hardware to reduce exposure to Asian foundry lead-time volatility. Anchor state-level relationships through emergency communications platform stickiness, as Motorola Solutions has demonstrated across Texas and California transportation authorities. For New Entrants and Emerging Players: Pursue Canadian provincial water infrastructure in Ontario and Quebec where sensor penetration lags US benchmarks by several years. Target 5G private network integration for transit authorities seeking sub-50-millisecond emergency response coordination. Lead with FedRAMP-authorized cloud platforms to bypass lengthy federal qualification cycles that disadvantage unproven vendors. For Investors and Strategic Acquirers: Capital is best deployed toward vertical-technology specialists with demonstrated interoperability certification across multi-vendor environments, as availability-based contracting fragments traditional equipment-sales relationships. Mid-cap sensor manufacturers with captive calibration facilities command scarcity premiums. Watch CISA directive expansion timelines as the inflection signal for accelerated replacement cycles in water utility SCADA systems.| Strategic Initiative | Industry Significance |
|---|---|
| Interoperability Certification Investment | FedRAMP and state-level emergency communications credentials unlock federal infrastructure grants. |
| Edge Computing Hardware Integration | Local preprocessing reduces bandwidth costs for bridge monitoring arrays in bandwidth-constrained corridors. |
| Availability-Based Contracting Transition | Per-functional-mile models transfer sensor degradation risk to vendors in extreme-temperature states. |
| 5G Private Network Deployment | Cellular edge computing enables sub-50-millisecond coordination across distributed transit networks. |
| Digital Twin Platform Development | Finite-element modeling fed by live strain-gauge streams compresses California bridge inspection cycles. |
Research Methodology
Initial hypotheses were tested against primary input from state transportation procurement officers, water utility engineering directors, federal emergency management coordinators, and systems integration specialists, then refined against secondary validation from FHWA bridge inventory databases, EPA enforcement action records, CISA binding operational directives, and state-level procurement disclosure filings. Bottom-up project pipeline analysis triangulated with top-down federal funding allocation tracking.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, end-user authority, technology maturity tier, and installation model. CAGRs were derived from fitted growth curves calibrated to Infrastructure Investment and Jobs Act disbursement schedules and state-level regulatory compliance deadlines. Industry-specific inputs included bridge inventory age distributions, water treatment facility lead-and-copper violation rates, and emergency communications interoperability upgrade cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers into edge infrastructure would shift outcomes beyond modeled ranges. Material shifts in CISA directive scope or EPA enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market
Critical Infrastructure Protection
Guardrail Protection System Market