
 Europe Tank Protection Market | 2026-2036
Europe Tank Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tank Protection Market Insights
Industrial distributor networks across Northern Europe are rewriting procurement pathways for tank protection systems. Schneider Electric SE leverages its automation portfolio to anchor digital monitoring solutions for petrochemical terminals. Siemens AG competes through integrated protection systems that combine corrosion sensors with predictive maintenance software. Rheinmetall AG specializes in armored and blast-resistant tank enclosures for defense fuel depots across Central Europe.
Tank protection encompasses engineered systems, materials, and services that preserve the structural integrity and operational safety of above-ground and underground storage vessels, typically incorporating cathodic protection circuits, polymer linings rated for chemical resistance, and automated leak detection arrays to prevent environmental release. The technology dimension splits across corrosion prevention, protection systems, monitoring solutions, and maintenance tools, with monitoring solutions commanding premium margins as operators shift from scheduled inspections to continuous digital oversight. Coatings and anodes within the product type category dominate current revenue, while liners represent the fastest-growing segment as owners extend tank service life rather than replacing aged carbon steel shells.
EMA's environmental risk assessments, REACH chemical compliance protocols, and the EU Green Deal's tightening emissions standards collectively elevate product certification requirements for tank protection suppliers. Germany's KBA enforces transport-related storage safety rules that cascade into industrial tank specifications. Stakeholders must track how CSRD reporting obligations will force asset owners to document tank integrity metrics with greater granularity.
Market Dynamics
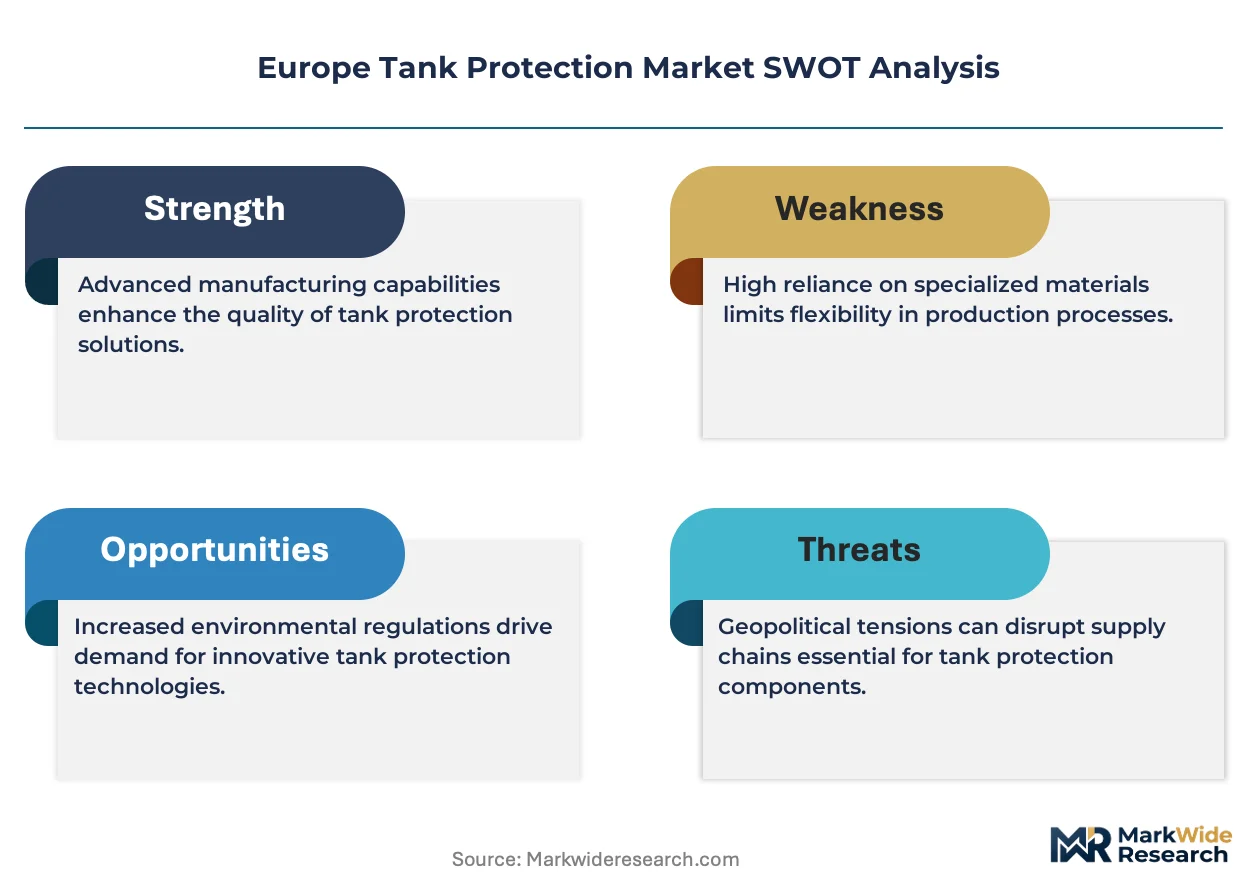
EU Green Deal mandates are forcing petrochemical operators across the Rhine-Ruhr corridor to accelerate tank integrity upgrades ahead of Industrial Emissions Directive deadlines, compressing replacement cycles for aging above-ground storage infrastructure.
Growth Catalysts
- Industrial Emissions Directive:The EU Green Deal's tightening storage integrity requirements for hazardous liquids mandate leak detection upgrades across petrochemical terminals in Belgium and the Netherlands.
- Rhine-Ruhr corridor expansion:Petrochemical refineries across this industrial cluster are expanding tank farm protection budgets to accommodate higher throughput volumes.
- Polymer liner technology:Advanced chemical-resistant linings enable tank life extension rather than carbon steel shell replacement, driving retrofit demand.
Market Restraints
- Zinc anode supply concentration:Sacrificial anode production concentrates in Central European foundries, exposing buyers to input cost volatility and extended lead times.
- REACH compliance friction:ECHA chemical registration requirements for protective coatings create formulation lock-in, slowing product innovation cycles.
- Carbon fiber substitution threat:Composite tank construction for new installations displaces traditional steel tank protection demand in specialty chemical storage.
Strategic Opportunities
- Eastern European underpenetration:Poland and Czech Republic tank farms operate with dated protection systems, creating upgrade potential as these markets align with EU environmental standards.
- CSRD reporting tailwind:Corporate Sustainability Reporting Directive obligations force asset owners to document tank integrity metrics, driving digital monitoring adoption.
- Sensor-AI convergence:Integration of corrosion sensors with predictive maintenance software creates continuous oversight platforms for terminal operators.
Industry Challenges
- Cathodic protection engineering shortage:Specialized technicians capable of designing impressed current systems for large tank farms remain scarce across Northern Europe.
- Legacy system integration complexity:Retrofitting automated leak detection onto 1970s-era tank farms requires custom engineering without standardized mounting protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tank Protection Market |
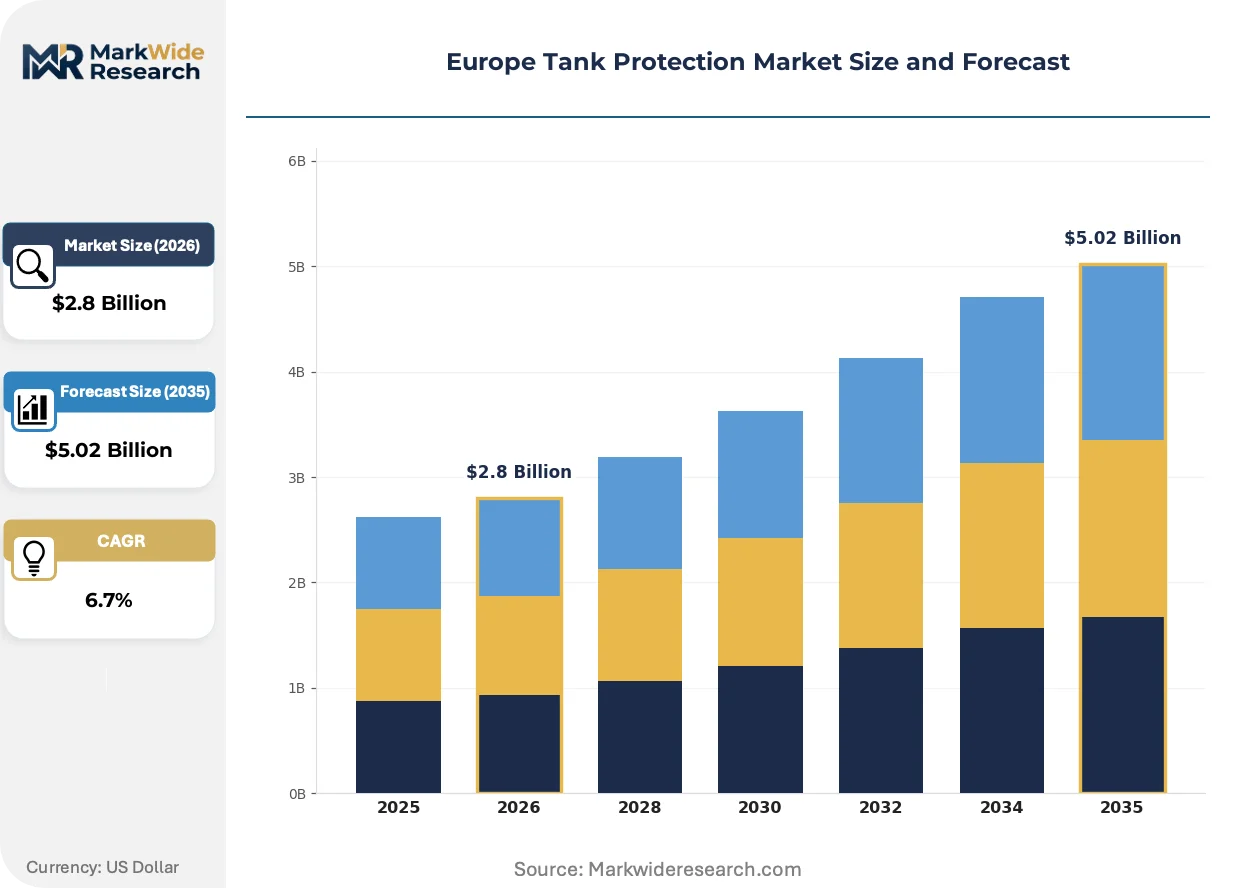
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Castings, Liners, Coatings, Anodes Technology: Corrosion Prevention, Protection Systems, Monitoring Solutions, Maintenance Tools End User: Petrochemical, Water Treatment, Oil & Gas, Industrial Storage Deployment: On-Site, Off-Site, Mobile Solutions, Stationary Installations |
| Companies Covered | Emerson Electric Co, Honeywell International Inc, Schneider Electric SE, Siemens AG, Flowserve Corporation, Pentair plc, Alfa Laval AB, Thales Group, Rheinmetall AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tank Protection Market Trends and Innovations
Digital oversight platforms are displacing scheduled manual inspections across European petrochemical terminals, with operators prioritizing continuous monitoring over periodic compliance checks.
Ultrasonic thickness monitoring arrays combined with cloud analytics is digitizing corrosion tracking for above-ground storage tanks. Terminal operators in the Port of Rotterdam and Antwerp deploy these systems at scale. Real-time data streams compress maintenance decision cycles from quarterly to daily intervals.
CSRD disclosure requirements are elevating documentation standards for tank integrity verification across EU member states. Asset owners must now maintain granular leak detection records spanning equipment lifecycle. Mid-sized chemical distributors in Germany face the steepest compliance burden due to limited legacy data digitization.
Service unbundling separates hardware supply from predictive analytics subscriptions, fragmenting vendor relationships. Traditional coating applicators now compete with software specialists for multi-year terminal contracts. Belgian and Dutch tank farm operators lead this procurement model evolution, negotiating outcome-based performance agreements rather than capital purchase orders.
Europe Tank Protection Market Segmentation
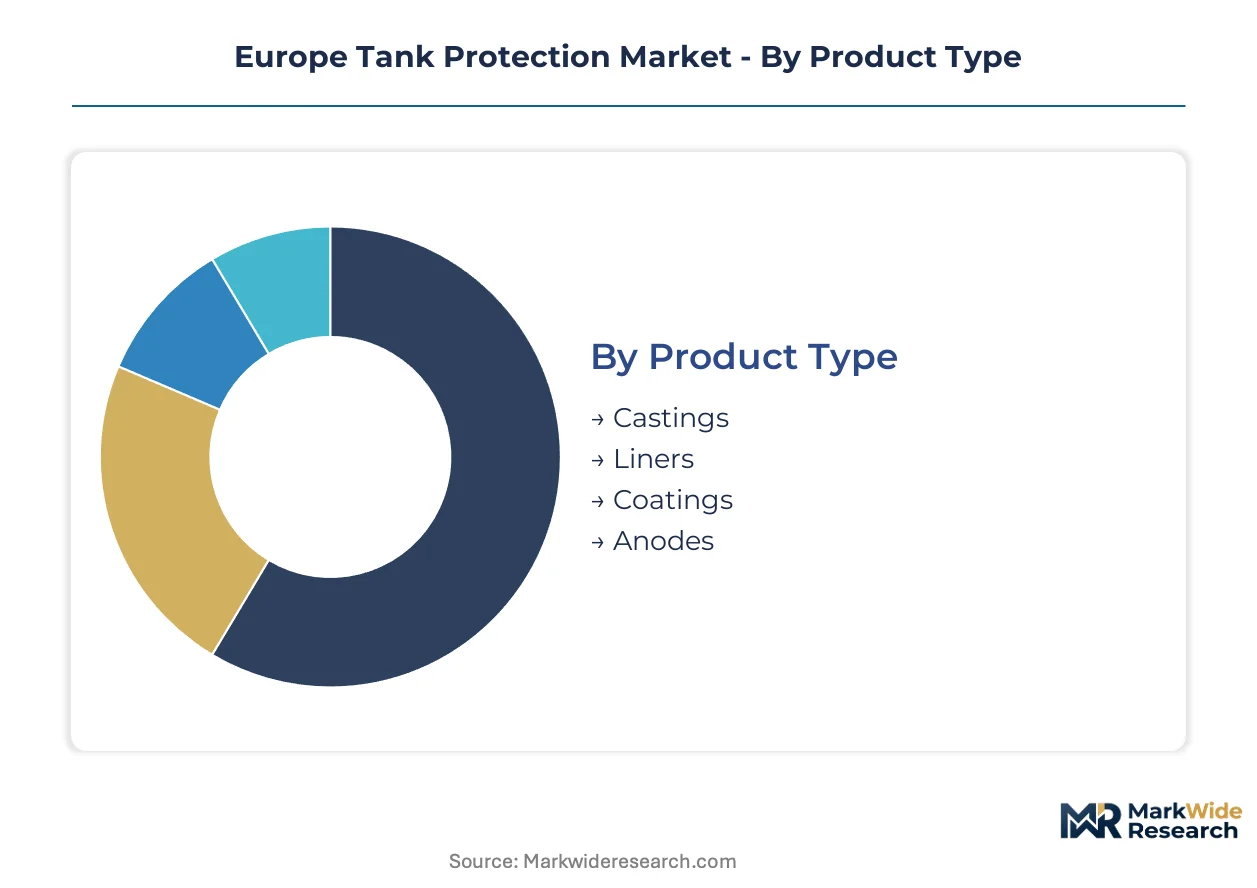
Tank protection procurement across Europe fragments across material technologies, deployment architectures, and end-use risk profiles. Operators in the Rhine-Ruhr corridor and Antwerp-Rotterdam port cluster configure protection stacks differently based on stored chemical hazard classes and regulatory inspection intervals.
Product Type:
Mature coating formulations dominate installed base revenue, while liner technologies sit at the emerging edge of life-extension economics.
- Castings:Sacrificial zinc and aluminum alloy castings form the backbone of cathodic protection systems for buried pipeline connections and tank bottom plates. Demand concentrates in German industrial zones where KBA transport safety rules mandate impressed current backup systems for high-value fuel storage.
- Liners:Advanced polymer membranes—fluoropolymer, epoxy, and vinyl ester formulations—bond to aged carbon steel interiors, eliminating shell replacement. Belgian petrochemical terminals in the Port of Antwerp deploy these for sulfuric acid and caustic soda storage, driven by EU Green Deal emissions containment deadlines.
- Coatings:Epoxy-phenolic and polyurethane spray systems protect external tank surfaces from atmospheric corrosion. German above-ground storage farms represent the core demand cluster.
- Anodes:Magnesium and zinc sacrificial blocks attach to tank exteriors and submerged foundations. Netherlands water treatment facilities specify these for steel reservoir protection.
Coatings handle the majority of throughput; liners are the fastest mover on share.
Technology:
Cost tiering separates preventive hardware from premium digital oversight platforms.
- Corrosion Prevention:Cathodic protection circuits—galvanic and impressed current—electrochemically suppress steel oxidation. Rhine-Ruhr refineries budget heavily for these systems under tightening Industrial Emissions Directive scrutiny.
- Protection Systems:Physical barriers include blast-resistant enclosures for defense fuel depots and secondary containment bunds for chemical terminals. Rheinmetall AG specializes in armored configurations across Central Europe.
- Monitoring Solutions:Ultrasonic thickness arrays, cloud-connected corrosion sensors, and AI-driven predictive platforms command premium margins. Rotterdam terminal operators deploy these for continuous oversight replacing quarterly manual inspections.
- Maintenance Tools:Robotic crawlers and automated surface preparation equipment reduce tank entry hazards. Polish tank farms are adopting these as CSRD reporting obligations intensify documentation requirements.
Monitoring Solutions capture the steepest margin expansion; Maintenance Tools face adoption friction from legacy asset compatibility constraints.
End User:
Application severity drives specification divergence across hazard classes.
- Petrochemical:Refineries and bulk liquid terminals store gasoline, diesel, and feedstock chemicals under strict EMA environmental risk protocols. The Netherlands and Belgium concentrate replacement demand for aging above-ground tanks.
- Water Treatment:Municipal and industrial water utilities protect steel reservoirs and clarifier tanks. German cities prioritize liner retrofits over full reconstruction.
- Oil & Gas:Strategic petroleum reserves and distribution terminals require blast-resistant and fire-rated protection. Czech Republic storage expansion projects source integrated protection systems.
- Industrial Storage:Chemical manufacturers and food processors maintain specialized tanks for acids, solvents, and edible oils. REACH compliance friction shapes coating formulation choices.
Petrochemical absorbs the largest protection spend; Water Treatment is expanding most quickly as infrastructure age triggers retrofit cycles.
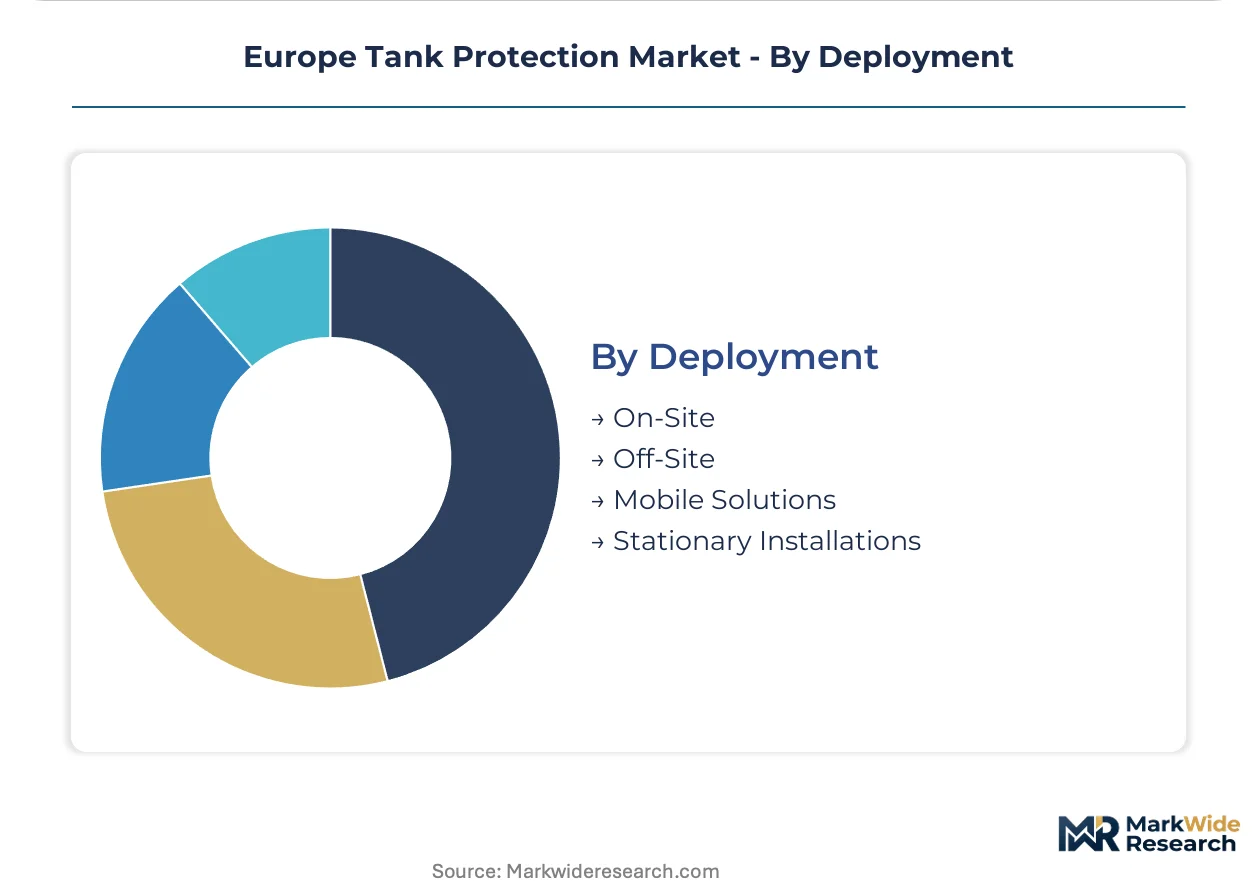
Deployment:
Customer type separates capital-intensive permanent installations from service-based mobility.
- On-Site:Permanent protection systems installed during tank construction or major turnaround. German and Dutch greenfield terminal projects specify these from engineering phase.
- Off-Site:Prefabricated liner panels and modular anode systems manufactured in controlled factory conditions. Belgian applicators ship these to Eastern European upgrade sites.
- Mobile Solutions:Trailer-mounted monitoring equipment and temporary cathodic protection units serve short-term storage and emergency response. Czech chemical distributors lease these for seasonal inventory surges.
- Stationary Installations:Fixed sensor networks and permanent impressed current rectifier systems. Rotterdam operators deploy these at scale for automated compliance documentation.
On-Site deployment anchors the revenue base; Mobile Solutions are climbing the fastest as rental models penetrate mid-sized operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European tank protection demand through its dense concentration of petrochemical terminals, refineries, and chemical processing infrastructure that require continuous integrity management.
Germany
Industrial clusters in North Rhine-Westphalia and Bavaria drive replacement cycles for aging above-ground storage tanks. The KBA enforces transport-related storage safety rules that cascade into stringent tank specifications for fuel depots. BASF's Ludwigshafen complex and Bayer's Leverkusen facilities anchor the nation's cathodic protection engineering demand.
Netherlands
The Port of Rotterdam and Amsterdam-Rijnkanaal terminals concentrate Europe's largest bulk liquid storage capacity under tightening environmental scrutiny. EMA environmental risk assessments mandate upgraded leak detection arrays across petrochemical terminals. Dutch water treatment utilities in Randstad cities prioritize liner retrofits for steel reservoirs over full reconstruction.
Belgium
The Port of Antwerp houses dense chemical storage infrastructure requiring advanced polymer liner deployments for sulfuric acid and caustic soda containment. REACH chemical compliance protocols shape protective coating formulation choices for local applicators. Flemish petrochemical operators face compressed upgrade timelines under EU Green Deal Industrial Emissions Directive deadlines.
Poland
Eastern European tank farms operate with dated protection systems as infrastructure age triggers retrofit cycles. CSRD reporting obligations intensify documentation requirements for mid-sized chemical distributors in Warsaw and Kraków industrial zones. Polish operators are adopting robotic maintenance tools to reduce tank entry hazards while meeting granular integrity verification standards.
France
Île-de-France and Hauts-de-France host strategic petroleum reserves and distribution terminals requiring fire-rated protection systems. ANSM chemical safety protocols influence storage integrity requirements for hazardous liquids in Paris Basin industrial zones. French refineries along the Seine corridor are expanding tank farm protection budgets to accommodate regulatory compliance upgrades.
Europe Tank Protection Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers. Diversified industrial conglomerates with automation portfolios compete against specialized corrosion engineering firms and defense-oriented armored enclosure manufacturers. Strategic archetypes include digital monitoring platform providers, integrated protection system integrators, and blast-resistant specialty fabricators. Competitive moves center on sensor-AI convergence partnerships and service unbundling that separates hardware supply from predictive analytics subscriptions.
Within the diversified industrial tier, Schneider Electric SE, Siemens AG, and Emerson Electric Co exemplify contrasting approaches to tank protection market participation. Schneider Electric SE anchors digital monitoring solutions through its automation portfolio breadth. Siemens AG occupies a position combining corrosion sensors with predictive maintenance software capabilities. Emerson Electric Co represents the process automation conglomerate archetype with instrumentation heritage applicable to leak detection arrays.
| Leading Market Players |
|---|
| Emerson Electric Co |
| Honeywell International Inc |
| Schneider Electric SE |
| Siemens AG |
| Flowserve Corporation |
| Pentair plc |
| Alfa Laval AB |
| Thales Group |
| Rheinmetall AG |
| Others |
Pricing and Supply Chain Analysis
Central European foundries concentrating sacrificial zinc anode production concentrate margin capture upstream, forcing downstream protection system integrators in Germany and the Netherlands to absorb input cost volatility or pass through to petrochemical terminal operators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled monitoring platforms from conventional cathodic protection hardware and commodity coating applications. Price differentiation hinges on certification grade under EU Green Deal Industrial Emissions Directive compliance tiers and volume scale across multi-tank terminal contracts. Cost compression in standard-tier coating applications is intensifying because REACH formulation lock-in restricts supplier switching. Mid-sized Polish chemical distributors exhibit the highest price sensitivity due to limited capital access, while Rotterdam bulk liquid terminals prioritize performance premiums over unit economics.
Supply Chain Analysis
Extended payment terms from Belgian liner applicators to Eastern European upgrade projects are stabilizing cash flow for polymer membrane distributors amid project financing delays. Geographic supply concentration centers on Germany for impressed current rectifier systems, the Netherlands for advanced sensor arrays, and Belgium for fluoropolymer liner manufacturing. Raw material dependencies draw from Norwegian magnesium ingot suppliers, Chinese rare earth elements for corrosion sensors, and German specialty chemical feedstocks for epoxy formulations. Single-source vulnerability in zinc anode foundry capacity exposes buyers to lead time extension risks. Distribution runs through industrial distributor networks that are unbundling hardware supply from predictive analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite tank construction for new chemical storage installations threatens to displace traditional steel protection demand, forcing incumbents to defend retrofit market positioning against structural substitution.
For Market Incumbents: Entrench digital monitoring capabilities through sensor-AI convergence partnerships that embed predictive maintenance software into long-term terminal service contracts. Deepen backward integration into polymer liner manufacturing to capture life-extension retrofit cycles before composite alternatives penetrate specialty chemical storage. The carbon fiber substitution threat demands preemptive positioning in tank life extension economics rather than new-build protection specification. For New Entrants and Emerging Players: Build out mobile solutions rental platforms targeting mid-sized Czech and Polish chemical distributors with limited capital budgets for permanent installations. Eastern European tank farm underpenetration offers the most accessible white-space, particularly for robotic maintenance tools that reduce tank entry hazards while satisfying CSRD documentation requirements. A leasing-based go-to-market angle bypasses incumbent relationships anchored in capital purchase orders. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across monitoring solutions as software margins expand relative to hardware-heavy protection systems. Long-term viability favors platform players combining sensor hardware with recurring analytics revenue over pure coating applicators facing REACH compliance friction. Acquisition targets should display installed base scale in Rhine-Ruhr or Antwerp-Rotterdam corridors. Watch for EU Green Deal enforcement acceleration as the inflection signal that compresses replacement cycles and elevates digital oversight penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Liner Manufacturing | Captures life-extension retrofit demand ahead of composite tank substitution in Belgian sulfuric acid storage. |
| Sensor-AI Convergence Partnership | Embeds predictive maintenance platforms into Rotterdam terminal operator procurement specifications. |
| Mobile Solutions Rental Platform Launch | Penetrates mid-sized Polish chemical distributors with seasonal inventory surge requirements. |
| REACH-Compliant Coating Formulation Investment | Unlocks German industrial storage procurement blocked by ECHA chemical registration friction. |
| Eastern European Distribution Channel Expansion | Positions for CSRD-driven upgrade cycles in Warsaw and Kraków industrial zones. |
Research Methodology
Cross-validation between primary interviews with terminal operations managers, cathodic protection engineering specialists, and industrial procurement leads and secondary validation through ECHA REACH registration databases, EU Green Deal directive documentation, and German KBA transport safety filings anchors the qualitative findings. Customs data tracking zinc anode and polymer liner trade flows, SEC filings from listed industrial conglomerates, and petrochemical terminal capacity expansion announcements provide quantitative grounding. Bottom-up project pipeline assessment triangulates against top-down market size calibration across the analysis window.
Calibration against historical tank replacement cycles and regulatory enforcement timelines shapes the projection framework. Segmentation dimensions span product type, technology tier, end-use hazard class, and deployment architecture. CAGRs derive from regression analysis of capital expenditure patterns across Rhine-Ruhr and Antwerp-Rotterdam corridor operators. Forecast inputs incorporate EU Green Deal implementation pace and CSRD disclosure requirement adoption curves.
Practitioners should monitor regulatory enforcement acceleration, composite tank cost parity milestones, and zinc supply disruption indicators for early signals. Forecasts reflect documented assumptions regarding petrochemical throughput expansion and environmental compliance stringency trajectories. Macroeconomic contraction, regulatory delay, or breakthrough composite material performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Middle East Commercial Security Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market