
 Brazil Retail Banking Market | 2026-2036
Brazil Retail Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Retail Banking Market Outlook
Cloud-native core banking migration is reshaping how retail financial products are architected and delivered across Brazil. Itaú Unibanco leverages its proprietary technology stack to sustain branch-digital hybrid operations at national scale. Nubank anchors its competitive position through mobile-first credit origination and zero-fee account structures. Banco do Brasil competes via its expansive physical network and government-backed lending programs.
Brazil retail banking encompasses deposit-taking, credit extension, payment facilitation, and wealth services directed at consumers and small enterprises, operating through regulated capital adequacy frameworks and central bank liquidity requirements. The sector channels household savings into productive credit while managing default risk through centralized credit bureaus and collateral registries. Individual customer segments dominate deposit volumes, while small businesses represent the fastest-growing demand pool for working capital and receivables financing. Mobile banking delivery models capture the majority of new account openings, though branch services retain importance for mortgage origination and complex wealth management advisory.
ANVISA oversees data protection standards applicable to health-linked financial products, while the Central Bank of Brazil's Open Finance regulation mandates interoperable data sharing and instant payment infrastructure through Pix. The National Monetary Council sets capital reserve requirements that directly constrain lending capacity and product pricing flexibility. Stakeholders must monitor how evolving central bank digital currency pilots and credit registry expansions alter competitive moats between incumbent banks and licensed fintechs.
Market Dynamics
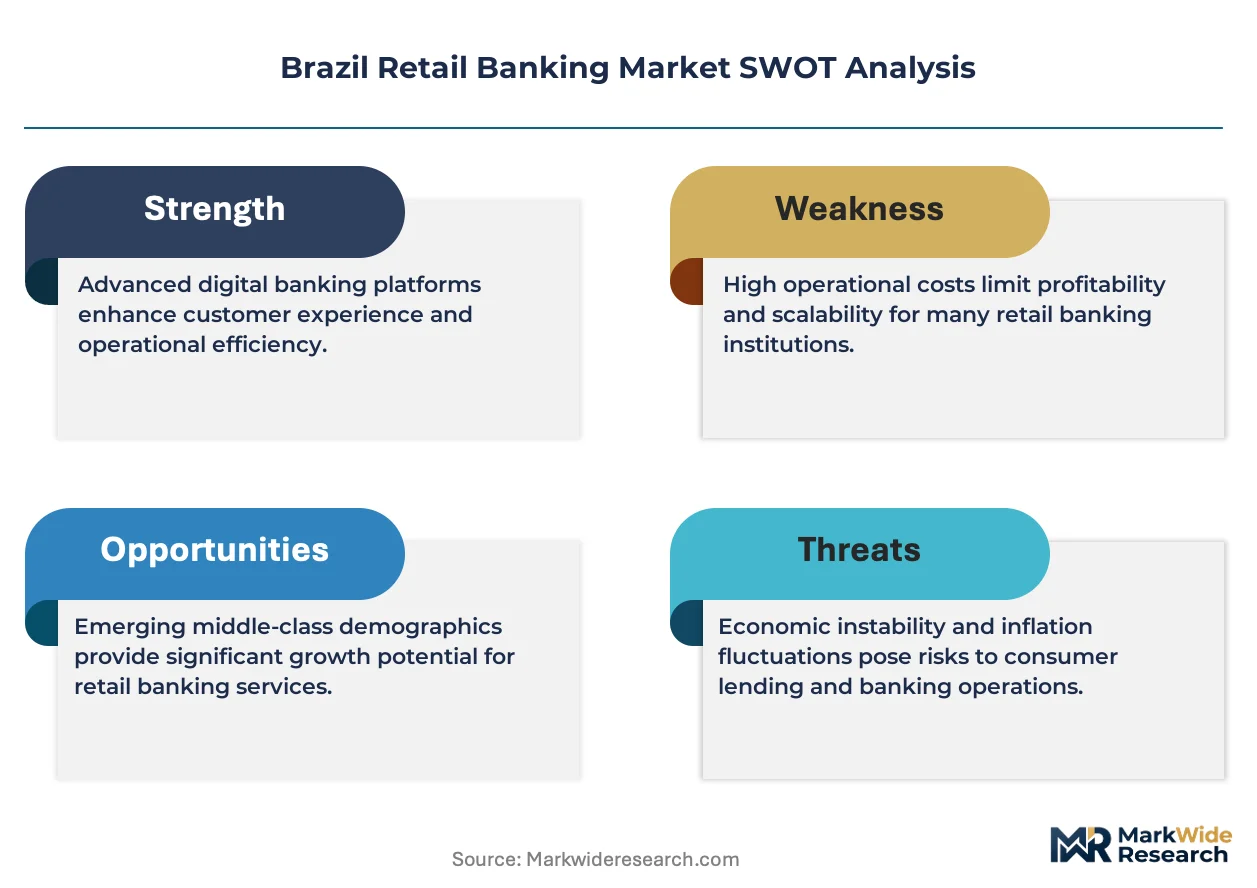
Open Finance regulation is compressing data moats between incumbent banks and licensed fintechs across Brazil's retail banking sector. The Central Bank of Brazil's API mandates and instant payment infrastructure through Pix are forcing incumbents to compete on execution speed rather than proprietary customer data.
Growth Catalysts
- Pix instant payment infrastructure:The Central Bank of Brazil's real-time settlement rails reduce transaction friction for small merchants. Microbusiness adoption of QR-code payments accelerates working capital velocity.
- Southeast region digital credit demand:São Paulo state concentrates fintech-bank competition intensity. Small enterprises in this corridor seek faster receivables financing than traditional collateral-based products permit.
- Cloud-native core banking migration:API-first architectures slash product development cycles from months to weeks. Institutions modernizing legacy mainframes capture mobile-first customer acquisition economics.
Market Restraints
- Centralized credit bureau concentration:Serasa Experian and Boa Vista SCPC dominate scoring data, creating single-point-of-failure risk for origination decisions.
- National Monetary Council reserve requirements:Mandatory capital buffers constrain lending capacity during high-growth demand periods. Pricing flexibility compresses when regulatory floors bind.
- Legacy core system technical debt:COBOL-based transaction engines resist real-time API integration. Maintenance costs divert technology budgets from customer-facing innovation.
Strategic Opportunities
- Northeast and North region underpenetration:Amazonas and Pará states show lower branch density per capita than Southeast benchmarks. Mobile-first distribution models bypass physical infrastructure gaps.
- Open Finance data monetization:Consent-based transaction history sharing enables personalized credit offers. Fintechs leverage enriched datasets for thin-file customer underwriting.
- Embedded finance convergence:Banking-as-a-Service APIs integrate deposit and credit products into retail ERP systems. Agricultural commodity traders embed working capital at point of sale.
Industry Challenges
- Cloud architecture talent scarcity:Kubernetes and microservices expertise concentrates in São Paulo and Rio de Janeiro metro areas. Regional institutions struggle to recruit against fintech compensation premiums.
- Multi-decade mainframe integration complexity:Hybrid cloud-batch architectures create transaction consistency failures during peak loads. Customer-facing outages damage trust in digital channel reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Retail Banking Market |
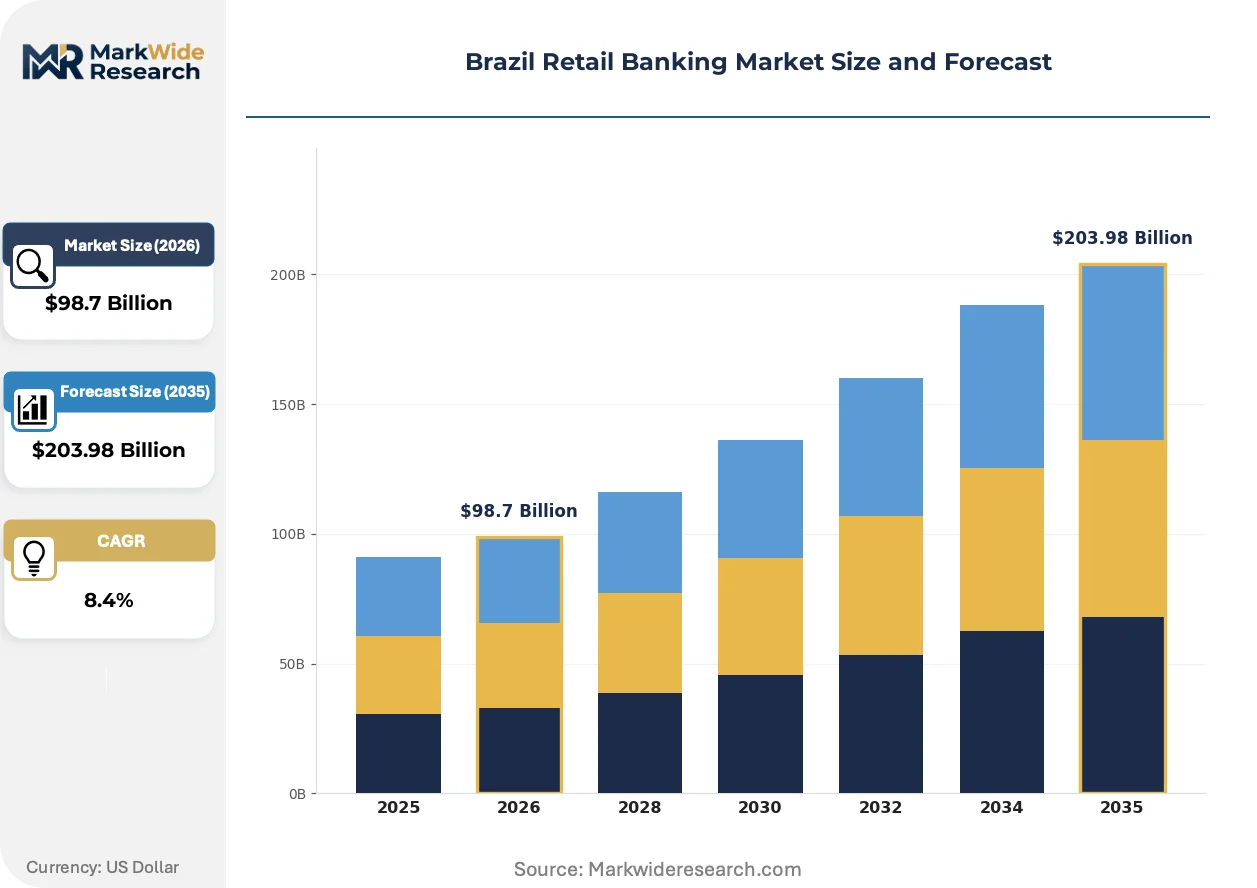
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Individual Customers, Small Businesses, Corporates, Wealth Management Service Type: Checking Accounts, Savings Accounts, Loans, Credit Cards Delivery Model: Online Banking, Mobile Banking, Branch Services, ATM Services Product Type: Mortgages, Personal Loans, Investment Funds, Insurance |
| Companies Covered | Caixa Econômica Federal, Nubank, Itaú Unibanco, Banco Votorantim, Banco Inter, Banco do Brasil, Santander Brasil, Banco Pan, Banco Bradesco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Retail Banking Market Strategic Shifts
Artificial intelligence and instant payment rails are restructuring how Brazilian retail banks originate credit, price risk, and retain customers. Three converging developments dominate strategic planning.
Generative AI is hybridizing credit decisioning workflows across Brazilian institutions. Large language models parse unstructured borrower documents—tax filings, invoices, contracts—that traditional scoring algorithms ignore. Mid-tier banks deploy these tools to compete with fintech speed without matching their technology headcount. The technology is hybridizing risk assessment by combining bureau scores with alternative data signals in real-time inference pipelines.
The Central Bank of Brazil's Open Finance regulation mandates interoperable data sharing across deposit, credit, and insurance products. Financial institutions must expose standardized APIs for account information and payment initiation by customer consent. This policy compresses product differentiation based on data exclusivity. Incumbents respond by investing in proprietary analytics layers atop shared raw data.
Small business borrowers are consolidating relationships with single-platform providers rather than fragmenting across specialized vendors. Merchants that adopted Pix for payments now seek integrated receivables financing and payroll from the same interface. This behavioral shift rewards institutions with broad product suites over point-solution specialists. The pattern is most visible in São Paulo's urban commercial corridors where platform switching costs accumulate rapidly.
Brazil Retail Banking Market Segmentation
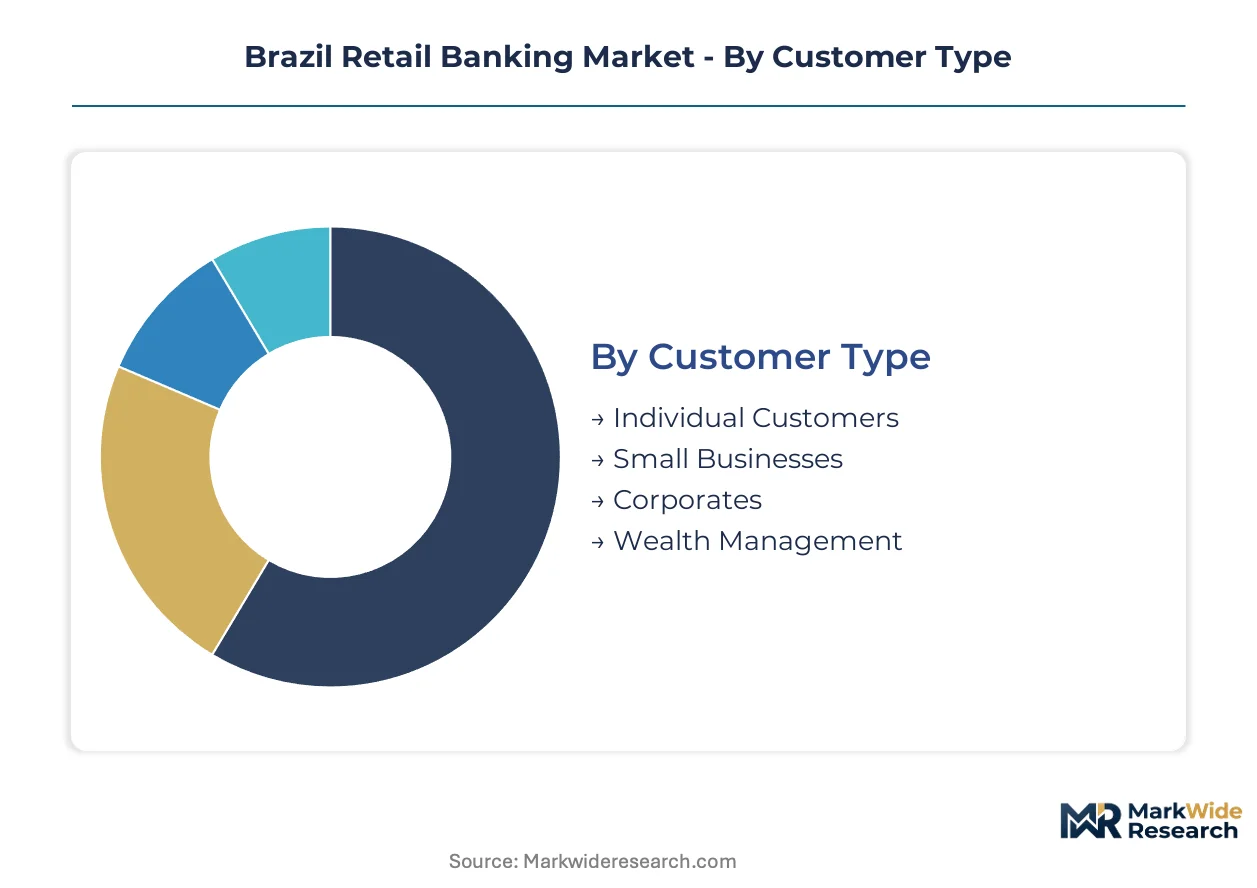
Brazil's retail banking segmentation reveals divergent profitability profiles across customer cohorts and delivery channels. Product velocity varies dramatically—from daily transactional accounts to decade-tenured mortgage relationships—shaping capital allocation and technology investment priorities for institutions competing under Open Finance mandates.
Customer Type:
Transaction frequency and relationship tenure separate segments with radically different unit economics and cross-sell potential.
- Individual Customers:Mass-market depositors generate low-margin transactional volume at high frequency. São Paulo metropolitan concentration drives mobile-first acquisition costs below interior state benchmarks by half.
- Small Businesses:Micro-merchants and formalized SMEs exhibit the shortest product origination cycles—working capital facilities renew quarterly against receivables. Pix adoption in Southeast commercial corridors accelerates credit decision velocity from weeks to hours.
- Corporates:Treasury management relationships lock in multi-year commitments with embedded foreign exchange and payroll services. Centralized credit bureau scoring reduces origination friction for established entities with Serasa Experian track records.
- Wealth Management:High-net-worth households demand illiquid alternative investments alongside traditional custody. Advisory fees concentrate in Rio de Janeiro and São Paulo where family office density exceeds national averages.
Individual Customers anchors the volume base while Small Businesses gains share at the steepest rate.
Service Type:
Revenue per transaction and regulatory capital intensity create distinct competitive battlegrounds across traditional and emerging product formats.
- Checking Accounts:Zero-fee structures dominate customer acquisition with interchange and float income subsidizing operational costs. Nubank's digital-first model demonstrates that deposit gathering without branch infrastructure achieves national scale.
- Savings Accounts:Remunerated deposits compete directly with government bond alternatives for household liquidity preference. National Monetary Council reserve requirements constrain pricing flexibility during monetary tightening cycles.
- Loans:Collateralized mortgage products carry the longest duration and highest capital charges. Agricultural credit and payroll-deducted consumer loans concentrate default risk in specific regional economies.
- Credit Cards:Revolving balances generate the steepest interest spreads among mass-market products. Cloud-native issuers compress fraud detection latency below legacy processor thresholds.
Checking Accounts commands the widest customer footprint while Credit Cards delivers the highest revenue intensity per active user.
Delivery Model:
Channel economics diverge sharply between fixed-cost physical networks and marginal-cost digital infrastructure.
- Online Banking:Browser-based interfaces serve corporate treasurers and wealth clients requiring multi-screen workflows. Security authentication protocols add friction that mobile-native designs have largely eliminated.
- Mobile Banking:Smartphone-native experiences capture over three-quarters of new account openings nationally. Pix instant payment integration transformed mobile apps from inquiry tools to primary transaction terminals.
- Branch Services:Physical locations concentrate mortgage origination and complex advisory conversations. Banco do Brasil's interior network maintains relevance where digital literacy and document notarization requirements persist.
- ATM Services:Cash withdrawal infrastructure faces volume compression as Pix peer-to-peer transfers displace physical currency. Maintenance and cash logistics costs erode profitability in low-density Northeast municipalities.
Mobile Banking has overtaken Branch Services as the primary customer touchpoint while ATM Services contracts in transaction share.
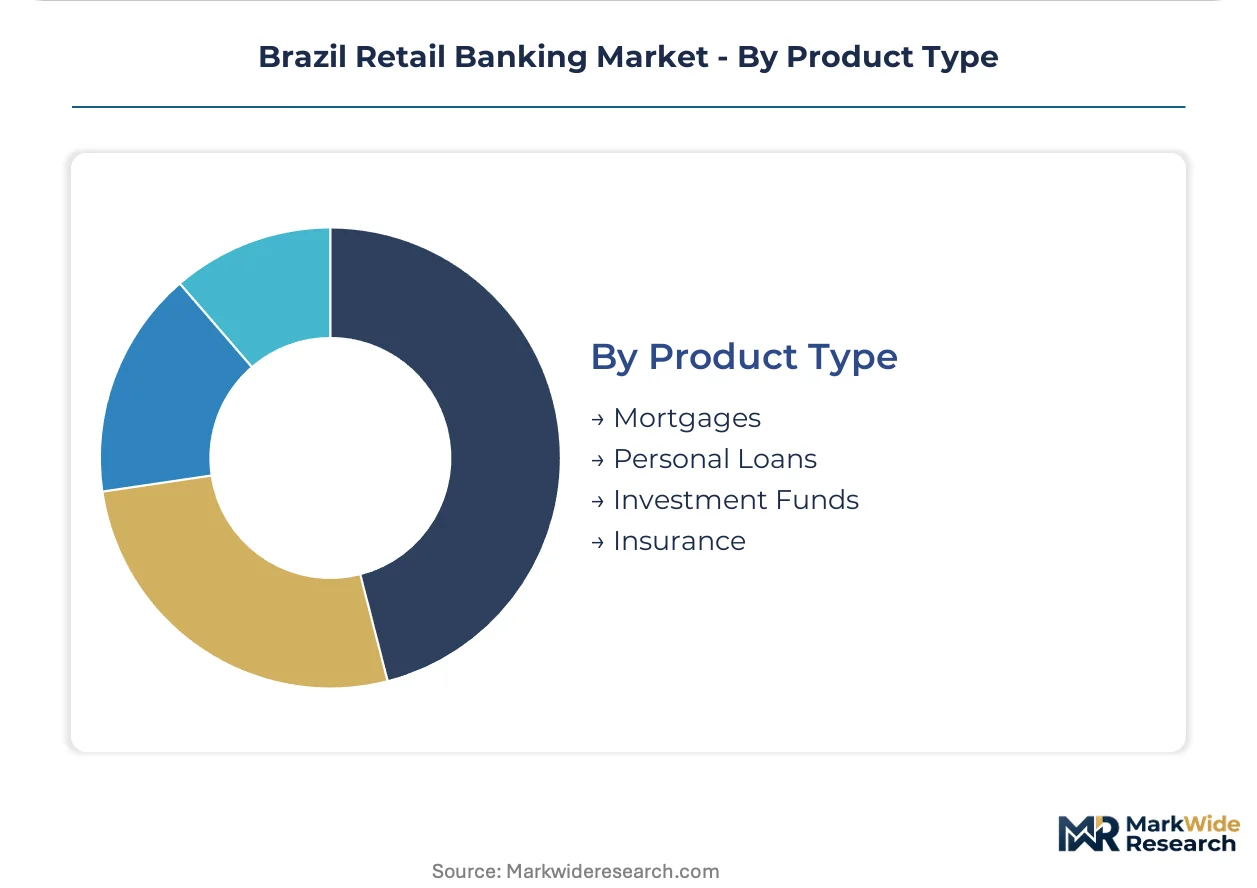
Product Type:
Balance sheet deployment and fee generation characteristics determine strategic priority within diversified product portfolios.
- Mortgages:Long-tenure real estate financing locks in spread income across interest rate cycles. São Paulo state property markets concentrate origination volume and collateral valuation expertise.
- Personal Loans:Unsecured consumer credit exhibits the highest loss rates and shortest origination cycles. Open Finance data sharing enables fintech competitors to price risk without proprietary deposit histories.
- Investment Funds:Asset management fees provide non-interest income diversification against credit cycle volatility. Central Bank of Brazil regulatory frameworks govern fund structures and distribution compensation.
- Insurance:Bancassurance distribution leverages branch and digital channels for property and life product placement. ANVISA oversight intersects with health-linked financial product design.
Mortgages retains the largest balance sheet allocation while Personal Loans demonstrates the most rapid origination technology transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's retail banking flows concentrate in the Southeast corridor, where São Paulo state exports financial services innovation to interior markets. The Central Bank of Brazil's regulatory harmonization enables product standardization across state boundaries while preserving regional credit risk differentiation.
São Paulo
São Paulo state hosts the densest fintech-bank competition intensity in Latin America. The Central Bank of Brazil's Open Finance mandates force data interoperability among institutions headquartered in the metropolitan region. The São Paulo city financial district anchors cloud-native core banking development teams that serve national deployment pipelines.
Rio de Janeiro
Rio de Janeiro state concentrates wealth management advisory relationships and family office density above national averages. ANVISA oversight intersects with health-linked financial product distribution through private banking channels. The Rio metropolitan corridor sustains branch-digital hybrid models for complex mortgage origination.
Minas Gerais
Minas Gerais exhibits accelerating small business digital credit demand across Belo Horizonte commercial corridors. The National Monetary Council's reserve requirements constrain regional lending capacity during agricultural commodity price cycles. The state's interior municipalities retain relevance for Banco do Brasil's government-backed lending program distribution.
Rio Grande do Sul
Rio Grande do Sul maintains distinct cooperative banking traditions alongside national branch network penetration. The Central Bank of Brazil's Pix instant payment infrastructure reduces transaction friction for Porto Alegre metropolitan merchants. Regional agricultural credit concentration creates seasonal liquidity management complexity for local institutions.
Bahia
Bahia represents underpenetrated territory for mobile-first banking distribution models relative to Southeast benchmarks. The National Monetary Council's capital adequacy frameworks apply uniform standards despite lower branch density per capita in the Northeast. Salvador metropolitan commercial activity drives working capital demand that outpaces traditional collateral-based product velocity.
Brazil Retail Banking Market Competitive Environment
On the supply side, the industry is bifurcated between legacy institution scale and fintech velocity. Five institutions control the majority of deposit market share through decades of branch network accumulation. Strategic archetypes separate into cloud-native digital attackers, hybrid branch-digital incumbents, and state-backed universal banks. Dominant competitive moves include API-based partnership ecosystems and legacy core system modernization programs.
Among Brazil-based institutions, Itaú Unibanco, Nubank, and Banco do Brasil occupy distinct competitive positions. Itaú Unibanco exemplifies the hybrid archetype through proprietary technology stack deployment at national scale. Nubank anchors the digital-native tier through mobile-first credit origination infrastructure. Banco do Brasil represents state-backed universal banking through expansive physical network coverage and government program participation.
| Leading Market Players |
|---|
| Caixa Econômica Federal |
| Nubank |
| Itaú Unibanco |
| Banco Votorantim |
| Banco Inter |
| Banco do Brasil |
| Santander Brasil |
| Banco Pan |
| Banco Bradesco |
| Others |
Value Chain & Pricing Dynamics
Centralized credit bureau concentration as a single-point-of-failure risk determines both pricing tier spreads and supply chain shape across Brazil retail banking. Serasa Experian and Boa Vista SCPC dominance forces institutions to compete on origination speed rather than proprietary scoring data, compressing margins in mass-market segments while premium advisory services command spreads.
Pricing Analysis
Legacy-to-cloud technology-generation pricing gaps separate incumbent banks from digital-native competitors across product origination economics. Three-tier pricing structure across premium relationship-managed, standard digital-first, and economy basic-access levels reflects divergent cost-to-serve models. Price differentiation hinges on API integration depth and real-time decisioning capability. Cost compression in economy tiers is intensifying because Pix-enabled fintechs eliminate branch infrastructure overhead. Small businesses in São Paulo commercial corridors exhibit highest price sensitivity, while wealth management clients in Rio de Janeiro show least elasticity to advisory fee structures.
Supply Chain Analysis
Upstream feedstock for Brazil retail banking draws from United States cloud infrastructure providers, Indian technology services firms, and domestic data center operators. Core dependencies include Kubernetes container orchestration platforms, mainframe modernization tools, and credit bureau data feeds. Single-source vulnerability concentrates in São Paulo and Rio de Janeiro metro areas where cloud architecture talent pools anchor. Distribution runs through API-based Banking-as-a-Service partnerships reaching micro-merchants in Northeast and North region underpenetrated territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil retail banking operates as a substitution defense against embedded finance convergence, where non-bank platforms threaten to disintermediate traditional deposit and credit relationships. Incumbents must navigate fintech-ERP integration momentum that consolidates small business financial services into single-platform providers.
For Market Incumbents: Entrench proprietary analytics layers atop Open Finance mandated data sharing to sustain differentiation. Accelerate legacy core system modernization programs to match fintech origination velocity. Defend against Nubank-style mobile-first attackers by embedding working capital products at agricultural commodity trader point-of-sale through API partnerships.
For New Entrants and Emerging Players: Pursue Northeast and North region mobile-first distribution white space where branch density per capita lags Southeast benchmarks. Target Amazonas and Pará states for thin-file customer underwriting using consent-based transaction history sharing. Establish go-to-market presence through Pix-integrated receivables financing for micro-merchants before incumbents deploy cloud-native architectures.
For Investors and Strategic Acquirers: Cloud-native mid-tier banks with hybrid mainframe migration capabilities represent the most defensible acquisition archetype against pure-digital competition. Long-term viability hinges on institutions that capture mobile-first customer acquisition economics while retaining mortgage origination branch infrastructure for complex advisory relationships. Watch Central Bank of Brazil digital currency pilot expansion as inflection indicator for competitive moat compression between licensed fintechs and universal banks.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Migration | API-first architectures slash product development cycles from months to weeks for mobile-first acquisition. |
| Open Finance Data Monetization | Consent-based transaction sharing enables personalized credit offers against Serasa Experian scoring dominance. |
| Embedded Finance Convergence | Banking-as-a-Service APIs integrate deposit products into retail ERP systems at agricultural commodity sale points. |
| Northeast Region Distribution Buildout | Mobile-first models bypass physical infrastructure gaps in Amazonas and Pará underpenetrated territories. |
| Generative AI Credit Decisioning | Large language models parse unstructured borrower documents that traditional scoring algorithms ignore. |
Study Parameters
The analysis maps deposit-taking, credit extension, payment facilitation, and wealth management sub-sectors, each validated through chief technology officers at incumbent banks, digital product heads at licensed fintechs, Central Bank of Brazil regulatory affairs specialists, and agricultural commodity trader treasury managers. Secondary validation draws from Central Bank of Brazil Open Finance regulatory filings, ANVISA data protection standards, National Monetary Council reserve requirement circulars, and Pix transaction infrastructure disclosures. Bottom-up product origination velocity estimates triangulate against top-down deposit market share concentration metrics.
Assumption sets hold Pix instant payment infrastructure penetration and Open Finance API mandate timelines as fixed conditions, while varying small business digital credit adoption rates and cloud migration investment cycles across the projection horizon. Segmentation dimensions modeled include customer type, service type, delivery model, and product type alongside regional fintech-bank competition intensity. CAGRs derive from reconciling historical deposit growth patterns with forward-looking mobile banking adoption curves, incorporating National Monetary Council capital buffer constraints and Serasa Experian credit registry expansion trajectories as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native repositioning by legacy institutions or accelerated Central Bank of Brazil digital currency deployment would shift outcomes beyond modeled ranges. Cross-checking against Central Bank of Brazil financial stability reports and fintech licensing disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Italy Data Analytics in Banking Market
Banking
Germany Neobanking Market
Banking
Australia Neobanking Market
Banking
Europe Data Analytics in Banking Market
Banking
Performance Bank Guarantee Market
Banking
Canada Data Analytics in Banking Market
Banking
North America Bank Kiosk Market
Banking
Banking Credit Analytics Market
Banking
Middle-East and Africa Banking-As-A-Service Market
Banking
Cloud-Based Core Banking Market
Banking
Russia Data Analytics in Banking Market
Banking
Predictive Analytics in Banking Market
Banking
Open Banking Market
Banking
Credit Intermediation Market
Banking
Bank Guarantee Market
Banking
Bank Management Software Market