
 Automated Teller Machine (ATM) Market | 2026-2036
Automated Teller Machine (ATM) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Teller Machine (ATM) Market Analysis
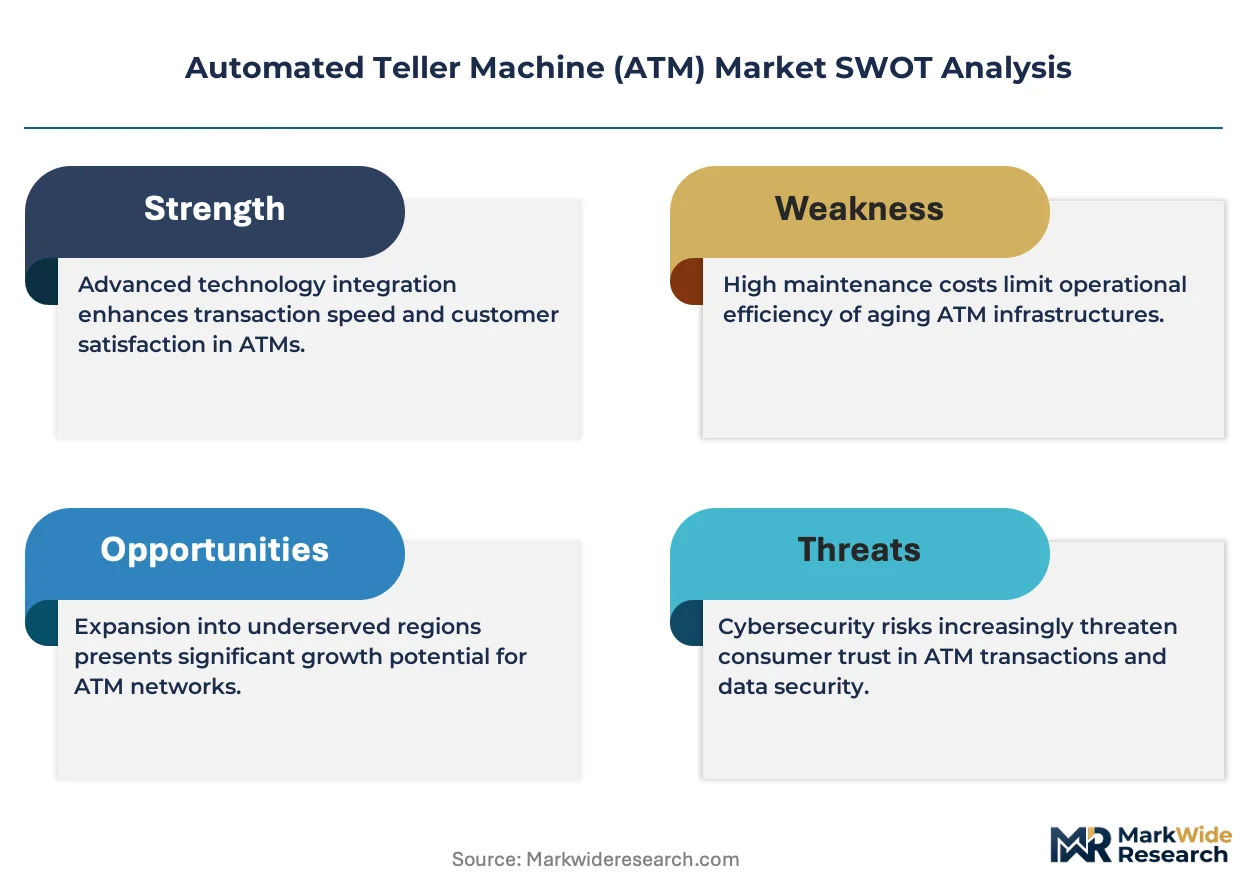
PCI DSS certification is consolidating the vendor landscape as smaller OEMs absorb compliance costs. Diebold Nixdorf leverages its integrated software-hardware stack to dominate managed services contracts. NCR Atleos sustains North American branch transformation momentum through ATM-as-a-service models. GRG Banking Equipment anchors Asia-Pacific supply chains with manufacturing scale in Guangdong province.
An automated teller machine is a self-service electromechanical terminal executing cash dispensing, deposit acceptance, and account queries through encrypted card reader modules and cash recycling mechanisms. Banking ATMs retain the largest installed base, though smart ATMs with integrated video conferencing and CRM connectivity capture the fastest replacement cycle. Biometric ATMs face regulatory fragmentation across fingerprint, iris, and palm-vein standards, complicating cross-border deployment for manufacturers.
The US Federal Reserve's cash access policies and the EU's PSD2 open-banking framework shape ATM network economics differently across jurisdictions. India's RBI mandates white-label ATM quotas for underserved postal codes, while Brazil's Banco Central requires traceability standards for cash logistics providers. Stakeholders must weigh cash-infrastructure commitments against digital-payment infrastructure investments as central banks diverge on physical currency strategy.
Market Dynamics
ATM fleet modernization is compressing replacement cycles as biometric authentication modules and cash-recycling mechanisms displace legacy dispensers in high-traffic installations.
Growth Catalysts
- India's RBI white-label mandates:Quotas for underserved postal codes force deployment of off-site ATM networks by non-bank operators, expanding hardware procurement beyond traditional banking channels.
- EMV chip compliance deadlines:European and North American mandates for Europay-Mastercard-Visa standards compel fleet-wide upgrades of card reader modules across aging installed bases.
- Financial inclusion programs:Brazil's northeastern states deploy solar-powered off-grid terminals to unbanked municipalities, creating concentrated demand for ruggedized outdoor ATM enclosures.
Market Restraints
- Semiconductor supply concentration:Encryption chip fabrication concentrates in Taiwan and South Korea, exposing ATM OEMs to geopolitical supply disruptions and extended lead times for card reader modules.
- Cash logistics cost inflation:Armored transport and vault cash management expenses rise with fuel and labor costs, squeezing operator margins and depressing hardware refresh budgets.
- Mobile wallet substitution:Real-time payment platforms and QR-code systems displace low-value cash withdrawals, eroding transaction volume at convenience-location ATMs.
Strategic Opportunities
- Video-enabled smart ATMs:Integrated telepresence and CRM connectivity allow banks to consolidate branch footprints while preserving high-touch advisory services through remote teller interfaces.
- Rural cooperative banking:India's regional cooperative banks lack digital infrastructure, creating first-mover advantage for OEMs offering bundled hardware-software-service packages with localized maintenance networks.
- Biometric standard harmonization:Proactive engagement with India's UIDAI and Brazil's Banco Central on fingerprint and palm-vein protocols positions vendors for cross-border deployment scalability.
Industry Challenges
- PCI DSS certification timelines:Payment Card Industry Data Security Standard recertification cycles extend to 18-24 months for complex multi-vendor integrations, delaying product launches and freezing R&D roadmaps.
- Legacy core banking integration:ATM management software must interface with decades-old host systems using proprietary protocols, requiring expensive middleware development for each financial institution deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Teller Machine (ATM) Market |
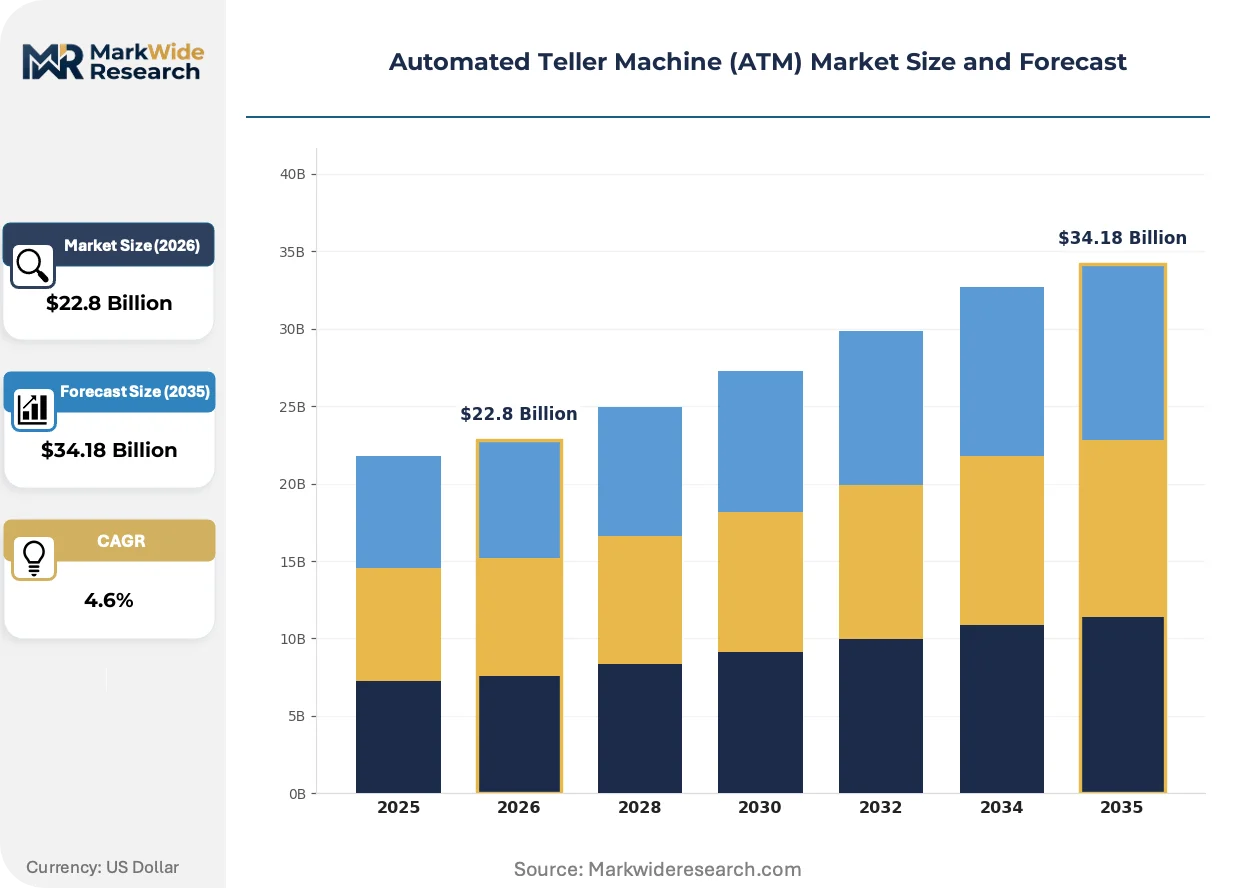
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Banking ATMs, Kiosk ATMs, Off-site ATMs, Mini ATMs Service Type: Transaction Services, Maintenance Services, Cash Management Services, Compliance Services Customer Type: Retail Customers, Corporate Clients, Financial Institutions, Government Agencies Technology: Standard ATMs, Biometric ATMs, Contactless ATMs, Smart ATMs |
| Companies Covered | Diebold Nixdorf, NCR Atleos, GRG Banking Equipment, Fujitsu, Hitachi-Omron Terminal Solutions, Nautilus Hyosung, OKI Electric Industry, Triton Systems of Delaware, Euronet Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Teller Machine (ATM) Market Emerging Trajectories
Hardware-software convergence is redefining ATM value propositions as cash-recycling mechanisms and cloud-native management platforms displace single-function dispensers. Equipment vendors now compete on total cost of ownership metrics spanning installation through end-of-life decommissioning.
Cash-recycling technology is overtaking traditional cash-in-cash-out configurations in branch transformation projects. Large retail banks in Germany and Japan deploy dual-denomination recyclers to reduce cash replenishment frequency from daily to weekly cycles. This compression of logistics intensity is enabling branch staff redeployment from cash handling to customer advisory roles.
The EU's PSD2 open-banking framework is mandating API-accessible account interfaces that ATM networks must integrate. European operators retrofit existing fleets with software stacks supporting real-time balance aggregation and payment initiation services. This regulatory pressure is accelerating obsolescence of standalone terminals lacking middleware connectivity to core banking platforms.
ATM-as-a-service contracting is displacing capital purchase models among mid-tier financial institutions. Brazilian and Indian regional banks favor per-transaction pricing with bundled maintenance and software updates, transferring obsolescence risk to OEMs. This shift is visible most acutely in markets where central bank liquidity requirements restrict large upfront capital allocations for infrastructure.
Automated Teller Machine (ATM) Market Segmentation
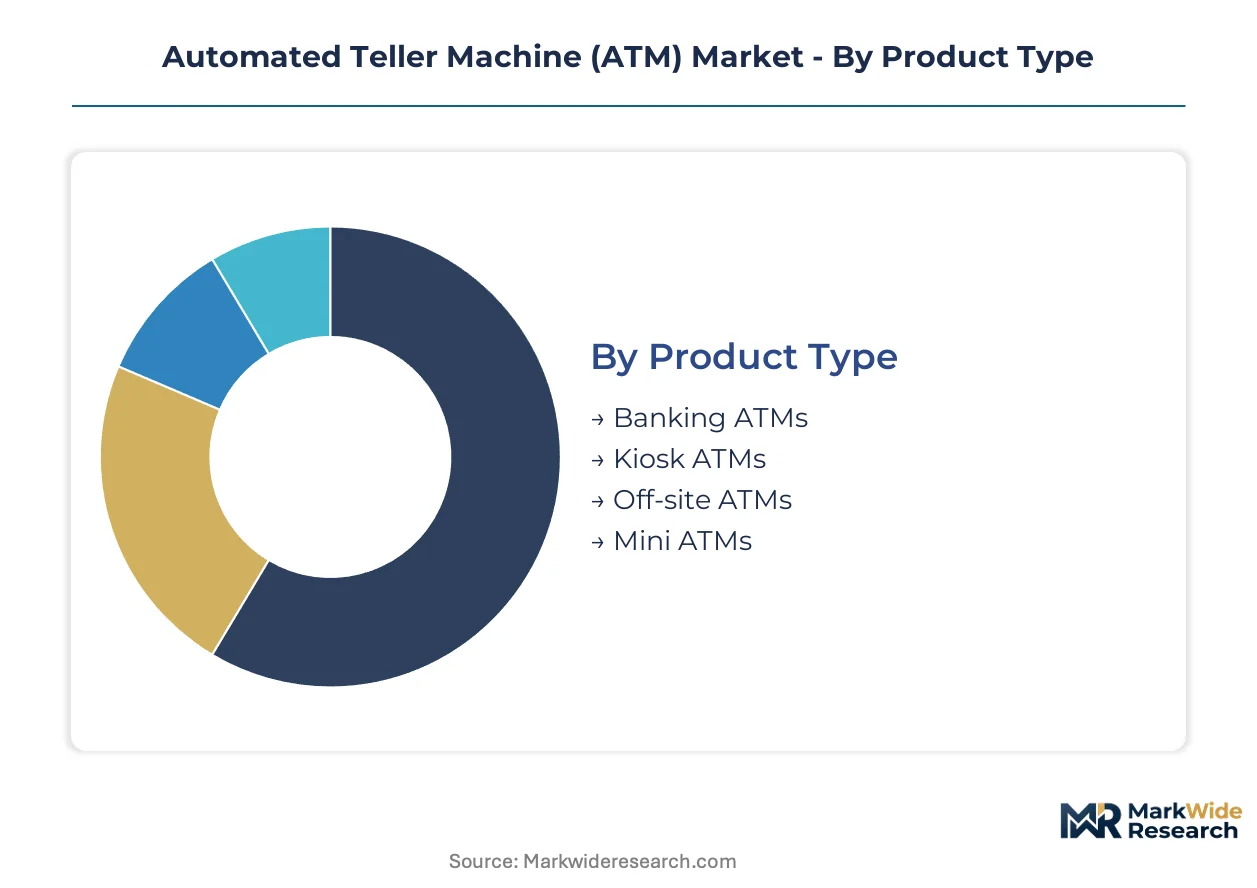
ATM market segmentation reveals how hardware configurations, service bundles, and authentication technologies map to distinct deployment economics. Understanding these divisions clarifies why rural cooperative banks in India and off-grid operators in Brazil's northeastern states source fundamentally different equipment than urban branch transformation projects in Germany or Japan.
Product Type:
Integration depth varies sharply across product categories, with standalone units dominating low-traffic rural deployments while embedded multi-function terminals anchor urban branch consolidation.
- Banking ATMs:Full-service terminals with cash recycling, deposit automation, and video conferencing modules. Demand concentrates in Germany and Japan where large retail banks compress branch footprints and redeploy staff from cash handling to advisory roles under dual-denomination recycler configurations.
- Off-site ATMs:Solar-powered ruggedized enclosures deployed in unbanked municipalities without permanent bank presence. Brazil's Banco Central financial inclusion programs drive concentrated procurement in northeastern states where armored transport infrastructure remains sparse.
- Kiosk ATMs:Limited-function terminals focused on balance inquiry and statement printing without cash handling capabilities.
- Mini ATMs:Compact wall-mounted or countertop units for space-constrained retail locations.
Banking ATMs lead volumes today; off-site ATMs are gaining share fastest.
Service Type:
Service bundling intensity tracks customer sophistication, with per-transaction pricing models displacing capital purchases among liquidity-constrained regional banks.
- Transaction Services:Core cash dispensing, deposit acceptance, and account query processing with encrypted card reader modules. India's RBI white-label mandates for underserved postal codes expand procurement beyond traditional banking channels to non-bank operators managing off-site networks.
- Cash Management Services:Vault cash optimization, armored transport coordination, and replenishment scheduling. Fuel and labor cost inflation squeezes operator margins and depresses hardware refresh budgets across European and North American fleets.
- Maintenance Services:Preventive and corrective field support for electromechanical components.
- Compliance Services:PCI DSS recertification support and EMV chip upgrade project management.
Transaction services anchor revenue today; cash management services are climbing the fastest as logistics costs escalate.
Customer Type:
Customer sophistication determines whether procurement favors capital expenditure models or ATM-as-a-service contracts with bundled software updates.
- Financial Institutions:Large retail banks with decades-old core banking systems requiring expensive middleware development for proprietary protocol integration. These customers dominate managed services contracts where integrated software-hardware stacks transfer obsolescence risk to OEMs.
- Retail Customers:Individual cardholders accessing cash through convenience-location networks. Mobile wallet substitution via real-time payment platforms and QR-code systems erodes transaction volume at these low-value withdrawal points.
- Corporate Clients:Businesses deploying on-premise terminals for employee payroll distribution.
- Government Agencies:Social benefit disbursement programs requiring biometric authentication for fraud prevention.
Financial institutions dominate installed base today; government agencies are expanding most quickly through inclusion mandates.
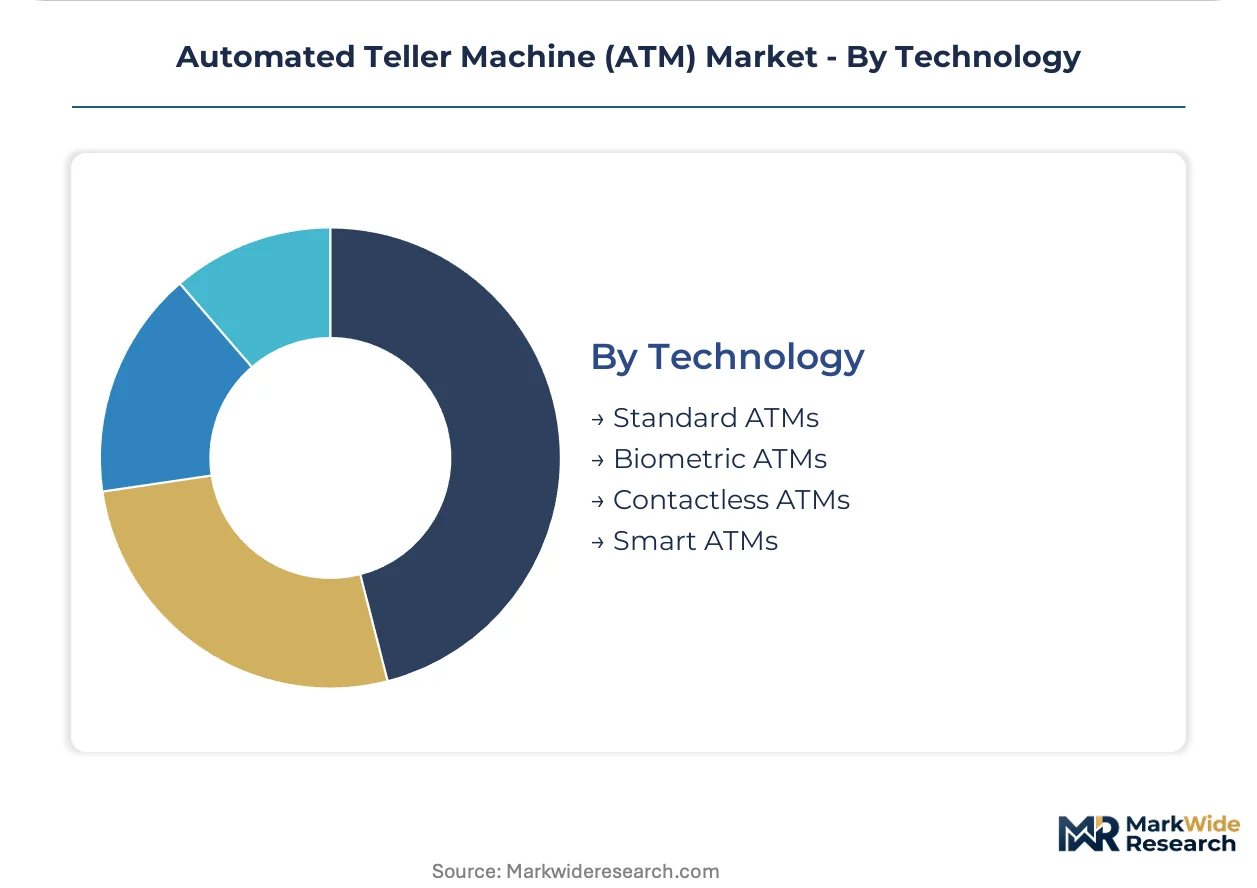
Technology:
Technology tiering reflects authentication complexity, with biometric and contactless modules commanding premium positioning against standard dispensers facing replacement pressure.
- Smart ATMs:Cloud-native platforms with integrated CRM connectivity, telepresence, and API-accessible interfaces mandated by the EU's PSD2 open-banking framework. European operators retrofit existing fleets to support real-time balance aggregation and payment initiation services.
- Biometric ATMs:Fingerprint, iris, and palm-vein authentication modules facing regulatory fragmentation across India's UIDAI and Brazil's Banco Central protocols. Proactive vendor engagement with these regulators positions equipment for cross-border deployment scalability.
- Contactless ATMs:Near-field communication and QR-code interfaces for cardless transaction initiation.
- Standard ATMs:Legacy EMV chip and magnetic stripe configurations facing fleet-wide upgrade mandates.
Standard ATMs retain largest installed base today; smart ATMs are capturing the fastest replacement cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Germany, India, and Japan anchor ATM hardware development and software integration capabilities across three continents.
United States
The Federal Reserve's cash access policies sustain ATM network economics while EMV chip compliance deadlines force fleet-wide upgrades of aging card reader modules. NCR Atleos dominates managed services contracts through ATM-as-a-service models. Deployment concentrates in Texas and Florida where regional banks favor per-transaction pricing over capital purchases.
Germany
Large retail banks deploy dual-denomination cash recyclers to compress branch footprints and redeploy staff from cash handling to advisory roles. The EU's PSD2 open-banking framework mandates API-accessible account interfaces that ATM networks must integrate. Manufacturing and R&D clusters concentrate in Bavaria and Baden-Württemberg where precision engineering capabilities support recycler mechanism production.
India
RBI white-label mandates for underserved postal codes expand hardware procurement beyond traditional banking channels to non-bank operators. Regional cooperative banks in Maharashtra and Gujarat lack digital infrastructure, creating demand for bundled hardware-software-service packages with localized maintenance networks. Manufacturing scale concentrates in Tamil Nadu and Karnataka where component supply chains support rural deployment logistics.
Brazil
Banco Central financial inclusion programs drive concentrated procurement of solar-powered off-grid terminals in northeastern states where armored transport infrastructure remains sparse. Traceability standards for cash logistics providers reshape operator procurement criteria. Equipment demand clusters in Bahia and Pernambuco where unbanked municipalities require ruggedized outdoor ATM enclosures.
Japan
Dual-denomination recyclers reduce cash replenishment frequency from daily to weekly cycles in branch transformation projects. METI industrial policy supports smart ATM development with integrated telepresence and CRM connectivity. Manufacturing and technical service capabilities concentrate in the Kanto and Kansai regions around Tokyo and Osaka.
Automated Teller Machine (ATM) Market Vendor Landscape
The competitive structure tilts toward integrated software-hardware stacks with managed services capabilities. Tier-one OEMs consolidate around full-stack offerings while mid-tier specialists compete on regional service density and compliance certification speed. Three archetypes dominate: integrated platform vendors, regional manufacturing specialists, and managed services operators. M&A activity concentrates on software capabilities and geographic service network expansion.
Among integrated platform vendors, Diebold Nixdorf and NCR Atleos exemplify the full-stack archetype with bundled hardware-software-service positioning. GRG Banking Equipment represents the regional manufacturing specialist model with concentrated Asia-Pacific supply chain presence. These three anchors illustrate how competitive positioning diverges between global platform plays and geography-specific manufacturing scale.
| Leading Market Players |
|---|
| Diebold Nixdorf |
| NCR Atleos |
| GRG Banking Equipment |
| Fujitsu |
| Hitachi-Omron Terminal Solutions |
| Nautilus Hyosung |
| OKI Electric Industry |
| Triton Systems of Delaware |
| Euronet Worldwide |
| Others |
Supply Flow & Price Mechanics
Copper and steel price indices cascade through ATM manufacturing tiers, compressing margins for standard dispenser configurations while insulating premium recyclers with software-anchored pricing power. Raw material volatility feeds into procurement decisions across India's regional cooperative banks and Brazil's off-grid operators, where total cost of ownership calculations favor bundled service contracts over capital purchases.
Pricing Analysis
Bundled hardware-software-service contracts separate from unbundled equipment sales across customer tiers. Three-tier pricing structure across premium smart ATMs, standard EMV-compliant units, and economy off-site enclosures tracks certification grade and after-sales density. Pricing pressure stems from semiconductor cost inflation and armored transport logistics, squeezing margins on transaction-only service tiers. Regional cooperative banks in India exhibit highest price sensitivity, while German retail banks prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Encryption chip fabrication rests on Taiwanese and South Korean foundries, tethering card reader module availability to geopolitical exposure points. Precision mechanical components for cash recyclers draw from German and Japanese engineering clusters, while ruggedized outdoor enclosures source from Guangdong province manufacturing scale. Single-source vulnerability concentrates in advanced semiconductor lithography. Distribution runs through OEM-direct channels for large financial institutions and regional distributor networks for cooperative banking procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's RBI liquidity restrictions and Brazil's Banco Central inclusion mandates create divergent procurement economics against German branch transformation budgets. Cost differentials between armored transport infrastructure density and solar-powered off-grid deployment reshape vendor prioritization.
For Market Incumbents: Anticipate mobile wallet substitution eroding convenience-location transaction volumes by accelerating video-enabled smart ATM deployments that preserve advisory revenue streams. Consolidate software-hardware integration depth to defend against ATM-as-a-service margin compression. Prioritize PCI DSS certification velocity as a competitive moat against mid-tier specialists. For New Entrants and Emerging Players: Launch via ATM-as-a-service contracts targeting India's white-label quota operators lacking captive maintenance networks. White-space concentrates in biometric standard harmonization across India's UIDAI and Brazil's Banco Central protocols. Rural cooperative banking bundles offer the most penetrable entry vector against entrenched OEM relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where software capabilities determine managed services contract win rates against hardware-only vendors. Long-term viability hinges on cloud-native platform ownership spanning the analysis window. Acquisition targets cluster around middleware specialists bridging legacy core banking protocols. The signal to watch is central bank digital currency pilot programs that may reshape cash infrastructure commitment levels.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Certification | UIDAI and Banco Central protocol alignment unlocks cross-border deployment scalability for equipment vendors. |
| Cash Recycler Mechanism Production | German and Japanese precision engineering capabilities anchor dual-denomination configurations for branch transformation. |
| ATM-as-a-Service Platform Launch | Per-transaction pricing transfers obsolescence risk to OEMs while capturing liquidity-constrained regional bank demand. |
| Solar-Powered Off-Grid Deployment | Brazil's northeastern financial inclusion programs create concentrated procurement for ruggedized outdoor enclosures. |
| Cloud-Native Management Integration | EU PSD2 API mandates accelerate retrofit demand for middleware-connected terminal fleets. |
Methodological Framework
Bottom-up financial institution deployment modeling reconciled against top-down OEM production tracking forms the analytical core. Primary interviews with ATM fleet managers, cooperative bank procurement officers, cash logistics operators, and regulatory compliance leads combine with secondary validation from RBI circulars, Banco Central resolutions, EU PSD2 implementation reports, and PCI DSS certification databases. Triangulation across stakeholder perspectives and documentary sources constrains estimate variance.
Historical fleet replacement cycle analysis informs projection parameters across the modeling period. Segmentation dimensions include product type integration depth, service bundling intensity, customer sophistication tier, and authentication technology complexity. CAGRs derive from fitted trendlines adjusted for regulatory mandate timing and semiconductor supply constraints. Forecast inputs incorporate EMV compliance deadline schedules and central bank cash access policy divergences.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwan semiconductor fabrication and abrupt central bank digital currency adoption curves. Forecasts reflect documented assumptions about logistics cost trajectories and biometric standard harmonization timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Banking-As-A-Service (Baas) Platform Market
Banking
Internet of Things (IoT) in Banking Market
Banking
Japan Data Analytics in Banking Market
Banking
Machine Learning in Banking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Russia Data Analytics in Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
Singapore Neobanking Market
Banking
Letter of Credit Confirmation Market
Banking
Corporate Banking Market
Banking
Middle East and Africa Neobanking Market
Banking
Digital Banking Market
Banking
Banking Software Market
Banking
Blockchain in Banking Market
Banking
Germany Neobanking Market
Banking
Global Chatbot for Banking Market