
 Internet of Things (IoT) in Banking Market | 2026-2036
Internet of Things (IoT) in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things (IoT) in Banking Market Foresight
Project finance for cloud-native infrastructure is tilting competitive dynamics toward vendors with balance-sheet capacity to underwrite multi-year transformation contracts. IBM Corporation leverages its hybrid cloud platform to anchor large-scale IoT deployments across North American banking networks. Microsoft Corporation sustains momentum through Azure IoT integration with core banking systems, while SAP SE specializes in ERP-linked asset tracking for European financial institutions.
Internet of Things in banking encompasses networked sensor systems, edge devices, and analytics platforms that capture real-time data from ATMs, branches, vaults, and customer touchpoints to enable automated monitoring, predictive maintenance, and contextual service delivery. These systems typically operate through encrypted low-latency protocols connecting distributed endpoints to centralized or edge-based processing nodes. Fraud detection applications currently occupy the largest deployment share as behavioral biometrics and geospatial transaction validation mature. Cloud-based deployment architectures are expanding fastest among mid-tier retail banks seeking to avoid capital-intensive on-premises infrastructure.
The EU AI Act, GDPR, and US FFIEC guidance collectively shape product roadmaps by mandating explainable algorithms, data minimization, and audit-grade logging across connected banking infrastructure. BIS standards in India and China's SAMR cybersecurity rules add further compliance layers for vendors serving those jurisdictions. Stakeholders must monitor evolving cross-border data localization requirements as they evaluate regional deployment strategies and partnership structures.
Market Dynamics
Cloud-native deployment architectures are compressing capital requirements for mid-tier retail banks while EU AI Act compliance mandates are forcing sensor vendors to reengineer edge-device firmware for explainable logging and data minimization.
Growth Catalysts
- EU AI Act and GDPR:Privacy-preserving sensor architectures are gaining mandatory adoption across European banking networks as institutions face audit-grade accountability requirements for algorithmic decision-making.
- Behavioral biometrics:Fraud detection deployments are expanding fastest in the United States where geospatial transaction validation and device fingerprinting reduce card-not-present losses.
- Connected ATM fleets:Predictive maintenance algorithms are cutting downtime for cash dispensing networks through vibration sensors and thermal imaging on critical mechanical components.
Market Restraints
- Semiconductor supply concentration:Edge device production depends on concentrated foundry capacity in East Asia, exposing banking IoT vendors to geopolitical disruption and extended lead times for custom ASICs.
- Cross-border data localization:India's RBI and China's SAMR cybersecurity rules fragment cloud architectures, forcing redundant infrastructure deployment and inflating operational complexity.
- Legacy core banking integration:SOAP-based mainframe interfaces resist real-time API connectivity, requiring expensive middleware layers that erode cloud-native cost advantages.
Strategic Opportunities
- India's digital public infrastructure:The account aggregator framework and UPI rails create openings for IoT-enabled micro-ATM networks and branchless banking in underserved rural districts.
- Digital twin convergence:Physics-based simulation of vault HVAC and power systems combined with live sensor feeds enables scenario planning for physical security breaches.
- Outcome-based maintenance contracts:Equipment vendors are repositioning from hardware sales to uptime guarantees, capturing recurring revenue streams tied to ATM availability metrics.
Industry Challenges
- Embedded systems security expertise:Banking IoT vendors face acute shortages of firmware engineers capable of implementing post-quantum cryptography on resource-constrained sensor microcontrollers.
- Multi-jurisdiction certification timelines:Separate BIS, FCC, and CE marking processes for radio modules delay product launches by 8-14 months and fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things (IoT) in Banking Market |
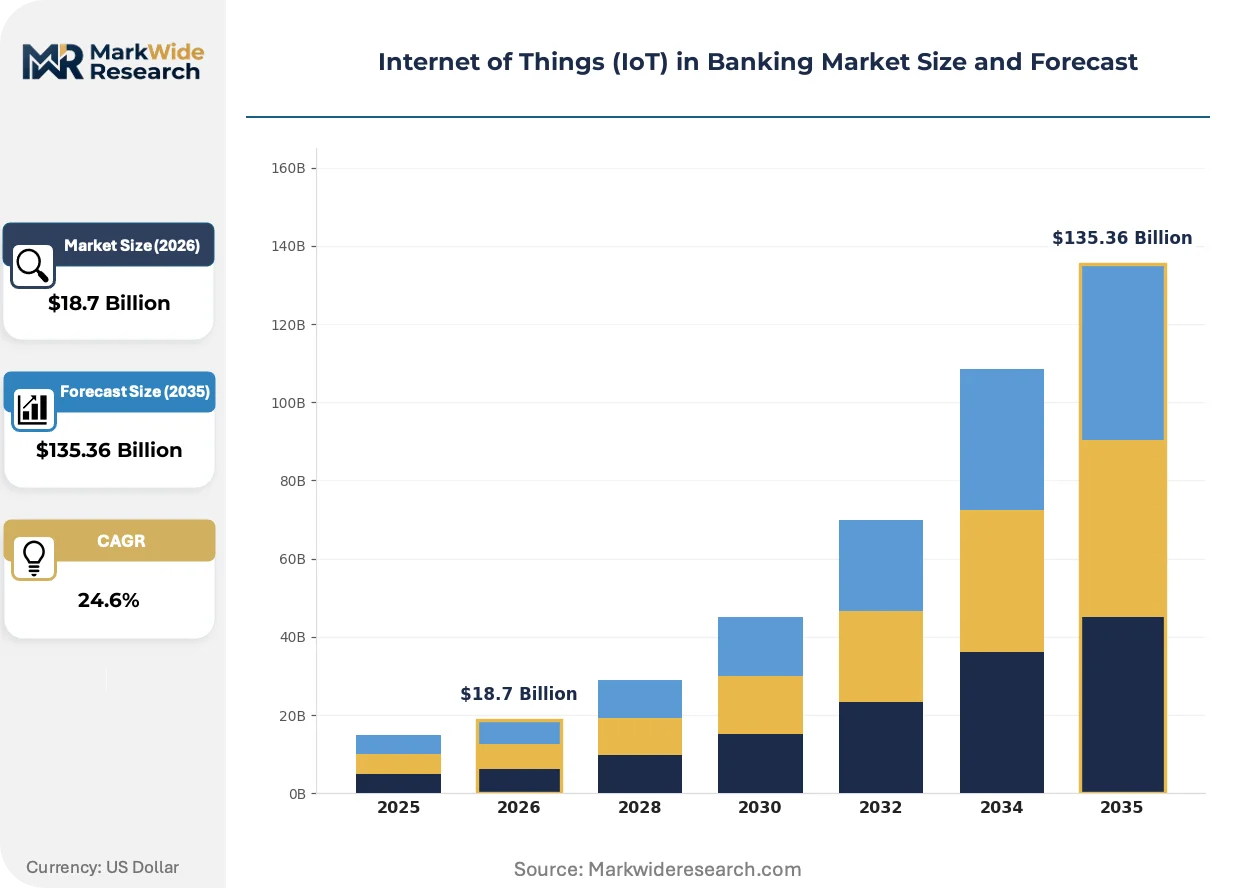
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Customer Experience Enhancement, Asset Tracking, Smart Branch Management Technology: Sensor Networks, Data Analytics, Cloud Computing, Machine Learning End User: Retail Banks, Investment Firms, Insurance Companies, Payment Processors Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, Oracle Corporation, Cisco Systems, Inc., Capgemini SE, Accenture PLC, Software AG, HCLTech Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things (IoT) in Banking Market Shifts & Advancements
Edge computing is displacing centralized cloud processing for latency-sensitive banking applications while explainable AI mandates are rewriting firmware development workflows across the vendor base.
Digital twin technology is virtualizing physical bank branch operations through real-time sensor feeds from HVAC, lighting, and occupancy systems. Mid-tier retail banks in Germany and the Netherlands are piloting these platforms to optimize energy consumption and staff scheduling. The technology is virtualizing capital planning decisions by enabling scenario simulation before physical renovation investments.
The EU AI Act's risk classification framework is mandating human oversight interfaces for high-risk biometric applications including behavioral analysis at ATMs. Vendors must now implement logging standards that trace algorithmic decisions to specific training data subsets. European deployment timelines are extending as engineering teams rearchitect edge devices for audit-grade transparency.
Subscription pricing for sensor-as-a-service is displacing perpetual license models among community banks with constrained IT capital budgets. Channel partners are bundling hardware, connectivity, and analytics into single monthly fees. This shift is most pronounced in the United States where regional banks face pressure to modernize branch networks without balance-sheet strain.
Internet of Things (IoT) in Banking Market Segmentation
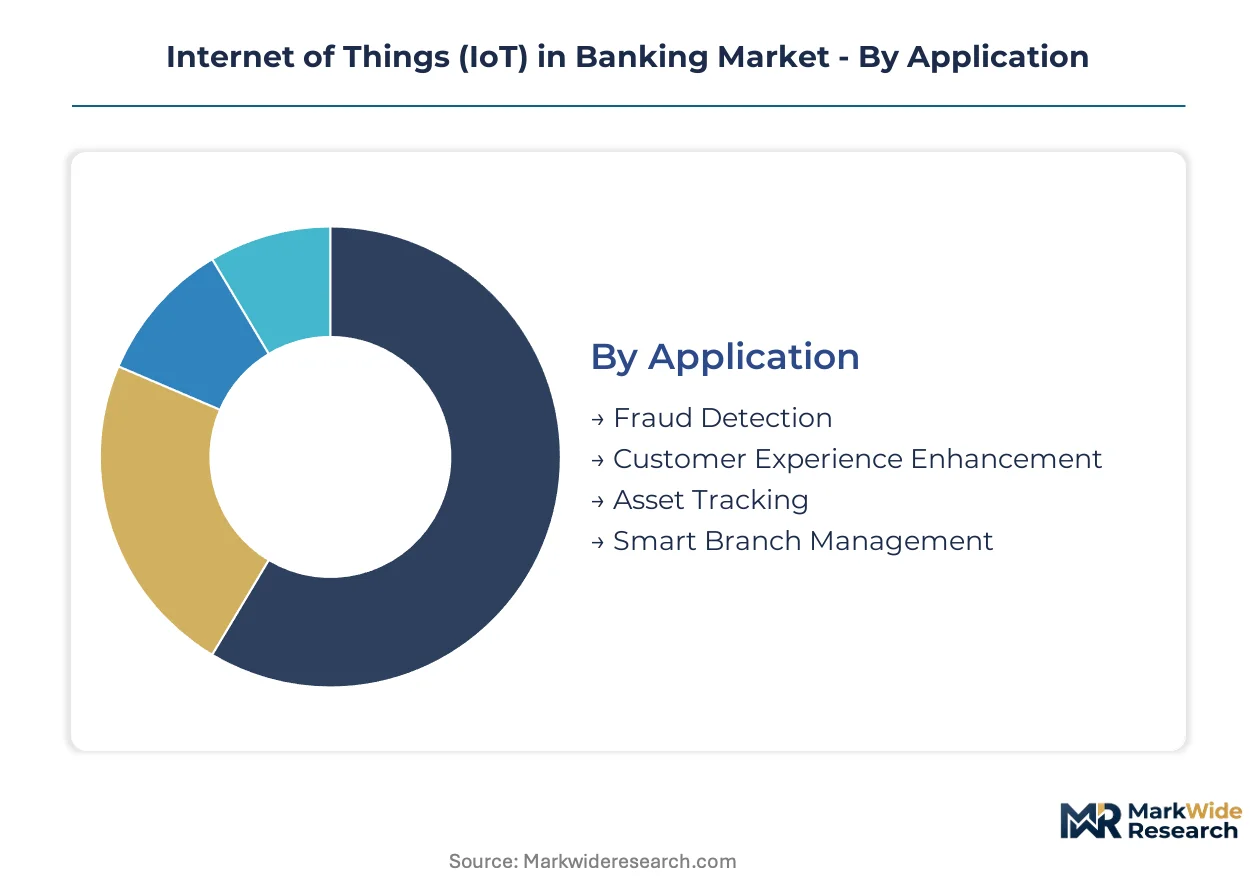
IoT banking deployments fragment across four critical dimensions that determine integration complexity, compliance exposure, and capital intensity. Each segmentation axis reveals distinct procurement patterns and vendor specialization zones that shape competitive positioning.
Application:
Mature fraud detection applications coexist with emerging smart branch deployments as institutions balance risk mitigation against customer-facing innovation.
- Fraud Detection:Behavioral biometrics and geospatial transaction validation systems process real-time device fingerprints and location signals. United States retail banks concentrate demand here as card-not-present losses drive authentication upgrades. EU AI Act explainability mandates are forcing algorithmic logging retrofits that extend deployment timelines.
- Customer Experience Enhancement:Proximity sensors and personalized digital signage adjust branch environments based on identified customer profiles. German and Dutch mid-tier banks pilot these systems to optimize staff scheduling and reduce physical queue friction.
- Asset Tracking:RFID and GPS-enabled monitoring covers high-value cash-in-transit vehicles and ATM cassettes.
- Smart Branch Management:Integrated HVAC, lighting, and occupancy sensors enable predictive facility maintenance and energy optimization.
Fraud Detection handles the majority of throughput; Smart Branch Management is the fastest mover on share.
Technology:
Cost tier stratification separates capital-intensive sensor hardware from recurring analytics subscriptions that dominate mid-tier bank procurement.
- Sensor Networks:Encrypted low-latency protocols connect distributed ATM, vault, and branch endpoints to processing nodes. Vibration and thermal sensors on cash dispensing mechanisms enable predictive maintenance that cuts downtime for United States ATM fleets.
- Data Analytics:Real-time stream processing platforms aggregate telemetry for operational dashboards and anomaly detection. European deployments emphasize GDPR-compliant data minimization architectures that filter sensitive biometric signals at the edge.
- Cloud Computing:Elastic infrastructure reduces capital requirements for community banks avoiding on-premises data center investments.
- Machine Learning:Edge-deployed inference models enable sub-second fraud scoring without round-trip latency to centralized servers.
Sensor Networks anchor the installed base; Machine Learning is expanding most quickly as edge silicon efficiency improves.
End User:
Customer type divergence separates regulated deposit-taking institutions from non-bank payment intermediaries with lighter compliance burdens.
- Retail Banks:Branch network operators deploy comprehensive IoT stacks spanning fraud prevention, asset monitoring, and facility management. United States regional banks concentrate investment in connected ATM fleets and smart vault systems.
- Investment Firms:Trading floor environmental sensors and secure document tracking dominate procurement. Data center cooling optimization and physical access logging drive sensor density in algorithmic trading facilities.
- Insurance Companies:Telematics-linked banking products and claims verification sensors create hybrid IoT-financial service offerings.
- Payment Processors:Merchant terminal monitoring and transaction routing optimization require lightweight, high-velocity telemetry architectures.
Retail Banks command the largest deployment volumes; Payment Processors are gaining share fastest through API-native integration models.
Deployment:
Geography-agnostic architecture preferences are fragmenting under India's RBI and China's SAMR data localization mandates that force jurisdiction-specific infrastructure.
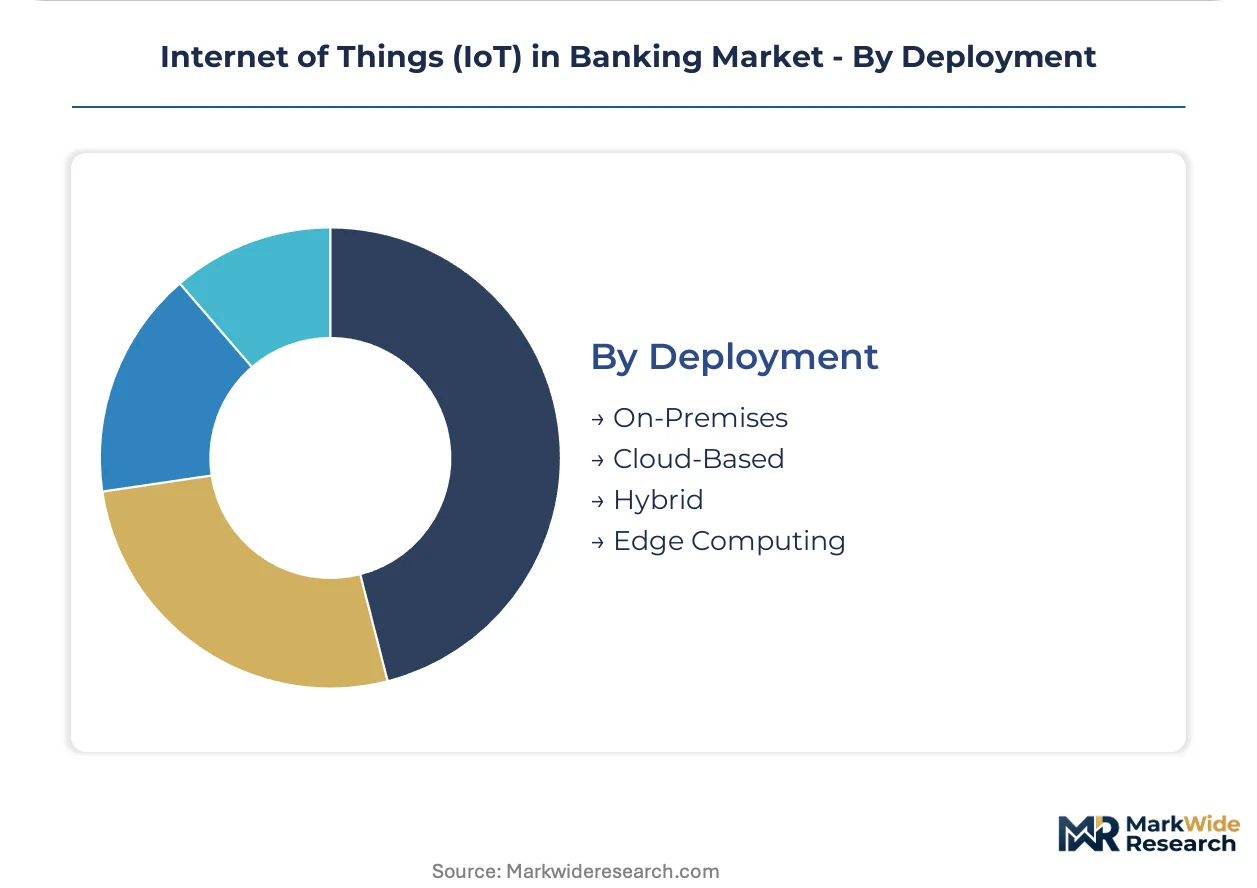
- On-Premises:Dedicated hardware installations in bank-owned data centers satisfy stringent data residency requirements. Large United States money center banks maintain these architectures for core transaction processing and vault monitoring systems.
- Cloud-Based:Multi-tenant SaaS platforms compress capital requirements and accelerate time-to-value for mid-tier institutions. European adoption faces GDPR Article 44 transfer mechanism complexity that extends legal review cycles.
- Hybrid:Sensitive biometric processing at the edge combines with cloud analytics for non-critical operational data. This architecture satisfies EU AI Act risk classification requirements while preserving elastic compute economics.
- Edge Computing:Micro-data centers at branch locations enable sub-10ms latency for real-time fraud decisions and autonomous ATM operations.
Cloud-Based deployments lead on new contract volume; Edge Computing is climbing the fastest as latency requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Banking IoT technology flows predominantly from the United States and Germany toward import-dependent markets in India and Brazil, creating trade imbalances that shape vendor expansion strategies and local partnership requirements.
United States
Major retail banks deploy connected ATM fleets and smart vault monitoring systems at scale, with JPMorgan Chase and Bank of America driving predictive maintenance adoption. FFIEC guidance on cybersecurity risk management mandates audit-grade logging for all connected banking infrastructure. New York City and Charlotte anchor the largest implementation clusters, where fintech vendors co-locate engineering teams alongside money center headquarters.
Germany
Mid-tier retail banks in Frankfurt and Munich pilot digital twin platforms for branch energy optimization and staff scheduling efficiency. GDPR Article 44 transfer mechanism complexity extends legal review cycles for cloud-based IoT deployments, favoring hybrid architectures. The Eindhoven-Düsseldorf corridor concentrates sensor hardware engineering talent for privacy-preserving edge device development.
India
RBI data localization rules fragment cloud architectures, forcing redundant infrastructure deployment for foreign banking IoT vendors. The account aggregator framework and UPI rails enable IoT-enabled micro-ATM networks in Maharashtra and Karnataka's underserved rural districts. Mumbai and Bangalore host the primary integration centers where domestic system integrators adapt foreign platforms to SAMR-influenced compliance requirements.
China
SAMR cybersecurity rules and dual carbon goals accelerate domestic substitution for foreign banking IoT components, with state-owned banks prioritizing indigenous sensor networks. The Yangtze River Delta, particularly Shanghai and Hangzhou, concentrates smart branch pilot programs combining facial recognition with queue management systems. Local vendors capture share through MIIT-certified edge devices that satisfy data sovereignty mandates.
United Kingdom
London-based investment firms deploy trading floor environmental sensors and secure document tracking for algorithmic trading facilities. FCA operational resilience requirements mandate sub-24-hour recovery capabilities for critical IoT-linked banking infrastructure. The London-Southeast cluster dominates procurement volume, though Edinburgh maintains specialized expertise in legacy core banking integration for Scottish financial institutions.
Internet of Things (IoT) in Banking Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: cloud hyperscalers with balance-sheet capacity for multi-year transformation contracts, ERP-anchored systems integrators with pre-existing banking relationships, and specialized edge-device vendors with firmware security expertise. Strategic archetypes include hybrid cloud platform providers, core banking integration specialists, and sensor-as-a-service subscription vendors. Competitive dynamics center on M&A activity targeting middleware capabilities and strategic partnerships with semiconductor foundries to secure ASIC supply.
Among technology conglomerates with banking sector presence, IBM Corporation exemplifies the hybrid cloud archetype through its North American network deployments. Microsoft Corporation occupies a comparable position on the hyperscaler tier, while SAP SE represents the ERP-anchored integration specialist serving European financial institutions. These three entities collectively illustrate the competitive tension between infrastructure ownership and application-layer specialization that defines vendor positioning.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| Cisco Systems, Inc. |
| Capgemini SE |
| Accenture PLC |
| Software AG |
| HCLTech Ltd. |
| Others |
Supply & Pricing Matrix
Taipei-Hsinchu corridor foundry capacity constraints are compressing margins for edge-device vendors serving North American banking networks, while subscription pricing models insulate SaaS providers from silicon cost volatility. This supply-demand asymmetry concentrates pricing power with cloud hyperscalers capable of underwriting multi-year transformation contracts.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium, standard, and economy levels in banking IoT deployments. Premium tiers bundle edge-device firmware with audit-grade logging for EU AI Act compliance, while standard offerings target mid-tier retail banks with cloud-native sensor-as-a-service subscriptions. Cost compression in economy tiers stems from community bank procurement consolidation through channel partners. Payment processors exhibit the highest price sensitivity due to thin transaction margins, whereas money center banks prioritize compliance certification over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for banking IoT vendors assembling edge devices. Taiwan, South Korea, and Japan concentrate advanced semiconductor foundry capacity that feeds custom ASIC production for encrypted sensor modules. Custom silicon, thermal imaging components, and low-latency radio modules constitute critical input dependencies. Single-source vulnerability in 7nm and 5nm fabrication nodes threatens production continuity. Distribution runs through systems integrators with pre-existing core banking relationships, bypassing direct vendor-to-bank procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Banking IoT investment cycles track capital expenditure recovery patterns at major retail institutions, with cloud migration budgets expanding as rate environments stabilize and multi-year transformation projects regain board approval.
For Market Incumbents: Build regulatory certification moats by accelerating BIS, FCC, and CE marking pre-approvals for next-generation radio modules before multi-jurisdiction timelines extend further. Deepen firmware security expertise through targeted acquisition of post-quantum cryptography specialists, as embedded systems engineering scarcity intensifies competition for talent. Secure foundry allocation agreements now to defend against geopolitical disruption of Taiwan-based capacity. For New Entrants and Emerging Players: India's account aggregator framework and UPI-enabled rural micro-ATM networks represent the most penetrable entry point for foreign vendors facing data localization barriers elsewhere. Community banks in the United States Midwest and Southeast present adjacent white-space demand for subscription-priced sensor-as-a-service bundles without upfront capital requirements. Partner with domestic system integrators in Mumbai and Bangalore to navigate RBI compliance complexity rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized edge-device vendors with firmware security expertise over horizontal cloud platforms approaching saturation. Long-term viability hinges on post-quantum cryptography implementation capabilities as regulatory mandates harden. Acquisition targets should demonstrate proven SAMR, RBI, or BIS certification pathways. Monitor semiconductor foundry utilization rates as the primary inflection signal for hardware margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Integration | EU AI Act audit-grade requirements are mandating firmware reengineering for algorithmic explainability. |
| Multi-Jurisdiction Certification Pre-Approval | BIS, FCC, and CE marking parallel tracks compress 8-14 month product launch delays. |
| Domestic System Integrator Partnership | RBI data localization rules force redundant infrastructure deployment without local channel expertise. |
| Foundry Allocation Securement | Taiwan semiconductor concentration exposes banking IoT vendors to geopolitical supply disruption. |
| Sensor-as-a-Service Subscription Pivot | Community bank IT capital constraints favor monthly fee structures over perpetual license models. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and regulatory guidance documents preceded structured interviews with bank CTOs, IoT platform engineers, channel integration specialists, and procurement officers at regional financial institutions. Primary fieldwork validated secondary estimates of deployment timelines and compliance cost structures. Bottom-up sensor shipment aggregation and top-down banking IT spending analysis were triangulated against vendor-reported contract values.
Forecast assumptions held cloud adoption elasticity and regulatory implementation schedules fixed while varying semiconductor supply scenarios and cross-border data localization enforcement intensity. Segmentation dimensions modeled include application type, deployment architecture, end-user institution category, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical banking technology adoption patterns, with edge computing penetration and fraud detection algorithm maturation serving as key industry-specific demand drivers.
Practitioners should monitor foundry utilization rates, EU AI Act enforcement precedents, and RBI data localization rulings for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Cloud-Based Core Banking Market
Banking
Global Neo and Challenger Bank Market
Banking
Banking Software Market
Banking
South Korea Data Analytics in Banking Market
Banking
Cloud Billing in Banking Market
Banking
Predictive Analytics in Banking Market
Banking
Retail Banking Market
Banking
Europe Data Analytics in Banking Market
Banking
Brazil Retail Banking Market
Banking
Australia Data Analytics in Banking Market
Banking
Global Certificate of Deposit Market
Banking
Cloud Computing Banking Market
Banking
Canada Data Analytics in Banking Market
Banking
Video Banking Service Market
Banking
Core Banking Solutions Market
Banking
Retail Banking IT Spending Market