
 China Bank Kiosk Market | 2026-2036
China Bank Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
China Bank Kiosk Market Insights
MIIT's GB standards for financial self-service terminals is consolidating the competitive field around manufacturers with certified testing infrastructure. GRG Banking sustains vertical integration across metal fabrication and cash-handling modules. Shenzhen Lean Kiosk System leverages coastal manufacturing clusters to control component costs. Inspur Technologies anchors server-to-terminal system integration for state-owned banking clients.
China bank kiosks are self-service terminals engineered to withstand operating temperatures of 0°C to 45°C with MTBF ratings exceeding 50,000 hours, designed primarily to automate cash transactions, account inquiries, and card issuance without teller intervention. Interactive kiosks dominate volume deployment across state-owned commercial banks, while biometric-enabled units capture expanding margin pools as facial-recognition authentication displaces card-only access. Cloud computing integration is accelerating fastest among payment solutions providers seeking centralized device management across distributed networks.
SAMR enforces product safety certification under GB 4943.1 for electrical equipment, while the PBOC mandates PCI compliance for all transaction terminals, and MEE tracks e-waste disposal obligations for retired kiosk fleets. These overlapping requirements favor domestic vendors with established regulatory relationships and localized compliance teams. Stakeholders must monitor evolving biometric data governance rules from the CAC as facial-recognition kiosks proliferate in rural branch networks.
Market Dynamics
MIIT's GB standards for financial self-service terminals are consolidating procurement around certified manufacturers, compressing the vendor base while elevating compliance costs for tier-two and tier-three city deployments.
Growth Catalysts
- Rural banking digitization:County-level commercial banks in Jiangsu and Zhejiang provinces are replacing staffed counters with interactive terminals to serve dispersed agricultural depositors.
- PCI compliance mandates:PBOC transaction security requirements are accelerating terminal refresh cycles at state-owned banks, creating replacement demand across legacy installed bases.
- Facial-recognition authentication:Biometric-enabled units are capturing margin expansion as card-only access models face obsolescence in high-traffic urban branches.
Market Restraints
- Component supply concentration:Cash-handling modules and industrial-grade touch panels rely heavily on Shenzhen and Dongguan manufacturing clusters, creating geographic vulnerability to regional logistics disruptions.
- E-waste compliance burden:MEE tracking obligations for retired kiosk fleets impose end-of-life management costs that inflate total cost of ownership for rural banks with limited reverse logistics infrastructure.
- Biometric data governance friction:CAC evolving rules on facial-recognition data storage and cross-border transfer create uncertainty for cloud-integrated terminal architectures.
Strategic Opportunities
- Centralized device management:Cloud computing integration is expanding into payment solutions providers seeking unified control over distributed networks of terminals across provincial boundaries.
- Server-to-terminal system integration:State-owned banking clients are demanding bundled hardware-software procurement, favoring vendors with captive server production capabilities.
- Tier-two city expansion:Commercial banks in provincial capitals like Chengdu, Wuhan, and Xi'an are accelerating self-service footprint growth ahead of saturation in Beijing and Shanghai.
Industry Challenges
- Certification timeline compression:SAMR product safety testing under GB 4943.1 and NMPA cybersecurity validation create multi-month approval bottlenecks that delay revenue recognition.
- Legacy core banking integration:Terminal deployment requires customized middleware development to interface with decades-old state-owned bank transaction processing systems, extending implementation cycles.
- Field service technician scarcity:Rural branch networks lack trained personnel for hardware maintenance and cash cassette replenishment, forcing vendors to build captive service organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Bank Kiosk Market |
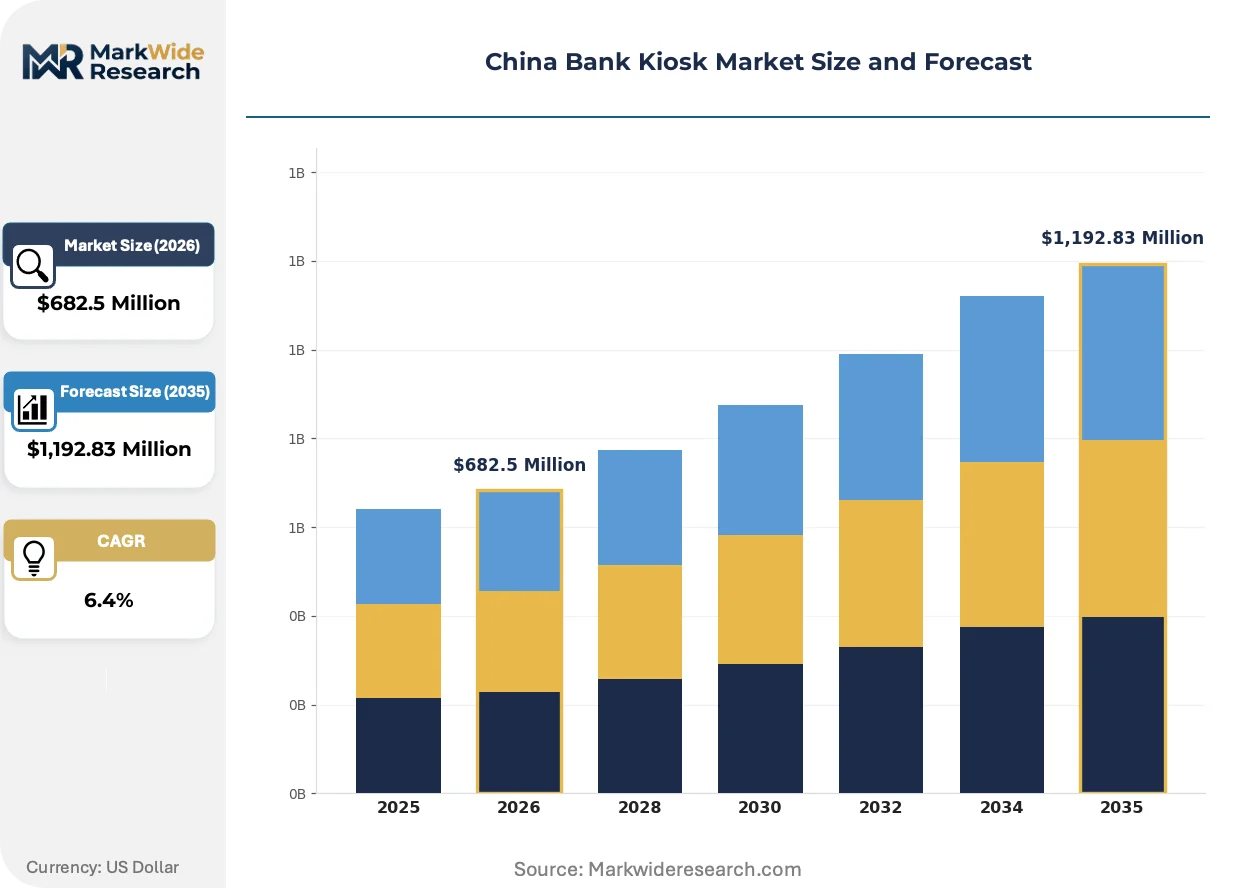
| Market Size in 2026 | $682.5 Million |
| Market Size in 2035 | $1,192.83 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Kiosks, Information Kiosks, Transaction Kiosks, Service Kiosks End User: Commercial Banks, Credit Unions, Investment Banks, Payment Solutions Technology: Touchscreen, RFID, Biometric, Cloud Computing Service Type: Installation, Maintenance, Support, Customization |
| Companies Covered | Shenzhen Lean Kiosk System Co. Ltd, KINGLEADER Technology Company, GRG Banking Co., Ltd, Shenzhen Hunghui IT Co. Ltd, Guangzhou LiQi Intelligent Technology Co. Ltd, Inspur Technologies Co., Ltd, SZZT Electronics Co. LTD, OKI Electric Industry Co., Ltd., Shenzhen Yi of Computer Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Bank Kiosk Market Trends and Innovations
Cloud-native terminal architectures and biometric authentication modules are restructuring how Chinese banks provision self-service infrastructure, shifting value capture toward software-integrated hardware vendors.
Biometric-enabled kiosks are expanding into state-owned commercial banks as facial-recognition authentication displaces card-only access in high-security transaction environments. Tier-one city branches are piloting these units at pace, with procurement committees prioritizing vendors with CAC-certified data handling protocols. The technology is expanding into margin pools previously captured by traditional interactive terminals, compressing pricing power for card-reader-only manufacturers.
MIIT's updated GB standards for financial self-service terminals are tightening electromagnetic compatibility and environmental durability requirements. Manufacturers without certified testing infrastructure face exclusion from state-owned bank procurement shortlists. Domestic vendors with established MIIT laboratory relationships are securing preferred supplier status, while smaller competitors absorb compliance consulting costs or exit the certified segment.
Rural branch managers are consolidating vendor relationships around full-service contracts bundling hardware, software, and field maintenance. This procurement pattern displaces transactional equipment purchasing, favoring suppliers with captive service networks in county-level markets. The shift is most visible in agricultural banking cooperatives across central and western provinces, where technical staffing constraints make bundled service economics compelling.
China Bank Kiosk Market Segmentation
Bank kiosk procurement in China stratifies sharply across certification tiers, with MIIT GB standards and PBOC PCI mandates filtering which manufacturers qualify for state-owned bank tenders. Segment boundaries reflect these regulatory fault lines more than pure technology differentiation.
Product Type:
MIIT GB 4943.1 electrical safety certification applies universally, yet transaction-intensive segments face additional PBOC PCI compliance burdens that elevate vendor qualification thresholds.
- Interactive Kiosks:Full-function terminals integrating cash handling, card issuance, and account inquiry modules. Demand concentrates in Jiangsu and Zhejiang county-level commercial banks replacing staffed rural counters, driven by agricultural banking digitization mandates.
- Transaction Kiosks:Purpose-built units for deposit, withdrawal, and transfer operations with cash-handling modules rated for 0°C to 45°C operating environments. State-owned commercial banks in tier-two cities like Chengdu and Wu'an are accelerating deployment ahead of Beijing and Shanghai saturation.
- Information Kiosks:Non-transactional wayfinding and product display terminals with reduced certification overhead.
- Service Kiosks:Specialized units for card issuance, passbook printing, and statement generation with modular component architectures.
Leading the category by volume: Interactive Kiosks. Growing fastest: Transaction Kiosks.
End User:
Procurement economics diverge sharply between state-backed institutions with captive compliance teams and rural cooperatives dependent on vendor-managed certification pathways.
- Commercial Banks:State-owned and joint-stock institutions with centralized procurement committees demanding bundled hardware-software-server integration. PCI compliance mandates are accelerating terminal refresh cycles across legacy installed bases.
- Credit Unions:Agricultural cooperatives and rural banking networks across central and western provinces. E-waste tracking obligations under MEE rules inflate total cost of ownership where reverse logistics infrastructure remains limited.
- Investment Banks:Securities firms deploying information-dense terminals for client onboarding and risk disclosure.
- Payment Solutions:Third-party processors seeking cloud-integrated terminal architectures for centralized device management across provincial boundaries.
Dominant procurement volume: Commercial Banks. Steepest expansion trajectory: Payment Solutions.
Technology:
Hardware-software integration intensity determines margin capture, with biometric and cloud layers commanding premium positioning over commoditized touchscreen infrastructure.
- Biometric:Facial-recognition authentication modules displacing card-only access in high-security urban branches. CAC evolving data governance rules create uncertainty for cloud-integrated architectures handling cross-border transfer scenarios.
- Cloud Computing:Native terminal architectures enabling unified control over distributed networks. Payment solutions providers are expanding fastest into this segment as centralized device management becomes competitive necessity.
- Touchscreen:Industrial-grade panels sourced from Shenzhen and Dongguan manufacturing clusters.
- RFID:Contactless card reading modules for transit-integrated banking applications.
Highest margin capture: Biometric. Gaining share fastest: Cloud Computing.
Service Type:
Rural branch technical staffing constraints are consolidating procurement around full-service contracts that displace transactional equipment purchasing.
- Maintenance:Field service contracts covering hardware repair and cash cassette replenishment. County-level markets lack trained personnel, forcing vendors to build captive service organizations.
- Installation:Deployment services including legacy core banking middleware development for decades-old state-owned transaction processing systems.
- Support:Remote monitoring and software update services for cloud-integrated terminal fleets.
- Customization:Interface and workflow adaptation for cooperative banking requirements.
Fastest-growing contract value: Maintenance. Expanding most quickly: Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Jiangsu and Zhejiang provinces where rural banking digitization accelerates fastest, with tier-two cities in Sichuan and Hubei now expanding procurement beyond coastal saturation points.
Jiangsu Province
County-level commercial banks in southern Jiangsu are replacing staffed rural counters with interactive terminals to serve dispersed agricultural depositors. MIIT's GB standards for financial self-service terminals are consolidating procurement around certified manufacturers with established laboratory relationships. Suzhou and Nanjing manufacturing clusters host cash-handling module suppliers that dominate component sourcing for provincial deployments.
Zhejiang Province
Agricultural banking cooperatives across Hangzhou and Ningbo are driving terminal refresh cycles ahead of PBOC PCI compliance deadlines. SAMR enforces product safety certification under GB 4943.1 for all electrical equipment entering rural branch networks. Wenzhou-based fabricators are securing preferred supplier status through bundled hardware-software contracts that displace transactional purchasing.
Sichuan Province
Commercial banks in Chengdu are accelerating self-service footprint growth ahead of saturation in coastal metros. NMPA cybersecurity guidelines for financial terminals are tightening compliance requirements for biometric-enabled units handling facial-recognition data. The Chengdu-Chongqing economic circle is emerging as a western hub for cloud-integrated terminal deployment.
Hubei Province
Wuhan-based state-owned banks are expanding procurement of transaction kiosks rated for 0°C to 45°C operating environments. MEE tracking obligations for retired kiosk fleets impose end-of-life management costs that favor vendors with captive reverse logistics infrastructure. The Wuhan-Optics Valley corridor is attracting payment solutions providers seeking centralized device management capabilities.
Guangdong Province
Shenzhen and Dongguan manufacturing clusters anchor component supply for cash-handling modules and industrial-grade touch panels serving national demand. CAC evolving rules on facial-recognition data storage create uncertainty for cloud-integrated architectures handling cross-border transfer scenarios. Pearl River Delta vendors are leveraging coastal production density to control costs for tier-two city expansion campaigns.
China Bank Kiosk Market Competitive Landscape
Guangdong producers anchor one tier; inland specialists hold procurement relationships with state-owned banking clients. The vendor base stratifies sharply across MIIT certification tiers, with GB standards compliance filtering which manufacturers qualify for centralized tenders. Three archetypes dominate: coastal fabricators with captive component sourcing, systems integrators with server-to-terminal bundling capabilities, and full-service contractors building county-level maintenance networks. Competitive intensity is concentrating around strategic partnerships with cloud infrastructure providers and geographic expansion into western provinces.
Among Shenzhen-based fabricators, Shenzhen Lean Kiosk System Co. Ltd and Shenzhen Hunghui IT Co. Ltd occupy positions within the coastal manufacturing cluster tier. GRG Banking Co., Ltd exemplifies the vertically integrated archetype through its control over metal fabrication and cash-handling module production. Inspur Technologies Co., Ltd represents the systems integration specialist segment, anchoring server-to-terminal procurement relationships with state-owned banking clients. KINGLEADER Technology Company sits within the tier of vendors pursuing full-service contract models for rural cooperative banking networks.
| Leading Market Players |
|---|
| Shenzhen Lean Kiosk System Co. Ltd |
| KINGLEADER Technology Company |
| GRG Banking Co., Ltd |
| Shenzhen Hunghui IT Co. Ltd |
| Guangzhou LiQi Intelligent Technology Co. Ltd |
| Inspur Technologies Co., Ltd |
| SZZT Electronics Co. LTD |
| OKI Electric Industry Co., Ltd. |
| Shenzhen Yi of Computer Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
MEE e-waste tracking obligations for retired kiosk fleets gate qualified supply to vendors with captive reverse logistics infrastructure, while simultaneously propping premium-tier pricing for full-service contracts that bundle end-of-life compliance. County-level commercial banks absorb elevated total cost of ownership where technical staffing constraints make vendor-managed certification pathways economically compelling.
Pricing Analysis
Short lead-time premiums compress standard-tier margins while spot inventory from coastal fabricators trades at discount to contract-bound procurement. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified manufacturers with laboratory relationships from uncertified competitors. Price differentiation hinges on GB 4943.1 electrical safety certification tier and bundled field maintenance coverage. Cost compression in economy tiers intensifies because agricultural cooperatives prioritize capital expenditure minimization over performance specifications. Credit unions exhibit highest price sensitivity; state-owned commercial banks with centralized procurement committees demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from state-owned banking clients, while distributor-mediated pathways serve county-level cooperative networks. Component supply concentrates in Shenzhen and Dongguan manufacturing clusters for cash-handling modules and industrial-grade touch panels. Raw material dependencies include precision metal fabrication feedstock, industrial computing chipsets, and biometric sensor arrays. Single-source vulnerability runs through Shenzhen-based cash-handling module suppliers where regional logistics disruptions propagate nationwide. Distribution runs through provincial equipment wholesalers with MIIT certification brokerage capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified testing infrastructure scarcity constrains qualified vendor supply, propping pricing power for incumbent manufacturers with established MIIT laboratory relationships. Capacity bottlenecks at SAMR and NMPA approval facilities extend revenue recognition timelines.
For Market Incumbents: Acquire captive field service organizations in county-level markets to defend full-service contract positioning against emerging systems integrators. Deepen backward integration into cash-handling module production to offset component supply concentration risk. Prioritize CAC-certified data handling protocol investment as facial-recognition authentication displaces card-only access. For New Entrants and Emerging Players: Enter via cloud-native terminal architectures targeting payment solutions providers seeking centralized device management across provincial boundaries. White-space concentrates in tier-two cities like Chengdu and Wuhan where self-service footprint expansion accelerates ahead of coastal saturation. Agricultural banking cooperatives in central provinces present penetrable segments with limited incumbent maintenance coverage. For Investors and Strategic Acquirers: NMPA cybersecurity guideline publication for financial terminals is the leading indicator that regulatory compliance capabilities will consolidate procurement around certified vendors. Long-term viability favors vertically integrated manufacturers with server-to-terminal bundling capabilities and established state-owned banking relationships. Target acquisition archetype: coastal fabricators with MIIT laboratory access and county-level service networks. Monitor PBOC PCI compliance deadline announcements as inflection signals for replacement demand cyclicality.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Certification Investment | GB standards compliance secures state-owned bank procurement shortlist inclusion against uncertified rivals. |
| Cloud-Native Architecture Development | Native terminal integration enables payment solutions providers to unify distributed network control. |
| County-Level Service Network Buildout | Captive maintenance organizations address rural branch technical staffing constraints for agricultural cooperatives. |
| Biometric Module Integration | Facial-recognition authentication captures margin expansion as card-only access faces obsolescence. |
| Western Province Geographic Expansion | Chengdu-Chongqing economic circle deployment accesses accelerating tier-two city self-service growth. |
Research Methodology
Multi-period observation of MIIT certification issuance patterns, PBOC PCI compliance deadline announcements, and county-level terminal deployment rates anchored the trend analysis, supplemented by interviews with kiosk manufacturing executives, state-owned bank procurement committee members, agricultural cooperative branch managers, and payment solutions platform engineers. Secondary validation drew from SAMR product safety filings, NMPA cybersecurity guidelines, MEE e-waste tracking disclosures, and provincial banking digitization policy documents. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing.
Segment-weighting across product type, end user, technology, and service type dimensions structured the analytical framework across the projection horizon. Interactive kiosk and transaction kiosk volumes were modeled separately with divergent growth assumptions reflecting rural digitization versus tier-two urban expansion trajectories. Biometric-enabled and cloud-computing technology segments received distinct CAGR derivations based on regulatory adoption curves and infrastructure investment patterns. Forecast inputs incorporated PBOC compliance refresh cycle timing and CAC data governance rule evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended SAMR certification approval delays or abrupt CAC biometric data storage restrictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Europe Neobanking Market
Banking
Canada Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Japan Data Analytics in Banking Market
Banking
Europe Machine Learning in Banking Market
Banking
Global AI in Banking Market
Banking
Voice Banking Market
Banking
Europe Banking-As-A-Service Market
Banking
Global Certificate of Deposit Market
Banking
US Commercial Banking Market
Banking
Saudi Arabia Retail Banking Market
Banking
Corporate Banking Market
Banking
Smart Banking Solutions Market
Banking
Australia Data Analytics in Banking Market
Banking
South America Challenger Banks Market
Banking
Virtual Teller Machine (VTM) Market
Banking
Armenia Banking Market