
 Global Banking Systems Software Market | 2026-2036
Global Banking Systems Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Banking Systems Software Market Analysis
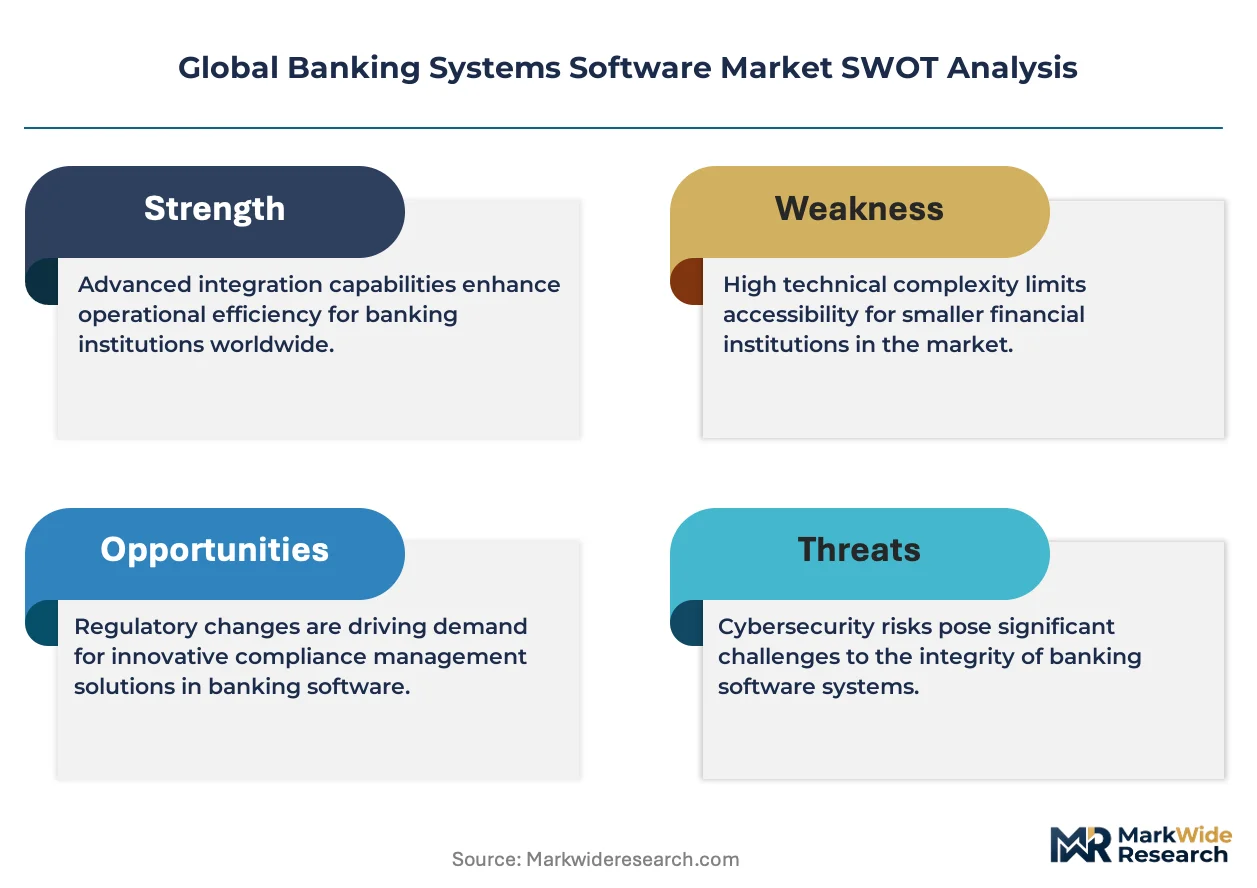
The divergence between premium enterprise suites and commodity cloud-native stacks is repositioning vendor economics across the sector. Fidelity National Information Services anchors its position through deep vertical integration with North American credit unions. Temenos specializes in modular core banking architectures that sustain margin pools in wealth management deployments. SAP SE leverages its ERP dominance to compete for integrated transaction management contracts at tier-one commercial banks.
Banking systems software encompasses the integrated application layers that process deposits, loans, payments, and regulatory reporting across financial institutions, typically architected on distributed databases with real-time transaction processing sub-100 millisecond latency requirements and API-first interoperability protocols. Core banking platforms retain the largest installed base but SaaS deployment models capture the fastest expansion as online banks and neobanks abandon on-premises infrastructure. Risk management functionality commands premium pricing due to Basel III and stress-testing automation requirements, while customer engagement modules face margin compression from low-code alternatives.
The European Banking Authority enforces open banking standards through PSD2 and PSD3 mandates that compel legacy vendors to expose payment initiation APIs, while the RBI in India mandates core banking solution adoption for urban cooperative banks to ensure financial inclusion traceability. The US OCC and FDIC scrutinize vendor concentration risk in cloud outsourcing agreements, pushing banks toward multi-provider hybrid architectures. Stakeholders must weigh regulatory interoperability requirements against the operational complexity of maintaining parallel compliance engines across jurisdictions.
Market Dynamics
Cloud-native core banking platforms are forcing incumbent vendors to abandon monolithic architectures as neobanks and digital lenders demand API-first infrastructure with sub-100 millisecond transaction latency. This technical transition compresses replacement cycles and fragments procurement authority between CIOs and chief digital officers.
Growth Catalysts
- PSD2 and PSD3 Mandates:European open banking regulations compel legacy institutions to expose payment initiation APIs, creating immediate demand for middleware and core system modernization across Germany, France, and the Netherlands.
- Financial Inclusion Pressure:India's RBI mandates core banking solution adoption for urban cooperative banks, accelerating replacement cycles in a market with over 1,500 eligible institutions.
- Real-Time Payment Rails:FedNow and equivalent instant settlement systems in Brazil and Thailand require banks to upgrade legacy batch-processing cores to 24/7 transaction engines.
Market Restraints
- Cloud Concentration Risk:US OCC and FDIC scrutiny of vendor concentration in cloud outsourcing agreements forces banks toward costly multi-provider hybrid architectures.
- Specialized Talent Scarcity:Shortage of engineers proficient in both COBOL legacy systems and Kubernetes containerization extends implementation timelines and inflates project costs.
- Data Sovereignty Friction:Cross-border data localization requirements in China, Russia, and Indonesia fragment cloud deployment strategies and duplicate compliance overhead.
Strategic Opportunities
- Embedded Finance White Space:Non-bank platforms in Southeast Asia—ride-hailing apps, e-commerce marketplaces, and telecom operators—require Banking-as-a-Service licensing infrastructure.
- Climate Risk Integration:EU CSRD and emerging stress-testing frameworks create demand for carbon accounting modules within existing risk management stacks.
- Generative AI Convergence:Large language models trained on regulatory filings and customer interaction data open automation pathways for compliance documentation and personalized product recommendations.
Industry Challenges
- Legacy Integration Complexity:Core banking migrations require parallel operation of old and new systems for 18-36 months, straining operational risk management and dual-run budgets.
- Certification Timeline Compression:Basel III finalization and regional implementation variations force vendors to maintain multiple compliance engine versions simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Banking Systems Software Market |
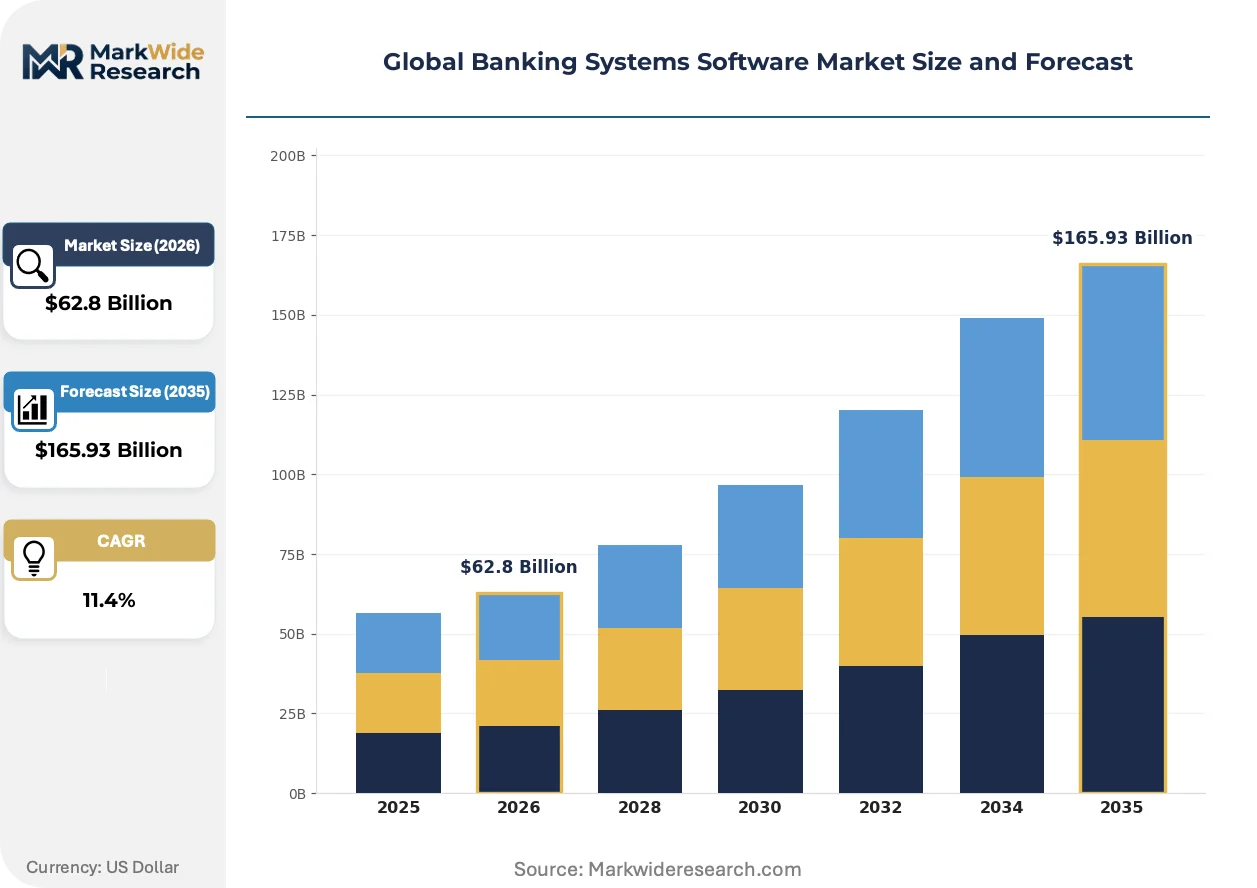
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $165.93 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Core Banking, Digital Banking, Risk Management, Wealth Management Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Commercial Banks, Investment Banks, Credit Unions, Online Banks Functionality: Transaction Management, Compliance Tracking, Reporting Tools, Customer Engagement |
| Companies Covered | Fidelity National Information Services Inc., SAP SE, Temenos AG, Mambu GmbH, Infosys Limited, Finastra International Ltd., Oracle Corporation, Jack Henry & Associates Inc., Fiserv Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Banking Systems Software Market Emerging Trajectories
Artificial intelligence and distributed ledger technologies are penetrating core banking infrastructure, but the dominant force is architectural—API-first platforms are unbundling vertically integrated software suites into composable, best-of-breed components.
Event-driven microservices architectures are converging with real-time payment networks to enable continuous transaction processing without batch windows. Tier-two banks in Brazil and Poland are adopting these patterns fastest, leapfrogging legacy mainframe dependencies. The structural consequence is compressing vendor switching costs and enabling multi-source procurement strategies that fragment incumbent market positions.
EU AI Act risk classifications for credit scoring and fraud detection algorithms impose documentation and human-in-the-loop requirements on automated decision systems. Vendors must now embed explainability modules and audit trails directly into machine learning pipelines. Wealth management and retail lending segments face the steepest compliance ramps, with German and Dutch regulators already enforcing draft provisions ahead of full implementation.
Subscription pricing for core banking modules is displacing perpetual license models as neobanks and digital lenders prioritize operational expenditure over capital deployment. Tier-one commercial banks in North America resist this shift, maintaining negotiated enterprise agreements, while mid-market institutions in Australia and the Nordics embrace consumption-based pricing. The geographic divergence reflects varying balance sheet flexibility and shareholder pressure for predictable technology spending.
Global Banking Systems Software Market Segmentation
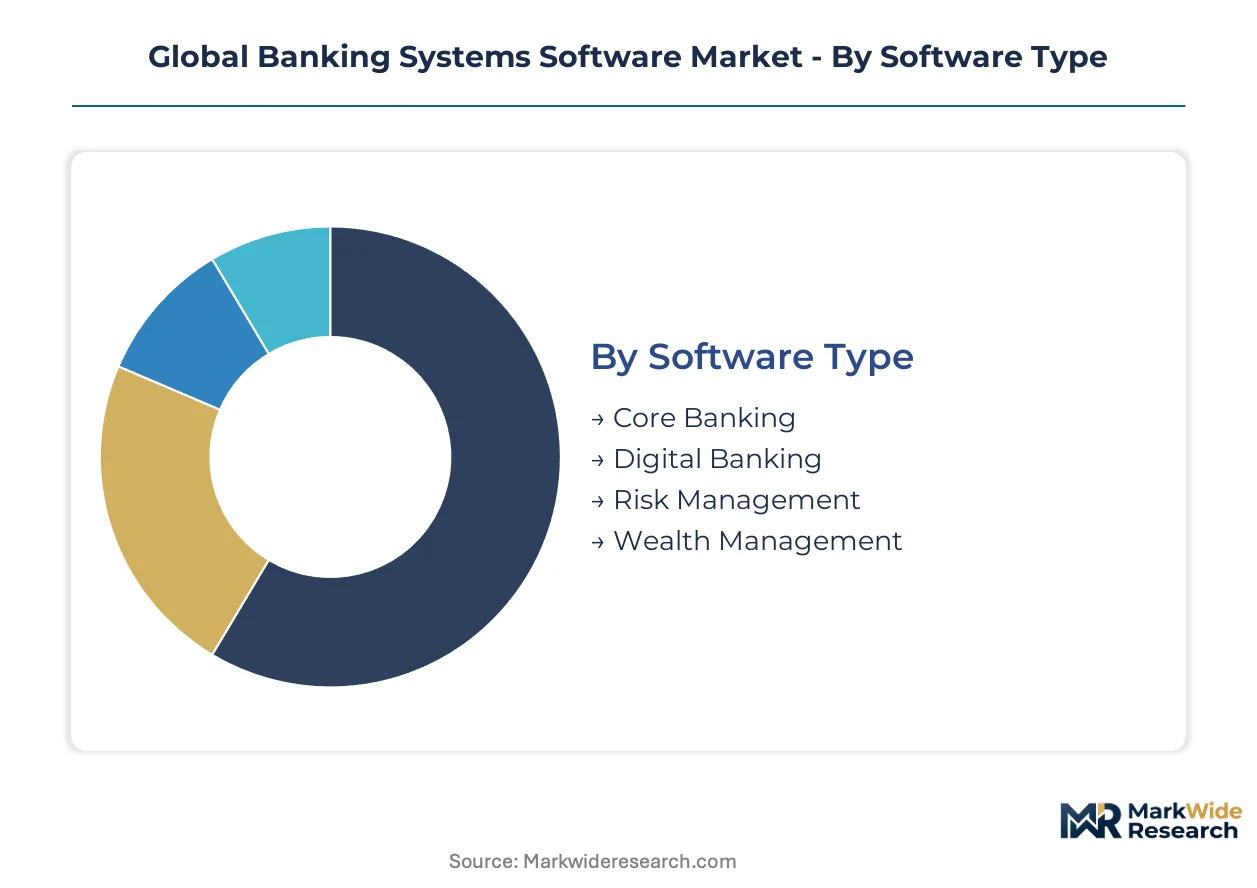
Banking systems software segments diverge sharply in their regulatory certification burdens, with core banking platforms requiring central bank approval in most jurisdictions while customer engagement modules face lighter oversight. Deployment models and end-user types further stratify procurement patterns, creating distinct margin pools across the value chain.
Software Type:
Certification intensity varies dramatically across software categories, with core banking platforms requiring RBI validation in India and ECB supervisory approval across the Eurozone, while wealth management modules face lighter SEC registration in the United States.
- Core Banking:Monolithic transaction processing engines handling deposits, loans, and general ledger operations with sub-100 millisecond latency requirements. Demand concentrates among urban cooperative banks in India where RBI mandates replacement of legacy systems, though COBOL-to-cloud migration timelines extend 18-36 months due to parallel operation requirements.
- Digital Banking:API-first customer-facing platforms enabling mobile and web channel services with microservices architectures. Neobanks in Brazil and Poland adopt these fastest, leapfrogging mainframe dependencies entirely as real-time payment rails like FedNow and Pix force 24/7 transaction engine upgrades.
- Risk Management:Basel III stress-testing and credit scoring modules with embedded explainability requirements under the EU AI Act.
- Wealth Management:Portfolio accounting and advisory platforms with modular deployment options for private banking divisions.
Leading the category by volume: Core Banking. Growing fastest: Digital Banking.
Deployment Model:
Cost tier stratification dominates procurement decisions, with tier-one commercial banks in North America maintaining capital-intensive on-premises infrastructure while mid-market institutions prioritize operational expenditure flexibility.
- On-Premises:Legacy mainframe and distributed server installations with full capital ownership and dedicated data center requirements. Tier-one commercial banks in the United States resist cloud migration due to OCC scrutiny of vendor concentration risk, maintaining negotiated enterprise agreements with perpetual license structures.
- Cloud-Based:Public cloud deployments on AWS, Azure, or GCP with consumption-based pricing and automatic scaling. Mid-market banks in Australia and the Nordics embrace this model fastest, driven by shareholder pressure for predictable technology spending and limited balance sheet flexibility for capital deployment.
- Hybrid:Split architectures retaining sensitive transaction processing on-premises while customer-facing applications migrate to cloud.
- SaaS:Fully managed subscription services with vendor-operated infrastructure and continuous feature updates.
Dominant by installed base: On-Premises. Expanding most quickly: Cloud-Based.
End User:
Customer type determines functionality requirements and pricing power, with investment banks demanding specialized trading integration while credit unions prioritize cost-efficient core modernization.
- Commercial Banks:Full-service institutions requiring integrated transaction management across retail, corporate, and treasury operations. These institutions in Germany and France drive demand for PSD2-compliant payment initiation APIs, forcing middleware upgrades to expose legacy core functions.
- Investment Banks:Capital markets specialists needing real-time risk calculation and regulatory reporting automation. Demand clusters in London and New York where Basel III finalization pressures stress-testing infrastructure replacement.
- Credit Unions:Member-owned cooperatives with constrained IT budgets seeking modular core replacements.
- Online Banks:Digital-native institutions built on cloud-native architectures without legacy technical debt.
Highest spend per seat: Investment Banks. Fastest new entity formation: Online Banks.
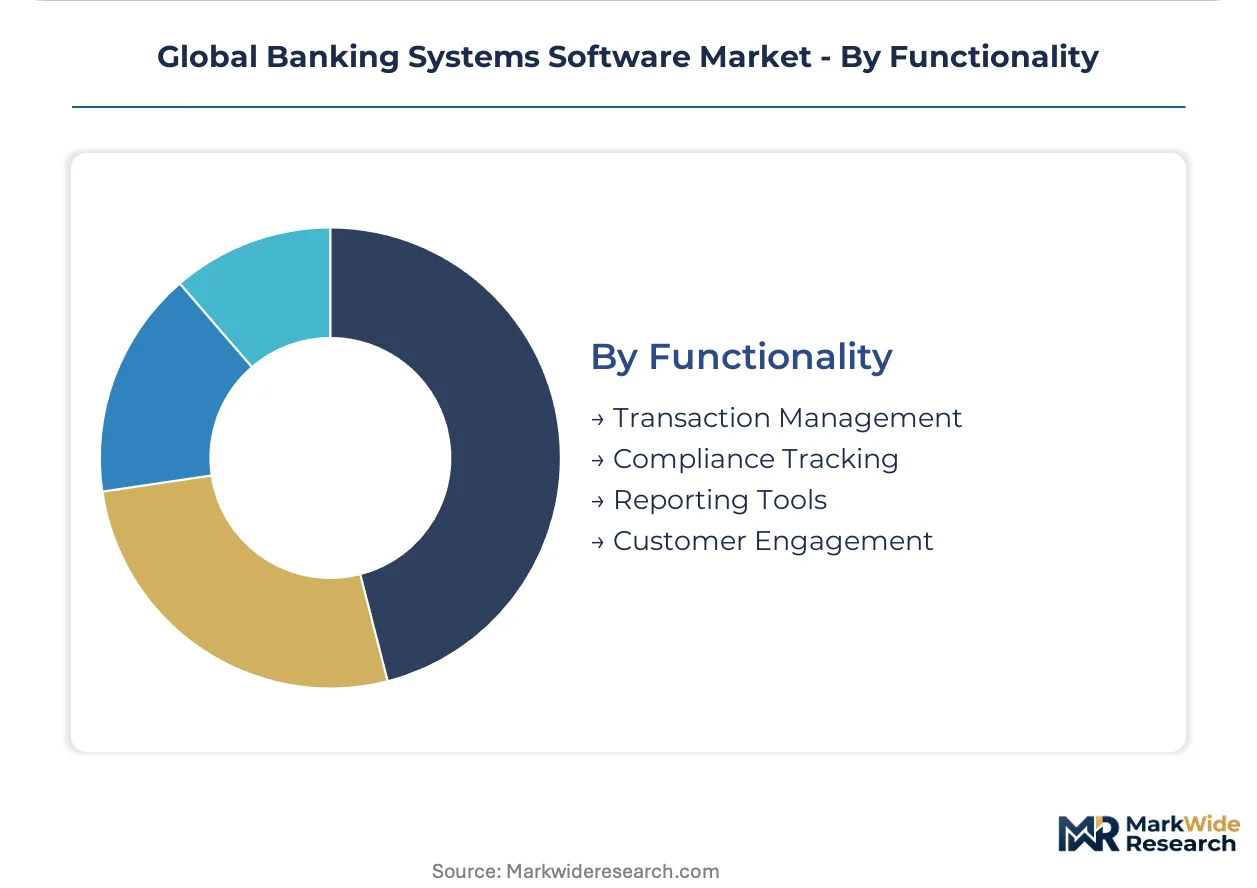
Functionality:
Application maturity varies across functional modules, with transaction management representing the most commoditized layer while compliance tracking commands sustained premium pricing.
- Transaction Management:Payment processing and account operation systems with 24/7 availability requirements. Brazilian tier-two banks modernize these fastest to meet Pix instant settlement mandates, abandoning batch-window architectures for event-driven microservices.
- Compliance Tracking:Automated regulatory reporting and audit trail generation with multi-jurisdiction engine requirements. Vendors maintain parallel compliance versions simultaneously as regional Basel III implementation variations proliferate, inflating development overhead.
- Reporting Tools:Executive dashboards and regulatory submission formatting with standardized data pipelines.
- Customer Engagement:CRM and marketing automation platforms facing margin compression from low-code alternatives.
Widest installed base: Transaction Management. Steepest pricing power: Compliance Tracking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's Square Mile anchors the highest concentration of banking technology procurement outside North America, with investment banks and clearing houses driving demand for real-time risk infrastructure. Regulatory divergence across monetary zones fragments vendor certification requirements.
United States
New York-based money center banks and San Francisco fintech clusters drive demand for cloud-native core replacements. The OCC and FDIC scrutinize vendor concentration in cloud outsourcing agreements, forcing multi-provider hybrid architectures. Chicago's derivatives exchanges require sub-100 millisecond latency for clearing systems.
Germany
Frankfurt's banking quarter and Munich's wealth management hubs sustain demand for PSD2-compliant payment APIs. The Bundesbank enforces ECB supervisory approval for core banking platforms. Berlin's neobank cluster adopts modular microservices fastest, leapfroging legacy mainframe dependencies.
India
Mumbai's commercial banking corridor and Bangalore's technology parks concentrate core system modernization demand. The RBI mandates core banking solution adoption for over 1,500 urban cooperative banks to ensure financial inclusion traceability. Hyderabad's cloud infrastructure providers support SaaS deployment models for mid-tier institutions.
Brazil
São Paulo's financial district and Rio de Janeiro's commercial banking centers drive Pix instant settlement compliance. The Banco Central do Brasil requires 24/7 transaction engines, forcing tier-two banks to abandon batch-processing cores. Curitiba's regional banks adopt event-driven microservices without legacy technical debt.
United Kingdom
The City of London and Edinburgh's asset management centers sustain demand for integrated wealth management platforms. The Financial Conduct Authority enforces operational resilience requirements for critical banking services. Manchester's emerging fintech cluster builds Banking-as-a-Service infrastructure for embedded finance deployments.
Global Banking Systems Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across deployment model sophistication, with tier-one commercial banks resisting SaaS transitions while neobanks force architectural unbundling. The vendor base clusters around three strategic archetypes: legacy core specialists with deep COBOL expertise, cloud-native challengers with API-first platforms, and ERP-anchored conglomerates leveraging transaction management adjacencies. Dominant competitive moves include vertical integration into payment networks and strategic partnerships with hyperscale cloud providers.
Within the legacy-to-cloud transition tier, Fidelity National Information Services Inc. and Jack Henry & Associates Inc. occupy positions anchored in North American credit union and community bank relationships, while Temenos AG exemplifies the modular architecture specialist archetype serving wealth management deployments across European private banking divisions.
| Leading Market Players |
|---|
| Fidelity National Information Services Inc. |
| SAP SE |
| Temenos AG |
| Mambu GmbH |
| Infosys Limited |
| Finastra International Ltd. |
| Oracle Corporation |
| Jack Henry & Associates Inc. |
| Fiserv Inc. |
| Others |
Supply Flow & Price Mechanics
API-first platform architectures are simultaneously collapsing legacy license premiums and fragmenting procurement authority across CIO and chief digital officer functions, compressing margin pools for monolithic vendors while elevating specialist component suppliers. This technical transition concentrates pricing power with engineers proficient in Kubernetes containerization and COBOL legacy bridging, creating acute scarcity premiums in talent-dependent cost structures.
Pricing Analysis
Uptime guarantees and transaction throughput SLAs anchor value-based pricing for core banking modules, with subscription tiers scaling by millisecond-latency performance bands and regulatory certification depth. Tier-one commercial banks in North America negotiate perpetual enterprise agreements resistant to SaaS conversion, while mid-market institutions in Australia and the Nordics embrace consumption-based models driven by balance sheet constraints. Cost compression in customer engagement modules intensifies as low-code alternatives erode traditional CRM pricing. Credit unions exhibit highest price sensitivity due to constrained IT budgets, whereas investment banks accept premium positioning for real-time risk calculation infrastructure.
Supply Chain Analysis
Central bank certification requirements for core banking platforms gate vendor participation, with RBI validation in India and ECB supervisory approval across the Eurozone creating regional qualification moats. Engineering talent concentrates in India, Poland, and Germany, where specialized training programs feed both legacy COBOL maintenance and cloud-native development pipelines. The supply chain draws from hyperscale cloud infrastructure providers, specialized middleware vendors, and regulatory compliance consultancies. Single-source vulnerability in Kubernetes-certified engineering pools threatens implementation timelines. Distribution runs through direct enterprise sales teams for tier-one institutions and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering capacity for legacy-to-cloud migration functions as the binding constraint propping pricing power across vendor tiers, with COBOL-proficient containerization specialists commanding scarcity premiums that extend project timelines and inflate implementation costs.
For Market Incumbents: Anchor defensive positioning through captive development of hybrid architecture expertise that bridges mainframe COBOL estates with Kubernetes-native platforms, insulating against cloud-native challengers. Deepen backward integration into regulatory compliance engines to capture Basel III implementation variations as recurring revenue streams. Prioritize certification investment for RBI-mandated urban cooperative bank replacements in India, where replacement cycle concentration creates volume leverage against emerging modular competitors. For New Entrants and Emerging Players: Tier-two banks in Brazil and Poland represent the most penetrable buyer archetype, having leapfrogged mainframe dependencies entirely and demonstrating openness to multi-source procurement strategies. Embedded finance infrastructure for Southeast Asian ride-hailing and e-commerce platforms offers uncaptured white space with limited incumbent penetration. Banking-as-a-Service licensing modules for telecom operators in Indonesia and Thailand provide a channel-driven go-to-market angle that bypasses direct core banking competition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by ERP-anchored conglomerates seeking transaction management adjacencies, with financial sponsor interest clustering around modular architecture specialists. Long-term viability hinges on sustaining engineering talent pipelines capable of both legacy maintenance and cloud-native development. Acquisition target archetypes include regional specialists with deep central bank certification relationships and proven parallel-run migration execution. The signal to watch is FedNow adoption velocity among US regional banks, which indicates core replacement cycle acceleration and vendor switching cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first unbundling of monolithic suites enables best-of-breed procurement for German and Dutch banks under PSD3 pressure. |
| Strategic Partnership | Hyperscale cloud alliances with AWS and Azure address OCC scrutiny of vendor concentration in US outsourcing agreements. |
| Acquisition of Specialist Firm | Climate risk module specialists capture EU CSRD-driven demand for carbon accounting integration within Basel III stacks. |
| Geographic Expansion | India's 1,500 urban cooperative bank RBI mandate creates immediate addressable market for certified core replacements. |
| Product Launch | Generative AI compliance documentation tools exploit EU AI Act explainability requirements for credit scoring algorithms. |
Methodological Framework
Multi-period observation of core banking replacement cycle velocity, regulatory mandate implementation timelines, and cloud-native adoption rates anchored the trend analysis, supplemented by interviews with CTOs at tier-one commercial banks, chief digital officers at neobanks, platform engineers at hyperscale cloud providers, and regulatory compliance leads at systemically important financial institutions. Secondary validation drew from SEC 10-K filings of publicly traded vendors, ECB supervisory approval databases, RBI circulars on urban cooperative bank modernization, and FedNow service provider disclosures. Bottom-up installation base counts across deployment models were triangulated against top-down vendor revenue segmentation.
The input-output matrix framed demand modeling across software type, deployment model, end-user category, and functionality module dimensions, with organization size and regional regulatory cluster serving as cross-cutting stratifiers. CAGRs were derived from trend extrapolation of replacement cycle compression and SaaS conversion rates. Forecast inputs included central bank mandate enforcement schedules, real-time payment rail deployment timelines, and engineering talent pool growth projections across certification categories.
Revisions become necessary when regulatory implementation timelines shift, central bank certification requirements expand, or hyperscale cloud concentration triggers additional supervisory scrutiny. Forecasts reflect assumptions about sustained engineering scarcity and parallel-run migration complexity. A model refresh is warranted upon material change in open banking mandate enforcement intensity or generative AI regulatory classification outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Investment Banking and Trading Services Market
Banking
Banking Maintenance Support and Services Market
Banking
Third-Party Banking Software Market
Banking
Middle East Data Analytics in Banking Market
Banking
Core Banking Solutions Market
Banking
Singapore Data Analytics in Banking Market
Banking
UK Banking as a Service Market
Banking
Banking Wearable Devices Market
Banking
Saudi Arabia Retail Banking Market
Banking
Global AI in Banking Market
Banking
Bank Kiosk Market
Banking
Blockchain in Retail Banking Market
Banking
Cloud-Based Core Banking Market
Banking
Asia-Pacific Machine Learning in Banking Market
Banking
Africa Data Analytics in Banking Market
Banking
Bank Guarantee Market