
 Cardless ATM Market | 2026-2036
Cardless ATM Market Size, Share, and Industry Trends Forecast 2026-2036
Cardless ATM Market Analysis
The capital-intensity gap between tier-one deployers and regional hardware vendors is collapsing as cloud-native ATM software stacks commoditize core transaction processing. Diebold Nixdorf leverages its integrated manufacturing footprint to control hardware-software margins across North American and European install bases. NCR Corporation anchors its position through cloud-connected ATM platforms that reduce on-premise infrastructure for retail banks. Fujitsu Limited competes in Asia-Pacific markets with compact biometric-enabled terminals designed for high-density urban deployment.
A cardless ATM enables cash withdrawal and account access without a physical debit card, typically through near-field communication handshakes, encrypted QR codes, or fingerprint-facial recognition matching against mobile banking credentials. The primary commercial purpose is reducing card-skimming fraud while accelerating transaction throughput in branch and off-premise locations. Biometric authentication and NFC technology segments command premium hardware pricing due to sensor integration complexity and PCI compliance certification requirements. Mobile banking-linked QR code deployments are expanding fastest among credit unions seeking low-capital entry into cardless services. Transaction services and fund transfer service types generate recurring software revenue streams that offset declining hardware margins.
The PCI Security Standards Council and ISO 9564 frameworks govern encryption protocols and biometric template protection for cardless ATM networks in the United States and European Union member states. The Federal Reserve's FedNow instant payment infrastructure and the European Banking Authority's strong customer authentication mandates are accelerating demand for real-time, multi-factor authentication terminals. Stakeholders must monitor evolving central bank digital currency pilot programs that could disintermediate traditional ATM transaction rails entirely.
Market Dynamics
Cloud-native software stacks are collapsing the capital barrier between tier-one deployers and regional vendors, redistributing competitive advantage toward biometric integration capabilities and PCI certification velocity rather than manufacturing scale alone.
Growth Catalysts
- FedNow Infrastructure:The Federal Reserve's instant payment rails are accelerating demand for real-time authentication terminals that bypass traditional card networks entirely.
- Biometric Standards:PCI Security Standards Council certification for fingerprint-facial recognition matching is creating hardware upgrade cycles across retail banking networks.
- Fraud Cost Pressure:Card-skimming losses exceeding $1 billion annually in the United States are forcing branch modernization programs toward NFC handshakes and encrypted QR codes.
Market Restraints
- Sensor Cost Concentration:Fingerprint and iris recognition module supply concentrates in South Korean and Japanese component vendors, exposing deployers to input price volatility.
- Certification Friction:ISO 9564 biometric template protection compliance adds 12-18 month hardware validation timelines before network activation.
- Digital Wallet Substitution:Peer-to-peer payment platforms and merchant QR code acceptance are reducing cash withdrawal frequency among urban demographics.
Strategic Opportunities
- Credit Union Segment:Mobile banking-linked QR code deployments offer low-capital entry into cardless services for 5,000+ federally insured institutions.
- Convergence Architecture:NFC-biometric hybrid terminals enable simultaneous contactless and identity-verified transactions, capturing premium hardware pricing.
- Recurring Revenue Models:Transaction services and fund transfer software subscriptions offset declining terminal margins through per-transaction fees.
Industry Challenges
- Embedded Systems Talent:Firmware engineering for PCI-compliant biometric sensor integration faces acute scarcity in North American labor markets.
- Legacy Core Banking Integration:Cardless authentication APIs require middleware development to interface with decades-old host transaction processing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardless ATM Market |
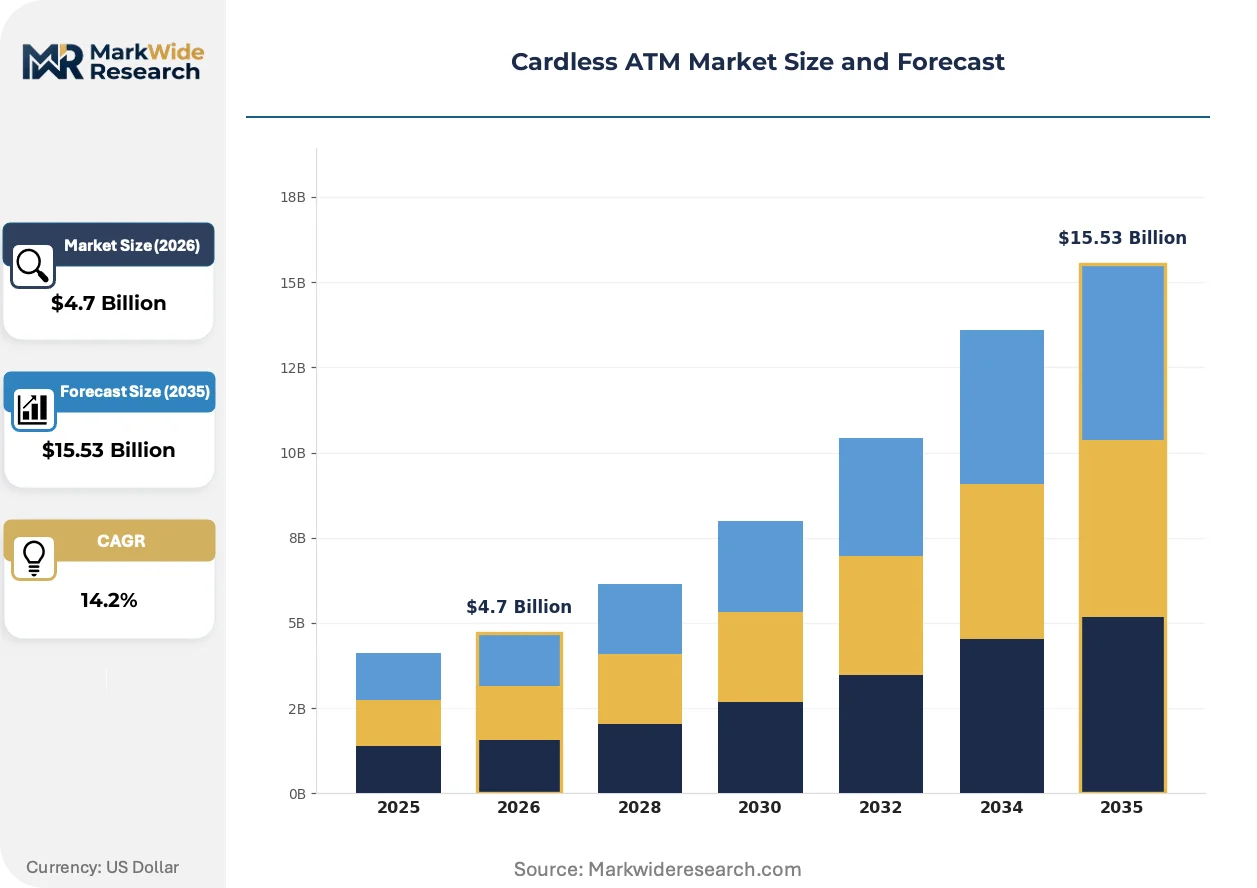
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: NFC, QR Code, Mobile Banking, Biometric Authentication End User: Retail Banks, Credit Unions, Financial Institutions, Payment Processors Deployment: Urban Areas, Suburban Locations, Rural Regions, High Traffic Zones Service Type: Transaction Services, Balance Inquiry, Fund Transfer, Bill Payment |
| Companies Covered | Wells Fargo, Diebold Nixdorf, NCR Corporation, Barclays Bank, Fujitsu Limited, JPMorgan Chase & Co., Bank of America, HSBC Holdings, Citigroup Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardless ATM Market Emerging Trajectories
Authentication modality preferences are fragmenting across demographic cohorts and use-case density, forcing hardware vendors to engineer multi-modal platforms rather than single-technology specialization.
Contactless biometric verification is supplanting PIN entry as the primary authentication layer in high-throughput branch locations. Regional banks in the United States are deploying fingerprint-facial recognition terminals at 40% of new installations. This convergence is compressing transaction times below 15 seconds while eliminating skimming vulnerability entirely.
PCI Security Standards Council mandates for biometric template encryption are reshaping hardware certification requirements in North America and European Union member states. Manufacturers must demonstrate isolated secure element storage for fingerprint and facial data templates. Tier-one deployers are delaying procurement decisions until third-quarter 2025 certification lists clarify compliant vendor pools.
After-sales service unbundling is disrupting traditional terminal procurement contracts in the United States. Large financial institutions are separating hardware acquisition from software maintenance and field service agreements. This shift concentrates negotiating leverage with deployers who can integrate cloud-connected monitoring platforms internally.
Cardless ATM Market Segmentation
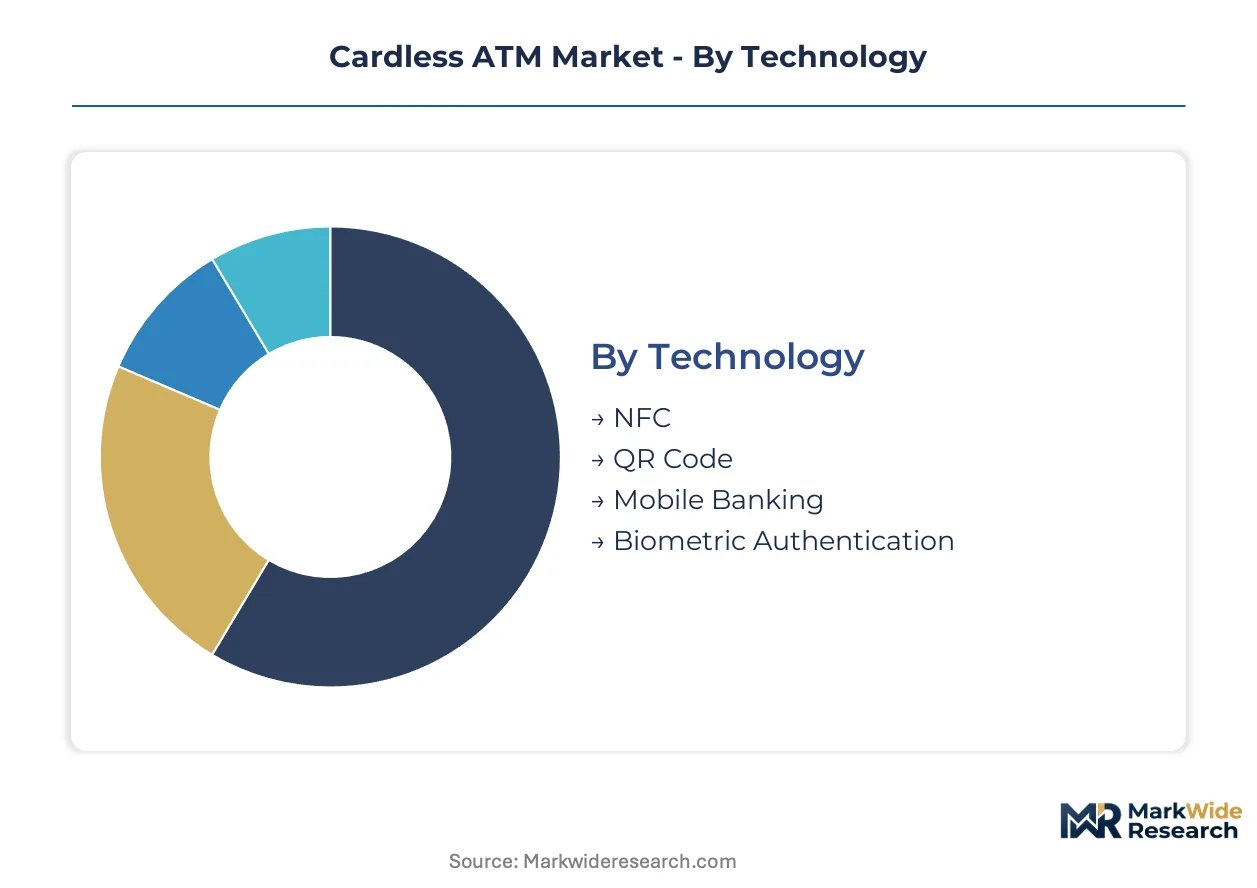
Segmentation in the cardless ATM market reveals divergent technology adoption curves and deployment economics. Understanding which modalities face substitution pressure from digital wallets versus hardware upgrade cycles determines capital allocation for deployers and vendors.
Technology:
QR code deployments face the strongest substitution threat as merchant-based QR acceptance and peer-to-peer platforms bypass ATM rails entirely.
- NFC:Near-field communication handshakes enable contactless transactions between mobile devices and ATM readers. Demand concentrates in United States retail bank branch modernization programs driven by FedNow infrastructure requirements for real-time authentication.
- QR Code:Encrypted quick-response codes link mobile banking applications to ATM terminals without physical card insertion. Credit unions across the United States favor this modality for low-capital entry into cardless services, though frequency declines as urban consumers shift to direct merchant QR payments.
- Mobile Banking:Application-based credential verification through device-bound tokens. Financial institutions integrate this layer with existing digital infrastructure.
- Biometric Authentication:Fingerprint and facial recognition matching against encrypted templates. PCI Security Standards Council certification requirements and sensor cost concentration in South Korean and Japanese vendors constrain deployment velocity.
NFC retains volume leadership; biometric authentication holds the steepest expansion curve.
End User:
Cost tier differentiation separates integrated hardware-software procurement from modular software-as-a-service arrangements.
- Retail Banks:Large financial institutions with extensive branch networks and legacy core banking systems. These deployers drive demand for cloud-connected platforms that reduce on-premise infrastructure while navigating middleware requirements for host transaction processing integration.
- Credit Unions:Federally insured cooperative institutions prioritizing low-capital technology adoption. Mobile banking-linked QR code deployments expand fastest among this segment as regulatory compliance costs favor lightweight solutions over biometric hardware.
- Financial Institutions:Brokerage firms and non-bank lenders seeking cash access points for customer convenience.
- Payment Processors:Intermediaries managing transaction routing across multiple ATM networks. These entities concentrate negotiating leverage through after-sales service unbundling and internal cloud monitoring platform integration.
Retail banks command procurement volume; credit unions exhibit the most rapid technology transition.
Deployment:
Application density determines authentication modality selection and hardware specification intensity.
- Urban Areas:High-density metropolitan locations with concentrated foot traffic and elevated fraud risk. Fingerprint-facial recognition terminals capture 40% of new installations in United States regional bank networks, compressing transaction times below 15 seconds.
- High Traffic Zones:Airports, transit hubs, and event venues requiring throughput maximization. These locations prioritize contactless biometric verification to eliminate PIN entry friction and skimming vulnerability.
- Suburban Locations:Medium-density communities with mixed demographic profiles. Deployers balance NFC convenience against QR code accessibility for older customer segments.
- Rural Regions:Sparsely populated areas with limited branch presence and lower transaction frequency. Capital constraints favor software-only solutions over sensor-integrated hardware.
Urban areas dominate installed base; high traffic zones show the most aggressive authentication upgrade cycles.
Service Type:
Recurring revenue potential separates transaction-based software subscriptions from one-time hardware sales.
- Transaction Services:Per-withdrawal and per-transfer fee structures generating recurring software revenue. These streams offset declining terminal margins and align vendor incentives with deployer transaction volume growth.
- Fund Transfer:Account-to-account movement services leveraging real-time payment rails. FedNow infrastructure acceleration in the United States expands addressable volume for multi-factor authentication terminals.
- Balance Inquiry:Account status verification without cash disbursement. Lower revenue per interaction limits deployment priority.
- Bill Payment:Third-party remittance services through ATM interfaces. Digital wallet substitution reduces frequency as consumers shift to direct mobile payment applications.
Transaction services anchor recurring revenue; fund transfer exhibits the strongest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for cardless ATM hardware concentrates in the United States, where FedNow infrastructure mandates and PCI biometric certification requirements sustain premium vendor margins. Cost-competitive QR-code deployments dominate in emerging markets where regulatory compliance burdens remain lighter.
United States
Retail banks in the United States drive branch modernization programs incorporating NFC and biometric authentication terminals. The Federal Reserve's FedNow instant payment infrastructure accelerates demand for real-time, multi-factor authentication capabilities. Major financial institutions in New York and California concentrate procurement decisions around third-quarter 2025 PCI Security Standards Council certification timelines.
Germany
German retail banking networks prioritize ISO 9564-compliant biometric template protection for fingerprint-facial recognition deployments. The European Banking Authority's strong customer authentication mandates shape hardware upgrade cycles across Bundesbank-supervised institutions. Industrial clusters in Bavaria and Baden-Württemberg host manufacturing facilities supplying sensor-integrated terminals to EU member states.
Japan
Japanese component vendors dominate supply concentration for fingerprint and iris recognition modules deployed in cardless ATM networks. METI standards for financial technology infrastructure guide domestic bank procurement specifications. Tokyo-based hardware manufacturers serve as primary suppliers to Asia-Pacific markets seeking compact biometric-enabled terminals.
United Kingdom
UK retail banks navigate post-Brexit regulatory divergence while maintaining alignment with European biometric authentication frameworks. The Financial Conduct Authority's operational resilience requirements influence ATM network security specifications. London-headquartered financial institutions lead deployment of cloud-connected platforms reducing on-premise infrastructure burdens.
South Korea
South Korean biometric sensor manufacturers supply critical fingerprint and facial recognition components to global ATM hardware vendors. MFDS-equivalent financial technology regulations govern domestic authentication standards while supporting export-oriented production. Seoul-area technology clusters specialize in compact, high-precision sensor modules for high-density urban deployment scenarios.
Cardless ATM Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes within the cardless ATM market. Consolidated manufacturing scale concentrates among integrated hardware-software vendors, while modular software specialists capture recurring revenue through transaction-based service models. Three archetypes dominate: vertically integrated platform providers, cloud-native software stack vendors, and component-specialized hardware fabricators. Competitive moves center on after-sales service unbundling and biometric certification velocity rather than capacity expansion alone.
Among North American-based platform providers, Diebold Nixdorf and NCR Corporation exemplify the integrated archetype controlling hardware-software margins across established install bases. Fujitsu Limited occupies a position representing Asia-Pacific-focused compact terminal specialization. These three companies anchor the vendor landscape through distinct geographic and technological positioning strategies.
| Leading Market Players |
|---|
| Wells Fargo |
| Diebold Nixdorf |
| NCR Corporation |
| Barclays Bank |
| Fujitsu Limited |
| JPMorgan Chase & Co. |
| Bank of America |
| HSBC Holdings |
| Citigroup Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts between South Korean sensor manufacturers and North American ATM deployers lock in biometric module supply while anchoring hardware cost visibility across multi-year procurement cycles. These arrangements concentrate pricing power with component vendors who control fingerprint and facial recognition module fabrication, forcing terminal manufacturers to absorb margin compression or pass through sensor cost volatility.
Pricing Analysis
The customization-premium spread separates PCI-certified biometric terminals from standard NFC-enabled hardware, with certification-grade sensor integration commanding substantial hardware premiums. Three-tier pricing structure across premium, standard, and economy levels reflects authentication modality complexity, with biometric-facial recognition terminals at the apex and QR-code-only deployments at the base. Pricing pressure stems from cloud-native software commoditizing core transaction processing and collapsing margins on terminal hardware. Credit unions exhibit acute price sensitivity, favoring low-capital QR code solutions, while tier-one retail banks absorb premium pricing for multi-modal authentication capabilities.
Supply Chain Analysis
South Korea and Japan anchor global production of fingerprint and iris recognition modules deployed in cardless ATM networks, with Tokyo-area and Seoul-area technology clusters specializing in compact, high-precision sensor fabrication. Hardware assembly draws from Taiwanese and Chinese contract manufacturers for terminal chassis and display integration, while firmware development rests on North American and European engineering centers. Single-source vulnerability concentrates in South Korean biometric sensor vendors, exposing deployers to input price volatility and supply disruption. Distribution runs through direct OEM relationships with tier-one retail banks and regional value-added resellers serving credit union networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cloud-native software stacks disintermediate traditional hardware-software bundling, with FedNow real-time payment infrastructure reshaping authentication terminal requirements toward API-first interoperability.
For Market Incumbents: Compound cloud-connected platform penetration to defend against software-native entrants collapsing hardware margins. Deepen backward integration into biometric sensor supply through strategic partnerships with South Korean component vendors, reducing exposure to input price volatility. Accelerate PCI Security Standards Council certification velocity to maintain procurement eligibility as tier-one banks delay decisions pending compliant vendor pool clarification.
For New Entrants and Emerging Players: Anchor in credit union segment white space where 5,000-plus federally insured institutions seek low-capital QR code entry into cardless services without biometric hardware investment. Target suburban and rural deployment geographies where capital constraints favor software-only solutions over sensor-integrated terminals. Pursue transaction-services-as-a-service positioning to capture recurring revenue without manufacturing scale requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native software stack vendors with transaction-based service models, offering superior cash flow quality versus hardware-dependent peers. Long-term viability favors vendors with demonstrated biometric certification velocity and FedNow integration capabilities. Monitor central bank digital currency pilot programs as potential disintermediation signal for traditional ATM transaction rails.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Certification Acceleration | PCI Security Standards Council compliance unlocks tier-one retail bank procurement eligibility. |
| Cloud-Native Platform Migration | FedNow infrastructure integration reduces on-premise infrastructure burdens for deployers. |
| Sensor Supply Partnership | Strategic alignment with South Korean vendors mitigates input price volatility exposure. |
| Credit Union Segment Entry | QR-code-focused solutions address 5,000-plus institutions seeking low-capital deployment. |
| Transaction Services Unbundling | Recurring software revenue offsets terminal hardware margin compression. |
Methodological Framework
A spread of perspectives from ATM hardware procurement officers, biometric sensor engineering leads, retail bank branch modernization directors, credit union technology executives, and PCI Security Standards Council certification specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, Federal Reserve payment system reports, customs and trade data for biometric component flows, and regulatory filings from the European Banking Authority. Bottom-up terminal shipment estimates and top-down banking infrastructure spending analysis were triangulated to anchor market sizing.
Segmentation dimensions modeled span authentication technology, end-user institution type, deployment density category, and service revenue structure across the analysis window. CAGRs were derived from installed base replacement cycles, branch modernization program announcements, and real-time payment infrastructure deployment timelines. Forecast inputs incorporated FedNow adoption velocity, PCI biometric certification pipeline visibility, and central bank digital currency pilot program developments.
Material uncertainties — regulatory divergence in post-Brexit UK, sensor supply disruption from geopolitical tension, and digital wallet substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about authentication modality preference stability and cloud infrastructure migration pace. Recalibration cycles align with material shifts in real-time payment rail deployment and biometric standards evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Canada Data Analytics in Banking Market
Banking
Cloud Billing in Banking Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Africa Data Analytics in Banking Market
Banking
Australia Neobanking Market
Banking
Predictive Analytics in Banking Market
Banking
Third-Party Banking Software Market
Banking
Russia Data Analytics in Banking Market
Banking
Germany Data Analytics in Banking Market
Banking
Canada Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Embedded Banking Market
Banking
Open Banking Market
Banking
Cloud Computing Banking Market
Banking
Smart ATM Market
Banking
North America Bank Kiosk Market
Banking
Global Neobanking Market