
 Cloud Billing in Banking Market | 2026-2036
Cloud Billing in Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Billing in Banking Market Analysis
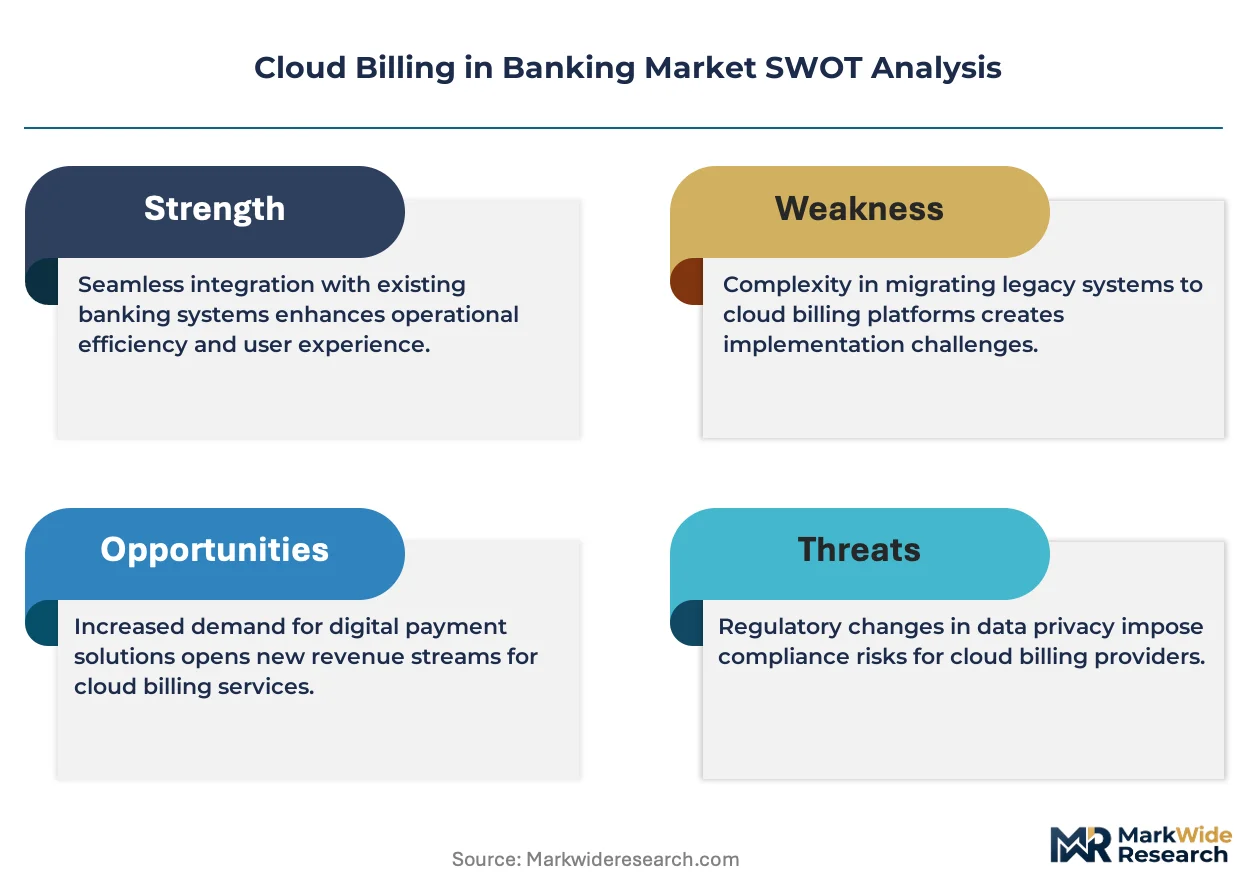
ISO 27001 certification is bifurcating the competitive landscape for cloud billing platforms serving financial institutions. Microsoft Azure leverages its FedRAMP authorizations to anchor public-sector banking contracts in North America. Amazon Web Services sustains R&D intensity across its dedicated financial services competency program, while Temenos specializes in core-agnostic billing orchestration for tier-one institutions.
Cloud billing in banking encompasses metered resource allocation, transaction-based invoicing, and API-driven cost attribution across distributed infrastructure environments, typically operating with sub-second latency for real-time payment settlement and 99.99% uptime SLAs. The technology stack serves commercial banks by enabling granular cost recovery from corporate treasury clients and dynamic pricing for liquidity services. Deployment patterns favor hybrid cloud configurations among retail banks seeking to retain sensitive customer data on-premises while bursting transactional workloads to public infrastructure. Service type segmentation shows usage billing outpacing subscription models as open banking APIs proliferate and transaction volumes become less predictable.
PCI DSS, GDPR, and the EU AI Act collectively govern data residency, algorithmic transparency, and payment security standards that determine market access for platform vendors. The Federal Reserve's FedNow service and India's UPI network illustrate how national real-time payment infrastructures create jurisdiction-specific compliance layers that shape product roadmaps. Stakeholders must monitor evolving central bank digital currency frameworks and their implications for billing granularity and settlement finality.
Market Dynamics
Real-time payment infrastructure buildouts across major economies are forcing cloud billing platforms to compress latency thresholds below 100 milliseconds while maintaining PCI DSS compliance across hybrid deployment architectures.
Growth Catalysts
- FedNow service rollout:The Federal Reserve's instant payment system in the United States mandates sub-second settlement visibility, driving demand for metered billing engines that can attribute infrastructure costs per transaction.
- Open Banking API proliferation:PSD2 and its successors across European markets require granular cost attribution for third-party payment service providers, expanding the addressable base for usage-based billing modules.
- Containerized microservices:Kubernetes-orchestrated billing engines enable retail banks to burst transactional workloads to public cloud during peak demand windows without overprovisioning fixed capacity.
Market Restraints
- Hybrid cloud complexity:Maintaining consistent billing logic across on-premises data centers and public cloud environments requires duplicate compliance audits for PCI DSS and ISO 27001, inflating implementation timelines.
- Talent scarcity in financial cloud architecture:Banks in Germany and India compete for engineers with dual expertise in core banking systems and cloud-native billing platforms, compressing deployment velocity.
- Data residency mandates:RBI guidelines in India and GDPR provisions in Europe prevent certain transaction data from leaving national boundaries, fragmenting vendor addressable markets.
Strategic Opportunities
- Central bank digital currency integration:Pilot programs for wholesale CBDC settlement in Singapore and retail CBDC trials in India will require entirely new billing primitives for programmable money flows.
- Embedded finance orchestration:Non-bank platforms deploying banking-as-a-service offerings need white-label billing engines that can attribute costs across complex multi-party transaction chains.
- Carbon-aware billing:CSRD disclosure requirements in Europe create demand for cloud billing platforms that surface Scope 3 emissions per transaction, enabling green pricing differentiation.
Industry Challenges
- Core banking system entanglement:Decades-old COBOL-based ledger architectures in tier-one institutions resist API integration with modern billing engines, forcing expensive middleware layers.
- Multi-jurisdiction certification lag:Vendors must sequentially obtain FedRAMP authorization, PCI DSS Level 1 certification, and national banking regulator approvals, stretching product roadmaps across 18-24 month cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Billing in Banking Market |
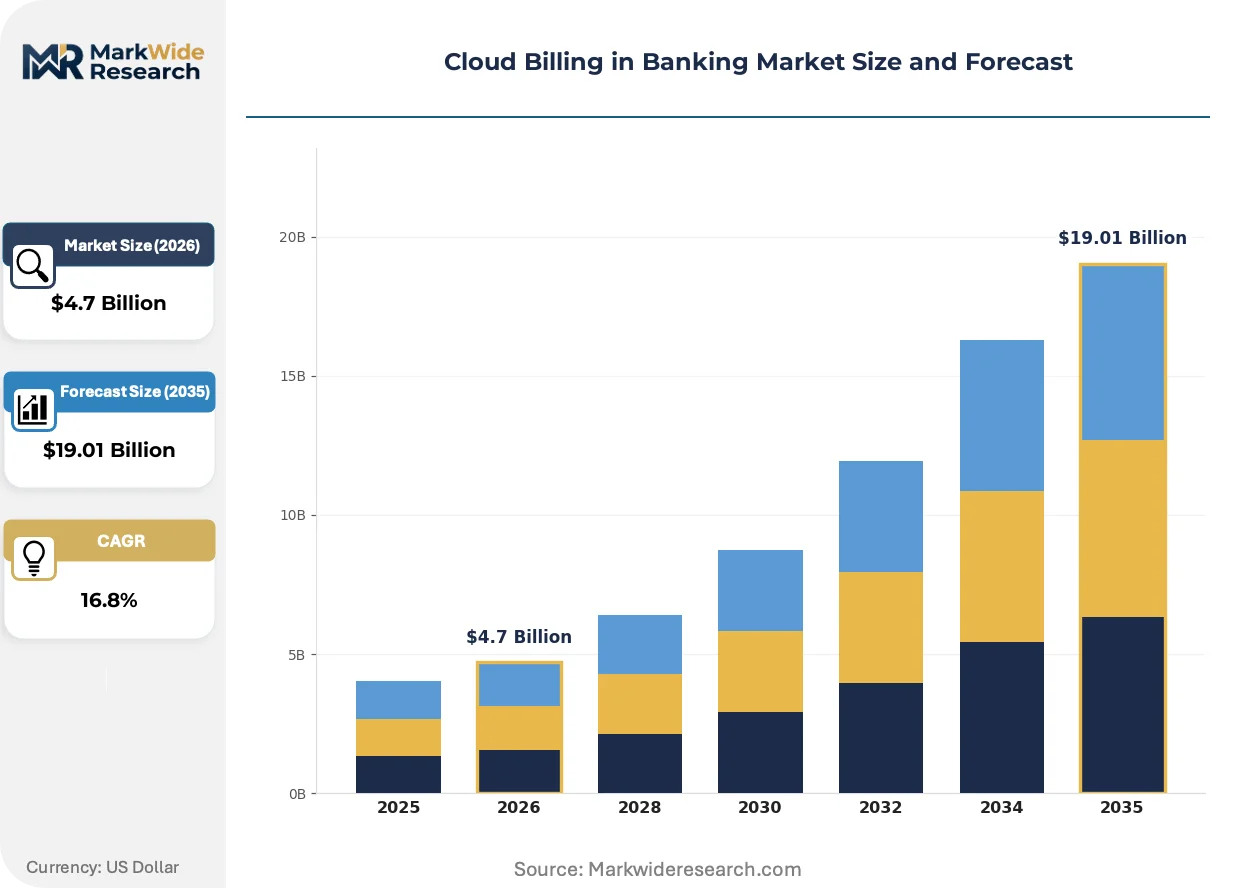
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Subscription Billing, Usage Billing, Invoice Management, Payment Processing End User: Retail Banks, Commercial Banks, Investment Banks, Credit Unions Technology: Software as a Service, Platform as a Service, Payment Gateway, API Integration |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Cloud, Temenos, Finacle, Fiserv, FIS, Mambu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Billing in Banking Market Emerging Trajectories
Event-driven billing architectures are replacing batch-oriented invoicing systems as transaction velocity and pricing granularity requirements intensify across retail and commercial banking segments.
Native metering agents embedded directly within Kubernetes sidecar containers are supplanting traditional hypervisor-level resource monitoring. Tier-two banks in India and Germany are adopting these agents to achieve per-transaction cost attribution without proxy latency. This architectural shift is compressing vendor differentiation around raw metering precision rather than dashboard aesthetics.
The EU AI Act's risk classification framework for credit-scoring algorithms is mandating algorithmic transparency logs that must be billed and stored separately from core transaction data. Cloud billing platforms serving European banks must now partition AI inference costs from traditional payment processing fees. Dutch and French regulators are requiring these partitions in audit trails, forcing product roadmap prioritization.
Corporate treasury clients are unbundling liquidity management fees from payment processing charges, demanding itemized invoices that attribute cloud infrastructure costs to specific treasury workstations. This procurement pattern is most visible among multinational corporations banking with institutions in the United States and Germany. Vendors responding with API-first billing granularity are capturing preferred vendor status in RFP processes.
Cloud Billing in Banking Market Segmentation
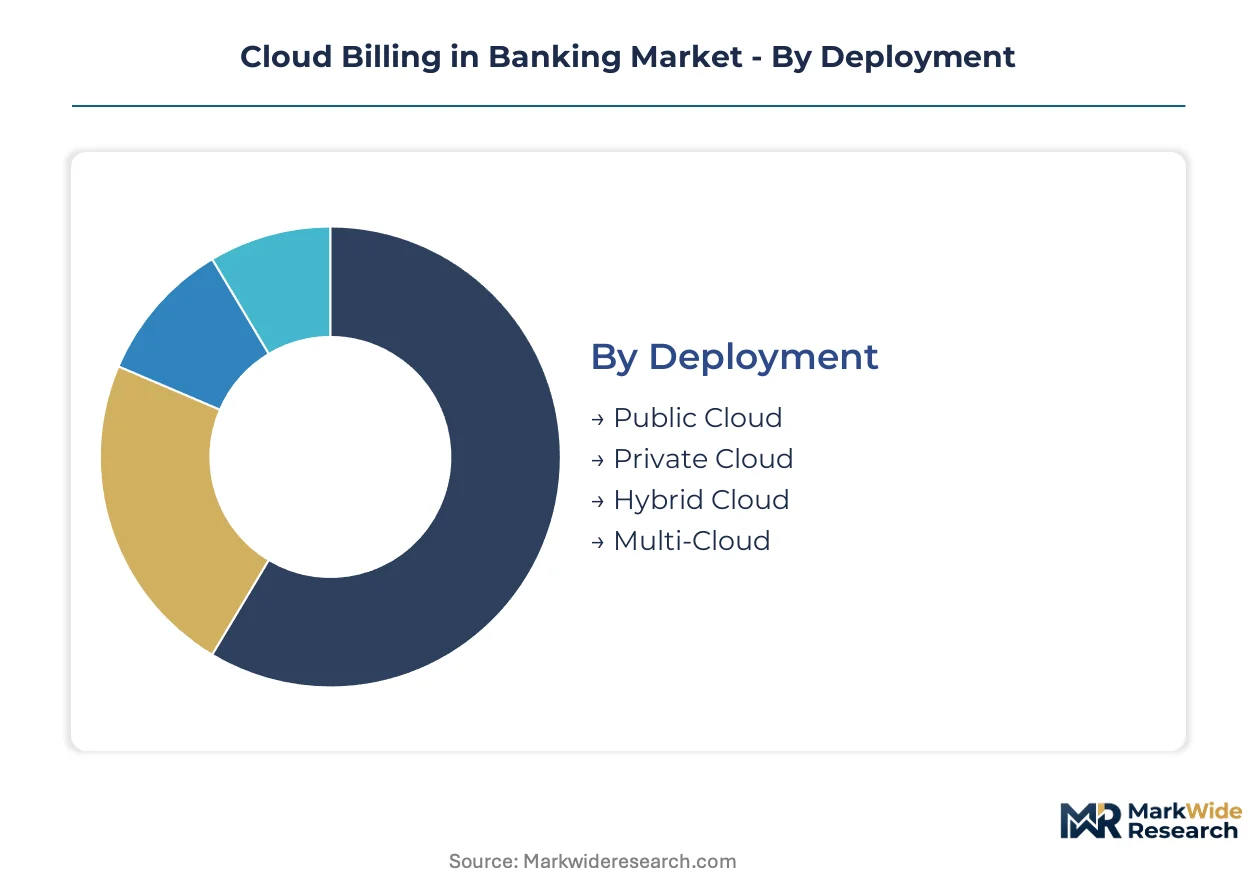
Cloud billing architectures fragment across four distinct dimensions, each reflecting different compliance postures and infrastructure investment patterns. Deployment models determine data residency capabilities, while service types capture the shift from fixed subscriptions to metered consumption. End-user segmentation reveals divergent latency requirements between retail transaction volumes and corporate treasury complexity.
Deployment:
Margin pools concentrate in configurations that balance elastic scalability with sovereign data control, particularly where central bank mandates restrict cross-border data flows.
- Public Cloud:Delivers metered compute and storage via hyperscale provider infrastructure with sub-second provisioning. Demand concentrates among neobanks and fintech subsidiaries in the United States seeking to bypass capital-intensive data center builds, though FedRAMP authorization requirements filter vendor eligibility.
- Hybrid Cloud:Orchestrates sensitive customer data on-premises while bursting transactional workloads to public infrastructure during peak windows. Tier-one retail banks in Germany favor this model to satisfy GDPR data residency mandates without sacrificing elasticity for seasonal payment surges.
- Private Cloud:Dedicated infrastructure deployed within bank-controlled facilities or single-tenant hosted environments. Indian commercial banks under RBI guidelines deploy private clouds for core ledger systems requiring guaranteed latency below 50 milliseconds.
- Multi-Cloud:Distributes workloads across two or more hyperscale providers to mitigate vendor concentration risk and optimize regional latency. Investment banks in Singapore leverage multi-cloud billing engines to arbitrage infrastructure pricing across AWS, Azure, and Google Cloud regions.
The dominant share belongs to Hybrid Cloud, while Multi-Cloud is closing the gap fastest as institutions diversify vendor concentration risk.
Service Type:
Revenue concentration tracks the migration from predictable subscription models toward granular consumption metering driven by open banking API proliferation.
- Usage Billing:Attributes infrastructure costs per transaction, API call, or compute second with real-time metering precision. PSD2-mandated third-party provider access across European markets forces retail banks to adopt usage-based modules for granular cost recovery from payment service providers.
- Subscription Billing:Fixed periodic charges for baseline platform access and committed capacity tiers. Smaller credit unions in the United States retain subscription models to simplify budgeting predictability despite sacrificing cost optimization opportunities.
- Invoice Management:Automated generation, distribution, and reconciliation of billing documents across multi-party transaction chains. Corporate treasury clients in Germany demand itemized invoices attributing cloud costs to specific workstations, unbundling liquidity fees from processing charges.
- Payment Processing:Settlement orchestration including PCI DSS-compliant tokenization and real-time payment rail integration. India's UPI network buildout drives demand for processing modules that compress settlement latency below 100 milliseconds.
Usage Billing commands the largest revenue pool, with Invoice Management expanding most quickly as corporate procurement demands granular cost attribution.
End User:
Technology requirements diverge sharply between high-volume retail transaction processing and complex multi-currency treasury operations.
- Retail Banks:Consumer-facing institutions processing millions of daily transactions across cards, deposits, and digital wallets. Institutions in India and the United States drive demand for burst-capable billing engines handling 10x volume spikes during payroll cycles.
- Commercial Banks:Corporate and institutional banking divisions managing liquidity, trade finance, and treasury services. German commercial banks require billing granularity that separates AI inference costs from payment processing fees per EU AI Act audit mandates.
- Investment Banks:Capital markets and securities operations with sub-millisecond latency requirements for algorithmic trading infrastructure. Singapore-based institutions pilot wholesale CBDC settlement modules requiring entirely new billing primitives for programmable money flows.
- Credit Unions:Member-owned cooperative institutions with constrained IT budgets and simplified compliance obligations. United States credit unions favor standardized subscription billing over complex usage metering to minimize operational overhead.
Commercial Banks generate the highest average contract values, though Retail Banks provide the deepest volume base across installed seats.
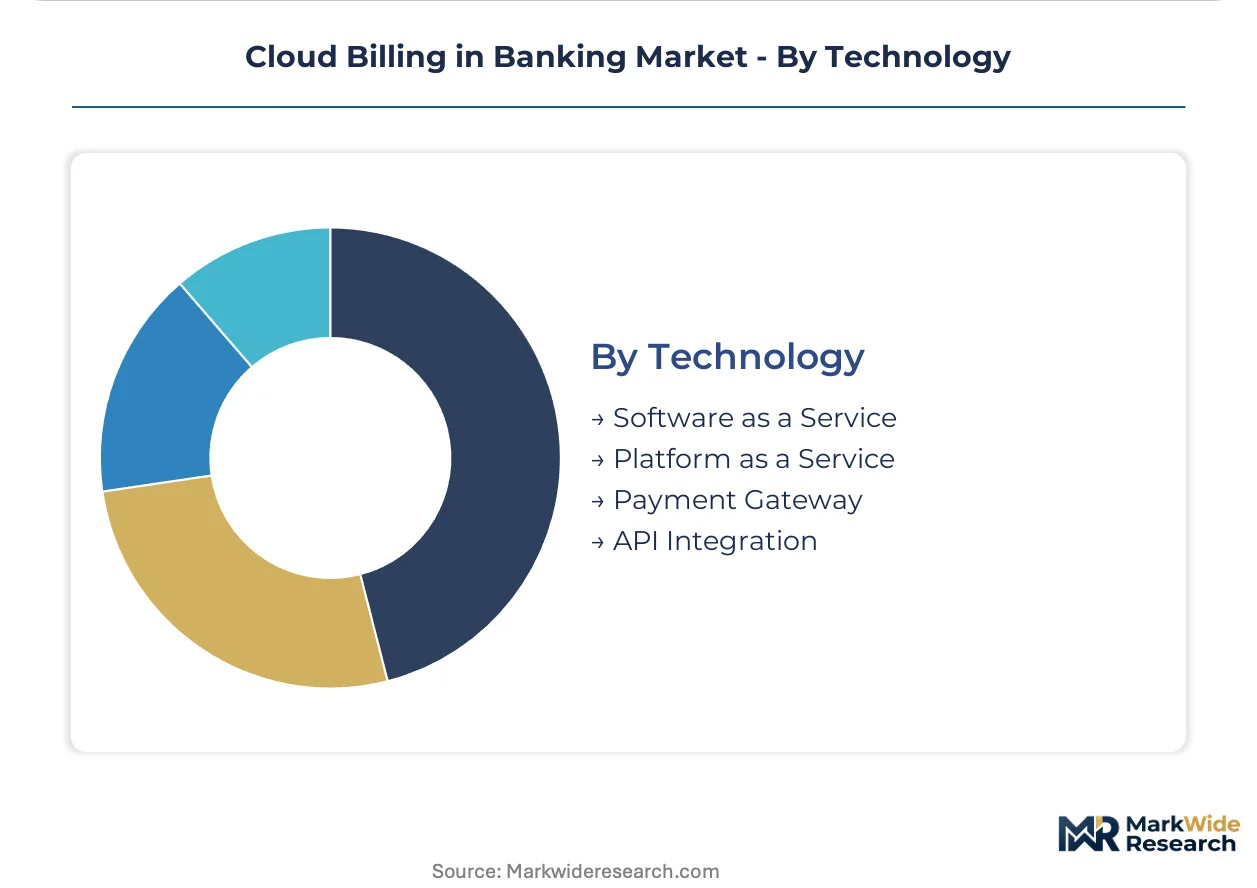
Technology:
Architecture choices determine integration complexity with legacy core banking systems and compliance automation capabilities.
- Software as a Service:Cloud-native billing applications delivered via browser with automatic updates and shared infrastructure economics. Neobanks across Germany and India accelerate deployment velocity by bypassing on-premises installation cycles.
- Platform as a Service:Developer-centric environments enabling custom billing workflow construction and API orchestration. Tier-two banks in Singapore leverage PaaS layers to build CBDC-compatible settlement modules without core system replacement.
- Payment Gateway:Specialized infrastructure handling authorization, settlement, and reconciliation across card networks and real-time payment rails. United States institutions integrating FedNow service demand gateway modules with sub-second settlement visibility.
- API Integration:Middleware connectivity enabling billing engines to ingest transaction data from COBOL-based core systems and modern microservices alike. European banks facing PSD2 open banking mandates prioritize API-first billing granularity for third-party provider cost attribution.
SaaS deployments retain the broadest installed base, while API Integration is climbing fastest as legacy modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FedNow's real-time payment rails anchor the United States' infrastructure leadership, while Germany's TARGET2 connectivity and India's UPI network create parallel demand centers for sub-second billing engines.
United States
The Federal Reserve's FedNow service mandates instant settlement visibility, driving tier-one banks to deploy metered billing engines that attribute infrastructure costs per transaction. SEC disclosure rules and FedRAMP authorization requirements filter vendor eligibility for public-sector contracts. New York's financial district hosts the densest cluster of neobanks adopting burst-capable cloud configurations to bypass capital-intensive data center builds.
Germany
Commercial banks in Frankfurt require billing granularity that separates AI inference costs from payment processing fees under EU AI Act audit mandates. GDPR data residency provisions and BaFin supervision guidelines enforce strict cross-border data controls. Bavaria's Munich tech corridor concentrates fintech subsidiaries leveraging hybrid cloud models to satisfy sovereign data requirements without sacrificing elasticity.
India
The Reserve Bank of India's UPI network buildout and CBDC pilot programs create jurisdiction-specific compliance layers for programmable money flows. RBI guidelines prevent certain transaction data from leaving national boundaries, fragmenting vendor addressable markets. Mumbai's banking district anchors the deepest volume base for retail transaction processing across installed cloud billing seats.
Singapore
Wholesale CBDC settlement pilots and multi-cloud arbitrage strategies position the city-state as a testbed for entirely new billing primitives. Monetary Authority of Singapore sandbox frameworks enable tier-two banks to build CBDC-compatible modules without core system replacement. The Marina Bay financial cluster hosts investment banks leveraging distributed workloads across AWS, Azure, and Google Cloud regions.
Cloud Billing in Banking Market Vendor Landscape
Listed hyperscale cloud providers compete with private banking technology specialists across certification depth and core system integration capabilities. The vendor base concentrates around three tiers: hyperscale infrastructure platforms with FedRAMP authorizations, core-agnostic billing orchestrators, and API-first fintech enablers. Strategic moves center on sequential multi-jurisdiction certification acquisition and embedded finance partnership structures.
Among hyperscale platforms, Amazon Web Services and Microsoft Azure occupy positions defined by public-sector authorization depth and financial services competency program investments. Temenos exemplifies the core-agnostic orchestration archetype, anchoring tier-one institution deployments where COBOL-based ledger architectures resist modernization. Google Cloud represents the multi-cloud arbitrage vector, capturing Singapore-based investment banks distributing workloads across regions.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Cloud |
| Temenos |
| Finacle |
| Fiserv |
| FIS |
| Mambu |
| Others |
Supply Flow & Price Mechanics
Eighteen-month FedRAMP authorization cycles anchor vendor pricing power, compressing margins for challengers while concentrating margin pools among hyperscale incumbents with pre-certified infrastructure stacks. Tier-one retail banks in Germany and India absorb these lead-time premiums to secure PCI DSS Level 1 compliance across hybrid deployments, forcing mid-tier vendors toward standardized SaaS tiers or exit.
Pricing Analysis
Three-tier pricing structure across enterprise, professional, and developer levels segments the market by certification depth and integration complexity. Enterprise tiers command premiums for FedRAMP authorization and ISO 27001 certification, while developer tiers sacrifice margin for seat expansion. Pricing pressure stems from Kubernetes-native entrants commoditizing raw metering precision. Credit unions in the United States exhibit highest price sensitivity, prioritizing predictable subscription charges over granular usage optimization.
Supply Chain Analysis
Container availability constraints across Asia-Pacific trade lanes inflate inbound logistics costs for specialized hardware appliances required in private cloud deployments. Hyperscale infrastructure concentrates in the United States, Germany, and India, drawing from semiconductor fabrication in Taiwan and enterprise storage manufacturing in Japan. Single-source vulnerability persists around custom ASICs for cryptographic acceleration. Distribution runs through direct enterprise sales teams with embedded solution architects, supplemented by systems integrator partnerships for legacy core banking integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors face substitution pressure from container-native billing engines that bypass traditional hypervisor licensing, eroding the middleware layer that once anchored enterprise contracts.
For Market Incumbents: Shield core relationships by deepening FedRAMP authorization breadth across additional agency categories, denying challengers public-sector beachheads. Accelerate ISO 27001 certification velocity to compress the 18-24 month multi-jurisdiction cycles that currently fragment product roadmaps. Vertical integration into Kubernetes sidecar metering agents displaces proxy-based architectures threatening margin pools.
For New Entrants and Emerging Players: Lead with carbon-aware billing modules targeting CSRD disclosure mandates in Europe, where incumbent hyperscalers lack native Scope 3 emissions attribution per transaction. Capture credit unions in the United States through simplified subscription tiers that sacrifice feature depth for procurement predictability. Partner with embedded finance platforms as white-label infrastructure providers, riding banking-as-a-service expansion without direct bank sales cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because sequential certification requirements across FedRAMP, PCI DSS, and national banking regulators create 18-24 month barriers that compound incumbent advantage. Target acquisition profiles center on core-agnostic orchestrators with proven COBOL integration layers, bridging decades-old ledger architectures. Monitor central bank digital currency pilot program announcements as inflection signals requiring entirely new billing primitives.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Acquisition | Sequential FedRAMP, PCI DSS Level 1, and BaFin approvals filter vendor eligibility for tier-one German retail banks. |
| Core-Agnostic Orchestration Development | API layers bridging COBOL-based ledger systems capture tier-one institutions resisting full modernization cycles. |
| Embedded Finance Partnership Structure | White-label billing engines for banking-as-a-service platforms expand addressable base beyond direct bank sales. |
| Carbon-Aware Billing Module Launch | Scope 3 emissions attribution per transaction satisfies CSRD disclosure requirements across European corporate treasury clients. |
| CBDC Settlement Primitive Development | Programmable money flow billing architectures capture pilot program demand from Singapore and India central banks. |
Methodological Framework
A spread of perspectives from cloud platform engineers, banking IT procurement officers, regulatory compliance leads, and core banking integration specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from hyperscale providers, RBI circulars on data localization, and EBA technical standards on PSD2 implementation. Bottom-up sizing of individual vendor deployments triangulated against top-down estimates from aggregate cloud infrastructure spending across financial services.
Segmentation dimensions modeled encompass deployment architecture, service type, end-user category, and technology layer across the projection horizon. Deployment splits capture public, hybrid, private, and multi-cloud configurations. Service type tracks the migration from subscription toward usage-based metering. End-user segmentation distinguishes retail, commercial, investment banking, and credit union requirements. CAGRs derive from regression analysis against real-time payment infrastructure buildout timelines and open banking API proliferation curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of PCI DSS and GDPR provisions would require recalibration. Forecasts reflect assumptions around continued central bank investment in real-time settlement rails and stable hyperscale capex trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Japan Data Analytics in Banking Market
Banking
Voice Banking Market
Banking
Performance Bank Guarantee Market
Banking
China Retail Banking System Market
Banking
Corporate Banking Market
Banking
Machine Learning in Banking Market
Banking
Video Banking Service Market
Banking
South Korea Data Analytics in Banking Market
Banking
Saudi Arabia Retail Banking Market
Banking
US Investment Banking Market
Banking
Intelligent Virtual Assistant (IVA) Based Banking Market
Banking
Banking Credit Analytics Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
UK Banking as a Service Market
Banking
Merchant Banking Services Market
Banking
Banking As a Service (BAAS) Market