
 Banking Tax Management Software Market | 2026-2036
Banking Tax Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Tax Management Software Market Outlook
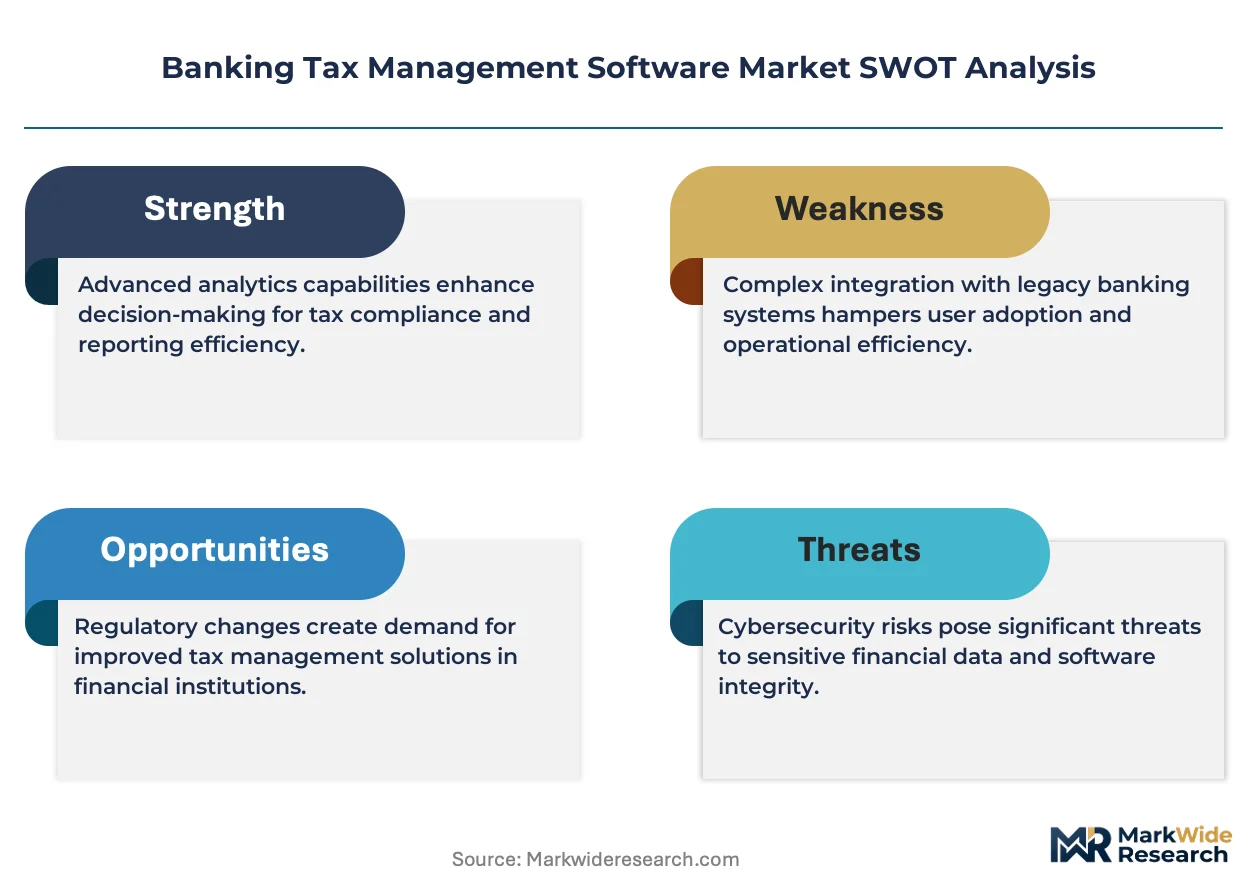
Platform licensing revenue from tax calculation engines is narrowing relative to recurring compliance subscription streams as banking clients prioritize continuous regulatory updates over perpetual licenses. Thomson Reuters sustains dominance through embedded regulatory content libraries spanning multiple jurisdictions. Wolters Kluwer differentiates via deep specialization in European VAT and withholding tax workflows. Avalara competes aggressively on cloud-native architecture for mid-tier financial institutions.
Banking tax management software comprises modular applications that automate tax determination, regulatory reporting, and audit documentation for financial institutions, typically integrating with core banking systems through APIs and supporting real-time transaction monitoring. Compliance Solutions and Reporting Tools occupy the largest margin pools as institutions face escalating filing obligations under FATCA, CRS, and OECD frameworks. Cloud-Based and SaaS deployment models represent the fastest-expanding segments as banks abandon on-premise infrastructure to reduce capital intensity and accelerate regulatory patch deployment.
The US Internal Revenue Service enforces FATCA compliance through penalty structures that compel foreign financial institutions to implement automated reporting systems, while the OECD coordinates CRS information exchange standards across signatory jurisdictions. The EU's DAC7 directive extends digital platform reporting requirements to payment processors and neo-banks, forcing software vendors to embed multi-jurisdiction rule engines. Stakeholders must evaluate whether to build proprietary tax logic or license regulatory content from established data providers as rule velocity accelerates.
Market Dynamics
Cloud-native tax engines are compressing deployment cycles from months to weeks, forcing incumbent vendors to rearchitect legacy stacks as mid-tier banks abandon perpetual licenses for subscription-based compliance automation.
Growth Catalysts
- FATCA Enforcement:The US Internal Revenue Service penalty structures compel foreign financial institutions to implement automated reporting systems, creating mandatory upgrade cycles across correspondent banking networks.
- Mid-Tier Banks:Regional commercial banks in Germany and the United Kingdom are consolidating fragmented tax workflows onto unified platforms to reduce manual reconciliation overhead.
- Real-Time APIs:Core banking system integration via open API architectures is accelerating regulatory patch deployment and enabling continuous transaction monitoring for withholding tax obligations.
Market Restraints
- Regulatory Content Licensing:Multi-jurisdiction rule engine maintenance requires expensive subscriptions to specialized data providers, compressing vendor margins.
- Cloud Concentration Risk:Hyperscaler infrastructure dependencies in the United States create single-point-of-failure exposure for European banks under data sovereignty requirements.
- Legacy System Entrenchment:Cobol-based core banking architectures at major money-center banks resist modular API integration, extending implementation timelines.
Strategic Opportunities
- DAC7 Compliance:The EU directive extending digital platform reporting to payment processors and neo-banks creates new module demand for automated information exchange workflows.
- Neo-Bank Segment:Digital-native challengers in the United Kingdom lack historical tax infrastructure, presenting greenfield deployment opportunities for cloud-first vendors.
- Embedded Analytics:Convergence of tax determination engines with regulatory risk dashboards is enabling premium pricing for predictive compliance offerings.
Industry Challenges
- Specialized Talent Scarcity:Software engineering teams with simultaneous expertise in international tax law and distributed systems architecture remain concentrated in London and New York financial technology clusters.
- Certification Lag:SOC 2 Type II and ISO 27001 audit cycles for cloud tax platforms extend 9-14 months, delaying go-live dates for regulated institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Tax Management Software Market |
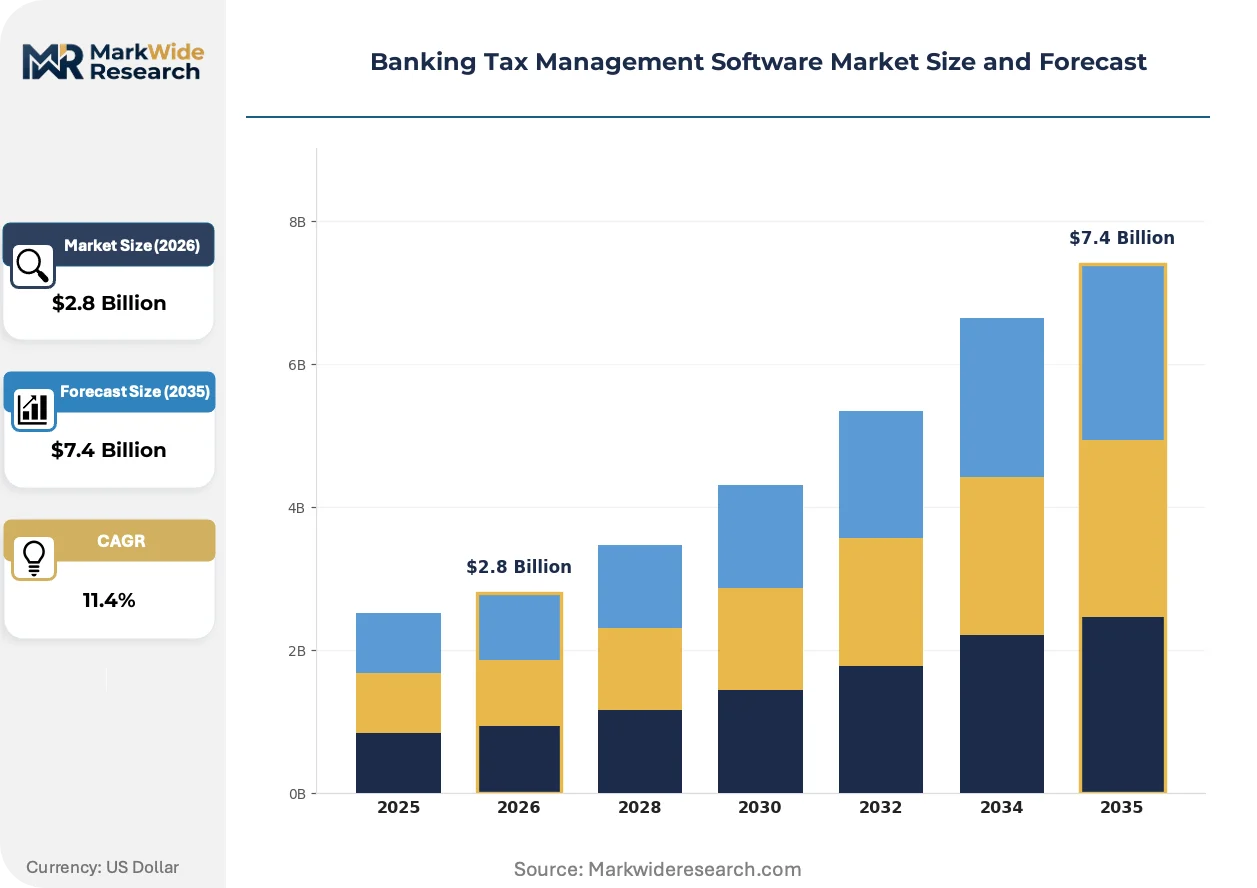
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compliance Solutions, Reporting Tools, Calculation Engines, Analytics Platforms Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Financial Institutions, Credit Unions, Investment Firms, Tax Advisory Services Feature: Audit Trails, Real-Time Reporting, Customizable Dashboards, Multi-Currency Support |
| Companies Covered | WEB GST, CosmoLex, Tipalti AP Automation, Zoho Corporation, FreshBooks, Patriot Software, Avalara, Thomson Reuters, Wolters Kluwer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Tax Management Software Market Strategic Shifts
Artificial intelligence is embedding directly into tax determination workflows, compressing the gap between transaction execution and regulatory classification while forcing vendors to compete on model interpretability rather than raw automation speed.
Explainable AI modules for tax classification are hybridizing deterministic rule engines with probabilistic natural language processing, enabling audit-trail documentation that satisfies both automated efficiency demands and regulatory transparency requirements. Tier-one institutions in the United States are piloting these hybrid architectures for complex cross-border interest withholding scenarios. The structural consequence is collapsing the traditional separation between pre-transaction tax planning and post-transaction reporting into continuous real-time compliance.
The OECD's mandatory disclosure regime for aggressive tax planning arrangements is compelling software vendors to embed automated risk-flagging algorithms directly into transaction processing pipelines. This regulatory architecture forces banks to document economic substance contemporaneously with deal execution rather than retrospectively. Investment banking divisions in London and Frankfurt are the most affected, reconfiguring front-office workflows around embedded compliance checkpoints.
Subscription-based procurement models for regulatory content are displacing perpetual license structures as banks prioritize continuous rule updates over static software ownership. Chief financial officers at mid-tier institutions are consolidating vendor relationships to reduce contract management overhead. This pattern is most visible in the United States and Germany, where procurement teams are bundling tax engines with broader regulatory technology suites.
Banking Tax Management Software Market Segmentation
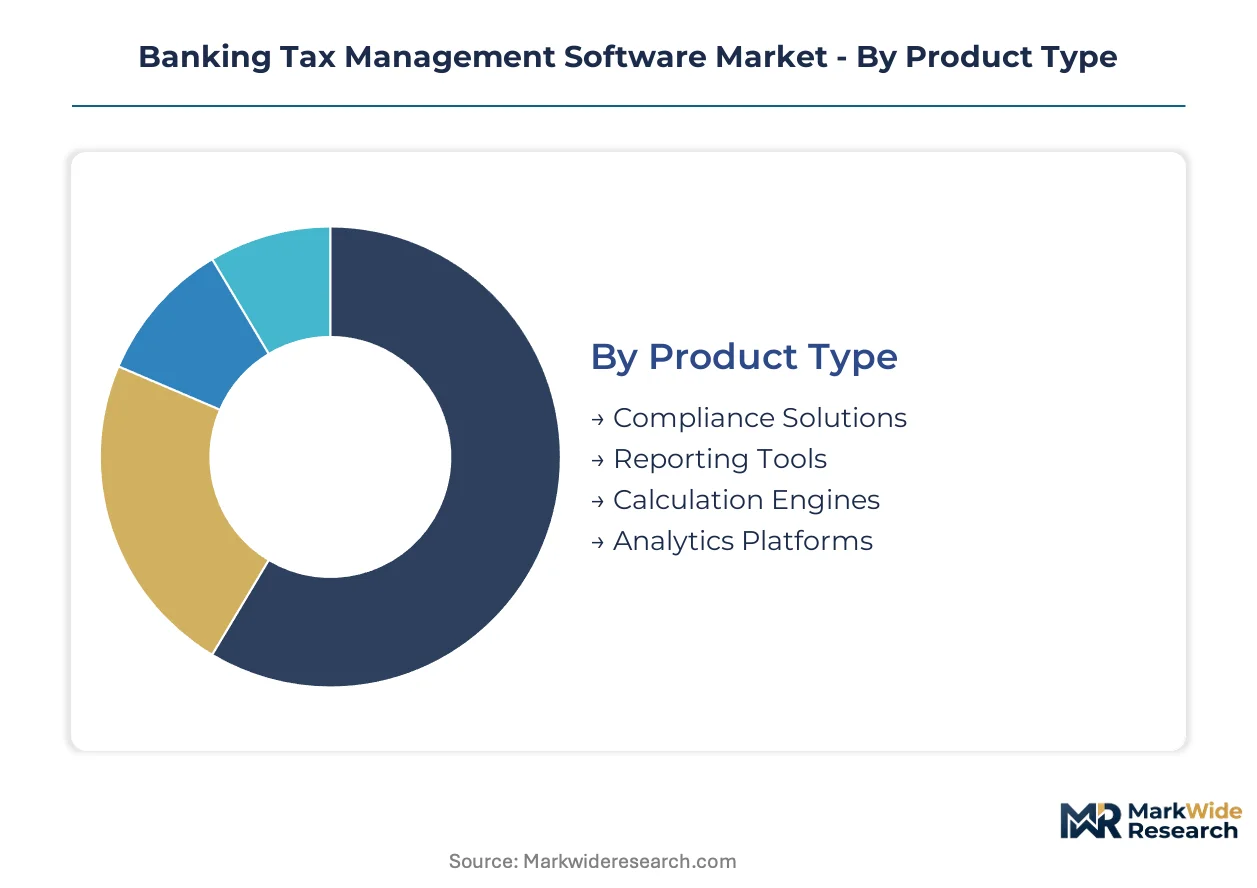
Banking tax management software segments by functional capability, infrastructure model, and user sophistication. Procurement patterns diverge sharply between regulatory compliance mandates and operational efficiency investments.
Product Type:
Compliance Solutions and Reporting Tools refresh on annual regulatory cycles, while Calculation Engines and Analytics Platforms turn over across multi-year core banking upgrades.
- Compliance Solutions:Modular applications automating FATCA, CRS, and OECD regulatory filing obligations through embedded rule engines. Demand concentrates among correspondent banks in the United States and Germany facing penalty exposure from revenue authorities. Continuous regulatory patch requirements sustain subscription pricing power.
- Reporting Tools:Automated documentation systems generating audit trails and information exchange filings for tax authorities. Investment banking divisions in London and Frankfurt drive adoption as the OECD's mandatory disclosure regime tightens contemporaneous documentation requirements. Integration with core banking APIs accelerates deployment velocity.
- Calculation Engines:Deterministic tax computation modules for withholding and transaction taxes.
- Analytics Platforms:Predictive compliance dashboards converging tax determination with risk monitoring.
Compliance Solutions anchors the volume base while Analytics Platforms gains share at the steepest rate.
Deployment:
Cloud-Based and SaaS models dominate procurement at mid-tier institutions, while On-Premise and Hybrid configurations persist at money-center banks with legacy Cobol architectures.
- Cloud-Based:Hyperscaler-hosted tax engines reducing capital intensity and compressing deployment cycles from months to weeks. Regional commercial banks in the United Kingdom prioritize this model to accelerate regulatory patch deployment. Data sovereignty requirements in Germany create multi-cloud sourcing complexity.
- SaaS:Subscription-delivered compliance automation with embedded regulatory content libraries. Neo-banks in London lack historical infrastructure and represent greenfield deployment opportunities. Chief financial officers bundle these contracts with broader regulatory technology suites.
- On-Premise:Perpetual-license installations at major institutions resisting modular API integration.
- Hybrid:Split architectures preserving sensitive calculation logic on-premise while leveraging cloud reporting layers.
On-Premise retains the largest installed base though Cloud-Based is expanding most quickly among new procurement decisions.
End User:
Financial Institutions and Investment Firms drive premium pricing, while Credit Unions and Tax Advisory Services concentrate in standardized mid-market tiers.
- Financial Institutions:Commercial banks with complex cross-border operations requiring multi-jurisdiction rule engines. United States and German institutions face the steepest compliance cost escalation under intensifying IRS and Bundesbank scrutiny. Procurement teams consolidate vendor relationships to reduce contract management overhead.
- Investment Firms:Asset managers and broker-dealers with real-time transaction monitoring requirements for withholding tax obligations. Front-office workflows in London and Frankfurt reconfigure around embedded compliance checkpoints. The OECD's aggressive tax planning disclosure regime affects these entities most directly.
- Credit Unions:Member-owned institutions with standardized domestic tax workflows.
- Tax Advisory Services:External compliance providers licensing platforms for client service delivery.
Financial Institutions command the deepest module penetration while Investment Firms show the steepest adoption acceleration.
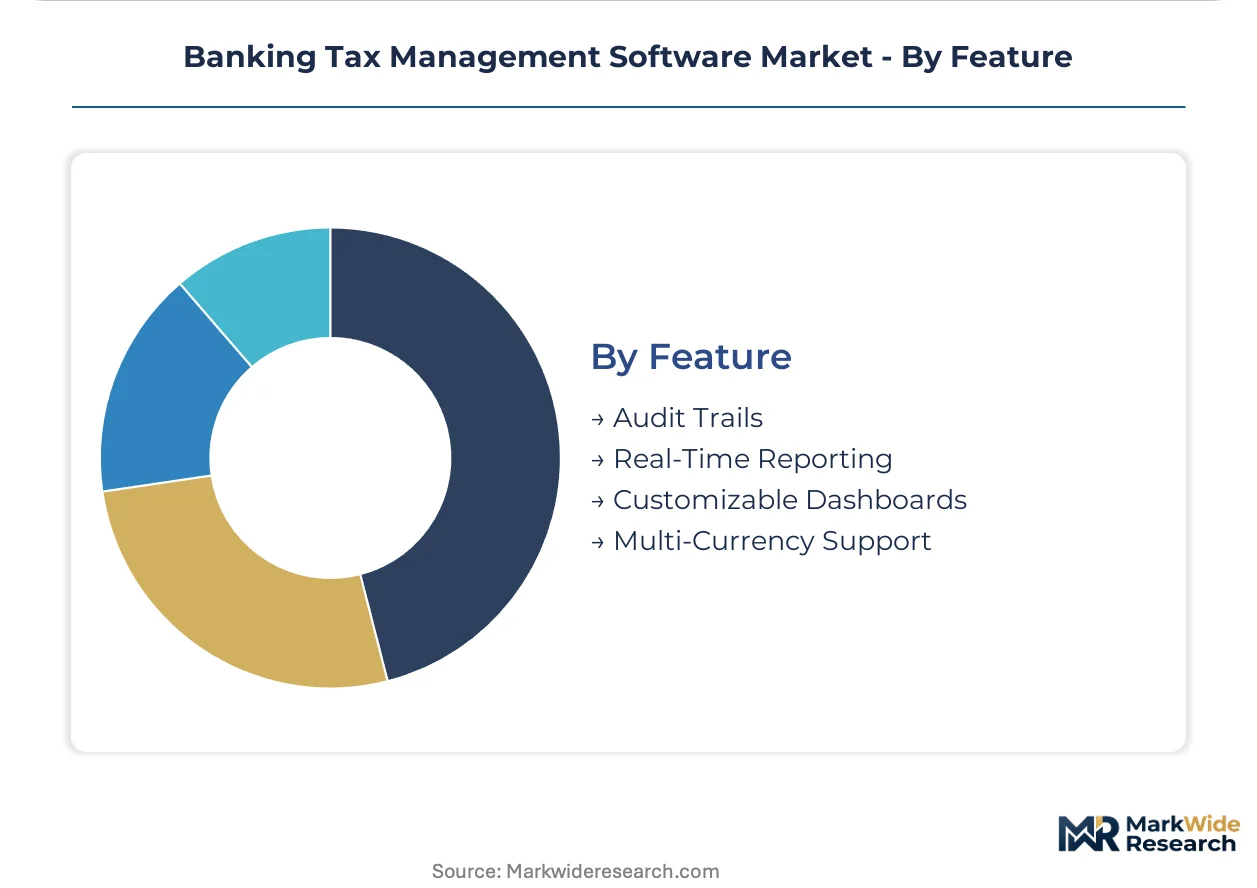
Feature:
Audit Trails and Real-Time Reporting function as baseline requirements, while Customizable Dashboards and Multi-Currency Support differentiate premium tiers.
- Audit Trails:Immutable transaction logs satisfying regulatory transparency and forensic examination requirements. Tier-one institutions in the United States pilot hybrid deterministic-probabilistic architectures for complex cross-border interest scenarios. Explainable AI modules satisfy both automation efficiency and audit documentation demands.
- Real-Time Reporting:Continuous transaction monitoring enabling contemporaneous compliance documentation. The structural consequence collapses traditional separation between pre-transaction planning and post-transaction reporting. Investment banking divisions demand this capability for OECD mandatory disclosure compliance.
- Customizable Dashboards:User-configurable regulatory risk visualization interfaces.
- Multi-Currency Support:Automated foreign exchange conversion for cross-border tax calculations.
Audit Trails represents table-stakes functionality while Real-Time Reporting climbs fastest as a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-tier banks in Germany and the United Kingdom demonstrate the lowest price elasticity, absorbing premium subscription costs for continuous regulatory updates, while credit unions in Canada and regional banks in India prioritize cost efficiency over advanced analytics capabilities.
United States
Commercial banks with complex cross-border operations drive demand for multi-jurisdiction rule engines. The Internal Revenue Service enforces FATCA compliance through penalty structures that compel foreign financial institutions to implement automated reporting systems. New York and Boston financial technology clusters concentrate specialized talent for hybrid deterministic-probabilistic tax architectures.
Germany
Regional commercial banks consolidate fragmented tax workflows onto unified platforms to reduce manual reconciliation overhead. The Bundesbank intensifies scrutiny of correspondent banking networks under EU regulatory frameworks. Frankfurt investment banking divisions reconfigure front-office workflows around embedded compliance checkpoints for OECD mandatory disclosure requirements.
United Kingdom
Neo-banks lack historical tax infrastructure, presenting greenfield deployment opportunities for cloud-first vendors. The Financial Conduct Authority coordinates with OECD information exchange standards across signatory jurisdictions. London's regulatory technology cluster anchors demand for real-time transaction monitoring and predictive compliance dashboards.
India
Mid-tier financial institutions prioritize cloud-native architectures to reduce capital intensity and accelerate regulatory patch deployment. The Reserve Bank of India mandates automated reporting systems for foreign financial institutions under bilateral tax treaties. Mumbai and Bangalore technology corridors concentrate software engineering teams with distributed systems expertise.
Japan
Major money-center banks resist modular API integration due to legacy system entrenchment, extending implementation timelines. The Ministry of Economy, Trade and Industry promotes open banking standards that accelerate core banking system integration. Tokyo financial institutions pilot explainable AI modules for complex cross-border interest withholding scenarios.
Banking Tax Management Software Market Competitive Environment
Established regulatory content providers and cloud-native specialists split the market between embedded compliance libraries and agile deployment architectures. The vendor base concentrates around three strategic archetypes: legacy data aggregators with jurisdictional breadth, European tax workflow specialists, and mid-market SaaS challengers. Consolidation pressures intensify as procurement teams bundle tax engines with broader regulatory technology suites. Dominant competitive moves include strategic partnerships for hyperscaler infrastructure and portfolio diversification into predictive analytics modules.
Within the regulatory content tier, Thomson Reuters and Wolters Kluwer occupy positions anchored by multi-jurisdiction rule libraries, while Avalara exemplifies the cloud-native challenger archetype targeting mid-tier institutions with subscription-delivered automation. These three companies represent the structural fault line between perpetual license maintenance and continuous compliance subscription models.
| Leading Market Players |
|---|
| WEB GST |
| CosmoLex |
| Tipalti AP Automation |
| Zoho Corporation |
| FreshBooks |
| Patriot Software |
| Avalara |
| Thomson Reuters |
| Wolters Kluwer |
| Others |
Value Chain & Pricing Dynamics
Regulatory content licensing from specialized data providers in the United States and Netherlands anchors margin pools downstream at vendor tiers, where subscription renewals for multi-jurisdiction rule engines now exceed perpetual license revenue. This upstream concentration of compliance intelligence directly shapes how procurement teams at mid-tier banks negotiate contract bundling.
Pricing Analysis
After-sales revenue from continuous regulatory content subscriptions drives lifetime value more than initial platform licenses. Three-tier pricing structure across premium, standard, and economy levels segments by jurisdictional complexity and API integration depth. Cost compression in the standard tier is intensifying because hyperscaler infrastructure commoditizes hosting while regulatory patch velocity demands specialist content. Neo-banks in London show the least price sensitivity, absorbing premium costs for embedded compliance automation, while credit unions in Canada prioritize economy-tier configurations.
Supply Chain Analysis
Export-control restrictions on AI-enabled transaction monitoring systems limit technology flows from the United States to certain jurisdictions. Software engineering talent concentrates in India, Poland, and Romania, where distributed systems expertise feeds development centers. The supply chain draws from hyperscaler infrastructure in the United States, Ireland, and Singapore, creating single-source vulnerability under EU data sovereignty mandates. Distribution runs through direct enterprise sales teams and systems integrators serving correspondent banking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as open API architectures enable modular substitution of tax engines within broader regulatory technology stacks, collapsing the traditional separation between compliance point solutions and core banking infrastructure.
For Market Incumbents: Entrench regulatory content libraries through exclusive data partnerships with national revenue authorities, insulating against cloud-native challengers. Deepen vertical integration into real-time transaction monitoring by acquiring specialized API gateway providers. The OECD's mandatory disclosure regime accelerates substitution risk for static rule engines lacking embedded risk-flagging capabilities. For New Entrants and Emerging Players: India's mid-tier financial institutions present the most penetrable geography, where Reserve Bank of India mandates for automated reporting outpace legacy vendor deployment capacity. Target greenfield neo-bank segments in Southeast Asia lacking historical tax infrastructure. Lead with cloud-native subscription models that compress implementation timelines from months to weeks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European tax workflow specialists holding deep Bundesbank and HMRC compliance relationships. Long-term viability hinges on convergence with predictive analytics modules rather than standalone calculation engines. Watch for inflection where procurement teams at major institutions consolidate tax engines with broader regulatory technology suites.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Content Partnership | Exclusive data agreements with IRS and OECD anchor multi-jurisdiction rule engine differentiation. |
| Cloud-Native Architecture Migration | Hyperscaler-hosted deployment compresses implementation timelines for mid-tier banking clients. |
| API Gateway Acquisition | Real-time core banking integration enables continuous transaction monitoring for withholding tax obligations. |
| Predictive Analytics Module Launch | Convergence of tax determination with risk dashboards commands premium subscription pricing. |
| Neo-Bank Geographic Expansion | Greenfield deployment opportunities in London and Southeast Asia bypass legacy system entrenchment. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with banking technology executives, regulatory compliance officers, procurement leads at mid-tier institutions, and systems integration specialists; and secondary validation through SEC filings, ECB supervisory reports, OECD regulatory framework publications, and hyperscaler capex disclosures. Bottom-up and top-down triangulation reconciled vendor revenue disclosures with institution-level procurement patterns.
Forecast inputs span deployment model transitions, organizational size tiers, vertical regulatory complexity, integration architecture patterns, and regional adoption velocities across the analysis window. CAGRs derive from regression analysis against historical regulatory mandate implementation cycles and banking IT spending elasticity. Specific inputs include FATCA penalty enforcement intensity and CRS signatory expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and cross-border capital flow volumes would shift the trajectory. Forecasts reflect documented assumptions about regulatory patch velocity and cloud migration willingness. Material shifts in OECD mandatory disclosure scope or EU data sovereignty enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Middle East and Africa Neobanking Market
Banking
Automated Teller Machine (ATM) Market
Banking
Global Banking Systems Software Market
Banking
Europe Neobanking Market
Banking
Banking Wearable Market
Banking
US Retail Banking Market
Banking
Onsite and Offsite Atms Market
Banking
Asia-Pacific Data Analytics in Banking Market
Banking
In Vitro Fertilization Banking Services Market
Banking
Africa Data Analytics in Banking Market
Banking
Internet of Things (IoT) in Banking Market
Banking
Commercial Banking Market
Banking
Middle East Data Analytics in Banking Market
Banking
Banking As a Service (BAAS) Market
Banking
Cloud-Based Core Banking Market
Banking
ATM Market