
 Milk Processing Systems Market | 2026-2036
Milk Processing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Processing Systems Market Analytics
The milk processing equipment sector is recalibrating around a widening split between premium aseptic processing lines and commodity-grade thermal systems. GEA Group leverages its centrifugal separation technology to anchor high-margin contracts with European dairy cooperatives. Tetra Pak differentiates through integrated packaging-to-processing platforms that control channel access in emerging markets. SPX FLOW competes on modular pasteurizer designs that sustain aftermarket service revenue across North American fluid milk plants.
Milk processing systems encompass equipment that transforms raw milk into shelf-stable or value-added dairy products through controlled thermal treatment, mechanical separation, or membrane-based fractionation, typically operating at temperatures between 72°C and 140°C depending on pasteurization protocol. These systems serve the primary commercial purpose of eliminating pathogens while preserving nutritional integrity and extending distribution reach for fluid milk, cheese, yogurt, and butter applications. Pasteurizers occupy the largest installed base across dairy operations globally, though membrane filtration technology leads growth as processors pursue protein concentration and extended shelf-life targets. Ultrasonic processing remains nascent but attracts R&D investment for its energy-efficient microbial reduction capabilities.
FDA Grade A Pasteurized Milk Ordinance and USDA dairy plant inspection standards shape equipment specifications and compliance costs for US-based processors, while EFSA hygiene criteria and EU MDR pressure vessel directives govern European system design and certification pathways. China's SAMR enforces GB standards for dairy machinery safety and energy labeling, creating tiered market access conditions for domestic versus imported equipment. Stakeholders must monitor evolving regulatory convergence around clean-in-place automation and carbon-footprint disclosure requirements as procurement criteria harden across major dairy-producing regions.
Market Dynamics
Membrane filtration technology is displacing conventional thermal processing across protein concentration and extended shelf-life applications, compressing equipment replacement cycles and reshaping supplier-customer contracting terms.
Growth Catalysts
- India's FSSAI cold-chain mandates:Cooperative dairies and private processors are modernizing infrastructure to comply with food safety guidelines, pulling demand for automated pasteurization systems into tier-2 and tier-3 dairy clusters.
- Ultrasonic processing R&D:Energy-efficient microbial reduction capabilities attract capital from processors seeking to cut thermal energy costs while maintaining pathogen elimination standards.
- China's MIIT energy-efficiency tightening:Domestic equipment upgrades accelerate as thermal processing machinery faces mandatory efficiency labeling and carbon-intensity benchmarks.
Market Restraints
- Stainless steel input volatility:Grade 316L and 304 price swings compress fabricator margins on custom pasteurizer vessels and membrane housings.
- European pressure vessel certification concentration:EU MDR compliance testing bottlenecks at notified bodies in Germany and Italy extend equipment approval timelines.
- Extended-shelf-life ESL packaging substitution:Aseptic carton and pouch formats reduce reliance on high-temperature processing hardware in fluid milk segments.
Strategic Opportunities
- India's cooperative dairy modernization:FSSAI-guided infrastructure investment creates whitespace for modular, skid-mounted pasteurizer systems in states with underpenetrated processing capacity.
- Clean-in-place automation convergence:Integration of IoT-enabled CIP monitoring with membrane filtration lines opens service-contract revenue streams for system integrators.
- USDA dairy plant inspection digitization:FDA Grade A PMO compliance documentation automation creates demand for processing equipment with embedded data-logging and traceability modules.
Industry Challenges
- ASME pressure vessel welder certification scarcity:Qualified orbital welding technicians for high-purity dairy equipment face acute shortages in North American fabrication hubs.
- Legacy PLC integration complexity:Retrofitting membrane filtration skids with 1990s-era plant control architectures demands custom protocol bridging and extends commissioning timelines.
- Clean-label certification timeline compression:Organic and grass-fed dairy processors require equipment validation documentation that exceeds standard 3-A Sanitary Standards audit windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Processing Systems Market |
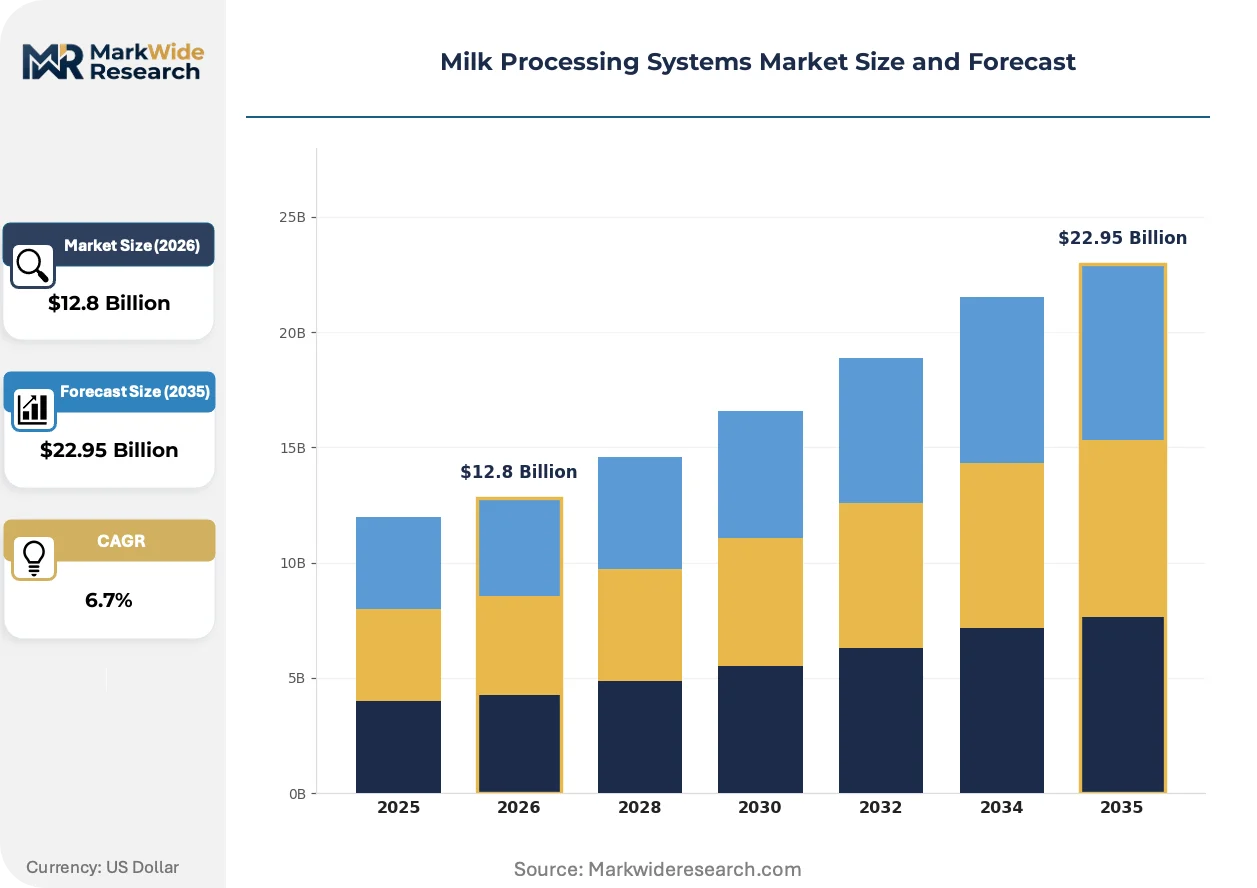
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pasteurizers, Homogenizers, Separators, Cream Chargers End User: Dairies, Food Manufacturers, Retail Chains, Food Service Technology: Thermal, Membrane Filtration, Centrifugal, Ultrasonic Application: Fluid Milk, Cheese, Yogurt, Butter |
| Companies Covered | GEA Group, Tetra Pak, Alfa Laval, SPX FLOW, DeLaval, IDMC Limited, Krones AG, JBT Corporation, Feldmeier Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Processing Systems Market Evolving Landscape
Processing hardware is reconfiguring around energy accountability and protein valorization, with thermal efficiency metrics and fractionation yield becoming primary procurement criteria alongside pathogen elimination performance.
Membrane filtration is converging with electrodialysis and microfiltration stages to enable native whey protein isolation without denaturation. European whey processors and North American Greek yogurt manufacturers are adopting these hybrid lines to capture premium protein ingredient markets. The technology is converging with traditional separation equipment, forcing centrifuge suppliers to defend position through integrated service contracts rather than hardware differentiation alone.
China's SAMR enforcement of GB standards for dairy machinery safety and energy labeling is creating tiered market access conditions that favor domestic equipment vendors with established certification pathways. Imported systems face extended compliance verification timelines and localized testing requirements. European and North American suppliers are responding by establishing joint-venture assembly operations within Chinese industrial zones to bypass import certification friction.
Fluid milk processors are unbundling after-sales service contracts from initial equipment purchases, treating maintenance and spare parts as separately negotiated spend categories. Large North American dairy cooperatives now run competitive tenders for multi-year service agreements independent of hardware procurement. This behavior is most visible in California and Wisconsin fluid milk plants, where cooperative procurement committees prioritize total cost of ownership transparency over bundled supplier relationships.
Milk Processing Systems Market Segmentation
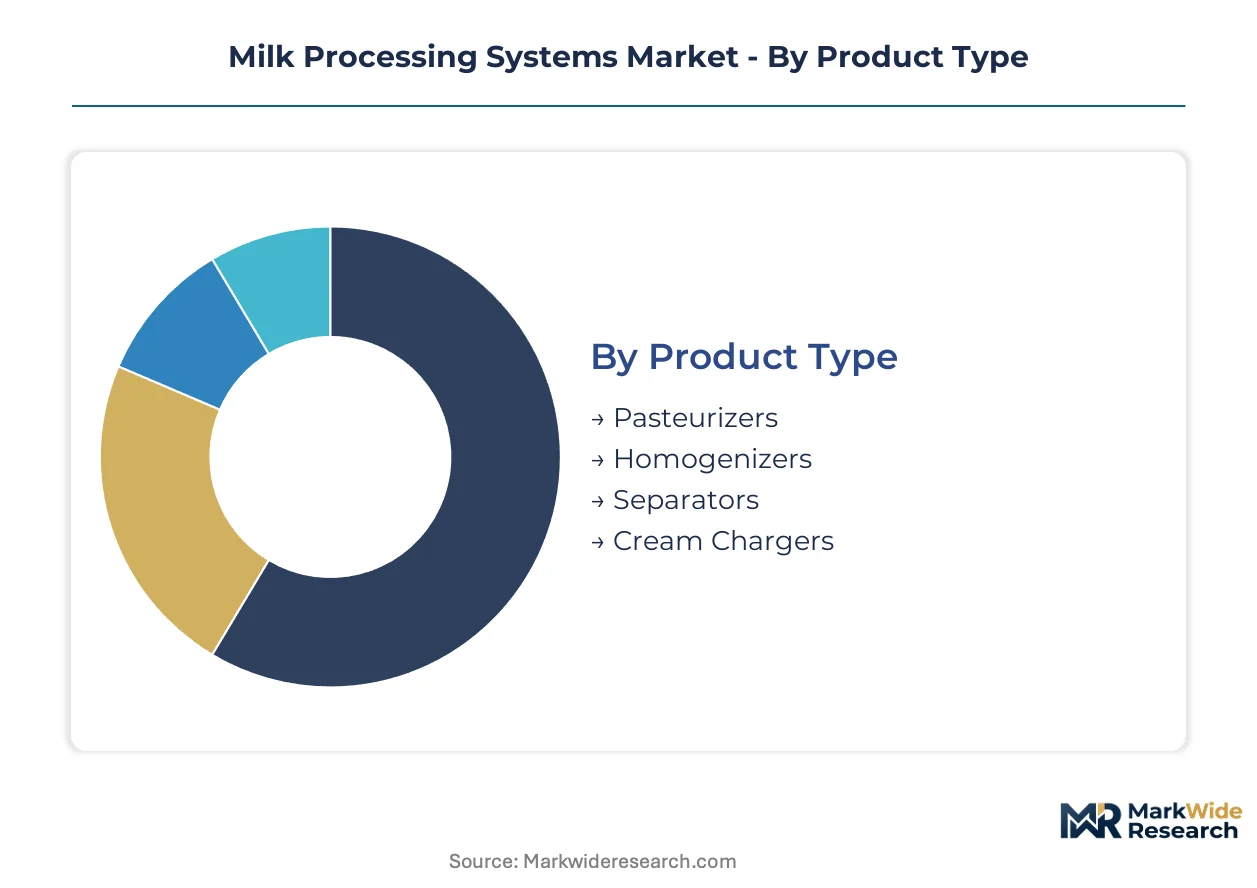
Milk processing equipment procurement decisions hinge on thermal efficiency mandates, protein valorization targets, and regulatory compliance pathways that vary sharply across dairy product categories and operational scales.
Product Type:
Equipment selection tracks capacity requirements and automation depth, with large cooperatives prioritizing integrated lines while regional processors favor modular skids.
- Pasteurizers:Thermal treatment systems operating between 72°C and 140°C eliminate pathogens while preserving nutritional integrity. Dairies in India and the United States are scaling automated pasteurization lines to meet FSSAI and FDA Grade A standards respectively, pulling demand into tier-2 processing clusters.
- Homogenizers:High-pressure mechanical systems disrupt fat globule membranes to prevent cream separation and extend shelf stability. European dairy cooperatives anchor high-margin contracts for aseptic homogenizer integration with downstream packaging platforms.
- Separators:Centrifugal clarification removes solids and standardizes fat content across fluid milk streams.
- Cream Chargers:Nitrous oxide injection systems enable rapid whipping for food service and retail dessert applications.
Pasteurizers lead on scale; membrane-integrated thermal systems lead on momentum.
End User:
Procurement authority concentrates with entities controlling cold-chain infrastructure and direct retail channel access.
- Dairies:Primary processors operating collection-to-packaging workflows across cooperative and private ownership structures. India's cooperative dairies are modernizing under FSSAI cold-chain mandates, creating whitespace for skid-mounted pasteurizer deployment in underpenetrated states.
- Food Manufacturers:Industrial ingredient producers fractionating milk proteins for sports nutrition and infant formula. North American Greek yogurt manufacturers are adopting hybrid membrane-electrodialysis lines to capture premium whey protein isolate markets.
- Retail Chains:Private-label processors seeking extended-shelf-life fluid milk for direct store distribution.
- Food Service:Dispensing and preparation equipment operators prioritizing compact footprint and rapid batch turnaround.
Dairies dominate installed base; food manufacturers are climbing the fastest on equipment upgrade intensity.
Technology:
Capital allocation is bifurcating between proven thermal systems and emerging fractionation platforms that reduce energy intensity.
- Thermal:Conventional pasteurization and UHT treatment systems remain the largest installed base. China's MIIT energy-efficiency tightening is accelerating domestic upgrades as thermal processing machinery faces mandatory efficiency labeling and carbon-intensity benchmarks.
- Membrane Filtration:Microfiltration, ultrafiltration, and reverse osmosis stages concentrate proteins and extend shelf life without thermal denaturation. European whey processors are converging membrane technology with electrodialysis to enable native protein isolation.
- Centrifugal:Mechanical separation technology for cream standardization and clarification duties.
- Ultrasonic:Energy-efficient microbial reduction through cavitation effects attracts R&D investment from processors seeking to cut thermal energy costs.
Thermal systems anchor revenue; membrane filtration gains share fastest on replacement cycle compression.
Application:
Product-specific processing requirements dictate equipment configuration, with protein concentration applications driving technology substitution.
- Fluid Milk:Bulk pasteurization and homogenization for direct consumption and retail distribution. Aseptic carton and pouch formats are reducing reliance on high-temperature processing hardware in this segment.
- Cheese:Curd formation, whey separation, and block forming require precise temperature and pH control. European and North American cheese processors are unbundling after-sales service contracts from initial equipment purchases.
- Yogurt:Fermentation vessel systems with integrated cooling and inoculation capabilities.
- Butter:Churning and working equipment for fat crystallization and moisture dispersion control.
Fluid milk leads on unit volume; cheese commands the steepest expansion trajectory on protein valorization investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled welding technicians and dairy equipment engineers concentrate in Wisconsin, Bavaria, and Gujarat, anchoring fabrication capacity close to major milk shed regions. These talent clusters shape where thermal processing systems are built, certified, and serviced.
United States
Dairy cooperatives in California and Wisconsin are unbundling service contracts from hardware purchases, running competitive tenders for multi-year maintenance agreements. FDA Grade A Pasteurized Milk Ordinance compliance drives demand for embedded data-logging modules in pasteurization lines. Fabrication hubs in the Upper Midwest face acute shortages of ASME-certified orbital welders for high-purity dairy vessels.
Germany
European dairy cooperatives anchor high-margin contracts for integrated separation and packaging platforms. EU MDR pressure vessel directives create compliance testing bottlenecks at notified bodies in Munich and Stuttgart, extending equipment approval timelines. The Bavarian industrial corridor hosts centrifugal technology specialists serving whey protein fractionation demand.
China
Domestic equipment vendors with established GB standards certification pathways capture share as MIIT energy-efficiency mandates tighten. SAMR enforcement of dairy machinery safety and energy labeling creates tiered market access favoring localized assembly operations. Yangtze River Delta joint-venture facilities bypass import certification friction for European and North American suppliers.
India
Cooperative dairies in Gujarat and Maharashtra modernize cold-chain infrastructure under FSSAI guidelines, pulling demand for skid-mounted pasteurizer systems into underpenetrated tier-2 and tier-3 dairy clusters. State-level dairy development boards channel subsidy flows toward automated processing capacity. The Anand milk shed anchors equipment deployment patterns across western India.
Netherlands
Whey processors in the Randstad region adopt hybrid membrane-electrodialysis lines for native protein isolation without thermal denaturation. EFSA hygiene criteria govern system design specifications for export-oriented dairy ingredient production. Eindhoven-area system integrators specialize in clean-in-place automation convergence with filtration lines.
Milk Processing Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the milk processing equipment sector. Full-system integrators with captive fabrication capacity face margin pressure from modular skid specialists outsourcing vessel production. Three archetypes dominate: integrated packaging-to-processing platforms, centrifugal separation technology anchors, and modular pasteurizer designers sustaining aftermarket revenue. Consolidation through joint-venture assembly operations and technology licensing agreements characterizes competitive moves in regulated Asian markets.
Within the integrated platform tier, Tetra Pak and GEA Group occupy positions controlling channel access in emerging markets and European cooperative supply chains respectively. SPX FLOW exemplifies the modular design archetype competing on aftermarket service revenue transparency. These three entities anchor competitive dynamics across thermal processing, membrane filtration, and separation technology segments where procurement committees now prioritize total cost of ownership visibility over bundled supplier relationships.
| Leading Market Players |
|---|
| GEA Group |
| Tetra Pak |
| Alfa Laval |
| SPX FLOW |
| DeLaval |
| IDMC Limited |
| Krones AG |
| JBT Corporation |
| Feldmeier Equipment |
| Others |
Value Network & Pricing Analysis
Grade 316L and 304 stainless steel price volatility propagates through three distinct equipment tiers, compressing fabricator margins on custom pasteurizer vessels while forcing buyers toward modular skid systems with standardized membrane housings.
Pricing Analysis
Bundled after-sales service contracts are unbundling from initial equipment purchases across North American fluid milk cooperatives, creating separately negotiated spend categories for maintenance and spare parts. Price differentiation hinges on certification grade—FDA Grade A PMO compliance versus commodity thermal standards—and volume scale, with large cooperatives extracting transparency on total cost of ownership. Pricing pressure stems from stainless steel input volatility squeezing custom vessel fabricators. Regional processors in tier-2 dairy clusters exhibit highest price sensitivity; European whey processors pursuing native protein isolation show lowest sensitivity due to premium ingredient margins.
Supply Chain Analysis
Direct-to-dairy channels handle cooperative procurement in Wisconsin and California, while indirect distribution through Yangtze River Delta joint-ventures serves Chinese domestic upgrades. Geographic supply concentrates in Germany, China, and India, with Bavarian centrifuge specialists, Yangtze Delta assembly operations, and Gujarat fabrication hubs anchoring regional capacity. Raw material dependencies draw from Grade 316L stainless steel, nitrile and EPDM seals, and high-purity orbital welding gases. Single-source vulnerability around ASME-certified welder scarcity in North American fabrication hubs poses structural risk. Distribution runs through equipment integrators for large cooperatives and regional distributors for modular skid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as protein valorization investment in whey and Greek yogurt processing sustains replacement cycle compression across thermal and membrane equipment categories.
For Market Incumbents: Extend service contract revenue transparency to defend against unbundling pressure from cooperative procurement committees in California and Wisconsin. Deepen backward integration into membrane module production to capture margin from hybrid electrodialysis-filtration lines. Certification investment in FSSAI-compliant skid designs anchors position in India's tier-2 dairy cluster expansion.
For New Entrants and Emerging Players: Launch via modular pasteurizer skids targeting underpenetrated cooperative dairies in Maharashtra and Gujarat under FSSAI modernization subsidies. White-space exists in IoT-enabled clean-in-place automation for membrane filtration lines, with system integrator partnerships as the primary go-to-market angle. Ultrasonic processing R&D partnerships with energy-conscious processors offer second entry path.
For Investors and Strategic Acquirers: Consolidation pressure builds where orbital welding technician scarcity constrains fabrication capacity expansion in North American hubs. The market supports long-term viability framing around captive aftermarket service revenue streams and recurring membrane replacement cycles. Acquisition targets should display integrated CIP automation capabilities or established GB standards certification pathways for Chinese market access. Watch MIIT energy-efficiency mandate enforcement intensity as inflection indicator for domestic equipment upgrade velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint-Venture Assembly Operations | Yangtze River Delta facilities bypass SAMR import certification friction for European suppliers. |
| Membrane-Electrodialysis Integration | Hybrid lines enable native whey protein isolation for North American Greek yogurt manufacturers. |
| Clean-in-Place Automation Convergence | IoT-enabled CIP monitoring opens multi-year service contracts with European whey processors. |
| Skid-Mounted Pasteurizer Deployment | Modular systems penetrate underpenetrated tier-2 dairy clusters under FSSAI guidelines. |
| Embedded Data-Logging Modules | FDA Grade A PMO compliance documentation automation anchors California and Wisconsin sales. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with dairy plant engineers, cooperative procurement committees, membrane technology R&D directors, and aftermarket service heads with secondary validation. Primary sources included equipment specification databases, FDA Grade A PMO enforcement records, FSSAI dairy infrastructure subsidy filings, and MIIT energy-efficiency labeling registries. Customs data on stainless steel vessel imports and SEC filings from listed equipment manufacturers anchored trade flow analysis. Bottom-up unit economics from pasteurizer and membrane system deployments triangulated against top-down market sizing from dairy processing capacity expansion announcements.
Comparable historical periods spanning equipment replacement cycles and regulatory implementation phases anchored the projection horizon across the analysis window. Segmentation dimensions modeled include product type, end user category, technology platform, and application with regional regulatory cluster overlays. CAGRs derived from equipment shipment trends and capacity utilization trajectories in major milk shed regions. Industry-specific forecast inputs incorporated FSSAI cold-chain mandate implementation schedules and MIIT carbon-intensity benchmark enforcement pathways.
Forecast precision tightens around the base case; tail outcomes carry wider variance under stainless steel price volatility extremes and ASME welder certification bottlenecks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Processing Machinery
Commercial Cheese Shredder Market
Dairy Processing Machinery
Cream Separator Market
Dairy Processing Machinery
Cheese Liners Market
Dairy Processing Machinery
Yogurt Cup Market
Dairy Processing Machinery
Milk Pasteurization Machines Market
Dairy Processing Machinery
Dairy Products Membrane Filtration Equipment Market
Dairy Processing Machinery
Milk Chiller Market
Dairy Processing Machinery
Electric Milkshake Machine Market
Dairy Processing Machinery
Milk Clarifier Market
Dairy Processing Machinery
Modified Milk Powder Market
Dairy Processing Machinery
Dairy Filtration Systems Market
Dairy Processing Machinery
Commercial Milkshake Machine Market
Dairy Processing Machinery
Cheese Cutting Machine Market
Dairy Processing Machinery
Ice Cream Making Machine Market
Dairy Processing Machinery
Dairy Machines Market
Dairy Processing Machinery
Multi-Spindle Milkshake Machine Market