
 Biometric in the Automotive Market | 2026-2036
Biometric in the Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric in the Automotive Market Outlook
Automotive-grade biometric certification is redrawing competitive boundaries in vehicle identity systems. Continental AG leverages its Tier-1 supplier position to anchor fingerprint-enabled steering wheel modules across European OEM platforms. Synaptics Incorporated specializes in capacitive touch sensors that integrate payment authentication with physical access control. Fujitsu Limited competes through iris recognition systems designed for low-light cabin environments.
Biometric in the automotive context encompasses fingerprint, facial, voice, and iris recognition technologies engineered to ISO 26262 functional safety standards for driver identification and cabin access. These systems authenticate occupants through unique biological markers, enabling personalized seat positioning, climate settings, and secure ignition authorization. Fingerprint recognition dominates current OEM installations due to mature sensor costs and proven durability against temperature cycling. Facial recognition captures the fastest expansion trajectory as convolutional neural networks enable real-time driver fatigue detection. Voice recognition maintains stable aftermarket demand where retrofit infotainment integration avoids hardware redesign.
NHTSA guidelines on driver distraction monitoring and the EU's General Safety Regulation mandate attention-tracking capabilities that directly stimulate iris and facial biometric adoption. ECE R79 compliance requirements in Europe and Japan's METI road safety technology roadmap create parallel certification pathways that shape sensor specification thresholds. Stakeholders must monitor divergence between privacy-focused GDPR biometric consent frameworks in Europe and sector-specific automotive exemptions emerging in other jurisdictions.
Market Dynamics
Regulatory mandates for driver monitoring systems are compressing OEM decision timelines and forcing Tier-1 suppliers to accelerate biometric sensor roadmaps. ECE R79 compliance deadlines and NHTSA guidelines are eliminating the option for gradual feature rollout.
Growth Catalysts
- EU General Safety Regulation:Mandatory driver distraction monitoring provisions require iris and facial recognition integration in new vehicle platforms sold across member states.
- Convolutional neural networks:Real-time fatigue detection algorithms enable predictive cabin personalization that automakers bundle with luxury trim packages.
- Germany:Premium OEM clusters around Stuttgart and Munich source biometric steering wheel modules at volumes that validate sensor durability testing investments.
Market Restraints
- Automotive-grade silicon shortages:Capacitive fingerprint sensor foundry capacity concentrates in Taiwan, creating allocation bottlenecks for steering wheel module production.
- GDPR biometric consent frameworks:European privacy requirements impose friction on cross-border data flows for cloud-connected facial recognition systems.
- Optical sensor degradation:Cabin temperature cycling between minus 40 and 85 degrees Celsius degrades iris camera lens coatings faster than OEM warranty periods.
Strategic Opportunities
- India:Domestic PLI scheme incentives for automotive electronics manufacturing attract biometric module assembly investments serving ASEAN export markets.
- Voice-biometric payment authentication:Integration of speaker recognition with in-vehicle commerce platforms opens subscription revenue streams for OEMs.
- ISO 26262 functional safety certification:Early compliance with ASIL-D standards for iris-based attention tracking creates supplier lock-in with European luxury brands.
Industry Challenges
- Embedded systems cybersecurity:Hardening biometric data pipelines against side-channel attacks requires hardware security module integration that extends development cycles.
- Multi-sensor fusion calibration:Synchronizing fingerprint, facial, and iris recognition thresholds across varying cabin lighting conditions demands specialized optical engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric in the Automotive Market |
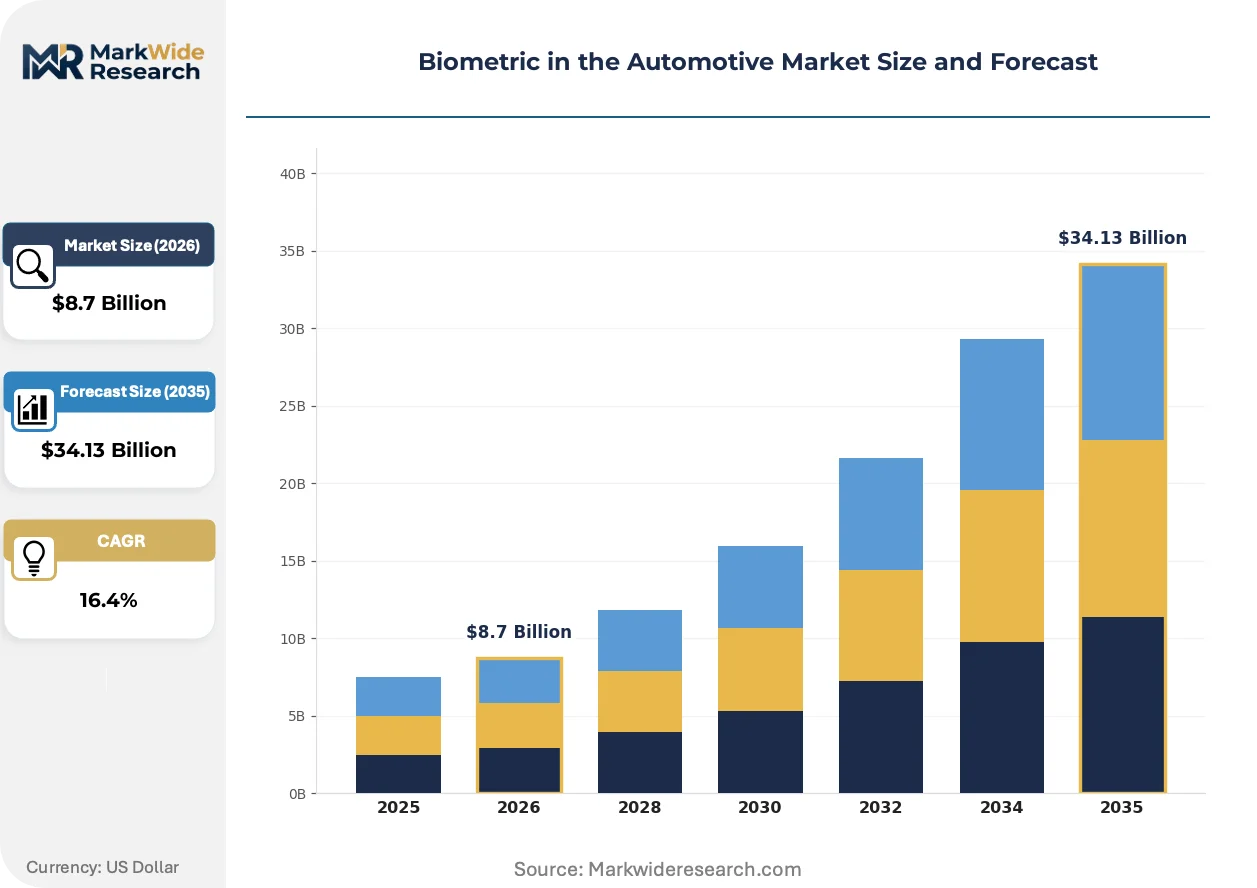
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Recognition, Facial Recognition, Voice Recognition, Iris Recognition Application: Access Control, Driver Monitoring, Security Systems, Payment Processing Technology: Biometric Sensors, Machine Learning, Artificial Intelligence, Edge Computing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators |
| Companies Covered | Continental AG, Synaptics Incorporated, Fujitsu Limited, Gentex Corporation, NEC Corporation, Fingerprint Cards AB, Methode Electronics, VOXX International Corporation, Cerence Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric in the Automotive Market Strategic Shifts
Convolutional neural networks and edge AI processors are collapsing the latency gap between biometric capture and vehicle system response. This acceleration enables real-time authentication loops that were previously confined to static cabin entry scenarios.
Capacitive fingerprint sensors with liveness detection are displacing pressure-based alternatives in steering wheel modules. European OEMs specify these for payment authentication integration. The shift compresses the addressable market for resistive sensor suppliers and rewards semiconductor foundries with automotive qualification.
ECE R79 driver monitoring mandates in Europe and parallel METI technology roadmaps in Japan are forcing iris camera integration into A-pillar and steering column assemblies. Tier-1 suppliers must redesign interior trim tooling to accommodate infrared illumination modules. German KBA type approval processes are setting the de facto certification benchmark that Japanese and South Korean regulators reference.
Fleet operators in the United States are unbundling biometric personalization from vehicle purchase, preferring subscription-based driver profile portability across leased assets. This procurement pattern shifts revenue recognition for OEMs from upfront hardware margin to recurring software fees. Rental car channels in Florida and Arizona are piloting facial recognition for frictionless handoff protocols.
Biometric in the Automotive Market Segmentation
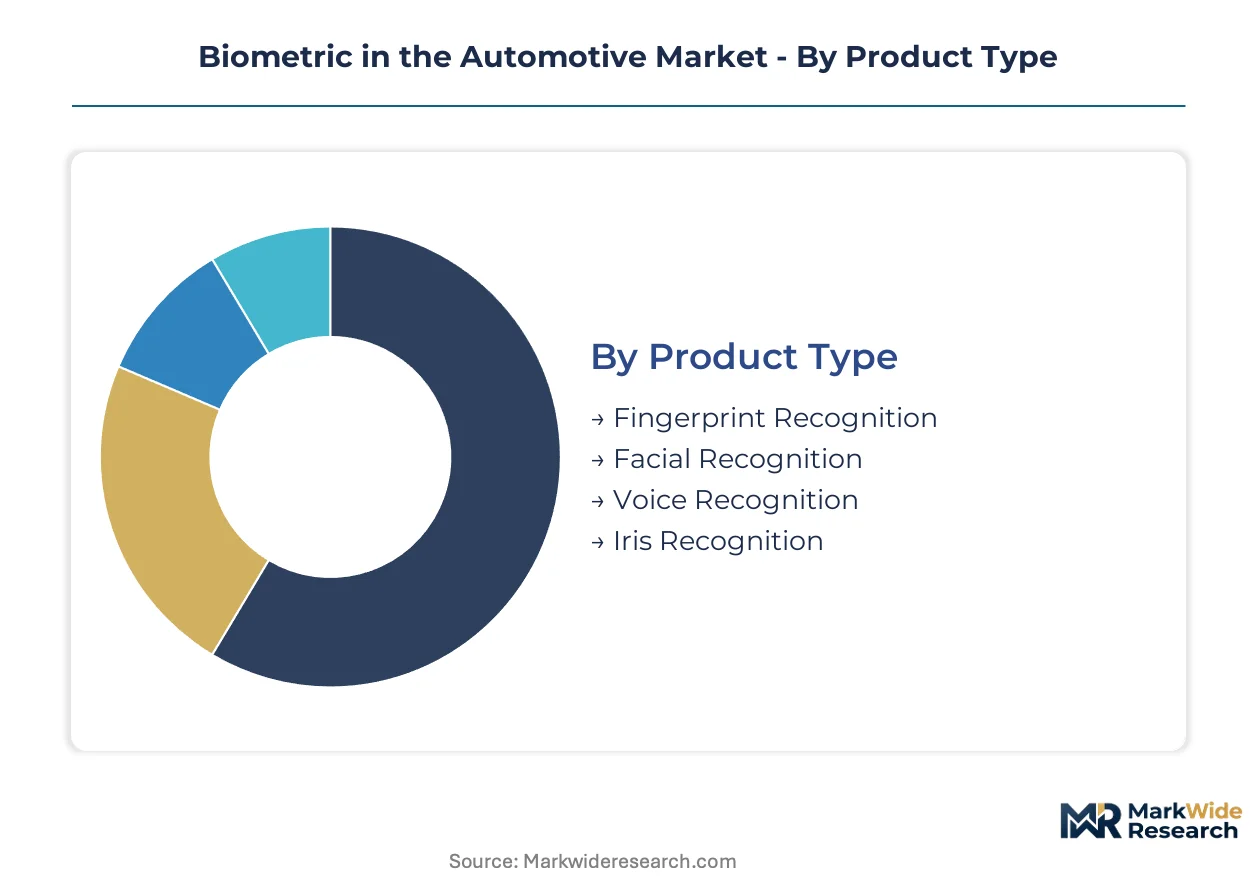
Automotive biometric segmentation reveals divergent margin profiles across hardware, software, and integration layers. Tier-1 suppliers capture value through sensor-module bundling, while AI algorithm providers monetize per-vehicle licensing. Understanding where profit pools concentrate enables precise positioning across the value chain.
Product Type:
Margin pools concentrate in facial and iris recognition where ECE R79 compliance mandates justify premium module pricing.
- Facial Recognition:Convolutional neural networks process driver identity and fatigue states through cabin-mounted infrared cameras. German premium OEMs in Stuttgart and Munich source these modules for personalized cockpit settings, driven by EU General Safety Regulation distraction-monitoring requirements. The dominant share belongs to Fingerprint Recognition, while Facial Recognition is closing the gap fastest.
- Fingerprint Recognition:Capacitive sensors embedded in steering wheels authenticate ignition and payment authorization. Taiwan foundry capacity constraints currently limit supply allocation for European steering wheel module production.
- Voice Recognition:Speaker identification algorithms enable hands-free cabin control and commerce authentication. Aftermarket retrofit demand in the United States avoids OEM hardware redesign cycles.
- Iris Recognition:Infrared cameras track pupil dilation for attention monitoring in low-light cabin conditions. METI road safety technology roadmaps in Japan parallel European ECE R79 adoption timelines.
Fingerprint sensors maintain volume leadership from mature automotive qualification, though facial systems are expanding most quickly through regulatory mandates.
Application:
Application segmentation tracks how biometric value migrates from security toward predictive personalization and commerce.
- Driver Monitoring:Real-time fatigue and distraction detection systems integrate iris and facial biometrics for ECE R79 compliance. German KBA type approval processes set certification benchmarks referenced by Japanese and South Korean regulators.
- Access Control:Frictionless vehicle entry replaces key fobs through facial or fingerprint authentication. Fleet operators in Florida and Arizona pilot facial recognition for rental handoff protocols.
- Security Systems:Biometric immobilizers prevent unauthorized ignition through multi-factor authentication. Aftermarket channels in the United States serve vehicle owners seeking retrofit theft protection.
- Payment Processing:In-vehicle commerce platforms authenticate transactions through voice or fingerprint verification. OEMs pursue subscription revenue streams decoupled from upfront hardware margins.
Driver Monitoring commands the steepest expansion trajectory as regulatory deadlines compress OEM integration timelines.
Technology:
Technology layers separate commodity sensor hardware from differentiated AI and edge processing capabilities.
- Artificial Intelligence:Convolutional neural networks and deep learning models enable real-time biometric pattern recognition with predictive accuracy. Cloud-connected training pipelines face GDPR biometric consent friction in Europe.
- Edge Computing:On-vehicle processors execute authentication loops without latency-prone cloud dependency. ASIL-D functional safety certification for iris-based attention tracking creates supplier lock-in with luxury brands.
- Biometric Sensors:Optical, capacitive, and infrared hardware captures biological markers across varying cabin conditions. Temperature cycling between minus 40 and 85 degrees Celsius degrades optical lens coatings faster than warranty periods.
- Machine Learning:Adaptive algorithms refine recognition accuracy through driver-specific behavioral patterning. Embedded systems cybersecurity requirements extend development cycles for hardened data pipelines.
Artificial Intelligence layers capture disproportionate margin expansion as software licensing displaces pure hardware monetization.
End User:
End user segmentation reflects divergent procurement power and technical specification authority across the supply chain.
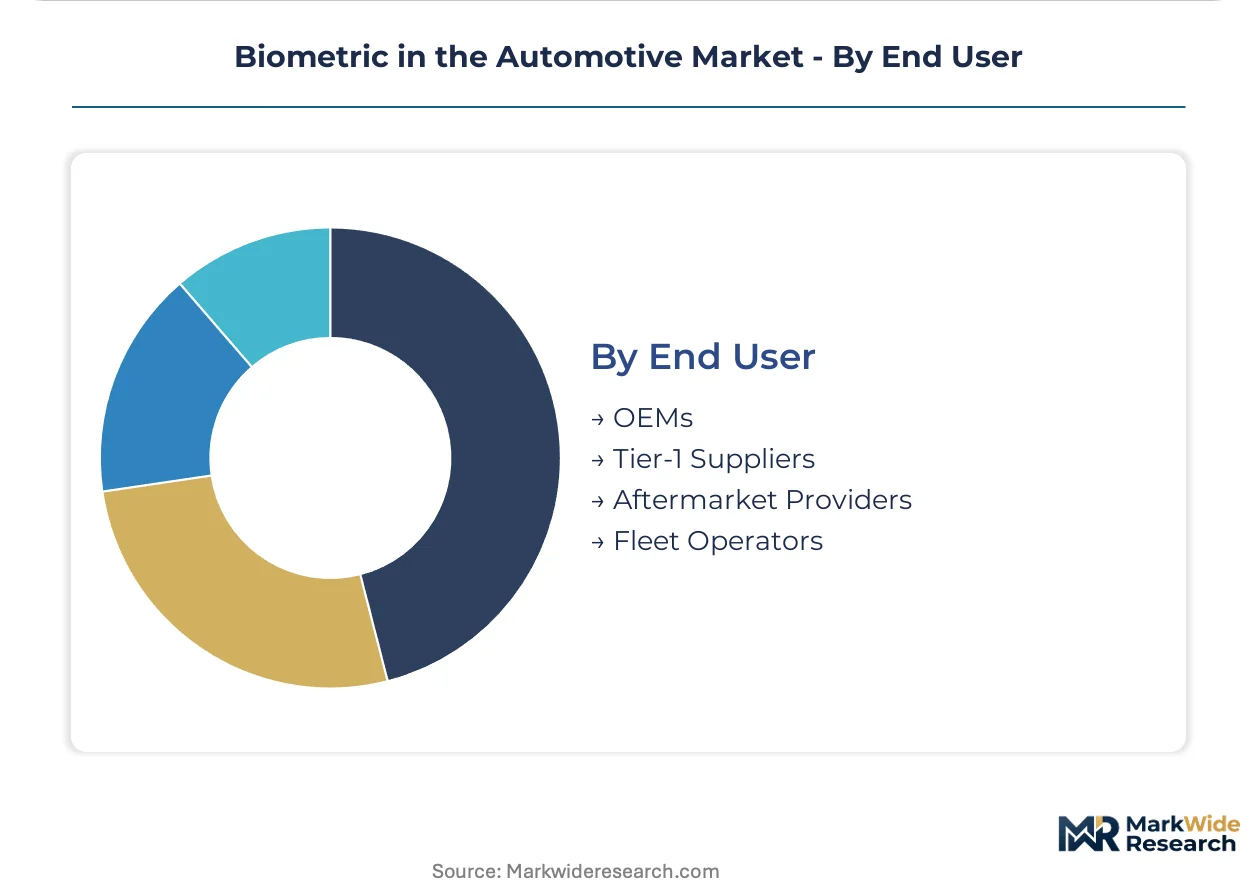
- OEMs:Vehicle manufacturers specify biometric integration requirements and validate Tier-1 module designs. Premium OEM clusters in Germany, Japan, and the United States drive sensor durability testing investments through volume commitments.
- Tier-1 Suppliers:Continental AG and specialized module integrators bridge OEM platforms with certified biometric hardware. ECE R79 compliance deadlines force accelerated sensor roadmap decisions.
- Fleet Operators:Leased-vehicle procurement in the United States shifts toward subscription-based driver profile portability. Revenue recognition migrates from upfront hardware margin to recurring software fees.
- Aftermarket Providers:Retrofit channels serve voice recognition and security system demand without OEM hardware redesign. Stable demand persists where infotainment integration avoids factory tooling changes.
OEMs retain specification authority and margin capture, while Fleet Operators are gaining procurement leverage fastest through subscription-model unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Fleet operators in the United States resist hardware premiums through subscription unbundling. German premium OEMs absorb module costs to secure ECE R79 compliance ahead of regulatory deadlines.
United States
NHTSA guidelines on driver distraction monitoring accelerate iris and facial biometric integration timelines. Fleet procurement in Florida and Arizona pilots facial recognition for rental handoff protocols. Automotive electronics clusters in Michigan and California validate sensor durability testing for Tier-1 module suppliers.
Germany
Premium OEMs around Stuttgart and Munich source biometric steering wheel modules at volumes justifying foundry capacity investments. KBA type approval processes set certification benchmarks referenced by Japanese and South Korean regulators. Bavarian automotive clusters anchor European demand for ASIL-D certified attention-tracking systems.
Japan
METI road safety technology roadmaps parallel European ECE R79 adoption timelines for driver monitoring mandates. Domestic OEMs specify iris camera integration into A-pillar assemblies for low-light cabin performance. Nagoya-based Tier-1 suppliers redesign interior trim tooling to accommodate infrared illumination modules.
India
Domestic PLI scheme incentives for automotive electronics manufacturing attract biometric module assembly investments. Tier-1 suppliers establish production serving ASEAN export markets with cost-optimized sensor specifications. Tamil Nadu and Gujarat clusters emerge as assembly hubs for fingerprint-enabled access control modules.
South Korea
Regulators reference German KBA certification benchmarks for domestic type approval of iris-based attention tracking. Domestic OEMs integrate convolutional neural networks for real-time fatigue detection in luxury vehicle platforms. Seoul-based electronics conglomerates supply edge AI processors for cabin-mounted biometric authentication loops.
Biometric in the Automotive Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the automotive biometric value chain. The supplier base consolidates around Tier-1 integrators with OEM platform access, while specialized sensor vendors compete on automotive-grade certification velocity. Three archetypes dominate: diversified automotive electronics conglomerates with steering wheel module franchises, semiconductor specialists with capacitive sensor foundry relationships, and AI software providers with per-vehicle licensing models. Competitive dynamics center on strategic partnerships for ECE R79 compliance roadmaps and capacity reservations at Taiwan-based capacitive sensor foundries.
Within the diversified Tier-1 tier, Continental AG exemplifies the integrated module supplier archetype with European OEM platform anchoring. Synaptics Incorporated occupies a position among capacitive touch sensor specialists serving payment authentication integration requirements. Fujitsu Limited represents the iris recognition systems segment with low-light cabin environment specialization. These three companies illustrate how geographic origin and corporate structure align with distinct competitive positioning across hardware, software, and integration layers.
| Leading Market Players |
|---|
| Continental AG |
| Synaptics Incorporated |
| Fujitsu Limited |
| Gentex Corporation |
| NEC Corporation |
| Fingerprint Cards AB |
| Methode Electronics |
| VOXX International Corporation |
| Cerence Inc. |
| Others |
Value Chain & Pricing Dynamics
ECE R79 certification requirements gate both supplier qualification timelines and module price premiums simultaneously, compressing the window for uncertified competitors to undercut established Tier-1 pricing while OEMs absorb compliance-driven cost premiums to secure type approval ahead of regulatory deadlines.
Pricing Analysis
Subscription-based driver profile portability across leased fleets drives lifetime value capture for OEMs and Tier-1 suppliers. Pricing stratifies across ASIL-D certified attention-tracking modules, standard driver monitoring systems, and economy-grade fingerprint access control. Cost compression in capacitive sensor tiers intensifies because Taiwan foundry allocation constraints limit supply elasticity. Fleet operators in the United States exhibit highest price sensitivity through procurement unbundling, while German premium OEMs absorb premiums for ECE R79 compliance.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes strain inbound logistics for infrared camera modules and edge AI processors. Manufacturing concentrates in Taiwan, Germany, and Japan for automotive-grade biometric sensors. Supply chains draw from silicon wafer substrates, infrared optical coatings, and specialized ASIC foundry capacity. Single-source vulnerability concentrates in Taiwan-based capacitive fingerprint sensor production. Distribution runs through Tier-1 module integrators with direct OEM platform relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks automotive semiconductor cyclicality, with recovery momentum tied to foundry capacity normalization easing sensor allocation bottlenecks.
For Market Incumbents: Shield module pricing power through accelerated ASIL-D certification investments that lock in European luxury OEM relationships before ECE R79 deadlines eliminate second-source options. Deepen backward integration into infrared optical component supply to offset Taiwan foundry concentration risk. Prioritize firmware-over-the-air architectures that extend subscription revenue capture beyond hardware replacement cycles. For New Entrants and Emerging Players: Voice-biometric payment authentication layers represent the most penetrable service gap where incumbents under-serve in-vehicle commerce platform integration. Target aftermarket retrofit channels in the United States where infotainment integration avoids OEM hardware redesign barriers. Pursue white-label partnerships with fleet telematics providers to bypass direct OEM certification requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists holding ECE R79 certification progress but lacking scale for Tier-1 platform anchoring. Five-to-ten year viability hinges on software licensing displacement of pure hardware monetization. Monitor Taiwan foundry allocation announcements as inflection indicators for sensor module margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Functional Safety Certification | Creates supplier lock-in with German premium OEMs ahead of ECE R79 enforcement. |
| Backward Integration into Optical Components | Reduces coating degradation risk from cabin temperature cycling exposure. |
| Voice-Biometric Payment Platform Integration | Opens recurring subscription revenue streams decoupled from hardware margins. |
| Edge AI Processor Partnership | Enables real-time authentication loops without GDPR-constrained cloud dependency. |
| Aftermarket Infotainment Channel Expansion | Avoids OEM hardware redesign cycles while capturing stable retrofit demand. |
Study Parameters
Desk research of vehicle production databases, regulatory filing repositories, and Tier-1 supplier technical documentation preceded structured interviews with OEM platform engineers, Tier-1 procurement leads, aftermarket distribution channel heads, and fleet telematics operators. Primary fieldwork combined with secondary validation from IHS Markit registration data, KBA type approval records, and METI technology roadmap disclosures. Bottom-up sensor module shipment analysis triangulated against top-down OEM platform penetration estimates.
Variance decomposition across vehicle class, biometric modality, functional safety tier, and regional production cluster shaped the analytical framework. CAGRs derived from segmented volume projections and module pricing trajectories across the analysis window. Modeled inputs incorporated ECE R79 compliance timelines, Taiwan foundry capacity utilization rates, and GDPR biometric consent enforcement patterns.
Forecasts assume regulatory continuity in ECE R79, NHTSA guideline evolution, and GDPR biometric frameworks; material policy shifts would require re-modeling. Semiconductor supply normalization and privacy regulation divergence represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Front Collision Warning Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Steering Column Locks Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market
Automotive Safety and Security Systems
Motorcycle Stability Control Market
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market