
 Public EV Charging Pile Market | 2026-2036
Public EV Charging Pile Market Size, Share, and Industry Trends Forecast 2026-2036
Public EV Charging Pile Market Insights
Asset-light leasing and project finance structures is rewriting competitive entry barriers for charging infrastructure, allowing capital-constrained operators to deploy networks without balance-sheet ownership. ChargePoint leverages its software-first platform to sustain recurring revenue streams across fragmented site hosts. ABB anchors its position through integrated power electronics manufacturing that competes on energy conversion efficiency. State Grid Corporation of China dominates ultra-high-voltage backhaul connections that feed corridor charging clusters.
A public EV charging pile is an electric power dispensing station designed to deliver controlled direct-current or alternating-current energy to battery electric vehicles, typically operating at outputs ranging from 7 kW for AC Level 2 units to 350 kW or higher for DC fast chargers with liquid-cooled cable assemblies. These installations serve the primary commercial purpose of extending vehicle operational range beyond home charging limits while enabling fleet utilization rates that depend on rapid turnaround times. DC Fast Chargers command concentrated capital deployment along interstate corridors and urban entry points where dwell-time compression unlocks fleet economics, while AC Level 2 Chargers occupy a mature cost-optimized niche in workplace and residential parking structures where vehicles park for multi-hour intervals. Dedicated Charging Hubs are emerging as margin-rich assets that aggregate multiple power levels, on-site storage, and amenity retail to capture higher revenue per site.
The Federal Energy Regulatory Commission and the National Highway Traffic Safety Administration shape US grid interconnection standards and charging safety protocols, while the EU Green Deal and F-Gas Regulation drive European interoperability mandates and refrigerant restrictions on cooled cable systems. China's MIIT enforces GB/T connector and communication standards that condition market access for foreign equipment suppliers. Stakeholders must monitor how evolving utility rate structures and building code amendments alter site economics before committing to long-term charger deployment contracts.
Market Dynamics
Fleet electrification mandates and utility rate reform are compressing payback periods for corridor fast-charging assets while fragmenting site-host economics across retail parking, transit depots, and logistics hubs.
Growth Catalysts
- EU Green Deal ICE phase-out deadlines:Member states must install high-power charging pools every 60 kilometers along core transport corridors by 2025, forcing obligated infrastructure spend.
- Silicon carbide power modules:Wider bandgap semiconductors cut conversion losses in 350 kW dispensers, shrinking cooling system size and enabling slimmer cable assemblies.
- Logistics fleet operators:Amazon, DHL, and regional parcel carriers are signing 10-year charging service contracts that guarantee utilization floors and accelerate capital recovery.
Market Restraints
- Copper and rare-earth magnet cost volatility:Liquid-cooled cable assemblies and permanent-magnet motors in power conditioning units face input price swings that erode fixed-price EPC margins.
- Transformer lead times from East Asian foundries:Grid-interconnection hardware for 1 MW+ hub sites concentrates production in China and South Korea, stretching project timelines to 18-24 months.
- GB/T connector lock-in:China's MIIT-enforced domestic standard fragments interoperability, forcing foreign suppliers to maintain parallel SKU lines for market access.
Strategic Opportunities
- India's PLI scheme for auto and ACC battery manufacturing:Production-linked incentives are attracting cell gigafactories that will need captive charging infrastructure for outbound logistics and employee transport.
- Vehicle-to-grid bidirectional integration:Aggregated EV batteries as grid storage assets create new revenue streams from frequency regulation and peak shaving for charging hub operators.
- Curbside charging on-street parking:Cities including London, Paris, and Singapore are tendering 15-20 year concessions for lamp-post and bollard AC units in residential zones without off-street parking.
Industry Challenges
- High-voltage electrical technician scarcity:Installation and maintenance of 480V three-phase DC fast chargers requires certified specialists whose training pipelines lag deployment targets by 3-5 years in most markets.
- Utility interconnection queue delays:Distribution system impact studies and transformer upgrades from FERC-jurisdictional grid operators in the US routinely add 12-18 months to project schedules.
- ISO 15118-20 certification complexity:Plug-and-charge communication protocols require multi-vendor interoperability testing that extends product launch timelines and raises firmware validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public EV Charging Pile Market |
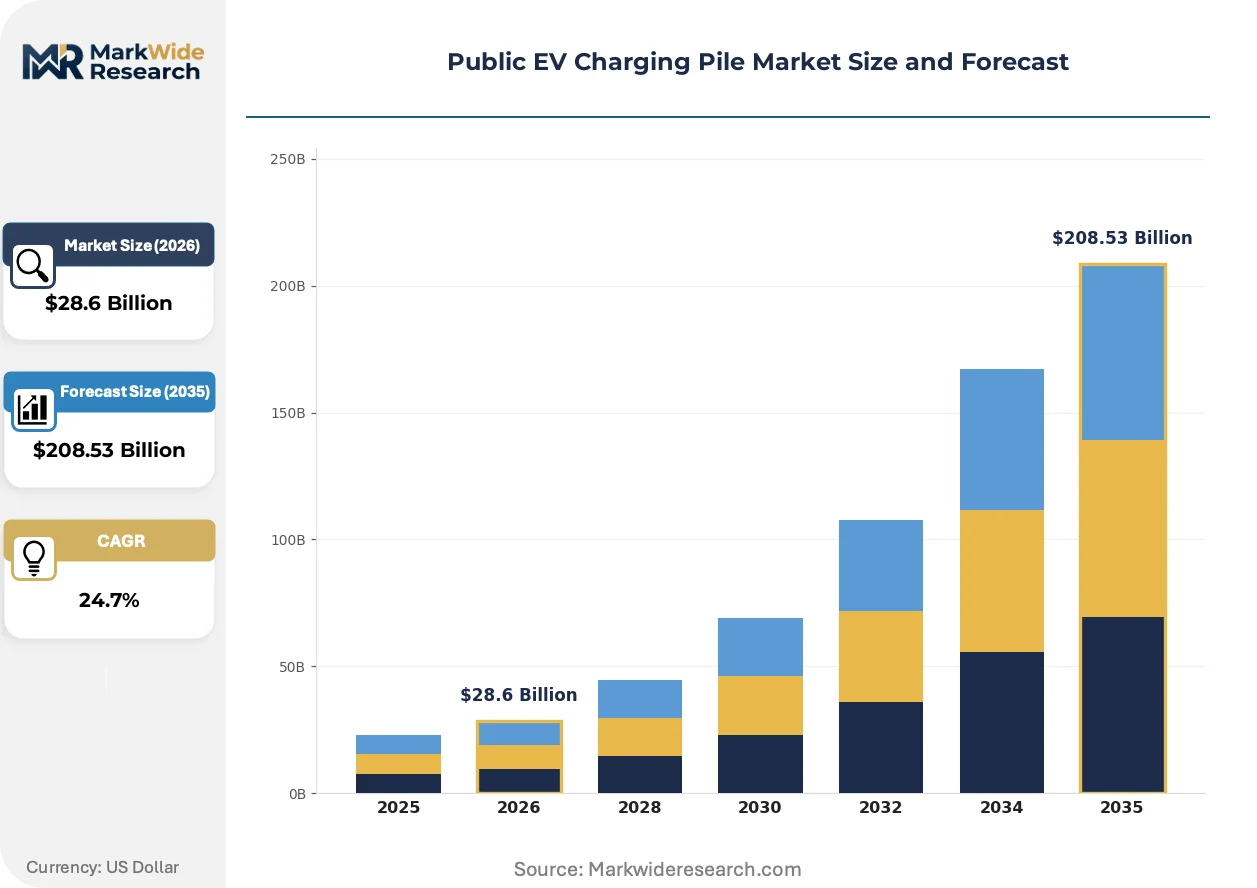
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $208.53 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Fast Chargers, AC Level 2 Chargers, Ultra-Fast Chargers, Mobile Charging Stations Installation Type: On-Street, Off-Street, Retail Locations, Dedicated Charging Hubs End User: Fleet Operators, Individual Consumers, Businesses, Government Agencies Payment Model: Pay-per-Use, Subscription-Based, Membership Plans, Free Charging |
| Companies Covered | Tesla, ChargePoint, ABB, State Grid Corporation of China, TELD New Energy, EVBox, Shell, Eaton, StarCharge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public EV Charging Pile Market Trends and Innovations
Hardware commoditization is pushing competitive differentiation toward software-defined load management, dynamic pricing algorithms, and integrated energy storage that buffers grid demand charges.
Liquid-cooled charging cables rated for 500 A continuous current are migrating from premium passenger vehicle applications to heavy-duty truck depots where megawatt-class dispensers must sustain 30-minute turnaround cycles for Class 8 tractors. Fleet operators at the Port of Long Beach and Rotterdam Maasvlakte are piloting these systems to replace diesel refueling throughput. The technology is migrating from early-adopter logistics nodes to standard procurement specifications in RFPs issued by national postal services.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in cable cooling systems, compelling manufacturers to adopt CO2 or propane-based heat pumps with lower global warming potential. Equipment suppliers must redesign thermal management architectures and secure new component certifications before 2027 enforcement deadlines. German TÜV and DEKRA testing protocols are becoming de facto European standards that condition market access.
Charging network access is unbundling from vehicle purchase through roaming platform subscriptions that aggregate multiple operators under single-app billing. Fleets and individual drivers in the Netherlands and California are abandoning direct membership with single networks in favor of third-party aggregators like Hubject and e-roaming platforms. This disintermediation compresses customer acquisition costs for new market entrants while eroding incumbent brand loyalty.
Public EV Charging Pile Market Segmentation
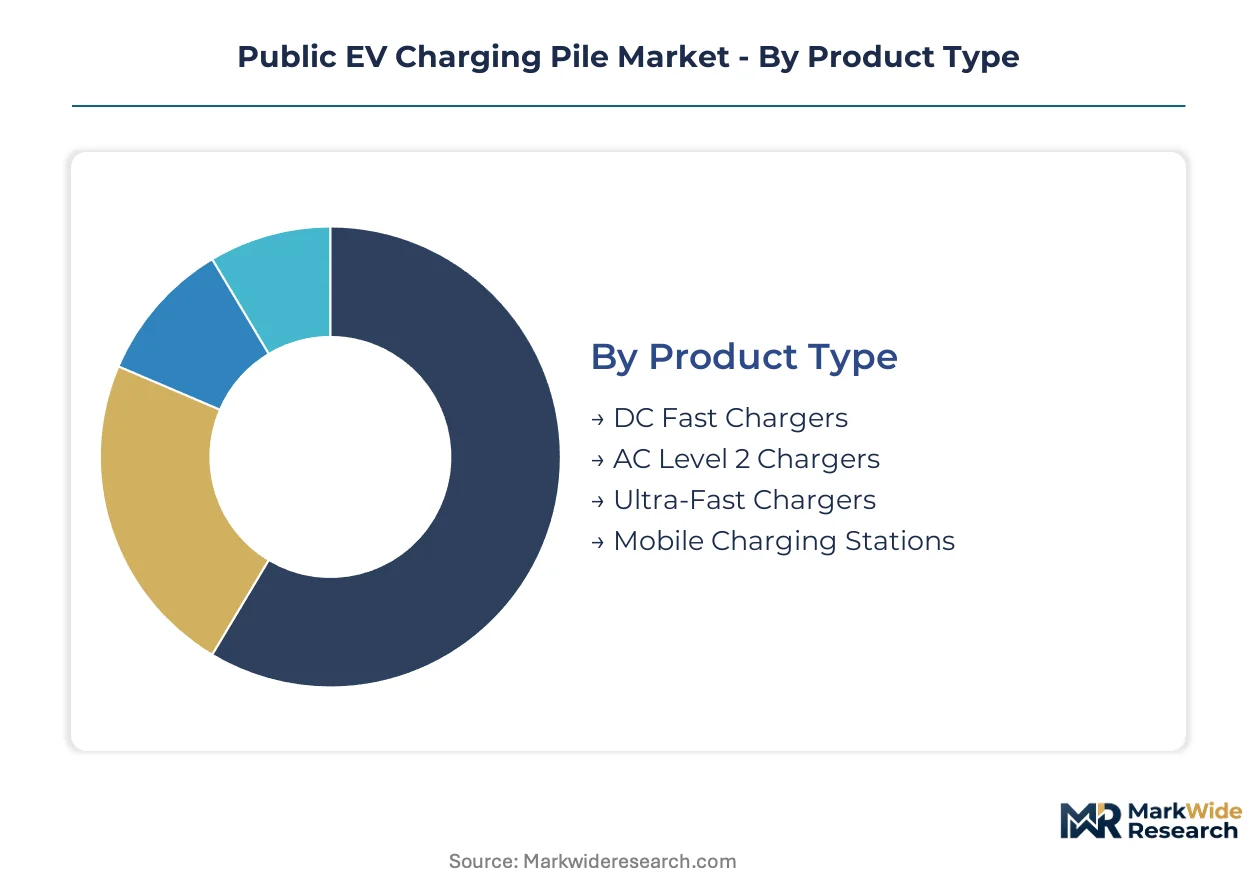
Segmentation in public EV charging infrastructure reveals how capital allocation, site economics, and utilization patterns diverge across equipment specifications and deployment contexts. Understanding these divisions helps operators match technology choices to revenue models and regulatory obligations.
Product Type:
Equipment maturity spans from cost-optimized legacy AC units to emerging megawatt-class systems for commercial trucking corridors.
- DC Fast Chargers:These units deliver 50-350 kW direct-current output through liquid-cooled cable assemblies, enabling 20-80% battery replenishment in 20-40 minutes. Highway corridor deployments in Germany and California absorb the dominant share of new capital, driven by EU Green Deal mandates for 60-kilometer spacing along core transport routes.
- AC Level 2 Chargers:Operating at 7-22 kW alternating current, these wall-mounted or pedestal units dominate workplace and residential parking structures where vehicles dwell for 4-8 hours. Cost per port has compressed below hardware margins, pushing competitive differentiation toward software-defined load management and dynamic pricing algorithms.
- Ultra-Fast Chargers:Silicon carbide power electronics enable 350 kW+ continuous output for heavy-duty truck depots at Rotterdam Maasvlakte and the Port of Long Beach.
- Mobile Charging Stations:Trailer-mounted battery-buffered systems serve temporary event infrastructure and emergency roadside assistance networks.
DC Fast Chargers retain volume leadership; Ultra-Fast Chargers hold the steepest expansion curve.
Installation Type:
Site configuration determines interconnection complexity, permitting timelines, and amenity revenue potential.
- On-Street:Curbside lamp-post and bollard installations in London, Paris, and Singapore target residential zones lacking off-street parking. Municipal tender concessions run 15-20 years, with utility rate structures and building code amendments altering site economics before contract commitment.
- Off-Street:Parking garage and surface lot deployments concentrate in commercial real estate portfolios where landlord-tenant cost allocation shapes utilization. Workplace charging in the United States benefits from FERC-jurisdictional utility rate reform that compresses demand charge exposure.
- Retail Locations:Grocery and big-box parking lots leverage dwell-time capture for customer loyalty programs.
- Dedicated Charging Hubs:Multi-megawatt sites aggregate power levels, on-site storage, and amenity retail to capture higher revenue per site.
Off-Street installations dominate current stock; Dedicated Charging Hubs are expanding most quickly as margin-rich anchor assets.
End User:
Customer type dictates contract structure, utilization guarantees, and hardware specification requirements.
- Fleet Operators:Amazon, DHL, and regional parcel carriers negotiate 10-year charging service contracts with utilization floors that accelerate capital recovery. These agreements specify 30-minute turnaround cycles for Class 8 tractors, driving procurement toward liquid-cooled 500 A cable systems.
- Individual Consumers:Roaming platform subscriptions through Hubject and e-roaming aggregators are displacing direct network memberships in the Netherlands and California, compressing customer acquisition costs while eroding incumbent brand loyalty.
- Businesses:Corporate fleet electrification commitments span logistics networks and employee transport pools.
- Government Agencies:Postal services and transit authorities issue RFPs with standardized procurement specifications for national infrastructure rollouts.
Fleet Operators command the largest committed capital pipelines; Individual Consumers represent the most fragmented revenue capture challenge.
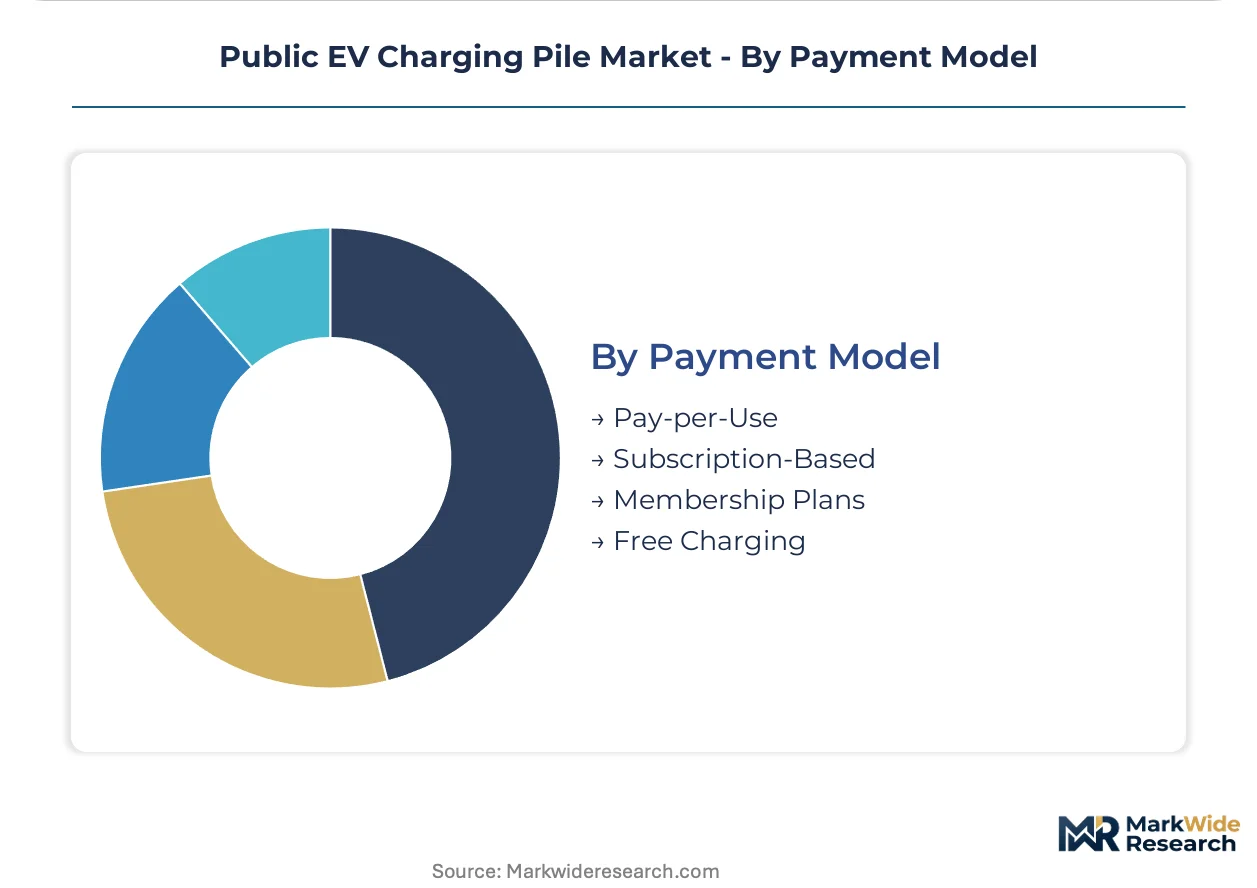
Payment Model:
Revenue structure alignment varies by customer lifetime value and transaction frequency economics.
- Pay-per-Use:Per-kWh or per-minute pricing dominates opportunistic public charging where session frequency remains unpredictable. Dynamic pricing algorithms adjust rates based on grid demand charges and real-time utilization.
- Subscription-Based: Monthly flat-fee structures reduce marginal transaction friction for regular commuters with predictable routes.
- Membership Plans:Annual contracts with network-specific discounts retain customer stickiness before roaming platform disintermediation.
- Free Charging:Employer-subsidized or retail-anchored loss-leader models drive foot traffic and employee retention.
Pay-per-Use generates the highest revenue per session volatility; Subscription-Based models are climbing the fastest as fleet operators seek cost predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in charging equipment concentrate manufacturing in East Asian foundries while deployment capital flows toward regulatory-mandated corridors in Europe and North America. China dominates transformer and power module production, creating supply dependencies for Western infrastructure rollouts. Trade frictions over GB/T standard enforcement reshape foreign supplier market access strategies.
China
Domestic deployment absorbs half of global DC fast charger installations annually, driven by MIIT-mandated GB/T connector standards that condition foreign equipment market access. State Grid Corporation of China controls ultra-high-voltage backhaul corridors feeding megawatt-class charging clusters along Beijing-Shanghai and Guangzhou-Shenzhen expressways. Yangtze River Delta manufacturing hubs in Jiangsu and Zhejiang provinces produce liquid-cooled cable assemblies for export to European and Southeast Asian markets.
Germany
Fleet electrification mandates from DHL and Amazon compress payback periods for Autobahn corridor assets, while EU Green Deal deadlines force 60-kilometer charging pool spacing by 2025. KBA enforcement of ISO 15118-20 plug-and-charge protocols extends product certification timelines for non-EU suppliers. Bavaria and North Rhine-Westphalia host the densest fast-charging concentrations, with dedicated hubs emerging at Ingolstadt and Düsseldorf logistics nodes.
United States
FERC-jurisdictional utility rate reforms alter demand charge economics for workplace and retail parking deployments across FERC Order 2222 implementation territories. NHTSA safety protocols and EPA refrigerant restrictions on cooled cable systems shape equipment procurement specifications. California and Texas absorb dominant shares of new capital, with Port of Long Beach pilots testing 500 A liquid-cooled systems for Class 8 tractor turnaround cycles.
India
PLI scheme incentives for ACC battery gigafactories in Gujarat and Tamil Nadu create captive charging infrastructure demand for outbound logistics and employee transport pools. CEA distribution code amendments streamline interconnection queues for 1 MW+ hub sites in Delhi-NCR and Maharashtra. Bangalore and Hyderabad technology corridors drive workplace AC Level 2 deployment for software sector commuter fleets.
Netherlands
Roaming platform aggregation through Hubject disintermediates direct network memberships, compressing customer acquisition costs for new market entrants. Municipal tender concessions for curbside lamp-post charging in Amsterdam and Rotterdam run 15-20 years with utility rate structures favoring residential zone deployment. Randstad logistics hubs anchor fleet operator charging service contracts with utilization floors.
Public EV Charging Pile Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in power electronics and thermal management. The vendor base stratifies between software-defined network operators and integrated hardware manufacturers, with capital-light leasing structures lowering entry barriers for site-host partnerships. Three archetypes dominate: utility-affiliated corridor developers, retail-anchored destination chargers, and fleet-captive depot specialists. Consolidation pressure concentrates on roaming interoperability and energy storage integration capabilities.
Among integrated hardware manufacturers, ABB and Eaton occupy positions spanning power conditioning and dispenser assembly. State Grid Corporation of China anchors the utility-affiliated tier through captive ultra-high-voltage interconnection assets. These three exemplify how vertical scope in power electronics or grid infrastructure shapes competitive differentiation against pure-play network operators.
| Leading Market Players |
|---|
| Tesla |
| ChargePoint |
| ABB |
| State Grid Corporation of China |
| TELD New Energy |
| EVBox |
| Shell |
| Eaton |
| StarCharge |
| Others |
Pricing and Supply Chain Analysis
East Asian foundry concentration for silicon carbide power modules and liquid-cooled cable assemblies concentrates margin capture with integrated manufacturers possessing captive semiconductor fabrication. Transformer lead times stretching 18-24 months for 1 MW+ hub sites force project developers to lock in equipment procurement before interconnection approval, shifting pricing power upstream.
Pricing Analysis
Fleet operators anchor contract-based long-term offtake structures with 10-year charging service agreements that guarantee utilization floors. Three-tier pricing structure across premium, standard, and economy levels differentiates by charging speed tier and ISO 15118-20 certification status. Cost compression in AC Level 2 hardware is intensifying because manufacturing scale has commoditized 7-22 kW units. Individual consumers exhibit highest price sensitivity through roaming platform aggregation, while fleet operators accept premium rates for turnaround reliability.
Supply Chain Analysis
Export-control restrictions on wide-bandgap semiconductor manufacturing equipment limit flows from US and Japanese suppliers to Chinese foundries. China, South Korea, and Germany dominate silicon carbide wafer and power module production. Copper conductor and rare-earth permanent magnet inputs feed from Chilean mining and Chinese processing operations. Single-source vulnerability concentrates in East Asian transformer foundries serving megawatt-class hub deployments. Distribution runs through EPC contractors and site-host leasing structures rather than direct manufacturer-to-operator sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The public EV charging pile market sits at a platform-economics inflection where ISO 15118-20 plug-and-charge interoperability disintermediates network-specific memberships in favor of roaming aggregation.
For Market Incumbents: Pre-empt roaming platform disintermediation by embedding proprietary load management software as the default integration layer for site hosts. Secure backward integration into silicon carbide power electronics manufacturing to defend margins against commodity hardware pressure. Anchor corridor positions through 10-year fleet service contracts with utilization floors before competitor hub development. For New Entrants and Emerging Players: Pursue curbside lamp-post charging concessions in European cities lacking off-street parking, where 15-20 year municipal tenders offer revenue visibility absent in competitive highway corridors. Target India's PLI-linked ACC battery gigafactory zones in Gujarat and Tamil Nadu for captive logistics and employee transport charging infrastructure. Lead with asset-light leasing structures that transfer balance-sheet risk to infrastructure funds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed charging network operators that expanded through 2020-2024 subsidy windows and now face roaming platform margin compression. Long-term viability hinges on software-defined energy management capabilities and vehicle-to-grid integration readiness rather than port count scale. Monitor FERC-jurisdictional utility rate reform implementation as the signal for demand charge economics inflection that reshapes hub site profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Vertical Integration | Captive power module production secures margin against commodity dispenser assembly competition. |
| Roaming Platform Partnership | Hubject and e-roaming aggregation reduces customer acquisition friction for network expansion. |
| Vehicle-to-Grid Certification | ISO 15118-20 bidirectional capability unlocks frequency regulation revenue streams for hub operators. |
| Curbside Concession Tendering | Amsterdam and Rotterdam municipal contracts provide 15-20 year revenue visibility in residential zones. |
| Fleet Service Contracting | Amazon and DHL 10-year agreements with utilization floors accelerate capital recovery timelines. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with charging network operators, fleet procurement managers, utility interconnection planners, and EPC contractors; and secondary validation through FERC filings, EU transport corridor deployment databases, NHTSA safety protocols, and MIIT GB/T standard documentation. Bottom-up installation forecasts triangulated against top-down regulatory mandate obligations across the analysis window.
Forecast inputs considered charger type segmentation by power output tier, installation context by site configuration, and end-user contract structure by fleet versus individual consumer revenue models. CAGRs derived from mandated deployment timelines under EU Green Deal corridor spacing requirements and US NEVI funding program implementation. Silicon carbide adoption curves and transformer lead time assumptions shaped capital deployment phasing.
Sensitivities concentrate around utility interconnection queue delays, copper and rare-earth input price volatility, and GB/T standard enforcement shifts affecting foreign supplier market access. Forecasts reflect documented assumptions on fleet electrification commitment timelines and subsidy program continuity. Material shifts in FERC-jurisdictional rate reform implementation or EU F-Gas Regulation enforcement deadlines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Asia-Pacific Wireless Electric Vehicle Charging Market
Electric Vehicle Charging
EV DC Chargers Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Charging Systems Testing Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle Quick Charging Station Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market