
 Fishing Rods Market | 2026-2036
Fishing Rods Market Size, Share, and Industry Trends Forecast 2026-2036
Fishing Rods Market Analysis
REACH compliance is decoupling European market access from legacy resin formulations, forcing manufacturers to reformulate binders and coatings. Shimano Inc. leverages its captive carbon fiber supply chain to absorb these compliance costs without outsourcing vulnerability. Pure Fishing Inc. competes through mass-market scale across freshwater spinning and casting categories. St. Croix Rods anchors its position in premium domestic manufacturing with proprietary blank construction.
A fishing rod is a tapered lever engineered from composite fibers, typically carbon graphite or fiberglass, designed to store elastic potential energy and cast line with controlled flexural recovery. The blank's modulus rating and resin system determine load-bearing capacity, action profile, and sensitivity transmission to the angler. Spinning rods occupy the highest volume tier across freshwater and saltwater usage, while fly rods command concentrated margin pools among technical anglers in North American and British markets. Graphite-dominant construction is displacing fiberglass in performance segments, though composite layups retain cost advantages for entry-level tournament equipment.
The EPA governs volatile organic compound emissions in rod-finishing operations across United States manufacturing facilities, while Japan's METI oversees carbon fiber precursor standards that propagate through Asian supply chains. ECHA's SVHC candidate list now scrutinizes specific epoxy hardeners used in high-modulus blank production, creating reformulation deadlines for European-sourced rods. Stakeholders must monitor how divergent chemical safety thresholds between American and Japanese regulatory frameworks reshape material sourcing strategies and factory location decisions.
Market Dynamics
Carbon fiber precursor supply concentration in Japan and Taiwan is forcing rod manufacturers to renegotiate blank sourcing contracts amid volatile aerospace sector competition for high-modulus fiber allocations.
Growth Catalysts
- EU Green Deal sustainable materials mandate:REACH-compliant bio-epoxy formulations are opening certified product lines for European retailers seeking defensible supply chains.
- Saltwater kayak fishing expansion:Coastal recreational anglers in Florida and North Carolina are driving specialized rod lengths and corrosion-resistant component demand.
- Precision carbon fiber engineering:Japanese toray-grade modulus advancement is enabling thinner-walled blanks with maintained hoop strength for technical freshwater applications.
Market Restraints
- Toray carbon fiber oligopoly:Three Japanese suppliers control precursor access, creating input cost volatility when aerospace contracts absorb available high-modulus capacity.
- SVHC epoxy hardener scrutiny:ECHA's expanding candidate list is forcing reformulation of legacy resin systems before existing inventory clears European distribution channels.
- Glass fiber substitution ceiling:Fiberglass retains cost advantages for youth tournament entry kits, capping graphite penetration in price-sensitive volume segments.
Strategic Opportunities
- Indonesia domestic manufacturing:ASEAN tariff structures and growing local angler populations support captive blank production for Asia-Pacific distribution.
- Direct-to-consumer reel-rod bundling:Subscription-based tackle curation services are bypassing traditional wholesale channels for committed angler cohorts.
- Modular travel rod systems:Four-piece blank technology convergence with airline carry-on constraints is opening premium price tiers for destination fishing travelers.
Industry Challenges
- Composite layup technician scarcity:Flagging apprenticeship pipelines in US and Japanese manufacturing hubs are constraining production ramp capacity.
- Dual regulatory certification timelines:Simultaneous EPA VOC compliance and ECHA SVHC documentation are extending new product introduction cycles.
- Legacy ERP integration with carbon fiber traceability systems:Batch-level precursor tracking requirements are forcing mid-tier manufacturers into expensive software migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishing Rods Market |
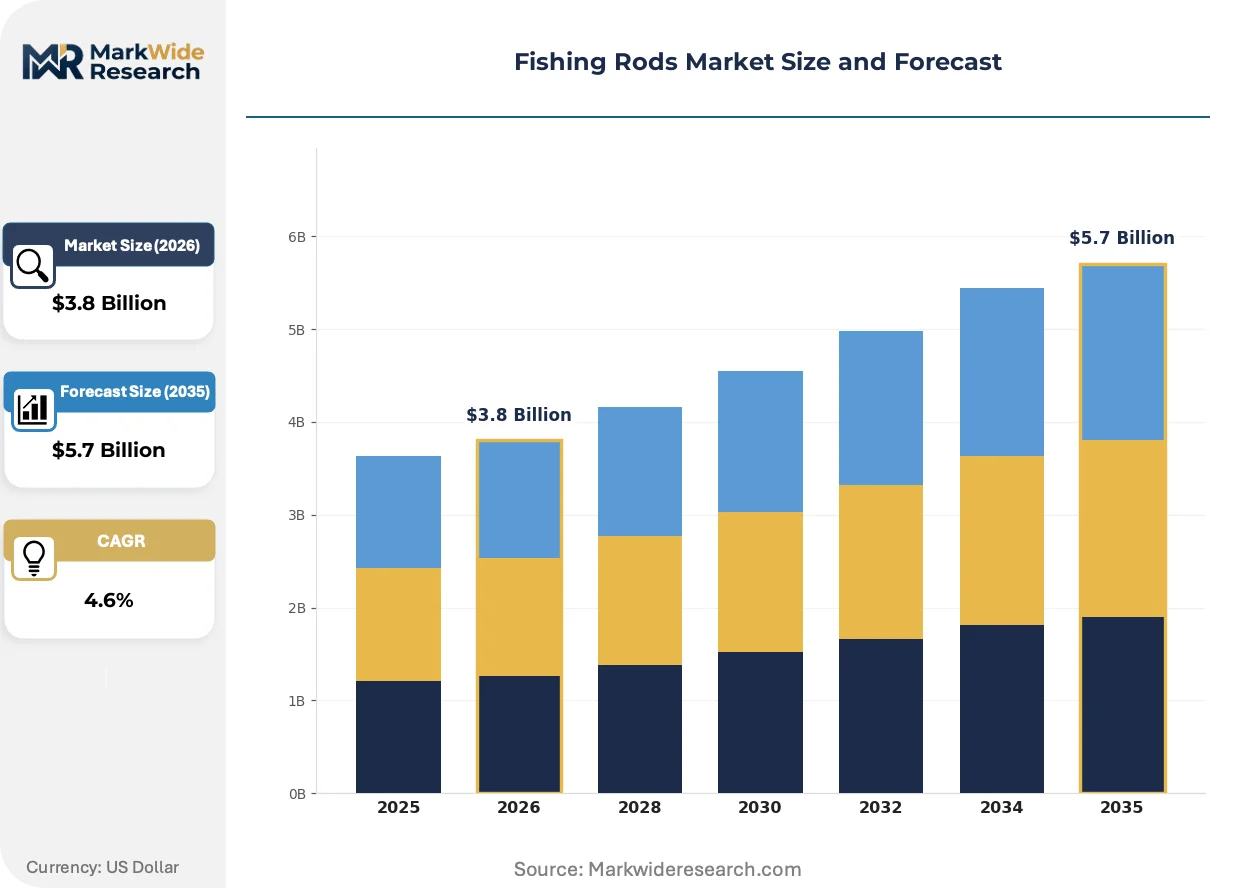
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinning Rods, Casting Rods, Fly Rods, Ice Fishing Rods Material: Fiberglass, Graphite, Bamboo, Composite Usage: Freshwater Fishing, Saltwater Fishing, Surf Fishing, Tournament Fishing Size: Ultralight, Light, Medium, Heavy |
| Companies Covered | Shimano Inc., Daiwa Corporation, Pure Fishing Inc., St. Croix Rods, Eagle Claw, Abu Garcia, Okuma Fishing Tackle Corp., RYOBI Limited, Shakespeare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishing Rods Market Emerging Trajectories
Blank construction methodologies are fragmenting across modulus grades and resin chemistries as regulatory divergence between jurisdictions forces parallel product development tracks rather than unified global SKUs.
Toray T1100G carbon fiber is modularizing high-performance rod architecture through interchangeable tip-section libraries that anglers configure for specific line weights and casting conditions. Tournament bass anglers in Texas and Alabama are adopting these systems fastest, compressing what were three separate rod purchases into modular tip investments. The structural consequence is margin compression on mid-tier complete rods while tip-section aftermarket sales concentrate with specialty retailers.
EPA volatile organic compound emission thresholds for rod-finishing operations are compelling US manufacturers to migrate solvent-based clear coats to waterborne UV-cure alternatives. This industrial consequence is elevating capital requirements for domestic finishing facilities while advantaging larger producers with in-house coating lines. Saltwater spinning rod categories face the steepest compliance timelines due to heavier epoxy build requirements for corrosion resistance.
Destination travel anglers are unbundling rod purchases from reel pairings, demanding warranty-backed four-piece blanks that survive airline baggage handling. This behavioral shift is disrupting traditional pro-shop bundling economics and elevating direct manufacturer relationships. The pattern is most visible in British Columbia and New Zealand guided fishing markets where clients arrive with pre-selected terminal tackle.
Fishing Rods Market Segmentation
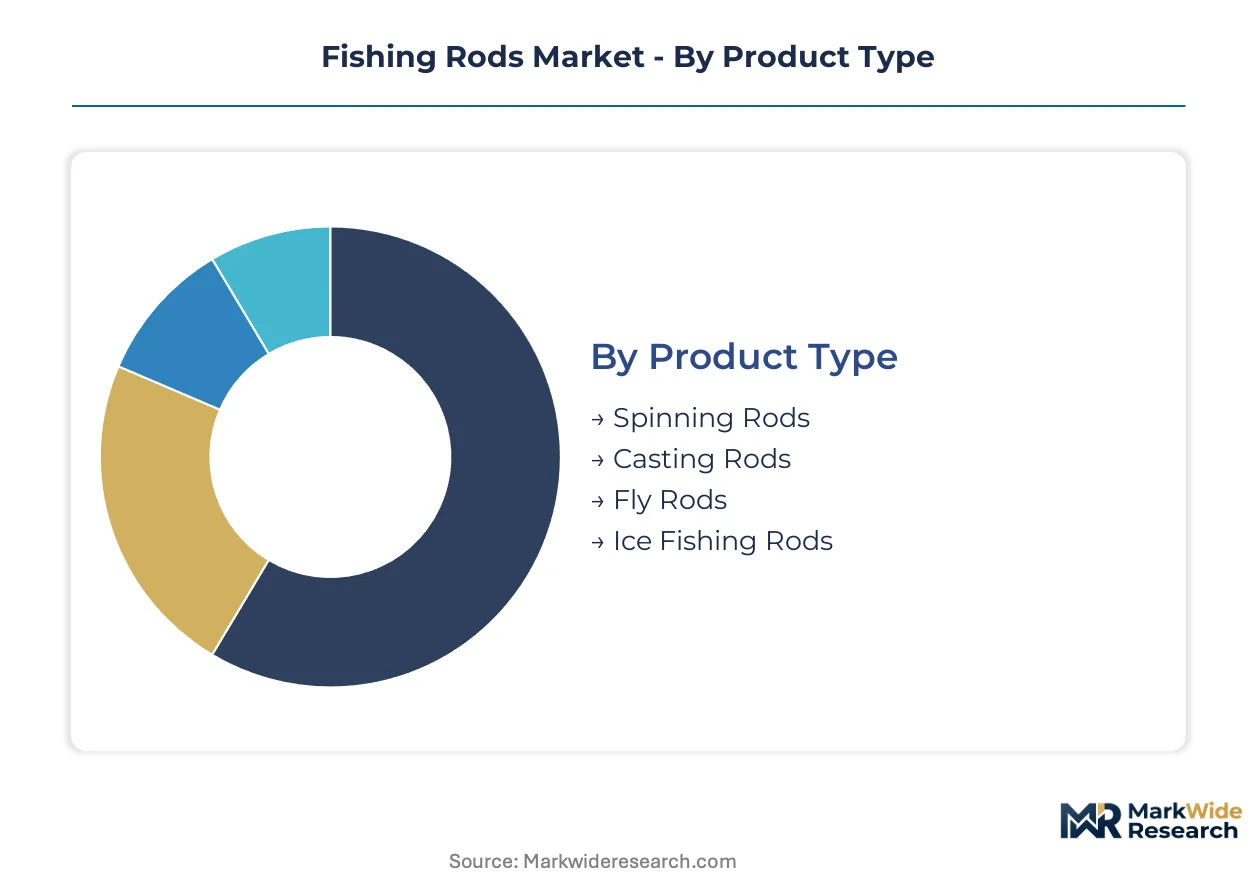
Anglers replace rods on distinct cadences—tournament competitors refresh annually, recreational users every three to five years. Material fatigue, blank failure, and action preference evolution drive these cycles differently across product categories.
Product Type:
Replacement cycles accelerate where competitive performance demands outpace durability improvements.
- Spinning Rods:Open-face reel compatibility and forgiving casting mechanics dominate volume sales across entry-level and mid-tier price bands. Coastal kayak anglers in Florida and North Carolina are driving specialized lengths with corrosion-resistant guides.
- Casting Rods:Trigger-style reel seats and stiffer backbone construction target accuracy-oriented bass anglers. Texas and Alabama tournament circuits are adopting modular tip-section systems that compress multiple rod purchases into configurable platforms.
- Fly Rods:Precision casting for technical trout and salmon applications commands concentrated margin pools. British Columbia and New Zealand guided fishing markets favor four-piece travel configurations with warranty-backed durability.
- Ice Fishing Rods:Short blanks with sensitive tip action dominate hardwater angling in Minnesota and Wisconsin lake regions.
Volume placements concentrate in Spinning Rods; the faster expansion belongs to Fly Rods.
Material:
Cost tier alignment determines manufacturer portfolio allocation and retail channel placement.
- Graphite:High-modulus carbon fiber construction delivers superior sensitivity-to-weight ratios for technical freshwater applications. Japanese toray-grade modulus advancement is enabling thinner-walled blanks with maintained hoop strength.
- Fiberglass:Durable, forgiving action retains dominance in youth tournament entry kits and price-sensitive volume segments. The material caps graphite penetration where parental purchase decisions prioritize replacement cost over performance.
- Composite:Hybrid layups blend fiberglass durability with graphite sensitivity for mid-market crossover appeal.
- Bamboo:Handcrafted traditional construction serves heritage fly fishing enthusiasts with artisanal scarcity positioning.
Manufacturing scale favors Graphite; heritage positioning sustains Bamboo.
Usage:
Application-specific corrosion and load requirements fragment blank engineering specifications.
- Freshwater Fishing:Lakes, rivers, and streams demand versatile action profiles across spinning and casting platforms. Bass tournament circuits in the southern United States drive the highest rod-per-angler ownership rates.
- Saltwater Fishing:Corrosion-resistant componentry and extended blank lengths target boat and pier anglers. Heavier epoxy build requirements for corrosion resistance face the steepest EPA VOC compliance timelines.
- Surf Fishing:Extreme length rods with fast tip recovery enable long-distance casting from beaches and jetties.
- Tournament Fishing:Standardized competition rules and sponsor alignment create concentrated demand for proven blank platforms.
Participation breadth anchors Freshwater Fishing; equipment intensity elevates Tournament Fishing.
Size:
Power rating alignment with target species determines retail assortment depth and inventory turns.
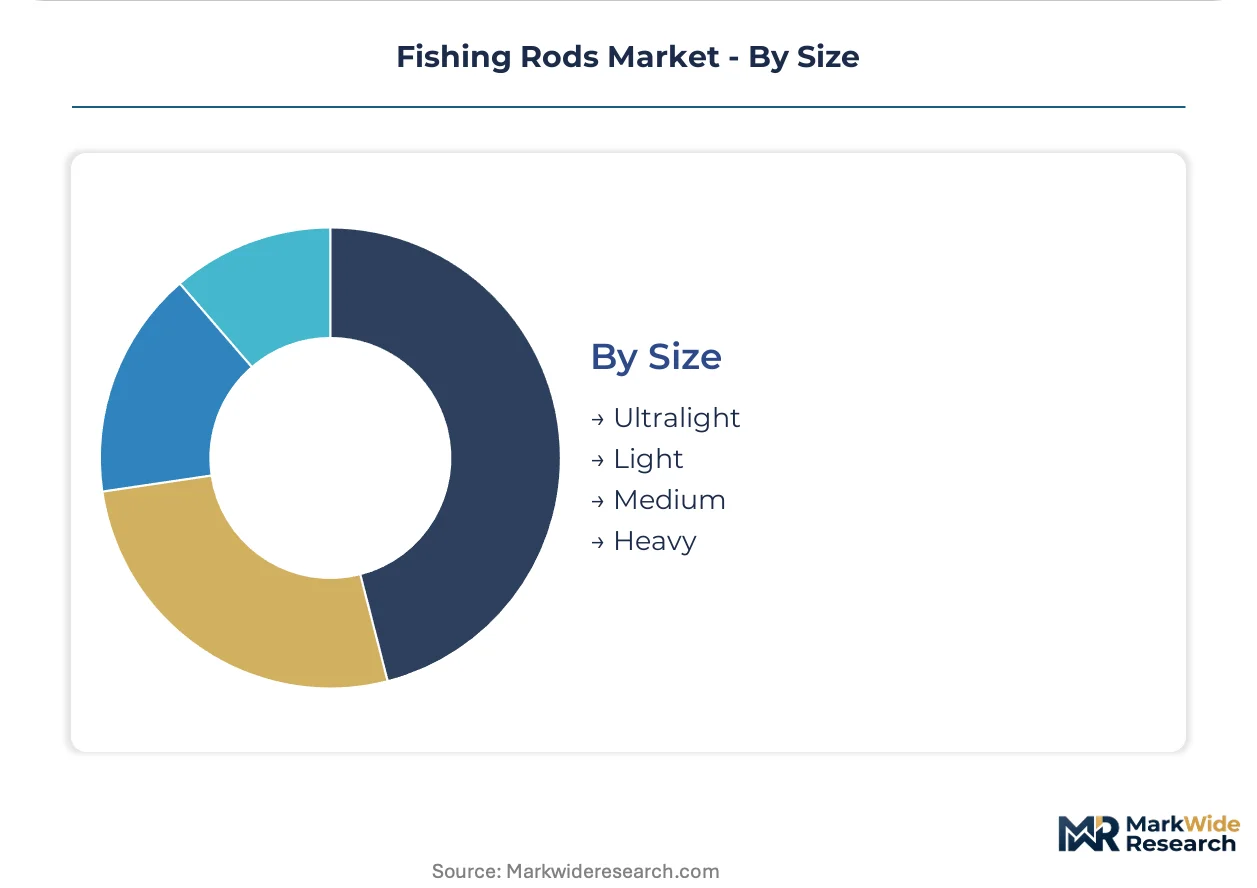
- Medium:Versatile backbone strength matches the widest species range from walleye to redfish. Retailers stock this rating deepest due to crossover appeal between freshwater and inshore saltwater applications.
- Heavy:Stiff action and reinforced blank construction target big-game species and heavy cover extraction. Gulf Coast offshore anglers and Great Lakes salmon trollers drive replacement demand where blank stress failure rates run highest.
- Light:Sensitive tip transmission suits finesse presentations for trout and panfish.
- Ultralight:Minimal weight and extreme flexibility serve micro-lure enthusiasts and youth introductory segments.
Inventory velocity peaks in Medium; stress-driven replacement frequency lifts Heavy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Batam Free Trade Zone is concentrating rod blank finishing capacity for Asia-Pacific distribution, leveraging ASEAN tariff preferences and proximity to Japanese carbon fiber precursor supply chains.
United States
Tournament bass anglers in Texas and Alabama drive replacement demand through modular tip-section systems. EPA volatile organic compound thresholds for rod-finishing operations are compelling solvent-to-waterborne coating transitions. Florida and North Carolina coastal clusters specialize in corrosion-resistant saltwater spinning rods for kayak fishing expansion.
Japan
Precision trout and salmon applications command concentrated margin pools among technical anglers. METI carbon fiber precursor standards propagate through Asian supply chains, shaping modulus grading protocols. Nagoya and Osaka manufacturing hubs integrate toray-grade fiber engineering with heritage craft traditions.
Germany
REACH-compliant bio-epoxy formulations are opening certified product lines for European retailers seeking defensible supply chains. ECHA scrutiny of specific epoxy hardeners is forcing reformulation deadlines before legacy inventory clears distribution. Bavarian and North Rhine-Westphalia fabricators are restructuring resin sourcing to maintain EU market access.
Indonesia
Growing domestic angler populations and ASEAN tariff structures support captive blank production for regional distribution. National industrial policy incentives for composite manufacturing are attracting Japanese equipment investment. Batam and Jakarta manufacturing zones are absorbing finishing capacity migration from higher-cost Asian hubs.
United Kingdom
British Columbia and New Zealand guided fishing markets favor four-piece travel configurations with warranty-backed durability. Domestic demand concentrates among heritage fly fishing enthusiasts seeking artisanal bamboo construction. Scottish and Welsh fabricators occupy premium positioning through handcrafted traditional methods.
Fishing Rods Market Vendor Landscape
Japanese producers anchor the high-modulus carbon fiber tier; American specialists hold premium domestic manufacturing positions. The vendor base splits between vertically integrated fiber-to-blank manufacturers and assembly-focused brands sourcing from Asian contract fabricators. Three archetypes dominate: toray-grade modulus innovators, mass-market scale operators, and heritage craft artisans. Competitive moves concentrate on captive carbon fiber supply arrangements and modular tip-section platform development.
Among Japanese toray-grade specialists, Shimano Inc. and Daiwa Corporation exemplify upstream integration into precursor supply chains. St. Croix Rods occupies a position within American premium domestic manufacturing. Pure Fishing Inc. represents mass-market scale deployment across freshwater spinning and casting categories.
| Leading Market Players |
|---|
| Shimano Inc. |
| Daiwa Corporation |
| Pure Fishing Inc. |
| St. Croix Rods |
| Eagle Claw |
| Abu Garcia |
| Okuma Fishing Tackle Corp. |
| RYOBI Limited |
| Shakespeare |
| Others |
Supply Flow & Price Mechanics
EU Green Deal sustainable materials mandates gate qualified supply access and premium-tier pricing power, forcing manufacturers to absorb bio-epoxy reformulation costs or forfeit European retail placement. REACH-compliant resin systems now command sourcing premiums that concentrate margin capture among toray-grade carbon fiber specialists with captive precursor arrangements.
Pricing Analysis
Short lead-time premiums separate tournament-grade blank deliveries from spot inventory discounts in legacy fiberglass categories. Three-tier pricing structure across premium, standard, and economy levels reflects modulus grade certification and METI-standard carbon fiber provenance. Price differentiation stems from EPA VOC compliance status and Japanese toray-grade fiber allocation priority. Tournament bass anglers in Texas and Alabama exhibit lowest price sensitivity; youth tournament entry kit buyers in freshwater segments face acute cost compression.
Supply Chain Analysis
Carbon fiber precursor supply rests on Japanese and Taiwanese specialty chemical producers, with toray-grade modulus advancement concentrated in Nagoya and Osaka manufacturing hubs. Raw material dependencies include epoxy resin systems, ceramic guide rings, and cork grip stock. Single-source vulnerability runs through three Japanese suppliers controlling high-modulus fiber allocations when aerospace contracts absorb available capacity. Distribution runs through specialty retailers, direct-to-consumer reel-rod bundling services, and mass-market sporting goods chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA SVHC scrutiny creates a barrier-to-entry moat for manufacturers with reformulated bio-epoxy capabilities and documented precursor traceability systems.
For Market Incumbents: Anticipate aerospace sector competition for toray-grade carbon fiber capacity by securing long-term precursor offtake agreements with Japanese suppliers. Backward integration into captive blank production in Indonesia's Batam Free Trade Zone mitigates tariff exposure and compresses lead times for Asia-Pacific distribution.
For New Entrants and Emerging Players: REACH in Germany opens a window for certified bio-epoxy rod lines targeting European retailers seeking defensible supply chains. White-space concentrates in modular travel rod systems for destination fishing markets in British Columbia and New Zealand, with direct-to-consumer warranty-backed distribution bypassing traditional wholesale markups.
For Investors and Strategic Acquirers: Japanese equipment investment announcements in Indonesian composite manufacturing zones are the leading indicator that captive finishing capacity migration is accelerating. Long-term viability favors vertically integrated fiber-to-blank specialists with METI-standard modulus grading protocols. Watch EPA VOC compliance timeline extensions for saltwater spinning rod categories as a demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor Supply | Captive toray-grade fiber access insulates margin from aerospace sector competition. |
| REACH-Compliant Bio-Epoxy Product Line Certification | European retail placement requires defensible supply chain documentation under ECHA scrutiny. |
| Modular Tip-Section Platform Development | Tournament bass anglers in Texas compress multiple rod purchases into configurable aftermarket investments. |
| Indonesia Manufacturing Footprint Expansion | Batam Free Trade Zone leverages ASEAN tariff preferences and Japanese equipment investment incentives. |
| Direct-to-Consumer Warranty-Backed Distribution | Destination travel anglers in British Columbia unbundle rod purchases from traditional pro-shop economics. |
Methodological Framework
Document review covered SEC filings from listed manufacturers, Japanese METI carbon fiber standards documentation, and ECHA SVHC candidate list updates, complemented by interviews with composite layup technicians, rod blank procurement managers at specialty retailers, and regulatory affairs leads at European distributors. Secondary validation drew from customs trade data, EPA VOC emission compliance records, and tournament angler equipment surveys. Bottom-up demand modeling across product categories triangulated against top-down market sizing from precursor fiber allocation data.
Cross-referencing historical replacement cycle patterns with panel input from rod component suppliers established the projection framework across the analysis window. Segmentation dimensions modeled include product type, material grade, usage application, and regional regulatory cluster. CAGRs were derived from modulus-grade volume trajectories and compliance-driven price tier shifts, incorporating aerospace sector fiber competition intensity and coastal kayak fishing participation trends as industry-specific inputs.
The model assumes a particular technology adoption path for waterborne UV-cure coating systems; alternative pathways for solvent-based clear coat retention would alter the outlook for domestic US finishing facility economics. Forecasts reflect assumptions about ECHA SVHC list expansion timelines and METI precursor standard propagation. Regulatory divergence between American and Japanese chemical safety thresholds, aerospace contract absorption of high-modulus fiber capacity, and apprenticeship pipeline recovery in composite layup technician pools warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Street Skateboards Accessories Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Ice Hockey Stick Market
Sports Equipment
Golf Gloves Market
Sports Equipment
North America Stand-Up Paddleboard Market
Sports Equipment
Global Skateboard Market
Sports Equipment
Cleat Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Mountain Bicycle Fork Market
Sports Equipment
Agility Ladders Market
Sports Equipment
Premium Bicycle Market