
 In Vitro Diagnostic (IVD) Reagent Market | 2026-2036
In Vitro Diagnostic (IVD) Reagent Market Size, Share, and Industry Trends Forecast 2026-2036
In Vitro Diagnostic (IVD) Reagent Market Analytics
Market Context
Single-source dependence on proprietary reagent-instrument systems is hardening among incumbent suppliers. Thermo Fisher Scientific leverages its integrated consumables-platform model to sustain recurring revenue streams across clinical and research channels. Roche anchors its position through captive chemistry-analyzer pairings that dominate high-throughput immunoassay workflows.
Technical Definition and Segment Structure
In Vitro Diagnostic (IVD) Reagents comprise formulated chemical and biological preparations—antibodies, enzymes, nucleic acid probes, calibrators, and substrates—designed to produce measurable analytical signals from patient-derived specimens outside the living organism. Molecular diagnostic reagents command premium positioning as PCR and NGS workflows displace conventional culture methods in infectious disease and oncology testing. Clinical chemistry reagents occupy mature, high-volume segments where price compression and commoditization pressure margin pools.
Regulatory Environment and Outlook
The FDA's phased enforcement of IVD reagent regulations, the EU Medical Device Regulation's stricter conformity requirements, and China's NMPA accelerated review pathways for innovative diagnostics collectively elevate compliance costs and extend time-to-market for new formulations. Stakeholders must monitor divergence between FDA's risk-based classification approach and EMA's notified body recalibration timelines. The decisive variable shaping competitive advantage will be harmonized quality management systems that satisfy multiple jurisdictions without redundant validation burdens.
Market Dynamics
Automated platform lock-in is hardening across the IVD reagent landscape as diagnostic laboratories consolidate around closed-system architectures that tether consumables to proprietary analyzers, compressing supplier switching flexibility and elevating lifetime customer value for integrated vendors.
Growth Catalysts
- Precision medicine infrastructure:Hospital systems in the United States, Germany, and China are scaling molecular diagnostic capabilities, pulling demand for companion diagnostic reagents into oncology and infectious disease workflows.
- EU MDR implementation:Stricter conformity assessment under the Medical Device Regulation is accelerating quality system investments among mid-tier suppliers, filtering subscale competitors and consolidating procurement toward validated reagent manufacturers.
- PCR-to-NGS transition:Next-generation sequencing chemistries are capturing share from conventional amplification methods in hereditary cancer screening and pharmacogenomics, expanding addressable reagent spend per patient test.
Market Restraints
- Raw material concentration:High-purity enzymes and recombinant antibodies concentrate among a handful of fermentation suppliers in Switzerland and Denmark, exposing reagent formulators to input bottlenecks and price volatility.
- FDA enforcement discretion:Phased regulatory oversight of laboratory-developed tests is creating registration pathway uncertainty for reagent manufacturers serving reference labs, delaying commercialization timelines.
- Commoditization pressure:Clinical chemistry segments face margin compression as open-system reagents achieve functional parity, eroding pricing power in high-volume electrolyte and enzyme testing.
Strategic Opportunities
- Point-of-care decentralization:Ambulatory settings in India and Brazil present underpenetrated demand for lyophilized reagent formats that eliminate cold-chain dependencies in resource-limited environments.
- AI-integrated assay design:Machine learning algorithms are converging with synthetic biology to compress reagent optimization cycles, enabling rapid development of multiplexed panels for emerging pathogens.
- China NMPA innovation pathway:Accelerated review channels for breakthrough diagnostics are shortening time-to-market for novel biomarker reagents, rewarding early regulatory engagement with priority market access.
Industry Challenges
- Multi-jurisdiction validation:Divergent FDA risk-classification and EMA notified-body recalibration timelines force redundant clinical studies, straining quality assurance teams and documentation systems.
- Legacy analyzer integration:New reagent chemistries must maintain backward compatibility with installed bases of aging immunoassay platforms, constraining formulation innovation and extending development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vitro Diagnostic (IVD) Reagent Market |
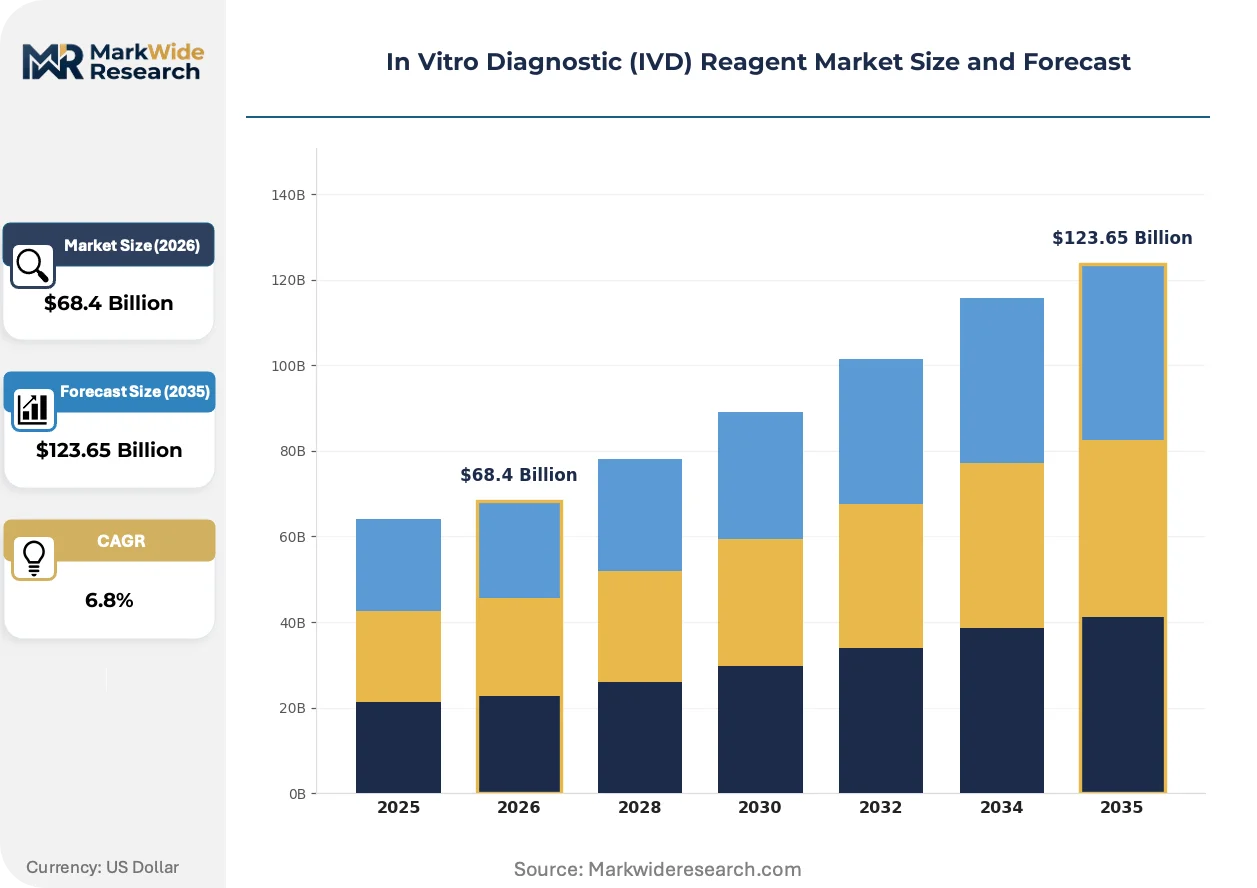
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Reagents, Molecular Diagnostic Reagents, Clinical Chemistry Reagents, Hematology Reagents Technology: Enzyme-Linked Immunosorbent Assay, Polymerase Chain Reaction, Flow Cytometry, Microarray End User: Hospitals, Diagnostic Laboratories, Research Institutions, Academic Medical Centers Application: Infectious Diseases, Cancer Diagnostics, Cardiovascular Diseases, Genetic Testing |
| Companies Covered | Thermo Fisher Scientific Inc, F. Hoffmann-La Roche Ltd, Danaher Corporation, Abbott, Siemens Healthineers AG, Bio-Rad Laboratories, Inc, QIAGEN N.V., Becton, Dickinson and Company, Hologic, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vitro Diagnostic (IVD) Reagent Market Evolving Landscape
Reagent chemistry is converging with digital workflow integration as laboratories demand seamless data transmission from assay execution to laboratory information systems, reshaping how consumables are specified, validated, and procured across health networks.
Lyophilized bead-based reagent formats are absorbing ambient-temperature stability requirements for decentralized testing. Community health centers and retail clinic chains are adopting these formats to bypass cold-chain infrastructure. The technology is absorbing margin pressure from conventional liquid reagents by reducing shipping costs and extending shelf life in distributed settings.
EMA's In Vitro Diagnostic Medical Devices Regulation enforcement is tightening post-market surveillance obligations for reagent manufacturers. Annual safety reporting and periodic performance reviews are elevating compliance staffing levels. Molecular diagnostic panels face the steepest documentation burdens as notified bodies scrutinize analytical and clinical validity claims under the new framework.
Consolidated procurement through group purchasing organizations is compressing supplier negotiation leverage. Integrated delivery networks in the United States are unbundling reagent contracts from instrument leases, forcing standalone pricing discipline. Reference laboratories are responding by qualifying secondary suppliers and diversifying assay menus to reduce single-source dependency.
In Vitro Diagnostic (IVD) Reagent Market Segmentation
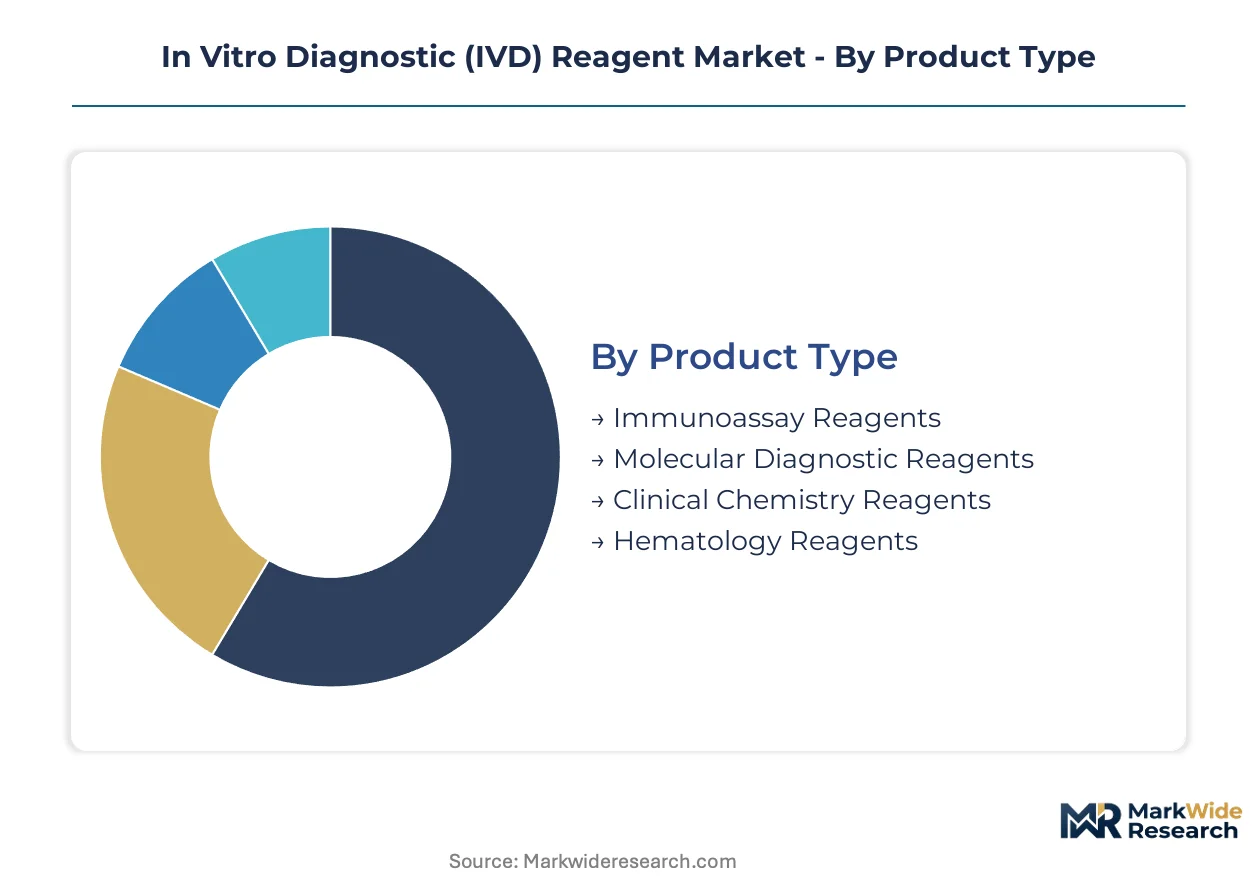
IVD reagent segmentation reveals divergent margin architectures across product chemistry, detection modality, and care setting. Capital deployment, regulatory burden, and customer concentration vary sharply by segment, reshaping how suppliers prioritize R&D and commercial resources.
Product Type:
Capital intensity peaks with molecular diagnostic platforms requiring cleanroom manufacturing and nucleic acid chemistry validation.
- Molecular Diagnostic Reagents:These formulations incorporate nucleic acid probes, polymerases, and reverse transcriptases for PCR and NGS workflows. Demand concentrates in the United States and China as hospital systems expand oncology and infectious disease testing menus. Companion diagnostic requirements from FDA and NMPA elevate validation costs and extend development timelines.
- Immunoassay Reagents:Antibody-antigen complexes and labeled conjugates power automated analyzer workflows in high-throughput hospital labs. Germany's precision medicine infrastructure pulls premium spend for cardiac and thyroid panels, though closed-system lock-in limits supplier switching.
- Clinical Chemistry Reagents:Enzymatic and colorimetric formulations for electrolyte, enzyme, and metabolite testing face commoditization pressure from open-system alternatives.
- Hematology Reagents:Diluents, lysing agents, and calibrators for cell-counting instruments serve high-volume screening programs with stable, predictable demand cycles.
Most installed capacity flows through clinical chemistry reagents. Expansion is steepest in molecular diagnostic reagents.
Technology:
Platform selection determines workflow integration costs and reagent consumables pricing power across laboratory networks.
- Polymerase Chain Reaction:Thermal cycling chemistries dominate infectious disease and oncology testing with established regulatory pathways. China's NMPA accelerated review channels reward early entrants with priority market access for novel infectious disease panels.
- Enzyme-Linked Immunosorbent Assay:Plate-based immunoassays anchor clinical chemistry menus with lower per-test costs than molecular alternatives. Diagnostic laboratories in the United States consolidate procurement around automated ELISA platforms that reduce manual handling.
- Flow Cytometry:Fluorochrome-labeled antibodies enable cell population analysis in leukemia and lymphoma diagnostics.
- Microarray:Solid-phase nucleic acid hybridization supports pharmacogenomics and cytogenetic screening with multiplexed throughput advantages.
Laboratory investment concentrates on PCR infrastructure. Microarray adoption is climbing fastest in pharmacogenomics applications.
End User:
Customer scale and purchasing sophistication fragment reagent procurement patterns across the care continuum.
- Diagnostic Laboratories:Reference labs and health system core laboratories command volume discounts and multi-year supply agreements. Group purchasing organizations in the United States unbundle reagent contracts from instrument leases, forcing standalone pricing discipline on suppliers.
- Hospitals:Acute care settings prioritize rapid turnaround for emergency and intensive care testing with integrated analyzer-reagent systems.
- Research Institutions:Academic and commercial R&D facilities demand specialized formulations with batch-to-batch consistency for reproducibility.
- Academic Medical Centers:Teaching hospitals combine clinical service with translational research, requiring flexible reagent sourcing across both regulated and investigational applications.
Procurement volume concentrates in diagnostic laboratories. Academic medical centers are expanding reagent spend fastest as precision medicine programs scale.
Application:
Disease area prioritization shapes biomarker validation requirements and reimbursement pathways for reagent developers.
- Cancer Diagnostics:Companion diagnostic reagents for targeted oncology therapies command premium pricing and require synchronized FDA approval with pharmaceutical partners. China's hospital systems are scaling molecular testing infrastructure for lung and colorectal cancer screening.
- Infectious Diseases:Multiplexed panels for respiratory, bloodstream, and sexually transmitted pathogens address antimicrobial stewardship priorities. EMA's MDR implementation elevates post-market surveillance documentation for European infectious disease test suppliers.
- Cardiovascular Diseases:Troponin, BNP, and lipid panel reagents serve high-frequency testing in emergency departments and outpatient monitoring.
- Genetic Testing:Carrier screening, prenatal diagnostics, and hereditary risk assessment require specialized nucleic acid chemistries with analytical validity documentation.
Test volume concentrates in infectious disease applications. Genetic testing is expanding most quickly as NGS costs decline and reimbursement stabilizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors precision medicine infrastructure development, pulling specialized reagent demand into companion diagnostic workflows. Hospital systems across Germany and China are scaling molecular testing platforms, while regulatory divergence between FDA, EMA, and NMPA timelines complicates multi-jurisdiction product launches.
United States
Integrated delivery networks in Texas and California are unbundling reagent contracts from analyzer leases, forcing standalone pricing discipline on suppliers. FDA's phased enforcement of laboratory-developed test regulations creates pathway uncertainty for reference lab reagent vendors. The Research Triangle Park cluster in North Carolina concentrates contract manufacturing for nucleic acid chemistries serving oncology panels.
Germany
Baden-Württemberg's precision medicine infrastructure pulls premium spend for cardiac and thyroid immunoassay panels into hospital core laboratories. EMA's MDR implementation elevates post-market surveillance documentation burdens, filtering subscale European suppliers. The Munich biotech corridor anchors automated platform manufacturing, with Siemens Healthineers AG maintaining captive chemistry-analyzer pairings for high-throughput workflows.
China
Yangtze River Delta hospital systems are scaling lung and colorectal cancer screening menus, expanding companion diagnostic reagent procurement. NMPA accelerated review channels for breakthrough diagnostics shorten time-to-market for novel biomarker formulations. The Beijing-Tianjin-Hebei cluster concentrates domestic fermentation capacity for high-purity enzymes, reducing import dependence for PCR and NGS chemistries.
Switzerland
Basel's pharmaceutical-diagnostic convergence anchors companion diagnostic co-development agreements with oncology drug sponsors. Swissmedic maintains alignment with EMA MDR timelines while offering streamlined quality system recognition for EU-validated products. The Zurich biotech corridor concentrates recombinant antibody fermentation supply, exposing global reagent formulators to input bottlenecks during demand surges.
India
Maharashtra's diagnostic laboratory chains are adopting lyophilized reagent formats to eliminate cold-chain dependencies in community health settings. CDSCO's evolving IVD regulatory framework creates registration pathway uncertainty for imported molecular diagnostic panels. The Hyderabad pharma cluster is absorbing contract manufacturing for enzyme and substrate formulations serving Southeast Asian export markets.
In Vitro Diagnostic (IVD) Reagent Market Competitive Landscape
Global majors compete with regional champions across platform integration depth, with automated system lock-in hardening as the decisive competitive dimension. The vendor base stratifies between integrated consumables-platform vendors, standalone reagent specialists, and contract fermentation suppliers. Three archetypes dominate: full-stack diagnostics conglomerates, precision reagent boutiques, and bioprocessing infrastructure providers. Consolidation pressure intensifies through strategic partnerships and captive supply agreements rather than outright acquisition.
Within the integrated-system tier, Thermo Fisher Scientific Inc and F. Hoffmann-La Roche Ltd exemplify platform-tethered business models that compress customer switching flexibility. Danaher Corporation occupies a position spanning analytical instrumentation and consumables, representing the diversified conglomerate archetype. These three entities anchor competitive dynamics through recurring revenue structures that extend lifetime customer value across clinical and research channels.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Abbott |
| Siemens Healthineers AG |
| Bio-Rad Laboratories, Inc |
| QIAGEN N.V. |
| Becton, Dickinson and Company |
| Hologic, Inc |
| Others |
Value Network & Pricing Analysis
EMA's MDR post-market surveillance mandates gate qualified supply access for European IVD reagent manufacturers, with annual safety reporting requirements filtering subscale suppliers and concentrating premium-tier pricing power among validated producers with harmonized quality systems across multiple jurisdictions.
Pricing Analysis
High-purity enzyme and recombinant antibody costs pass through directly to molecular diagnostic reagent pricing, with fermentation capacity concentration in Switzerland and Denmark amplifying volatility. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and analytical performance tier. Price differentiation hinges on FDA breakthrough designation status and NMPA innovation pathway qualification. Clinical chemistry reagents face the steepest cost compression as open-system alternatives achieve functional parity, eroding margins in high-volume electrolyte testing. Reference laboratories and group purchasing organizations in the United States exhibit highest price sensitivity, while companion diagnostic reagents for oncology maintain lowest sensitivity due to synchronized pharmaceutical co-development requirements.
Supply Chain Analysis
High-purity enzyme supply rests on fermentation infrastructure concentrated in Switzerland, Denmark, and China's Beijing-Tianjin-Hebei cluster. Recombinant antibodies, nucleic acid probes, and polymerase formulations constitute critical input dependencies. Single-source vulnerability concentrates in Swiss recombinant antibody production, exposing global reagent formulators to input bottlenecks during demand surges for infectious disease panels. Distribution runs through integrated consumables-platform vendors and standalone reagent specialists serving diagnostic laboratories, with consolidated procurement through group purchasing organizations compressing supplier negotiation leverage across hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IVD reagent market functions as a stable compounder anchored by recurring consumables demand tethered to installed analyzer bases, with precision medicine infrastructure scaling in the United States, Germany, and China providing durable volume growth.
For Market Incumbents: Anticipate regulatory divergence between FDA risk-classification and EMA notified-body recalibration timelines by investing in harmonized quality management systems that satisfy multiple jurisdictions without redundant validation burdens. Defend against open-system commoditization pressure in clinical chemistry by deepening captive chemistry-analyzer pairings and expanding companion diagnostic co-development agreements with oncology drug sponsors. Prioritize backward integration into fermentation capacity for high-purity enzymes to reduce exposure to Swiss and Danish supply concentration. For New Entrants and Emerging Players: Direct-to-clinic digital distribution channels enable rapid market entry for lyophilized reagent formats targeting India's Maharashtra diagnostic laboratory chains and Brazil's community health centers, where cold-chain elimination commands procurement priority. White-space concentration sits in point-of-care decentralization for resource-limited environments and AI-integrated assay design for emerging pathogen multiplexed panels. Target ambulatory settings with ambient-temperature stable formulations, leveraging CDSCO registration pathway uncertainty to establish early relationships with domestic contract manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for precision reagent boutiques because automated platform lock-in hardens customer switching costs and extends lifetime value through recurring consumables revenue. Five-to-ten year viability favors targets with validated companion diagnostic pipelines and NMPA breakthrough designation access. Acquisition target archetype: mid-tier molecular diagnostic specialists with cleanroom manufacturing infrastructure and synchronized FDA-NMPA regulatory strategies. Signal to monitor: EMA MDR implementation filtering subscale European suppliers and consolidating procurement toward validated manufacturers with multi-jurisdiction quality systems.| Strategic Initiative | Industry Significance |
|---|---|
| Harmonized Quality System Investment | EMA MDR and FDA risk-classification convergence reduces redundant validation burdens for multi-jurisdiction launches. |
| Companion Diagnostic Co-Development | Synchronized FDA-NMPA approval with oncology drug sponsors commands premium pricing and captive demand. |
| Lyophilized Format Expansion | Ambient-temperature stability eliminates cold-chain dependencies in India's community health settings. |
| Backward Integration into Fermentation | In-house enzyme production reduces exposure to Swiss and Danish supply concentration risks. |
| AI-Integrated Assay Design | Machine learning convergence with synthetic biology compresses reagent optimization cycles for emerging pathogens. |
Research Methodology
Coverage spans the United States, Germany, China, Switzerland, and India, with primary inputs from each market cluster combining structured interviews with regulatory affairs leads at IVD manufacturers, procurement managers at diagnostic laboratory chains, biomedical engineers at academic medical centers, and contracts managers at group purchasing organizations. Secondary validation draws from FDA 510(k) filings, EMA MDR submission databases, NMPA innovation pathway approvals, hospital procurement databases, and GPO contract disclosures. Bottom-up reagent volume modeling triangulates with top-down precision medicine infrastructure spending analysis.
Granularity-level modeling disaggregates molecular diagnostic, immunoassay, clinical chemistry, and hematology reagents by PCR, ELISA, flow cytometry, and microarray technology platforms across diagnostic laboratories, hospitals, research institutions, and academic medical centers. Application-level segmentation captures cancer diagnostics, infectious diseases, cardiovascular diseases, and genetic testing with companion diagnostic and pharmacogenomics specificity. CAGRs derive from instrument install base projections, test menu expansion rates, and reagent consumables pricing trajectories across the projection horizon. NGS cost decline curves and reimbursement stabilization timelines inform genetic testing expansion assumptions.
The model assumes a particular technology adoption path; alternative pathways for PCR-to-NGS transition would alter the outlook for nucleic acid chemistry demand and reagent spend per patient test. Forecasts reflect assumptions regarding EMA MDR implementation pace, FDA laboratory-developed test enforcement discretion, and NMPA accelerated review channel capacity. Regulatory timeline slippage, raw material fermentation bottlenecks, and open-system commoditization acceleration constitute specific revision risks. A small set of named triggers—companion diagnostic reimbursement decisions, major infectious disease outbreak demand surges, and multi-jurisdiction quality system harmonization progress—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Global Blood Culture Tests Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market