
 Canned Tuna Market | 2026-2036
Canned Tuna Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Tuna Market Intelligence
Foodservice operators are unwinding decades of household-centric demand as institutional buyers expand procurement of portion-controlled tuna formats for quick-service and casual-dining menus. Thai Union Group leverages its vertically integrated fleet-to-can supply chain across the Western Pacific to secure raw material access. Bumble Bee Foods sustains brand recognition in North American retail through shelf-stable innovation and channel partnerships. Dongwon Industries anchors volume leadership in South Korea and extends processing reach into Southeast Asian waters.
Canned tuna comprises cooked, cleaned, and hermetically sealed skipjack, yellowfin, or albacore loin preserved in brine, oil, or sauce with shelf stability exceeding thirty-six months under ambient storage. The product serves as a low-cost, high-protein ingredient for retail pantries, institutional kitchens, and emergency food programs requiring minimal refrigeration. Chunk light products dominate volume due to lower raw material cost and broader recipe compatibility across foodservice applications. Pouch packaging represents the fastest-growing format as consumers prioritize portability and reduced liquid weight in e-commerce fulfillment. Online retailers capture expanding margin pools by bypassing traditional wholesale markups and offering subscription replenishment models.
NOAA dolphin-safe labeling requirements and E.U. IUU fishing regulations enforce vessel-level traceability, reshaping procurement compliance costs for processors sourcing from multi-flag fleets. The E.U. F-Gas Regulation and national refrigeration standards in Japan and Thailand constrain cold-chain energy profiles, indirectly affecting pre-canning holding costs. Stakeholders must monitor evolving Marine Stewardship Council certification thresholds and regional depletion measures as sustainability criteria increasingly gate retail and foodservice contract eligibility.
Market Dynamics
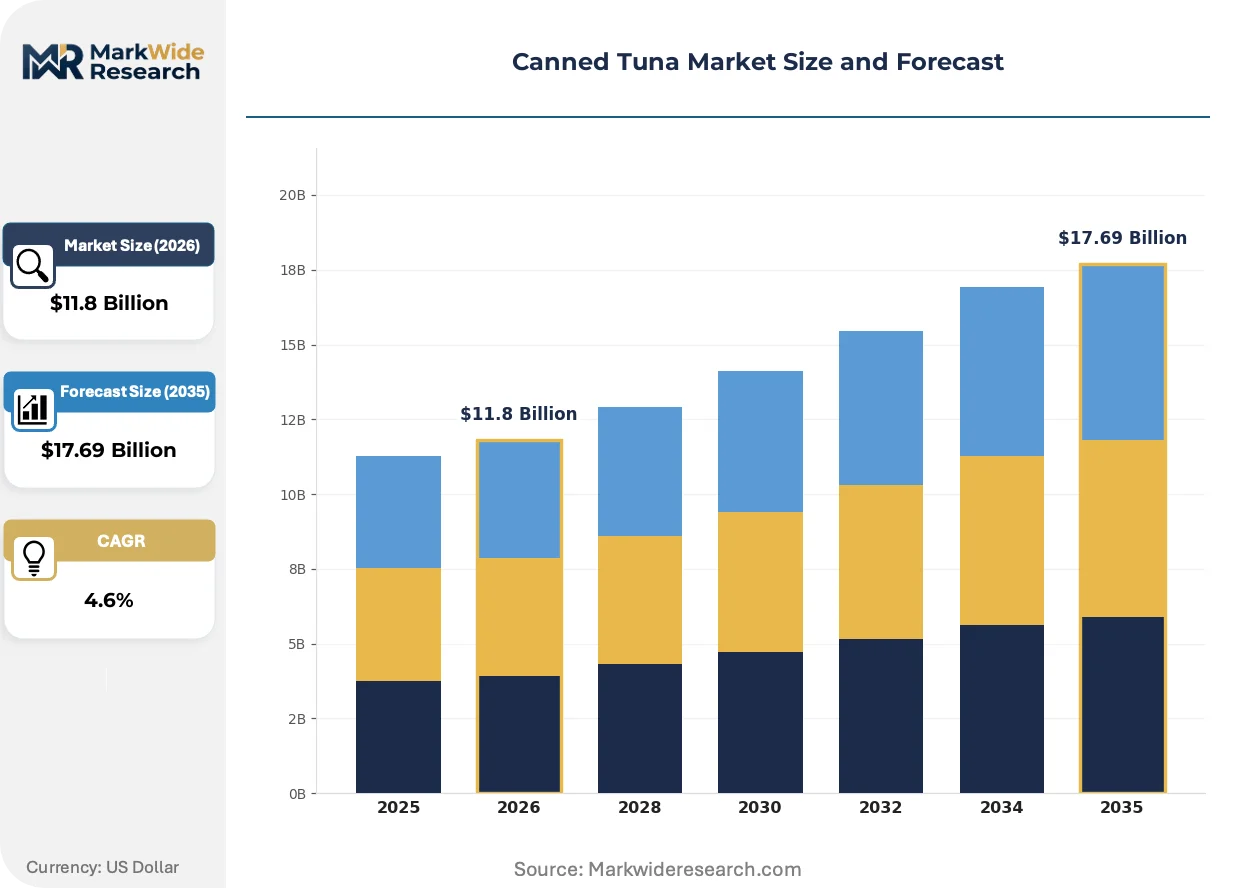
Foodservice procurement of portion-controlled tuna formats is displacing decades of household-centric demand patterns across Southeast Asian markets, while NOAA dolphin-safe and E.U. IUU traceability mandates reshape compliance cost structures for multi-flag fleet operators.
Growth Catalysts
- E.U. IUU Regulation:Vessel-level traceability requirements are forcing supply chain digitization that locks out non-compliant suppliers, tightening raw material access for certified processors.
- Pouch packaging technology:Reduced liquid weight and improved portability are accelerating e-commerce fulfillment efficiency, capturing margin pools previously absorbed by wholesale intermediaries.
- Thailand cold-storage expansion:Regional processing hub capacity additions are shortening pre-canning holding periods and reducing spoilage rates for skipjack and yellowfin landings.
Market Restraints
- Skipjack price volatility:Western Pacific purse-seine catch fluctuations transmit directly into raw material cost instability for Thai and Philippine canners.
- Fleet concentration in Taiwan/China:Multi-flag vessel registration complexity creates supply interruption risk when regional fisheries management measures tighten.
- E.U. F-Gas Regulation:Refrigerant phase-down constraints elevate cold-chain holding costs for pre-processing frozen loin inventory.
Strategic Opportunities
- Indonesia processing underpenetration:Archipelagic landing proximity offers shorter transport legs versus Thai hub dependence for Indian Ocean catch.
- Subscription replenishment models:Direct-to-pantry e-commerce channels bypass traditional retail slotting fees and capture recurring revenue streams.
- Marine Stewardship Council certification:Retail and foodservice contract eligibility gates are widening for MSC-labeled product, creating premium positioning potential.
Industry Challenges
- Electronic monitoring system integration:Vessel-level traceability hardware deployment requires capital expenditure and crew retraining across aging fleet infrastructure.
- Dolphin-safe certification timeline compression:NOAA documentation requirements for net deployment logs are extending procurement verification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Tuna Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunk Light, Solid, Flaked, White Meat, Albacore Packaging Type: Can, Pouch, Jar, Vacuum Pack, Tray Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Clubs, Specialty Stores End User: Foodservice, Household, Catering, Institutional, HoReCa |
| Companies Covered | Thai Union Group, Century Pacific Food, Bumble Bee Foods, Dongwon Industries, Bolton Food, StarKist Co., Grupo Calvo, Frinsa, Jealsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Tuna Market Strategic Shifts & Innovations
Pouch packaging formats, regulatory traceability mandates, and foodservice procurement centralization are converging to compress traditional wholesale channels and elevate sustainability certification as a contract gate.
Retort pouch technology is miniaturizing portion sizes while eliminating can-weight shipping penalties. Quick-service operators in the Philippines and Indonesia are adopting single-serve formats for grab-and-go menu integration. The structural consequence is margin compression for conventional can manufacturers as pouch converters capture format innovation premiums.
E.U. F-Gas Regulation phase-down schedules are constraining cold-chain refrigerant choices for Thai and Indonesian pre-processing facilities. Industrial consequence includes accelerated ammonia system retrofits and elevated capital intensity for holding capacity expansion. Japanese and South Korean processors with existing CO2 infrastructure face lower compliance friction.
Foodservice procurement centralization is consolidating purchasing authority into regional distributor networks. Independent restaurant operators in Bangkok and Manila are losing direct processor relationships as broadline distributors capture volume aggregation benefits. This concentration is most visible in quick-service chain expansion across secondary Indonesian cities.
Canned Tuna Market Segmentation
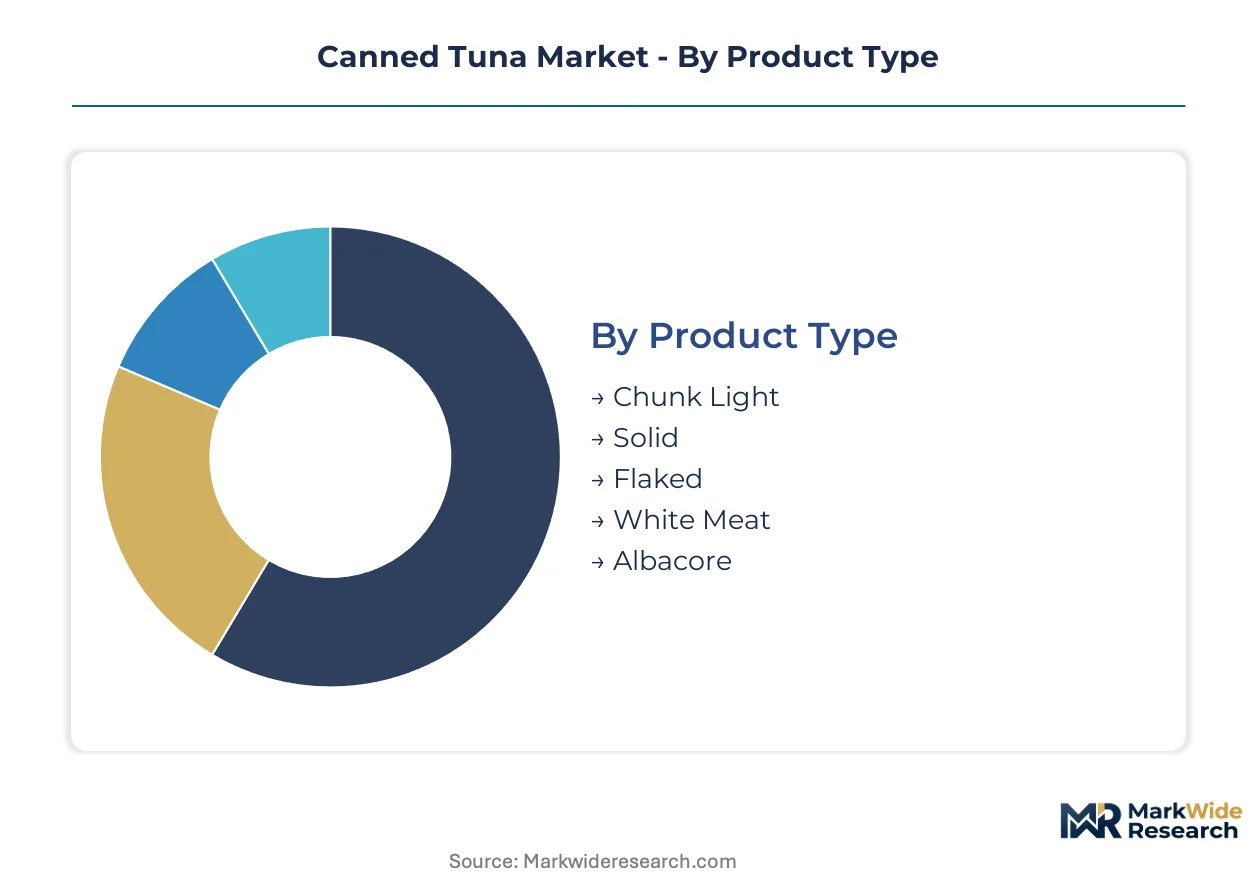
Segmentation in canned tuna reveals how processing methods, packaging formats, and channel structures create divergent margin profiles and vulnerability to substitute proteins. Understanding these fault lines exposes where incumbent formats face displacement from alternative seafood and plant-based analogs.
Product Type:
Substitution pressure from plant-based tuna analogs and fresh chilled alternatives concentrates most intensely on lower-specification segments where taste differentiation is weakest.
- Chunk Light:Composed of mixed skipjack and yellowfin pieces cooked in broth before flaking and canning. Demand concentrates in Southeast Asian foodservice channels where Thai and Philippine processors supply quick-service operators with cost-optimized portion packs. Price volatility in Western Pacific purse-seine landings compresses margins for this commoditized tier.
- Solid:Whole loin sections preserved intact in oil or brine, commanding premium positioning in Japanese and South Korean retail where texture integrity drives purchase decisions. E.U. IUU traceability requirements elevate compliance costs for solid-pack processors sourcing from multi-flag fleets.
- Flaked:Finely shredded tuna tissue suited for sandwich spreads and salad applications. European private-label demand anchors volume.
- White Meat:Bleached albacore loin with mild flavor profile targeting North American pantry replacement cycles. FDA canned food safety standards govern thermal processing parameters.
- Albacore:Single-species pack with higher omega-3 content and firmer texture, concentrated in premium retail slots and subscription replenishment channels.
Chunk Light anchors the volume base while Albacore gains share at the steepest rate.
Packaging Type:
Cost tier stratification separates capital-intensive format investments from legacy asset bases, with cold-chain infrastructure requirements determining regional feasibility.
- Can:Three-piece steel or aluminum construction with hermetic double-seam closure, retaining dominant shelf presence in North American and European mass retail. Thai Union Group and Dongwon Industries maintain captive can manufacturing to control input costs.
- Pouch:Multi-layer polyester-aluminum laminate retortable bags reducing shipping weight by 40% versus metal formats. Japanese and South Korean e-commerce fulfillment networks adopt pouch configurations fastest, bypassing wholesale markups through direct-to-pantry subscription models.
- Jar:Glass container format with twist-off closure, concentrated in Mediterranean private-label contracts where visual product inspection influences purchase.
- Vacuum Pack:Thermoformed barrier film enclosing loin portions for refrigerated distribution, bridging shelf-stable and fresh chilled categories.
- Tray:Rigid plastic or aluminum platforms with peelable film lidding, deployed in Indonesian and Philippine convenience retail for single-serve immediate consumption.
Can formats retain the installed production base while Pouch configurations expand most quickly.
Distribution Channel:
Customer type concentration determines procurement authority structures, with institutional buyers consolidating purchasing power at the expense of fragmented independent operators.
- Supermarkets:Full-assortment retail with dedicated shelf-stable seafood sections, capturing planned pantry replenishment in Thailand, Indonesia, and the Philippines. Slotting fee structures favor established brands with velocity guarantees.
- Convenience Stores:Limited SKU count with grab-and-go positioning, concentrated in Japanese urban corridors and Indonesian secondary cities where single-serve pouch formats dominate.
- Online Retailers:Platform-mediated fulfillment with algorithmic replenishment recommendations, capturing margin pools previously absorbed by wholesale intermediaries.
- Wholesale Clubs:Volume-tier pricing with multi-unit pack requirements, anchoring North American household stockpiling behavior.
- Specialty Stores:Curated assortment emphasizing Marine Stewardship Council certification and pole-and-line sourcing claims.
Supermarkets anchor the volume base while Online Retailers gain share at the steepest rate.
End User:
Application maturity separates saturated household penetration from underdeveloped institutional segments where portion control and menu integration drive adoption.
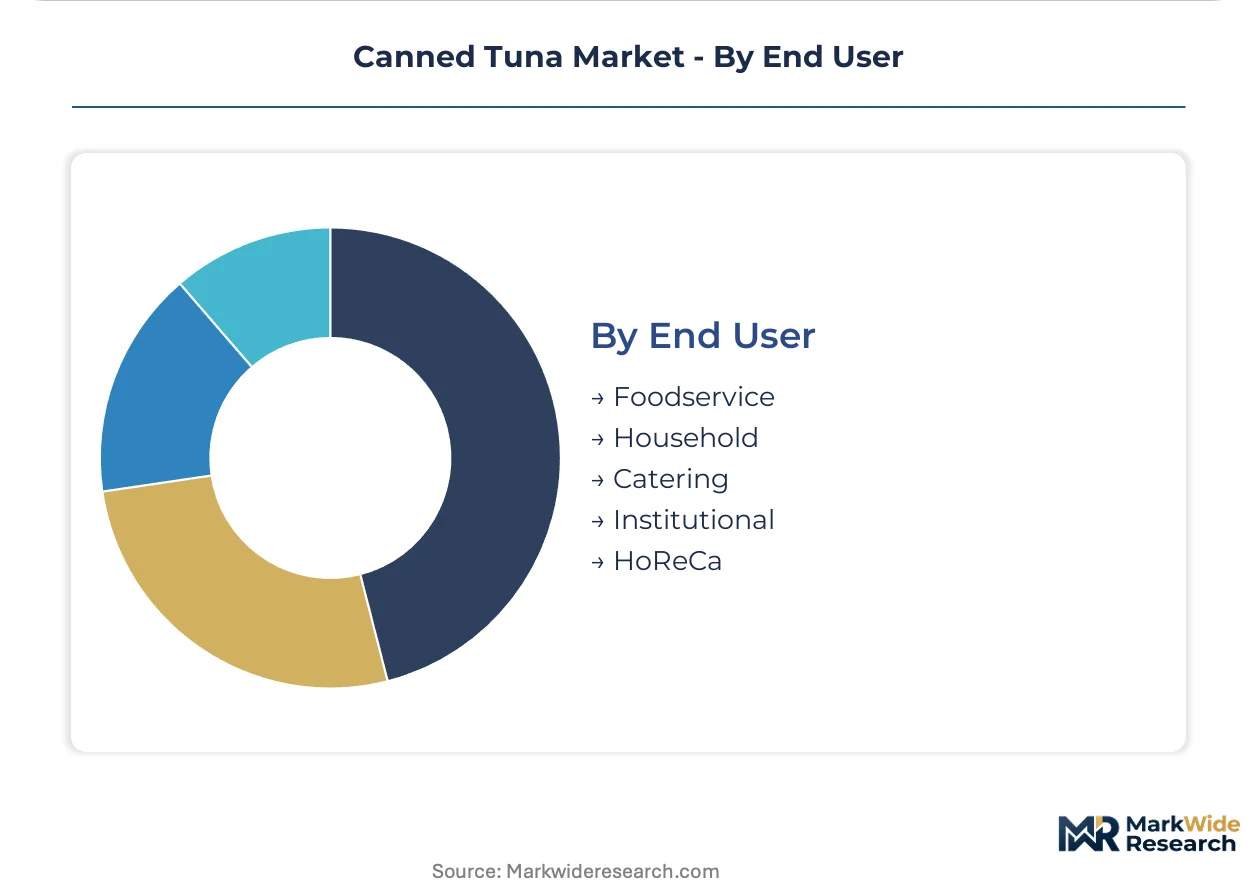
- Foodservice:Quick-service and casual-dining operators in Bangkok, Manila, and Jakarta adopting portion-controlled pouch formats for menu integration. Centralized procurement through broadline distributors displaces direct processor relationships for independent restaurants.
- Household:Pantry stockpiling behavior in North American and European markets with thirty-six-month shelf stability enabling bulk purchase cycles.
- Catering:Event and institutional feeding operations requiring scalable protein solutions with minimal refrigeration dependency.
- Institutional:School feeding and emergency food programs in the Philippines and Indonesia where shelf stability and cost per protein gram determine specification.
- HoReCa:Hotel, restaurant, and café segment with quality-tier differentiation between buffet service and plated presentation requirements.
Household consumption anchors the volume base while Foodservice gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Bangkok's container throughput underwrites Thailand's dominance in tuna canning, while cold-chain corridors from Manta, Ecuador to Manila sustain Pacific-to-Asia protein flows.
Thailand
Foodservice procurement from quick-service chains in Bangkok and secondary cities drives pouch format adoption. Thai FDA labeling requirements for dolphin-safe certification extend verification cycles for imported skipjack. Samut Sakhon province hosts the densest canning cluster, where Thai Union Group operates integrated fleet-to-can facilities.
Philippines
Institutional feeding programs and emergency food reserves concentrate demand in Mindanao and Visayas regions. Bureau of Fisheries and Aquatic Resources vessel monitoring rules enforce electronic logbook submission for purse-seine operators. General Santos City anchors the tuna landing and primary processing corridor, with canneries expanding pouch conversion lines.
Indonesia
Archipelagic catch proximity reduces transport legs for Indian Ocean yellowfin and skipjack landings. Ministry of Marine Affairs and Fisheries traceability mandates require catch documentation scheme integration for export eligibility. Bitung and Ambon emerging as rival processing hubs to Thai dependence, with cold-storage capacity additions accelerating.
United States
Pantry stockpiling behavior in California and Texas sustains white meat albacore demand through wholesale club channels. NOAA dolphin-safe labeling requirements enforce net deployment log documentation for all imported product. American Samoa canneries face volume pressure as mainland distributors consolidate procurement authority.
South Korea
Premium solid-pack positioning in Seoul and Busan retail favors texture-intact loin products for household consumption. MFDS refrigeration standards constrain cold-chain energy profiles for pre-canning frozen inventory. Dongwon Industries anchors volume leadership from Busan-Ulsan processing infrastructure, extending fleet presence into Southeast Asian waters.
Canned Tuna Market Key Industry Players
Concentration sits with vertically integrated fleet operators and brand-holding processors. The structure tiers between captive raw material access and retail brand equity. Strategic archetypes include Pacific basin fleet owners with canning assets, North American brand licensors with co-manufacturing networks, and European private-label specialists. Competitive moves center on pouch format capacity conversion and sustainability certification acquisition.
Within the integrated-fleet tier, Thai Union Group and Dongwon Industries exemplify upstream control over skipjack and yellowfin supply. Bumble Bee Foods occupies a position as a brand-centric North American operator. These three anchors illustrate the divergence between raw material security and channel-dependent positioning.
| Leading Market Players |
|---|
| Thai Union Group |
| Century Pacific Food |
| Bumble Bee Foods |
| Dongwon Industries |
| Bolton Food |
| StarKist Co. |
| Grupo Calvo |
| Frinsa |
| Jealsa |
| Others |
Cost & Logistics Intelligence
Pouch packaging displacement of metal can formats simultaneously redraws processing geography toward Southeast Asian pouch converters and compresses per-unit economics through reduced shipping weight and elimination of captive can manufacturing overhead.
Pricing Analysis
Volume-discount tiering structures separate institutional foodservice procurement from household retail channels. Three-tier pricing stratifies across Marine Stewardship Council-certified premium, standard dolphin-safe compliance, and economy-grade commodity tiers. Pricing pressure stems from skipjack price volatility in Western Pacific landings transmitting directly into raw material cost instability. Foodservice operators exhibit highest price sensitivity due to centralized procurement authority, while subscription replenishment channels show lowest sensitivity due to convenience premiums.
Supply Chain Analysis
Strait of Malacca transit chokepoints underwrite Thai and Indonesian processing hub dominance for Indian Ocean catch flows. Raw material supply draws from Philippines, Indonesia, and Taiwan-flag purse-seine fleets. Single-source vulnerability concentrates in Thai Union Group and Dongwon Industries fleet control over Western Pacific skipjack access. Distribution runs through broadline foodservice distributors consolidating purchasing authority across Bangkok, Manila, and Jakarta metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with sustainability-certified niche positioning as foodservice procurement centralization creates tiered entry points below integrated-fleet scale.
For Market Incumbents: Compound defensive positioning through backward integration into Indonesian cold-storage capacity and accelerated Marine Stewardship Council certification acquisition. Fleet-to-can operators face margin compression from pouch format converters capturing format innovation premiums. Priority lever rests on electronic monitoring system deployment locking out non-compliant suppliers from raw material access. For New Entrants and Emerging Players: Anchor in Indonesian archipelagic processing underpenetration where Indian Ocean catch proximity shortens transport legs versus Thai hub dependence. White-space targets include subscription replenishment channel bypass of wholesale markups and specialty retail Marine Stewardship Council-certified positioning. Go-to-market angle emphasizes direct-to-pantry e-commerce fulfillment with algorithmic replenishment recommendations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fleet operators with cold-chain infrastructure and sustainability certification portfolios. Long-term viability across the analysis window hinges on regulatory traceability compliance as contract eligibility gate. Acquisition target archetype encompasses Indonesian processing assets with archipelagic landing proximity. Signal to watch: E.U. IUU Regulation enforcement intensity tightening raw material access for non-compliant processors.| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Format Capacity Conversion | Retort pouch technology captures 40% shipping weight reduction versus metal formats for Japanese e-commerce fulfillment. |
| Marine Stewardship Council Certification Acquisition | MSC labeling gates retail and foodservice contract eligibility across North American and European procurement specifications. |
| Electronic Monitoring System Deployment | Vessel-level traceability hardware satisfies NOAA dolphin-safe and E.U. IUU documentation requirements for net deployment logs. |
| Indonesian Cold-Storage Expansion | Bitung and Ambon hub capacity additions rival Thai dependence for Indian Ocean yellowfin and skipjack landings. |
| Subscription Replenishment Model Launch | Direct-to-pantry channels bypass traditional retail slotting fees and capture recurring revenue streams from pantry stockpiling behavior. |
Research Approach
Desk research of customs trade records, fisheries landing databases, and regulatory filing precedents preceded structured interviews with fleet operations managers, cannery procurement directors, foodservice distributor category buyers, and sustainability certification auditors. Primary fieldwork across Bangkok, General Santos City, and Jakarta processing corridors combined with secondary validation against Thai FDA, Philippines Bureau of Fisheries and Aquatic Resources, and Indonesian Ministry of Marine Affairs and Fisheries documentation. Bottom-up volume modeling triangulated against top-down value chain analysis.
Variance decomposition across product type, packaging format, distribution channel, and end-user segmentation dimensions structured the analytical framework. Modeled CAGRs derived from historical volume trajectories, capacity expansion pipelines, and regulatory compliance cost absorption rates across the projection horizon. Industry-specific forecast inputs incorporated skipjack price volatility indices and cold-chain energy cost profiles under E.U. F-Gas Regulation phase-down schedules.
Material uncertainties — Western Pacific purse-seine catch fluctuations, regional fisheries management measure tightening, and refrigerant technology transition timelines — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued dolphin-safe certification adherence and foodservice procurement centralization trajectories. Practitioners should keep alternative scenarios live as E.U. IUU Regulation enforcement intensity and Indonesian processing hub development evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Europe Lobster Market
Seafood
North America Frozen and Canned Seafood Market
Seafood
Global Shrimp Market
Seafood
Seafood Extracts Market
Seafood
Rainbow Trout Market
Seafood
Surimi Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Tuna Market
Seafood
Food Clamshells Market
Seafood
Japan Frozen Seafood Market
Seafood
Smoked Salmon Market
Seafood
Caviar Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Fish Meal Market
Seafood
Europe Shrimp Market