
 Organic Seafood Market | 2026-2036
Organic Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Seafood Market Intelligence
Market Context with Strategic Players
Premium organic salmon pricing is shifting away from conventional farmed benchmarks as certification costs and feed traceability requirements widen the gap between tiers. Mowi ASA leverages its integrated feed-to-retail operations to secure consistent organic supply across European markets. Cooke Aquaculture Inc. anchors its position through specialized organic hatcheries in Atlantic Canada and Scotland. Glenarm Organic Salmon Ltd. differentiates via small-batch production with direct distribution to UK specialty retailers.
Technical Definition and Structural Segments
Organic seafood denotes aquatic organisms raised or harvested without synthetic pesticides, antibiotics, or genetically modified feed, meeting third-party certification standards for water quality, stocking density, and feed composition. The category serves commercial buyers seeking verified provenance for health-conscious consumers and regulatory-compliant food service procurement. Fish dominates product type segmentation due to established salmonid farming infrastructure, while shellfish represents the fastest-expanding category driven by lower organic conversion costs and strong restaurant demand. Distribution channel structure favors supermarkets for volume throughput, though online retail captures margin-rich direct-to-consumer sales with full traceability documentation.
Regulatory Frame and Forward Outlook
USDA Organic, EU Organic, and Marine Stewardship Council standards govern market access across North America and Europe, with certification audits now requiring continuous water quality monitoring and feed ingredient chain-of-custody records. The EU F-Gas Regulation and national aquaculture licensing boards in Norway and Scotland further constrain production expansion, tightening supply eligibility. Stakeholders must monitor evolving feed ingredient rules, particularly around fishmeal substitution thresholds, to maintain certification continuity and premium price realization.
Market Dynamics
EU F-Gas Regulation and tightening EU Organic feed traceability mandates are compressing certified supply eligibility faster than cold-water aquaculture capacity can expand, forcing buyers into longer-term offtake contracts with accredited Norwegian and Scottish producers.
Growth Catalysts
- EU Organic Regulation stringency:Third-party certification requirements for water quality and stocking density are locking in premium pricing tiers that reward early compliance investments by established Atlantic salmon farmers.
- Shellfish conversion economics:Lower organic certification costs for bivalve operations relative to finfish are accelerating restaurant procurement of certified oysters and mussels across upscale dining segments.
- Norwegian licensing boards:National aquaculture permit constraints are limiting new entrant supply, protecting margin structures for incumbent certified organic producers with grandfathered site authorizations.
Market Restraints
- Fishmeal substitution thresholds:EU Organic rules capping non-marine feed ingredients are elevating input costs for organic salmon feed formulations relative to conventional aquafeed benchmarks.
- Cold-water geography concentration:Scalable organic salmon production remains tethered to Norwegian fjords, Scottish lochs, and Irish bays, exposing supply chains to localized disease or thermal events.
- Antibiotic-free mortality risk:Prohibition of synthetic treatments under organic standards elevates biological risk during viral outbreaks, compressing achievable stocking densities and unit yields.
Strategic Opportunities
- Online retail traceability:Direct-to-consumer channels with blockchain-verified catch documentation are capturing margin-rich sales from health-conscious households seeking provenance transparency.
- USDA Organic recognition:Emerging equivalency agreements between EU and US organic standards are opening transatlantic export pathways for certified Irish and Scottish producers.
- Integrated multi-trophic systems:Seaweed-bivalve-finfish polyculture operations are reducing feed input intensity while generating additional certified organic revenue streams from kelp biomass.
Industry Challenges
- Continuous monitoring infrastructure:Certification audits now mandate real-time water quality telemetry, requiring capital deployment into sensor networks and data logging systems across dispersed marine sites.
- Feed ingredient chain-of-custody documentation:Organic standards require batch-level traceability from hatchery to harvest, forcing legacy operations to reconstruct supplier documentation retroactively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Seafood Market |
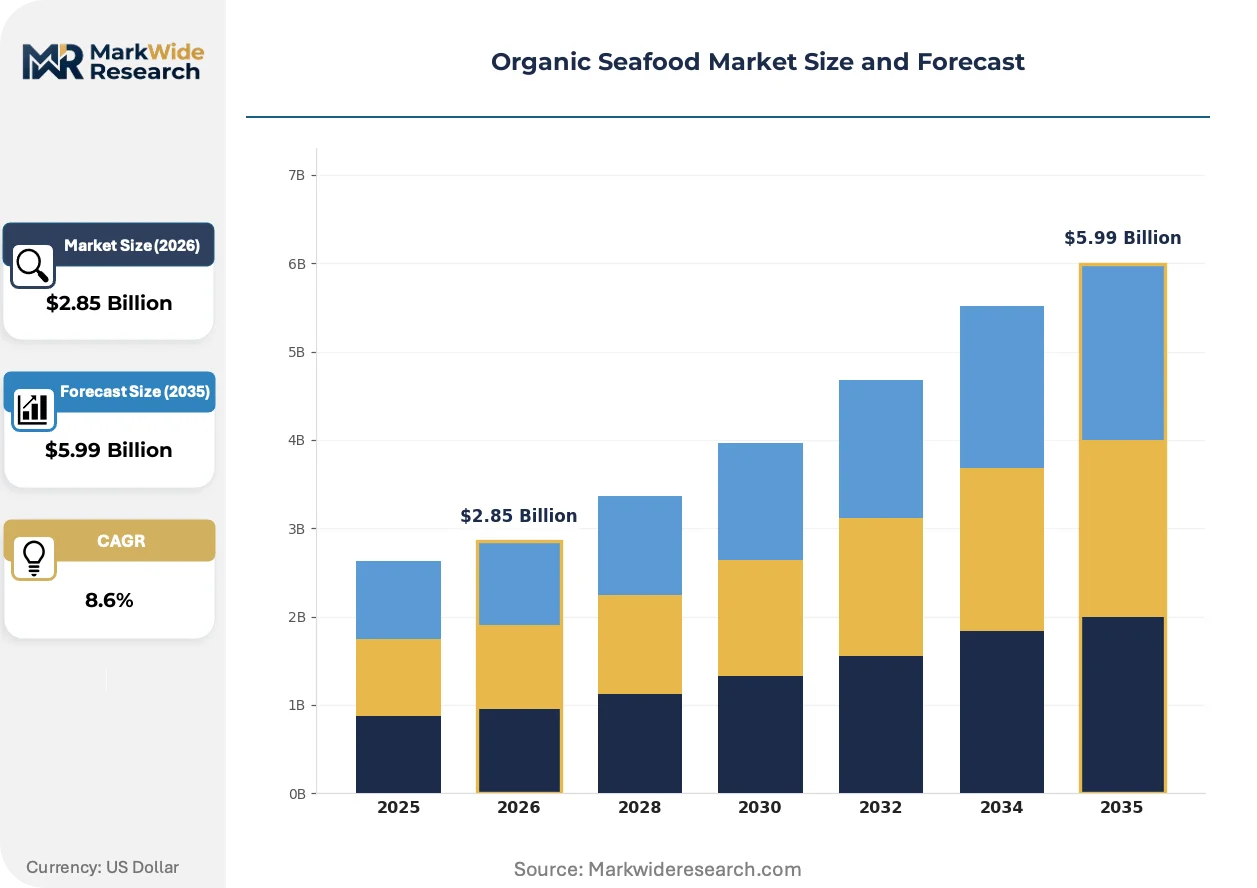
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shellfish, Cephalopods, Crustaceans Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Restaurants End User: Household, Food Service, Cafes, Catering Services Certification: USDA Organic, EU Organic, Marine Stewardship Council, Aquaculture Certification |
| Companies Covered | Loch Duart Ltd., Valhalla Salmon, Mowi ASA, Cooke Aquaculture Inc., The Irish Organic Salmon Company Ltd., Leroy Seafood Group ASA, Glenarm Organic Salmon Ltd., Scottish Salmon Company (Bakkafrost), SalMar ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Seafood Market Strategic Shifts & Innovations
Automation and remote sensing technologies are compressing the labor intensity of organic certification compliance, while regulatory convergence between EU and North American standards is reshaping export market access for accredited producers.
Recirculating aquaculture systems with closed-loop water treatment are electrifying organic salmon production by enabling land-based operations outside traditional cold-water coastal zones. Dutch and Danish engineering firms are deploying these systems for premium retail contracts. The technology is electrifying geographic diversification away from fjord-dependent supply concentration.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are forcing cold-chain logistics providers serving organic seafood to retrofit processing and transport infrastructure. Industrial consequence includes accelerated capital expenditure cycles for certified organic distributors. Nordic and Baltic logistics clusters are responding with ammonia-based refrigeration retrofits to maintain organic handling eligibility.
Certification-driven preference shifts are displacing conventional farmed salmon in upscale restaurant procurement specifications. Chefs in Copenhagen, London, and New York are rewriting menu sourcing criteria around Marine Stewardship Council and EU Organic dual certification. This behavioral pivot is most visible in Michelin-starred dining segments where provenance documentation carries direct pricing power.
Organic Seafood Market Segmentation
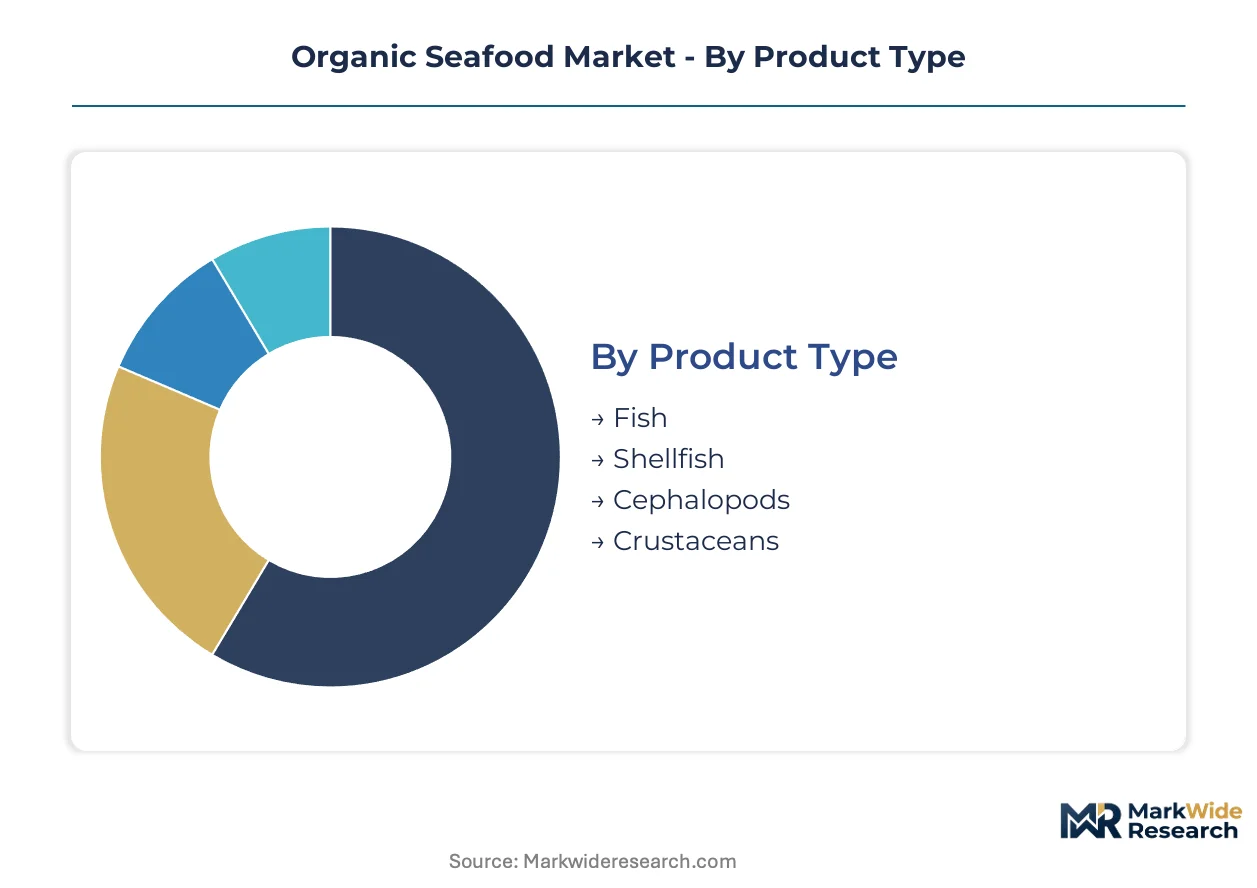
Organic seafood segmentation reflects divergent cost structures across species and the premium capture potential of certification-backed distribution channels. Buyers sort procurement by biological complexity, cold-chain requirements, and end-use provenance documentation needs.
Product Type:
Fish commands volume throughput while shellfish delivers margin expansion through lower certification conversion costs.
- Fish:Salmonids dominate organic finfish output, with Norwegian and Scottish producers leveraging established cold-water aquaculture infrastructure for scalable certified supply. Premium restaurant buyers in Copenhagen, London, and New York specify Marine Stewardship Council dual certification for menu placement.
- Shellfish:Bivalve operations achieve organic certification at substantially lower feed traceability cost than finfish, accelerating procurement across upscale dining segments. Irish and Scottish oyster producers capture direct-to-restaurant contracts through simplified batch-level documentation.
- Cephalopods:Wild-capture dominates with limited organic aquaculture scale; certification concentrates on Mediterranean and Japanese coastal fisheries with existing sustainability audit infrastructure.
- Crustaceans:Organic shrimp farming faces elevated feed ingredient scrutiny under EU Organic rules, constraining supply eligibility to Ecuadorian and Vietnamese operations with integrated hatchery control.
Today's leader: Fish. Tomorrow's challenger: Shellfish.
Distribution Channel:
Channel selection determines margin capture versus volume throughput, with traceability infrastructure requirements filtering participant eligibility.
- Supermarkets:Volume throughput anchors retail organic seafood sales, with EU and UK chains requiring continuous cold-chain telemetry for shelf placement. Major multiples leverage centralized distribution to amortize certification audit costs across high-turnover SKUs.
- Online Retail:Direct-to-consumer channels with blockchain-verified documentation command premium pricing from health-conscious households seeking provenance transparency. Nordic and Baltic logistics clusters invest in ammonia-based refrigeration retrofits to maintain EU F-Gas Regulation compliance.
- Specialty Stores:Independent fishmongers and organic grocers in Germany, France, and the Netherlands curate small-batch certified supply for discerning local clientele.
- Restaurants:Michelin-starred dining segments rewrite sourcing criteria around dual certification, with chefs in Copenhagen and London specifying verified organic salmon and shellfish for menu differentiation.
Supermarkets anchor current volume. Online retail climbs fastest on margin expansion.
End User:
Procurement sophistication varies sharply between household convenience purchasing and food service compliance requirements.
- Household:Retail buyers prioritize convenience and price accessibility, with supermarket penetration highest in Germany, France, and the UK where organic labeling recognition is mature.
- Food Service:Upscale restaurant and hotel procurement departments mandate third-party certification documentation for supplier qualification, with EU Organic and Marine Stewardship Council dual standards increasingly specified in contract tenders.
- Cafes:Limited organic seafood penetration due to menu simplicity and cost constraints; specialty coffee chains in Scandinavian markets represent niche adoption.
- Catering Services:Event and institutional catering face compressed margins that limit organic premium absorption, though corporate sustainability mandates in the Netherlands and Denmark drive selective procurement.
Food service leads on certification compliance investment. Household represents the broadest addressable base.
Certification:
Regulatory convergence between EU and North American standards is reshaping export market access for accredited producers.
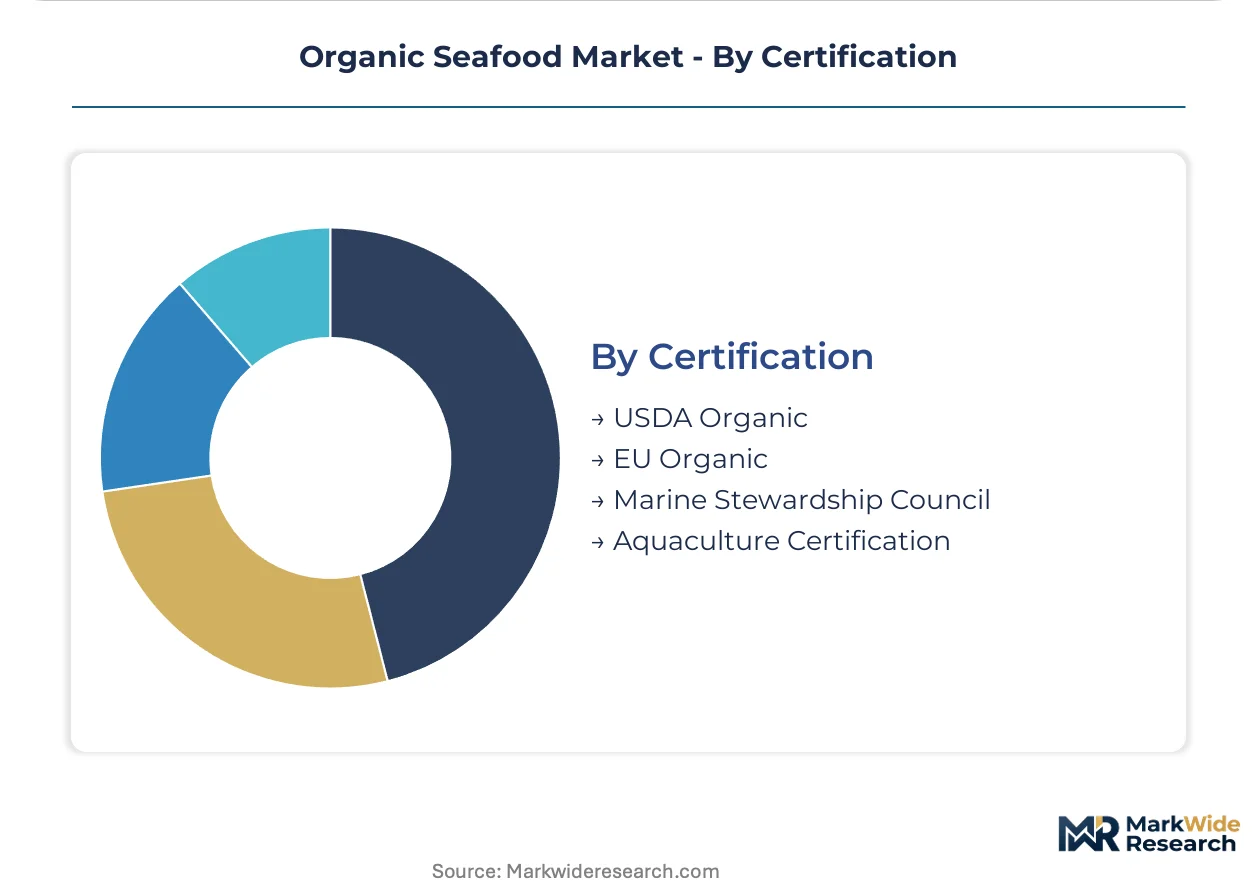
- USDA Organic:US federal standard governs North American market access, with emerging equivalency agreements opening transatlantic pathways for certified Irish and Scottish producers. Feed ingredient chain-of-custody documentation requirements match EU stringency.
- EU Organic:Third-party audits mandate real-time water quality monitoring and stocking density verification, locking in premium pricing tiers that reward early compliance investments. Norwegian licensing boards reference EU Organic standards for national permit conditions.
- Marine Stewardship Council:Wild-capture sustainability certification complements organic aquaculture labels in dual-certified retail and restaurant positioning, particularly valued in UK and German markets.
- Aquaculture Certification:Species-specific and regional standards fill gaps between comprehensive organic frameworks, with ASC certification gaining traction in Asian export markets.
EU Organic sets the compliance ceiling today. USDA Organic equivalence unlocks tomorrow's transatlantic volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands certified organic salmon volume through fjord-based infrastructure, while Scotland leverages loch systems and stricter national licensing to capture premium pricing tiers. Ireland and Canada are expanding cold-water capacity, though regulatory stringency varies sharply across North Atlantic jurisdictions.
Norway
Salmonid buyers in Copenhagen and London specify Norwegian-origin organic supply for menu placement, with Leroy Seafood Group and SalMar anchoring certified output. The Norwegian Food Safety Authority enforces aquaculture site licensing that limits new entrant expansion, protecting incumbent margin structures. Bergen and Trondheim harbor clusters concentrate feed-to-harvest integration for EU Organic compliance.
Scotland
Scottish loch systems support scalable organic conversion with lower thermal risk than southern European waters, attracting UK supermarket procurement contracts. The Scottish Environment Protection Agency references EU Organic stocking density rules for national discharge permits. Shetland and Western Isles processing hubs maintain cold-chain telemetry for Marine Stewardship Council dual certification.
Ireland
Irish bays offer organic shellfish conversion economics that outpace finfish certification timelines, accelerating oyster and mussel restaurant contracts. The Department of Agriculture, Food and the Marine administers organic aquaculture licensing aligned with EU feed traceability mandates. Cork and Galway harbor operations supply direct-to-restaurant channels across London and Paris.
Canada
New Brunswick and Newfoundland cold-water sites enable North American organic salmon production outside European supply concentration. Health Canada and the Canadian Food Inspection Agency coordinate organic equivalency discussions with USDA to unlock transatlantic export pathways. Cooke Aquaculture anchors Atlantic Canada operations with specialized organic hatchery infrastructure.
United States
Pacific Northwest and Maine coastal operations serve domestic organic seafood demand with shorter cold-chain legs than imported supply. The USDA National Organic Program governs certification with feed ingredient documentation matching EU stringency. Seattle and Portland metro areas concentrate direct-to-consumer online retail with blockchain-verified provenance systems.
Organic Seafood Market Key Industry Players
Top-tier vendors anchor integrated feed-to-retail operations, while mid-scale specialists compete on batch-level traceability and regional certification speed. The vendor base stratifies across Norwegian-Scottish volume players, Irish-Canadian mid-tier converters, and niche single-site operators. Three archetypes dominate: integrated multinationals with captive feed mills, regional specialists with direct distribution relationships, and small-batch producers with Michelin-channel positioning. Competitive moves concentrate on backward integration into hatchery control and ammonia-based cold-chain retrofits for EU F-Gas Regulation compliance.
Among Norwegian-Scottish volume leaders, Mowi ASA and Scottish Salmon Company exemplify integrated archetypes with fjord-to-shelf operations. Cooke Aquaculture occupies a position spanning North Atlantic geography with specialized organic hatcheries in Atlantic Canada and Scotland. Glenarm Organic Salmon Ltd. represents the small-batch specialist tier with direct UK specialty retail relationships.
| Leading Market Players |
|---|
| Loch Duart Ltd. |
| Valhalla Salmon |
| Mowi ASA |
| Cooke Aquaculture Inc. |
| The Irish Organic Salmon Company Ltd. |
| Leroy Seafood Group ASA |
| Glenarm Organic Salmon Ltd. |
| Scottish Salmon Company (Bakkafrost) |
| SalMar ASA |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps in Atlantic Canada and coastal Ireland anchor supply discipline through patient capital allocation, insulating organic seafood pricing from quarterly earnings pressure that erodes feed quality in publicly traded volume players.
Pricing Analysis
Certification-bundled pricing separates EU Organic-verified salmon from conventional farmed benchmarks, with feed traceability costs and stocking density compliance widening spreads between tiers. Price differentiation rests on Marine Stewardship Council dual certification and geographic proximity to Copenhagen and London restaurant clusters. Pricing pressure intensifies in shellfish segments where Irish and Scottish oyster producers compete for direct-to-restaurant contracts. Food service buyers exhibit lowest price sensitivity due to menu premiumization mandates, while supermarket procurement teams in Germany and France drive volume-tier negotiation.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian fjord-based smolt supply, where national licensing boards constrain hatchery expansion faster than grow-out capacity. Production concentrates in Norway, Scotland, and Ireland, with Canadian operations scaling in New Brunswick and Newfoundland. Feed formulation draws from marine ingredient suppliers in Peru and Chile, plus non-marine protein sources facing EU Organic substitution caps. Tariff exposure looms for transatlantic shipments pending USDA-EU equivalency finalization. Distribution runs through ammonia-refrigerated Nordic and Baltic logistics clusters serving EU F-Gas Regulation compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic seafood functions as a stable compounder where regulatory ratcheting on feed traceability and water quality standards perpetually tightens eligible supply, protecting incumbent pricing power through compliance moats rather than commodity cycles.
For Market Incumbents: Deepen backward integration into captive hatchery control to secure smolt supply against Norwegian licensing constraints. Expand ammonia-based cold-chain infrastructure ahead of EU F-Gas Regulation phase-down deadlines. Certification investment in dual Marine Stewardship Council standards defends menu positioning against emerging Irish shellfish specialists. For New Entrants and Emerging Players: The premium-to-economy gap in organic salmon pricing creates entry space for land-based recirculating aquaculture systems outside fjord-dependent geographies. Target Dutch and Danish engineering partnerships for closed-loop facility deployment. White-space concentrates in direct-to-consumer online retail with blockchain-verified provenance documentation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Irish and Canadian operators with grandfathered site authorizations and incomplete certification documentation. Long-term viability favors assets with integrated feed-to-harvest control and established EU Organic audit trails. Watch for USDA-EU equivalency agreement finalization as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery Capacity Expansion | Norwegian licensing board constraints protect margin structures for early movers with site authorizations. |
| Ammonia Refrigeration Retrofit | EU F-Gas Regulation compliance maintains organic handling eligibility across Nordic logistics clusters. |
| Dual Certification Investment | Marine Stewardship Council plus EU Organic unlocks Michelin-starred restaurant procurement specifications. |
| Land-Based RAS Deployment | Closed-loop systems electrify geographic diversification away from fjord supply concentration. |
| Blockchain Traceability Integration | Direct-to-consumer channels capture premium pricing from health-conscious households seeking provenance transparency. |
Research Approach
Multiple input streams — executive interviews with aquaculture operations directors, regulatory affairs leads at certification bodies, and procurement managers at UK and German supermarket chains — were reconciled against secondary validation from EU Organic audit records, Marine Stewardship Council certification databases, Norwegian Food Safety Authority licensing disclosures, and trade flow data from Bergen and Trondheim harbor clusters. Bottom-up volume modeling across hatchery-to-harvest stages triangulated with top-down expenditure analysis from food service and retail channels.
Data-stream reconciliation anchored forecast construction across product type, distribution channel, and certification tier dimensions, with geographic production clusters modeled separately for fjord-based versus land-based operations. CAGRs were derived from elasticity-adjusted demand projections and supply-constrained capacity expansion timelines. Feed ingredient cost trajectories under EU Organic substitution rules and cold-chain capital expenditure cycles informed scenario boundaries.
Caveats apply where disease outbreaks in concentrated Norwegian fjord systems, abrupt EU feed traceability mandate tightening, or transatlantic trade policy shifts could materially shift the outlook. Forecasts reflect documented assumptions about certification continuity and licensing board behavior. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Dried Scallop Market
Seafood
Europe Seafood Market
Seafood
Latin America Salmon Market
Seafood
Crustacean Market
Seafood
United States Salmon Market
Seafood
Seafood Extracts Market
Seafood
Europe Shrimp Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
GCC Seafood Market
Seafood
Europe Salmon Market
Seafood
Tinned Fish Market
Seafood
Surimi by-Product Market
Seafood
Halibut Market
Seafood
Mussel Oil Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Global Smoked Fish Market