
 Seafood Processing Market | 2026-2036
Seafood Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Seafood Processing Market Outlook
Portion-controlled retail packs and individually quick-frozen (IQF) fillet configurations is broadening buyer choice across supermarkets and food service channels. Maruha Nichiro Corporation leverages integrated cold-chain logistics from vessel to shelf across Japan and Southeast Asia. Mowi ASA anchors Atlantic salmon farming and processing scale from Norway to Scotland. Thai Union Group PCL differentiates through vertical ownership of tuna supply from Thai canneries to European retail private label.
Seafood processing encompasses the transformation of raw marine and aquaculture harvests into shelf-stable, refrigerated, or frozen products through mechanical filleting, thermal treatment, salting, smoking, or controlled-atmosphere packaging for human consumption. Critical parameters include HACCP compliance, core temperature maintenance below minus 18 degrees Celsius for frozen goods, and residual moisture content below 60 percent for dried products to inhibit microbial proliferation. Frozen seafood commands the largest value share among product types due to extended distribution reach and reduced spoilage rates, while canned seafood retains stable margin pools in emergency stockpiling and military procurement channels. Shellfish processing exhibits the fastest structural expansion driven by automated shucking technologies and rising consumer preference for ready-to-eat crustacean formats in Asian and European retail.
FDA's Seafood HACCP Regulation and the EU's IUU Regulation shape import compliance costs and traceability infrastructure investments for processors serving trans-Atlantic trade lanes. ISO 22000 certification and ASC chain-of-custody standards increasingly gate access to premium retail and food service contracts in North America and Europe. Stakeholders must monitor evolving digital traceability mandates and cold-chain energy costs as determinants of processing location decisions and export market eligibility.
Market Dynamics
Traceability mandates and cold-chain energy costs are forcing processors to consolidate operations near aquaculture clusters while rewiring supplier relationships across trans-Atlantic trade lanes.
Growth Catalysts
- EU IUU Regulation:The EU's Illegal, Unreported and Unregulated Fishing Regulation tightens catch certification requirements, accelerating investment in blockchain-based tracking systems among Vietnamese and Thai exporters seeking European retail contracts.
- Automated shucking technologies:Robotics for crustacean processing cuts labor intensity by half, enabling shellfish processors to scale ready-to-eat formats for Asian supermarket chains.
- Food service procurement:North American restaurant groups are expanding direct sourcing of IQF fillet portions, bypassing traditional wholesale layers for freezer-to-fryer operational efficiency.
Market Restraints
- Input cost volatility:Wild-capture raw material prices swing with quota allocations and fuel costs, compressing margin predictability for Atlantic whitefish processors dependent on Icelandic and Norwegian landings.
- Supply concentration risk:Vietnam's Mekong Delta hosts over sixty percent of global pangasius fillet capacity, creating single-point vulnerability for buyers during monsoon flooding or disease outbreaks.
- Regulatory friction:FDA Seafood HACCP compliance timelines stretch fourteen to eighteen months for new facility approvals, freezing capital deployment for emerging market entrants.
Strategic Opportunities
- Underpenetrated African markets:Cold-chain infrastructure gaps in West African coastal cities present first-mover openings for frozen pelagic processors establishing hub-and-spoke distribution from Senegal and Morocco.
- Regulatory tailwind:Japan's METI carbon-neutral port initiatives subsidize energy-efficient processing equipment retrofits, lowering operational expenditure for exporters serving Tokyo and Osaka retail.
- Technology convergence:Hyperspectral imaging combined with AI grading is unifying quality assessment and species verification into single-pass inspection lines, cutting labor and fraud risk simultaneously.
Industry Challenges
- HACCP auditor scarcity:Qualified seafood safety assessors concentrate in Western Europe and North America, creating bottlenecks for Southeast Asian and Latin American facilities seeking export certification.
- Legacy ERP integration:Mid-scale processors running decade-old inventory systems face twelve-to-eighteen-month migration timelines to connect with retailer traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seafood Processing Market |
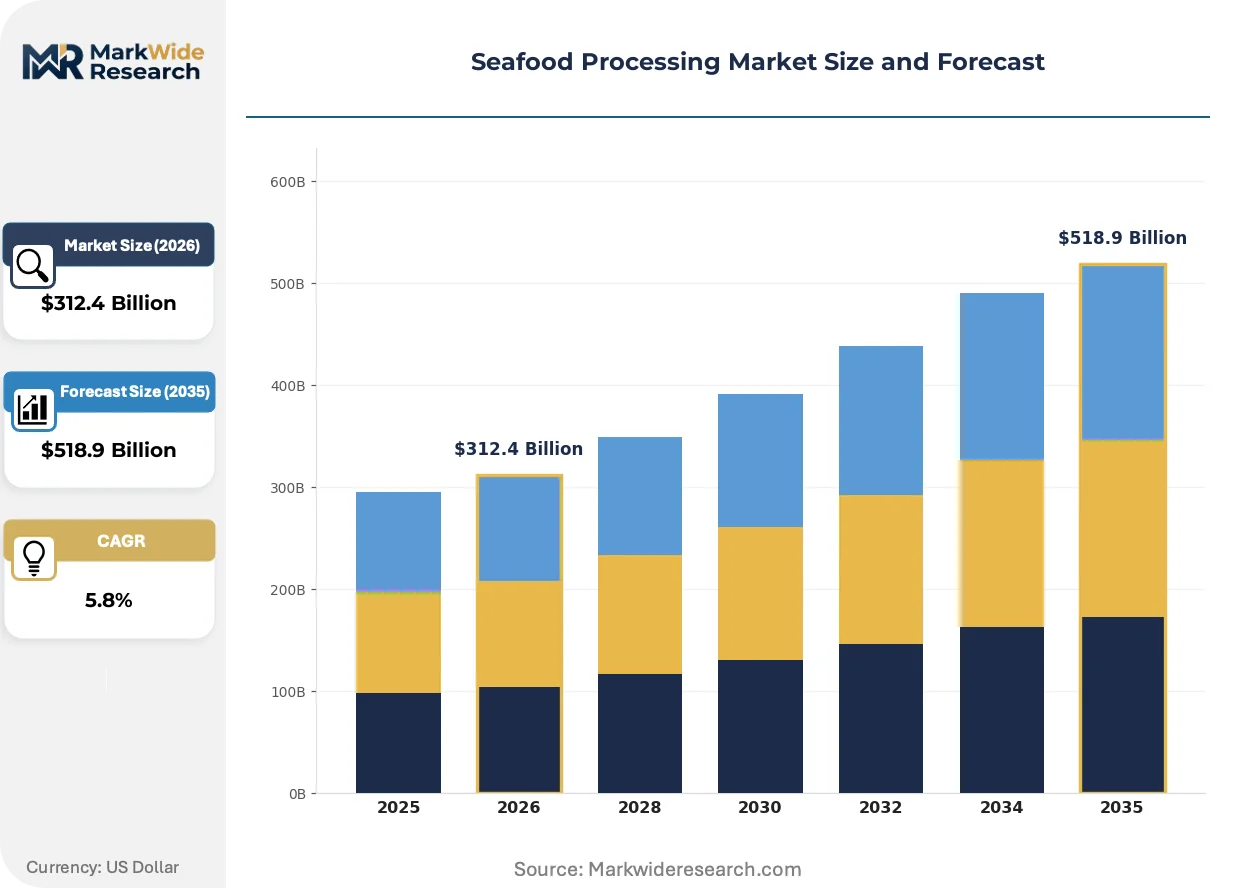
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $518.9 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shellfish, Canned Seafood, Frozen Seafood Processing Method: Filleting, Smoking, Salting, Canning End User: Restaurants, Retailers, Food Service Providers, Exporters Distribution Channel: Direct Sales, Online Retail, Wholesale, Supermarkets |
| Companies Covered | Maruha Nichiro Corporation, Mowi ASA, Thai Union Group PCL, Trident Seafoods Corporation, High Liner Foods, Nippon Suisan Kaisha (Nissui), Marubeni Corporation, Clearwater Seafoods, Lerøy Seafood Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seafood Processing Market Strategic Shifts
Digital traceability infrastructure and energy transition pressures are rewiring how processors validate origin claims and power their operations. These shifts favor capital-rich operators capable of absorbing compliance and retrofit costs.
Blockchain-enabled catch documentation is unifying vessel data, processing records, and retail scanning into immutable ledgers. Major European supermarket chains now require this interoperability for private-label seafood contracts. The technology is compressing audit cycles from weeks to hours while exposing supply gaps for non-compliant competitors.
The EU's Corporate Sustainability Reporting Directive expands disclosure requirements for seafood importers on scope-three emissions and labor practices. Processors serving Dutch and German retail must now integrate supplier questionnaires into quarterly filings. Smaller Vietnamese and Indonesian exporters are consolidating to afford dedicated compliance staff.
Direct procurement between processors and food service operators is displacing layered distributor relationships. Large North American restaurant chains now contract frozen portion suppliers for multi-year volume commitments with price collars. This concentration is most visible in the quick-service seafood segment, where buyers prioritize freezer-to-fryer consistency over origin flexibility.
Seafood Processing Market Segmentation
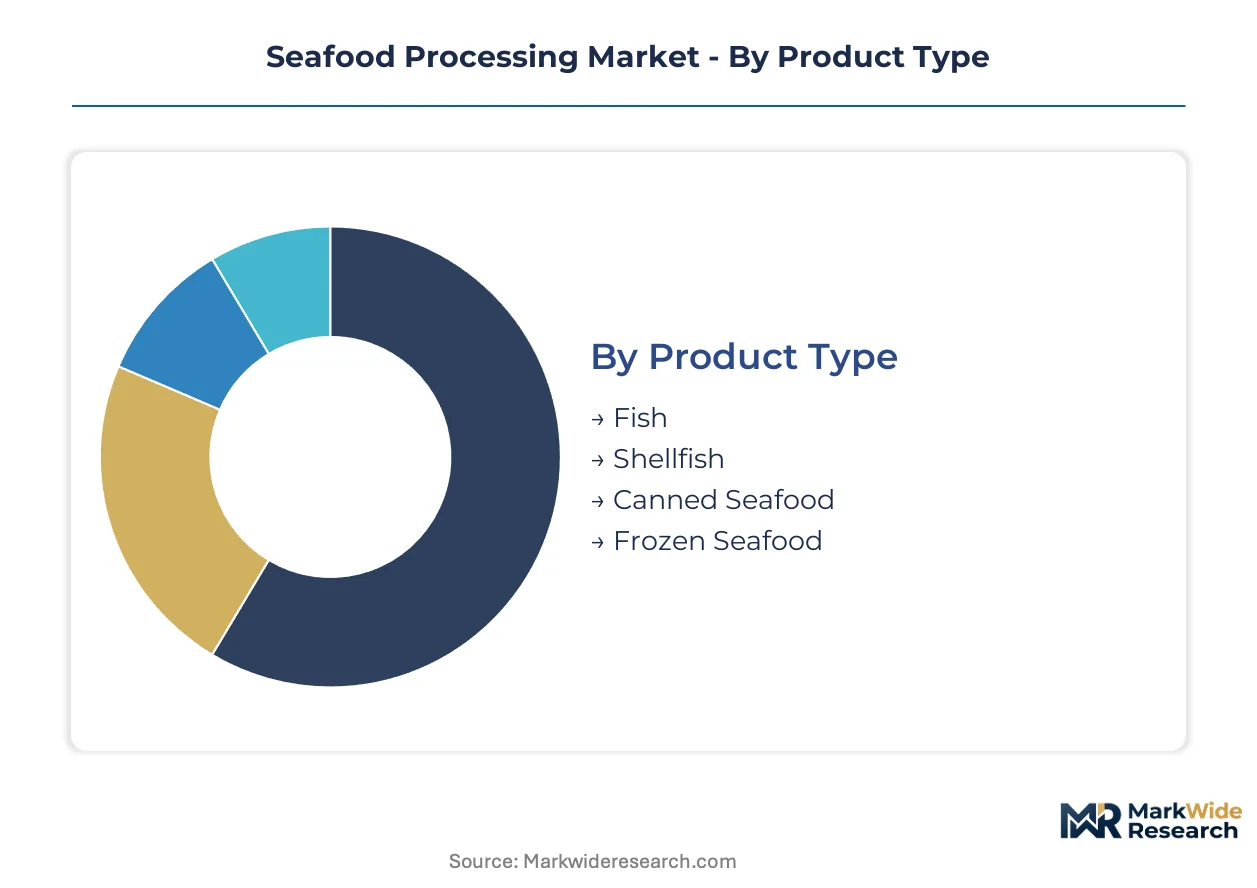
Segmentation in seafood processing reveals how product format, preservation technology, and channel structure determine margin capture and capital intensity. Processors optimize equipment configuration and cold-chain investment based on which segments they target.
Product Type:
Thermal stability and moisture content specifications differentiate shelf-life economics across marine species categories.
- Fish:Whitefish species dominate mechanized filleting lines with core temperature maintenance below minus 18 degrees Celsius for frozen distribution. Atlantic cod and Alaskan pollock concentrate in North American quick-service restaurant procurement for standardized portion control.
- Shellfish:Automated shucking technologies reduce labor intensity for crustacean processing, enabling ready-to-eat crab and shrimp formats. Vietnamese and Thai exporters deploy robotics to meet European retail traceability mandates for peeled shrimp.
- Canned Seafood:Retort thermal treatment delivers shelf stability above 24 months, anchoring emergency stockpiling and military procurement channels. Tuna and sardine dominate Thai and Ecuadorian cannery output.
- Frozen Seafood:Individually quick-frozen fillet portions command premium positioning in supermarket retail through reduced spoilage rates and extended distribution reach. Pangasius from Vietnam's Mekong Delta clusters supplies European food service.
Mature deployment sits with frozen seafood. Newer deployment is concentrated in shellfish automation.
Processing Method:
Capital intensity and labor substitution potential vary sharply by preservation technology.
- Filleting:Mechanized descaling and pin-bone removal systems achieve throughput above 20 tons per hour in Norwegian and Scottish salmon facilities. Portion-cutting robotics reduce yield loss to under 12 percent.
- Smoking:Controlled-atmosphere kilns with electronic temperature profiling enable consistent flavor delivery for Scottish and Norwegian salmon. Cold-smoked formats dominate deli retail in German and French supermarkets.
- Salting:Brine injection and dry-cure systems preserve moisture below 60 percent for dried cod and mackerel. Iberian and Japanese traditional processors maintain artisan positioning alongside industrial scale.
- Canning:Retort sterilization at 121 degrees Celsius eliminates Clostridium botulinum risk in tuna and sardine packs. Thai and Ecuadorian facilities run continuous lines above 500 cans per minute.
High-volume automation concentrates in filleting. Premium positioning clusters in smoking.
End User:
Procurement specifications and traceability requirements diverge by customer type.
- Restaurants:Quick-service chains specify IQF portion packs with freezer-to-fryer consistency, bypassing wholesale layers for direct processor contracts. North American burger chains drive standardization.
- Retailers:European supermarket private-label programs mandate blockchain traceability and ASC chain-of-custody certification. Dutch and German chains enforce strictest supplier questionnaires.
- Food Service Providers:Institutional caterers and hospital systems prioritize HACCP documentation and extended shelf-life formats. Japanese and South Korean contract food service drives portion-control innovation.
- Exporters:Re-export hubs in Morocco and Senegal aggregate West African pelagic catch for EU and Middle East markets. Cold-chain infrastructure gaps limit direct retail penetration.
Traceability investment concentrates in retail. Volume scale dominates restaurant procurement.
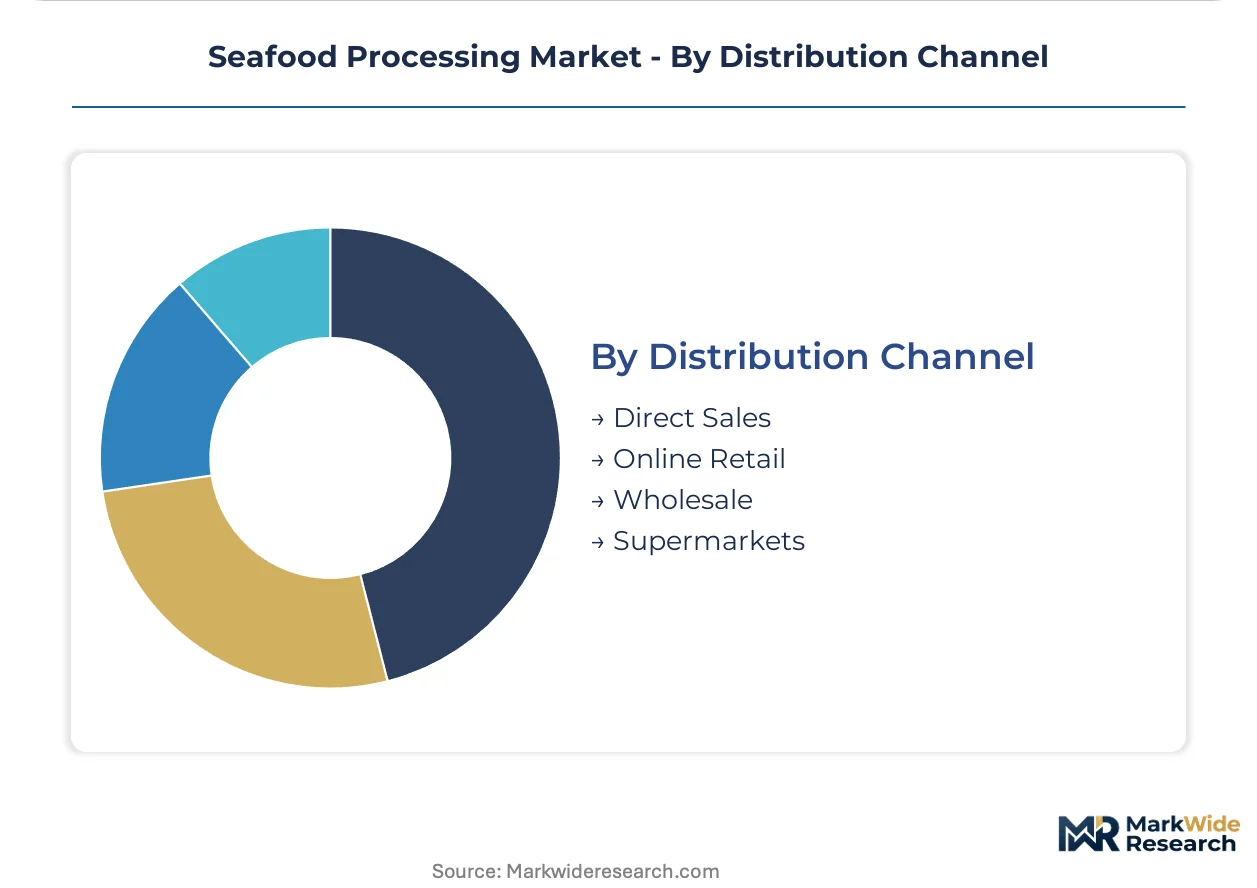
Distribution Channel:
Channel selection determines margin retention and brand exposure.
- Direct Sales:Processor-to-restaurant contracts eliminate distributor margins, favoring large-scale fillet suppliers with multi-year volume commitments. North American seafood chains lead this displacement.
- Online Retail:E-commerce penetration for frozen seafood remains constrained by last-mile cold-chain reliability. Japanese and South Korean platforms show highest adoption for premium gift boxes.
- Wholesale:Traditional layered distribution persists for small-scale processors lacking retail certification. Consolidation pressure mounts as direct procurement expands.
- Supermarkets:Private-label shelf space allocation favors processors with ISO 22000 certification and dedicated compliance staff. Vietnamese and Indonesian exporters consolidate to meet this threshold.
Margin compression hits wholesale most severely. Supermarket traceability requirements accelerate channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity concentrates in coastal aquaculture zones while consumption pulls from inland urban centers, creating trans-continental trade flows that hinge on cold-chain reliability and regulatory interoperability.
Vietnam
Mekong Delta processing clusters supply frozen pangasius fillets to European food service buyers through integrated aquaculture-to-export facilities. The EU's IUU Regulation drives blockchain traceability investments among exporters seeking Dutch and German retail contracts. Can Tho and An Giang provinces anchor automated filleting lines scaling cold-chain capacity for shrimp and pangasius shipments.
Norway
Atlantic salmon farming integrates with mechanized processing from Bergen to Ålesund for IQF portion packs serving North American quick-service chains. Norwegian Food Safety Authority HACCP enforcement maintains export eligibility for US and Japanese markets. Trøndelag and Vestland counties host vertically integrated facilities achieving throughput above 20 tons per hour through robotics deployment.
Thailand
Tuna canneries in Samut Sakhon and Songkhla provinces run continuous retort lines above 500 cans per minute for European private-label contracts. Thai FDA alignment with FDA Seafood HACCP protocols preserves trans-Pacific market access. Bangkok-based processors consolidate to afford dedicated compliance staff for EU Corporate Sustainability Reporting Directive disclosures.
United States
Alaskan pollock processors in Dutch Harbor and Kodiak supply standardized portions to domestic burger chains through freezer-to-fryer direct procurement. FDA Seafood HACCP compliance timelines stretch fourteen to eighteen months for new facility approvals, freezing capital deployment for entrants. Seattle-based distributors anchor re-export networks linking Pacific Northwest processing to Asian retail.
Japan
Tokyo and Osaka retail demand drives portion-control innovation for frozen gift boxes through e-commerce platforms. METI carbon-neutral port initiatives subsidize energy-efficient processing equipment retrofits for exporters. Hokkaido and Kyushu landing sites integrate vessel-to-shelf cold-chain logistics serving domestic supermarket private-label programs.
Seafood Processing Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across frozen, canned, and value-added segments. The market exhibits tiered consolidation with scale leaders commanding retail shelf space through certification compliance while mid-scale operators face margin compression from direct procurement displacement. Three archetypes dominate: vertically integrated aquaculture-to-retail operators, specialized cannery networks, and robotics-enabled crustacean processors. Competitive moves concentrate on backward integration into vessel fleets and multi-year volume commitments with North American restaurant chains.
Among Japanese integrated conglomerates, Maruha Nichiro Corporation and Nippon Suisan Kaisha occupy positions spanning vessel operations through retail distribution. Norwegian salmon specialists Mowi ASA and Lerøy Seafood Group exemplify the aquaculture-anchored archetype with processing scale from farming operations. Thai Union Group PCL represents the cannery-network model with vertical ownership from Thai production through European private-label placement.
| Leading Market Players |
|---|
| Maruha Nichiro Corporation |
| Mowi ASA |
| Thai Union Group PCL |
| Trident Seafoods Corporation |
| High Liner Foods |
| Nippon Suisan Kaisha (Nissui) |
| Marubeni Corporation |
| Clearwater Seafoods |
| Lerøy Seafood Group |
| Others |
Value Chain & Pricing Dynamics
North American quick-service chains' freezer-to-fryer standardization demands are compressing processor margins and forcing supply consolidation around automated filleting hubs in Vietnam and Norway.
Pricing Analysis
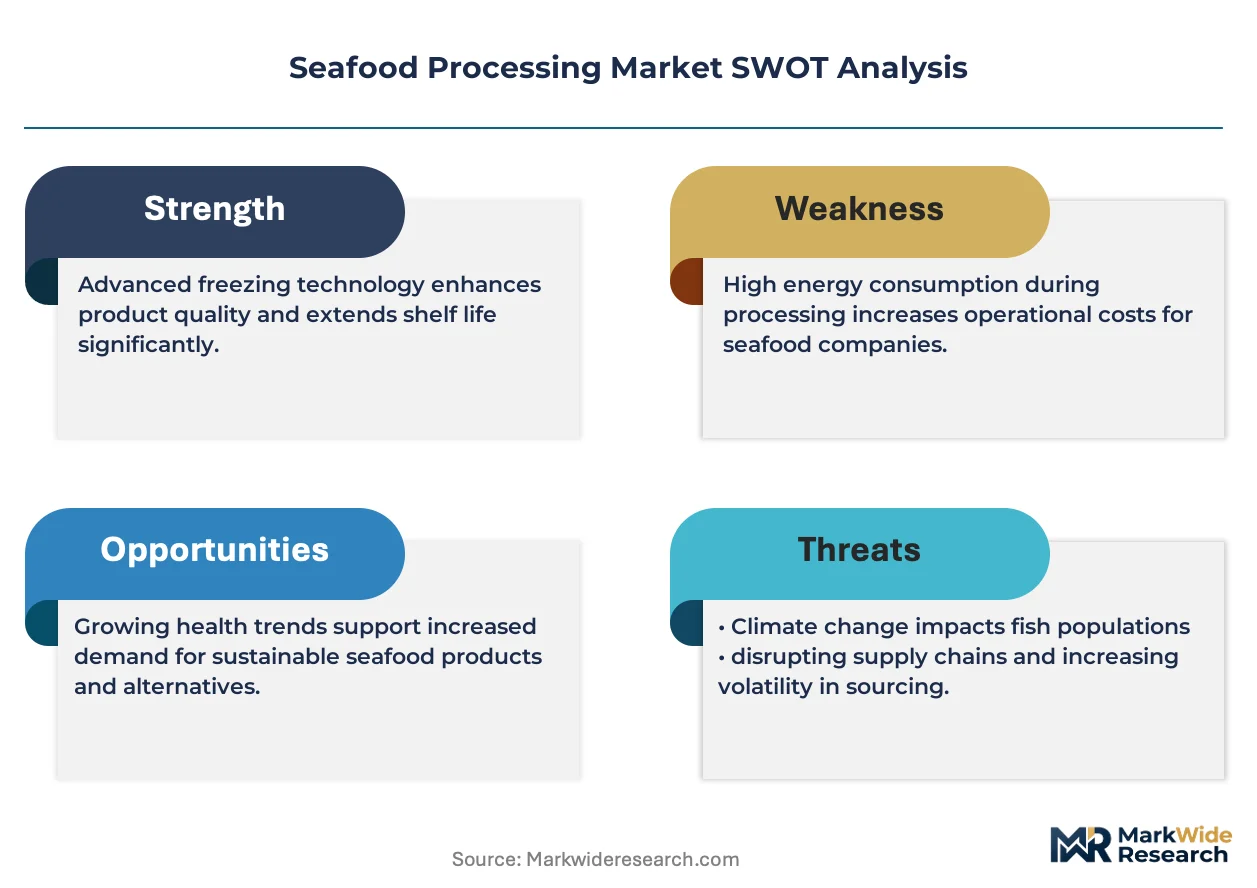
Margin tightening in economy-tier pangasius traces to Mekong Delta input cost swings and Vietnamese exporter consolidation. Three-tier pricing structure across premium ASC-certified salmon, standard IQF whitefish, and economy pangasius separates buyers by certification grade and volume commitment. Pricing pressure stems from direct procurement displacement of wholesale layers. Quick-service chains exhibit highest price sensitivity; Japanese gift-box retail shows lowest.
Supply Chain Analysis
Single-source vulnerability sits with Vietnam's Mekong Delta, hosting over sixty percent of global pangasius capacity. Raw material dependencies draw from Norwegian salmon farming, Thai tuna landings, and Alaskan pollock quotas. Tariff exposure looms for EU-bound Vietnamese exports under evolving IUU enforcement. Distribution runs through integrated cold-chain logistics from vessel to retail shelf.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU traceability mandates and direct procurement displacement are filtering out mid-scale processors lacking compliance infrastructure, creating consolidation openings for capital-rich operators.
For Market Incumbents: Cement backward integration into vessel fleets and aquaculture concessions to lock in raw material security against quota volatility. Anchor multi-year volume commitments with North American restaurant chains to defend share against emerging robotics-enabled crustacean specialists. For New Entrants and Emerging Players: West African institutional caterers represent an underserved buyer archetype with cold-chain infrastructure gaps creating first-mover openings. Target Senegal and Morocco re-export hubs with hub-and-spoke frozen pelagic distribution. Lead with HACCP documentation and extended shelf-life formats as the go-to-market wedge. For Investors and Strategic Acquirers: The window for entry favors vertically integrated aquaculture-to-retail operators with ISO 22000 certification and dedicated compliance staff. Long-term viability hinges on traceability infrastructure ownership. Watch EU Corporate Sustainability Reporting Directive enforcement stringency as the inflection signal for compliance cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vessel Fleets | Captures raw material security against Icelandic and Norwegian quota volatility. |
| Blockchain Traceability Deployment | Unlocks Dutch and German private-label contracts under EU IUU Regulation. |
| Robotics-Enabled Crustacean Automation | Halves labor intensity for Thai and Vietnamese shrimp exporters serving European retail. |
| Direct Procurement Contracts | Eliminates wholesale margins for North American quick-service freezer-to-fryer specifications. |
| Cold-Chain Infrastructure Expansion | Closes last-mile gaps for West African pelagic re-export through Senegal and Morocco. |
Study Parameters
Independent corroboration across seafood processing executives, HACCP compliance officers, and European retail procurement directors underwrites the qualitative findings. Primary interviews with cold-chain logistics specialists and aquaculture farm operators combined with secondary validation from FDA Seafood HACCP filings, EU IUU Regulation documentation, and customs trade data. Bottom-up facility capacity assessments and top-down trade flow analysis complete the triangulation.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects. Segmentation dimensions span product format, preservation technology, and channel structure alongside species-specific regulatory cluster. CAGRs derive from facility throughput trajectories and trade lane expansion patterns. Forecast inputs incorporate automated shucking technology adoption curves and carbon-neutral port subsidy uptake in Japan.
Revisions become necessary when EU IUU enforcement stringency exceeds baseline assumptions or monsoon flooding disrupts Mekong Delta processing clusters. Deviation in North American quick-service direct procurement velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Seafood Powders Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Global Smoked Fish Market
Seafood
South America Canned Seafood Market
Seafood
Wild Pollock Market
Seafood
US Crustacean Market
Seafood
Mussel Extract Market
Seafood
North America Frozen Seafood Market
Seafood
Canned Sardines Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
Fish Meal and Fish Oil Market
Seafood
United States Seafood Market
Seafood
Fresh Fish Market
Seafood
European Frozen Seafood Market
Seafood
Tuna Market
Seafood
Octopus Market