
 China Crustaceans Market | 2026-2036
China Crustaceans Market Size, Share, and Industry Trends Forecast 2026-2036
China Crustaceans Market Outlook
Guangdong's aquaculture belt is tilting toward industrial-scale shrimp and crab farming to feed domestic and export channels. Zhanjiang Guolian Aquatic Products Co., Ltd. anchors its position through integrated hatchery-to-processing operations across the Pearl River Delta. Tongwei leverages its feed-to-food platform to control input costs across crustacean cultivation cycles. Joyvio Food Co., Ltd. competes on branded retail distribution through supermarket and e-commerce channels.
Crustaceans comprise aquatic arthropods with segmented exoskeletons, including shrimp, crab, lobster, and shellfish species harvested through wild catch or aquaculture systems operating at controlled salinity and temperature parameters; these organisms serve as high-protein inputs for food service, retail, and export industries requiring HACCP-compliant handling protocols. Shrimp dominates volume throughput due to shorter grow-out cycles and established hatchery infrastructure, while lobster commands premium margin pools in restaurant and direct-sales channels. Frozen packaging captures the largest share of distribution through supermarkets and fish markets, though vacuum-sealed formats are gaining traction in online retail segments.
SAMR enforces national food safety standards for aquatic products, including GB specifications for heavy metal limits and additive use, while MEE regulates wastewater discharge from coastal processing facilities. The PLI scheme for fisheries infrastructure incentivizes cold-chain investments that expand market access for inland producers. Stakeholders must monitor evolving GB standard revisions and MEE enforcement intensity as these determine which processing configurations remain economically viable.
Market Dynamics
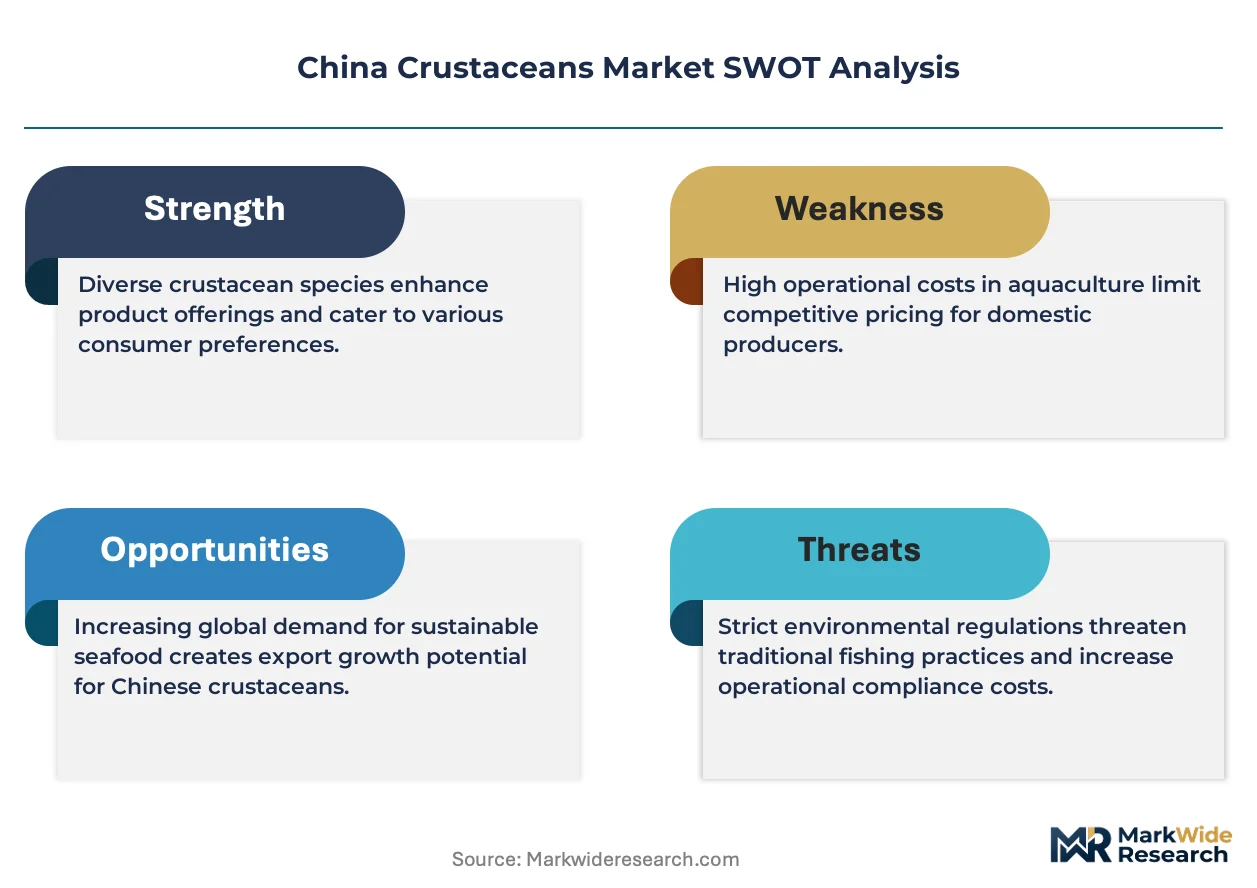
GB standard revisions for heavy metal limits and additive use are compressing processing margins while forcing facility upgrades across coastal provinces, reshaping which operators can sustain export certification.
Growth Catalysts
- PLI scheme for fisheries infrastructure:Cold-chain investments incentivize inland producers to enter crustacean distribution networks previously blocked by spoilage constraints.
- Domestic restaurant chains:Premium seafood menu expansion drives volume pull for shrimp and crab species in tier-one and tier-two cities.
- Recirculating aquaculture systems:Closed-loop water management technology shortens grow-out cycles and reduces coastal land dependency for industrial-scale operators.
Market Restraints
- Feed cost volatility:Soybean meal and fishmeal price swings compress margins for shrimp farmers lacking captive feed supply.
- Processing concentration risk:Zhanjiang and Shantou clusters dominate export-oriented capacity, creating single-point vulnerability for cold-chain disruptions.
- MEE wastewater enforcement:Coastal discharge standards force capital-intensive treatment retrofits on mid-scale processing facilities.
Strategic Opportunities
- Inland cold-chain expansion:Sichuan and Hubei provinces remain underpenetrated for live-crustacean retail distribution via supermarket channels.
- Vacuum-sealed e-commerce formats:Direct-to-consumer packaging innovation unlocks premium pricing for branded crab and lobster products.
- Dual carbon goals alignment:Solar-powered aquaculture facilities qualify for subsidized grid connections and green financing instruments.
Industry Challenges
- HACCP certification timelines:Export-oriented processors face 12-18 month approval cycles for EU and US market access.
- Genetic breeding expertise scarcity:Domestic hatcheries lack sufficient shrimp broodstock specialists to support industrial expansion targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Crustaceans Market |
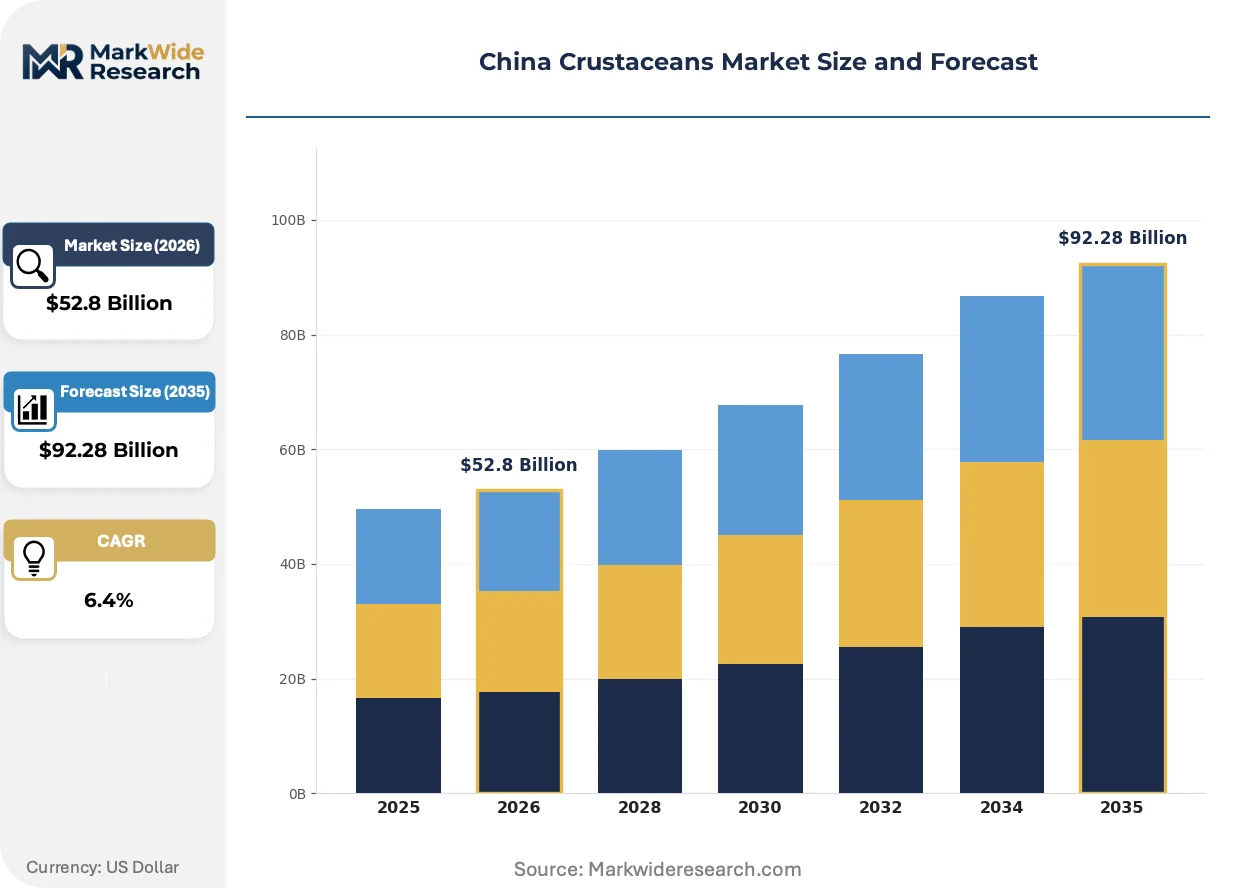
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shrimp, Crab, Lobster, Shellfish End User: Restaurant, Retail, Food Service, Exporters Distribution Channel: Online, Supermarkets, Fish Markets, Direct Sales Packaging Type: Bulk, Vacuum-Sealed, Canned, Frozen |
| Companies Covered | China National Fisheries Corp., China Marine Foison Group Co. Ltd, Zhanjiang Guolian Aquatic Products Co., Ltd., Joyvio Food Co., Ltd., Dalian Athena Seafood Limited, Dandong Grand Ocean Foods Co. Ltd, Tongwei, Haida, CP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Crustaceans Market Strategic Shifts
Digital traceability systems and automated feeding platforms are compressing operational inefficiencies across hatchery-to-retail value chains. Three developments are altering competitive positioning.
IoT sensor networks deployed in pond environments are digitizing water quality monitoring and feed optimization decisions. Large-scale shrimp farms in Guangdong and Hainan are adopting these systems at accelerating rates. The technology is digitizing mortality prediction and harvest timing, reducing feed conversion ratios by enabling real-time adjustment protocols.
SAMR enforcement of GB 2762-2022 heavy metal limits for aquatic products is tightening cadmium and lead thresholds in processed crustacean exports. Processing facilities must install upgraded testing infrastructure or forfeit EU and US market access. Frozen shrimp and crab segments face the steepest compliance costs as these categories dominate export volume.
Direct sourcing contracts between restaurant chains and integrated aquaculture operators are displacing traditional wholesale market intermediaries. Haidilao and Xiabuxiabu are negotiating multi-year volume commitments with Zhanjiang-based suppliers. This consolidation is most visible in Guangdong province where vertical coordination reduces price volatility for premium lobster and crab categories.
China Crustaceans Market Segmentation
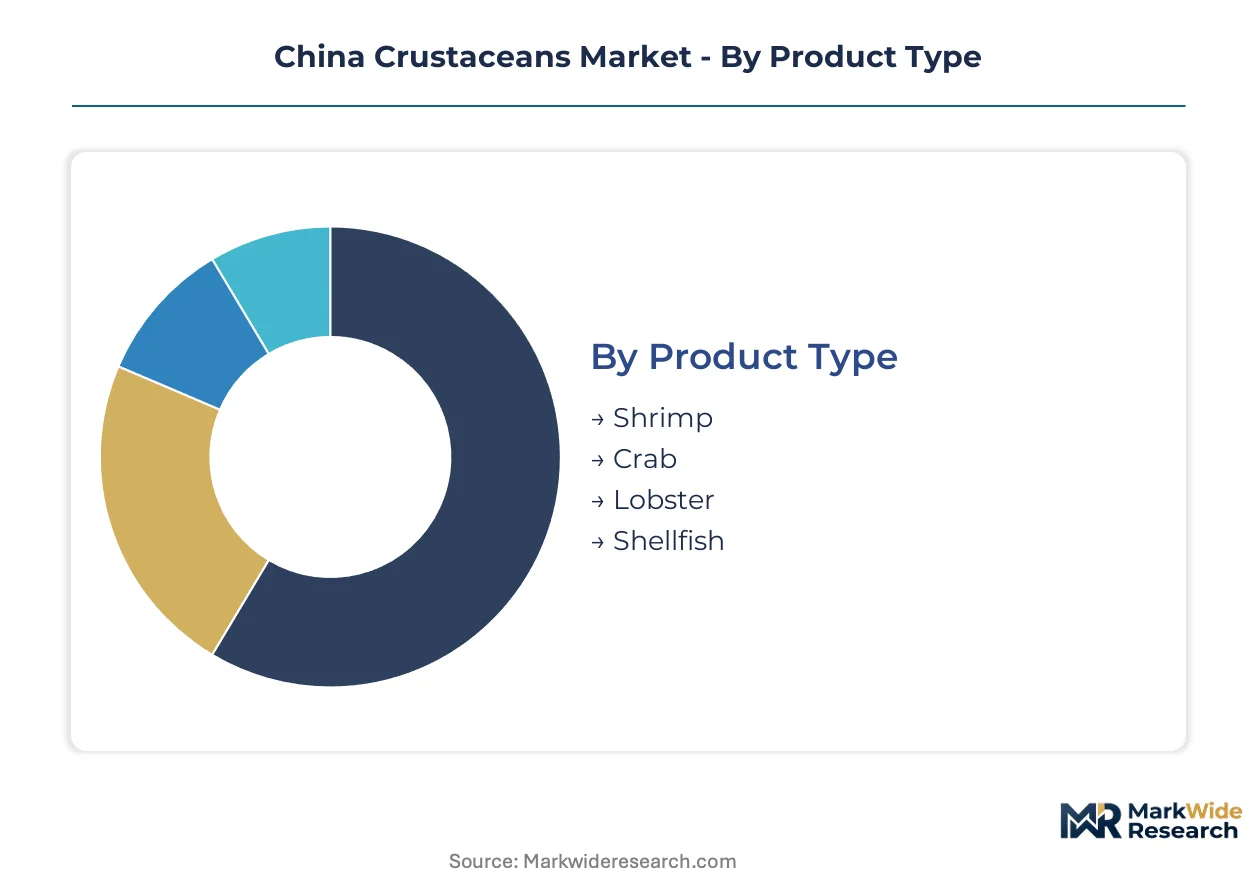
Segmentation in China's crustaceans market reveals how supply chain configuration and end-use requirements diverge across species, channels, and packaging formats. Understanding these divisions exposes where margin pools concentrate and where regulatory pressure reshapes competitive viability.
Product Type:
Species selection maps directly onto grow-out economics, cold-chain requirements, and premium positioning in Guangdong and Fujian processing clusters.
- Shrimp:Penaeid and vannamei varieties dominate volume throughput with 90-120 day grow-out cycles. Coastal hatcheries in Zhanjiang supply Guangdong restaurants and frozen export channels, though genetic breeding expertise scarcity constrains industrial expansion.
- Crab:Eriocheir sinensis and Scylla serrata command higher unit margins through seasonal scarcity and gift-giving demand. Yangcheng Lake and Ningbo clusters anchor domestic premium retail, while MEE wastewater enforcement raises processing costs for mid-scale facilities.
- Lobster:Panulirus and Homarus species concentrate in Hainan and Shandong aquaculture zones for tier-one restaurant chains.
- Shellfish:Mollusk categories including oysters and clams serve lower-price retail segments with minimal processing infrastructure.
The dominant share belongs to shrimp, while crab is closing the gap fastest through premium restaurant menu expansion and branded retail positioning.
End User:
Customer type determines certification requirements, pricing tolerance, and volume predictability across the value chain.
- Restaurant:Haidilao and Xiabuxiabu negotiate direct sourcing contracts with Zhanjiang suppliers, bypassing wholesale intermediaries. Multi-year volume commitments reduce price volatility for lobster and crab categories in Guangdong province.
- Retail:Supermarket and e-commerce channels demand vacuum-sealed formats with SAMR-compliant traceability labeling. Joyvio Food anchors branded distribution through cold-chain partnerships.
- Food Service:Institutional catering and centralized kitchens source frozen bulk formats through Shantou processing clusters.
- Exporters:EU and US market access requires 12-18 month HACCP certification cycles and GB 2762-2022 heavy metal compliance testing infrastructure.
Restaurant procurement is concentrating fastest, while exporter margins face steepest compression from standard revision timelines.
Distribution Channel:
Channel selection reflects cold-chain maturity and consumer proximity to coastal production zones.
- Online:Direct-to-consumer platforms unlock premium pricing for branded crab and lobster through vacuum-sealed formats. Sichuan and Hubei provinces remain underpenetrated for live-crustacean delivery.
- Supermarkets:Yonghui and Carrefour outlets in tier-one cities stock frozen and live tanks with SAMR-mandated origin labeling.
- Fish Markets:Traditional wholesale venues in Guangzhou and Xiamen serve restaurant procurement with minimal traceability infrastructure.
- Direct Sales:Integrated operators like Guolian bypass intermediaries for export and large-chain restaurant accounts.
Online channels are expanding most quickly, while fish markets retain volume dominance in coastal provinces.
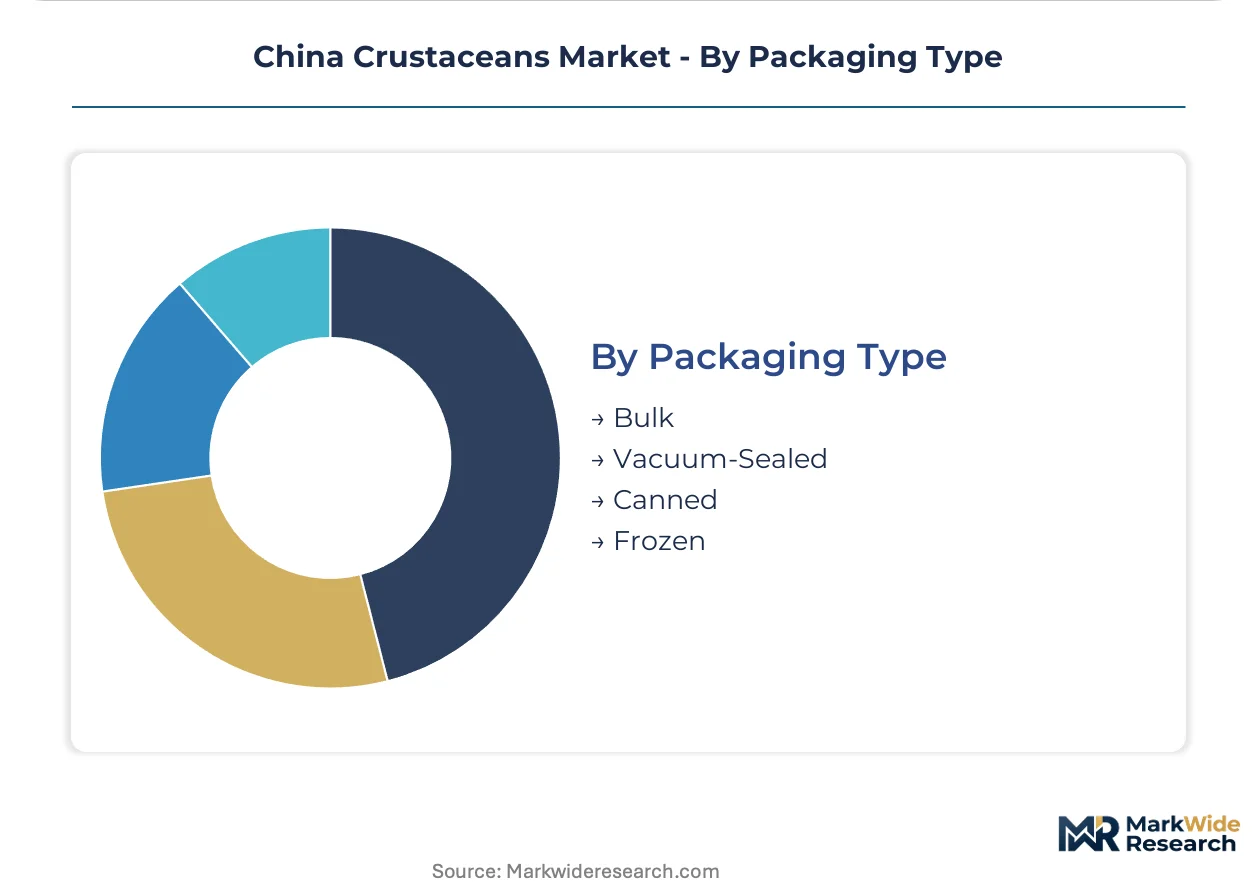
Packaging Type:
Format choice balances shelf-life extension against processing capital requirements and end-use temperature protocols.
- Bulk:Unpackaged fresh delivery serves live-tank restaurant segments in Guangdong and Fujian with same-day harvest-to-table logistics.
- Vacuum-Sealed:Modified atmosphere packaging extends retail shelf life for e-commerce crab and lobster products, qualifying for premium tier pricing.
- Canned:Heat-sterilized formats serve institutional food service with minimal cold-chain dependency.
- Frozen:Blast-frozen shrimp and crab blocks dominate export volume and supermarket distribution, facing steepest GB 2762-2022 compliance costs for heavy metal testing.
Frozen formats hold the largest share, while vacuum-sealed products are gaining share fastest through online retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Zhanjiang Port cold-chain terminal anchors Guangdong's export capacity for frozen crustacean shipments to EU and US markets. Shandong's Yantai Port infrastructure supports live lobster air-freight operations to tier-one city restaurants. These maritime assets determine which provinces capture premium distribution margins.
Guangdong Province
Haidilao and Xiabuxiabu expand premium seafood menus across Shenzhen and Guangzhou outlets, pulling volume through direct sourcing contracts. SAMR enforces GB 2762-2022 heavy metal limits on processed exports from Zhanjiang processing clusters. The Pearl River Delta concentrates hatchery-to-processing operations where Guolian anchors integrated supply chains.
Fujian Province
Restaurant procurement shifts toward multi-year volume commitments for crab and lobster categories in Xiamen and Fuzhou. MEE wastewater discharge standards force capital-intensive treatment retrofits on mid-scale Shantou processing facilities. The coastal belt from Quanzhou to Zhangzhou clusters export-oriented freezing capacity for EU-bound shrimp consignments.
Shandong Province
Live lobster tank systems serve Beijing and Tianjin restaurant demand through Yantai and Weihai logistics hubs. Provincial fisheries infrastructure investments under the national PLI scheme expand cold-chain penetration into inland Hebei corridors. The Shandong Peninsula hosts industrial-scale Homarus cultivation for tier-one city premium channels.
Hainan Province
Panulirus farming operations supply tropical seafood positioning for resort and restaurant segments in Sanya and Haikou. Free trade port policies accelerate customs clearance for imported broodstock and processing equipment. The island's warm-water aquaculture zones shorten grow-out cycles compared to temperate coastal competitors.
Sichuan Province
Supermarket retail demand for vacuum-sealed crab products expands through Chengdu and Chongqing cold-chain partnerships. Underpenetrated live-crustacean distribution creates whitespace for e-commerce platform entry via refrigerated last-mile networks. The Yangtze River corridor connects to coastal supply through Wuhan rail-hub transshipment.
China Crustaceans Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in feed, broodstock, and processing equipment. The vendor base organizes around three strategic archetypes: integrated hatchery-to-retail operators, branded retail distributors, and feed-to-food conglomerates controlling input costs. Consolidation pressures concentrate export certification capacity in coastal processing clusters while inland distribution remains fragmented. Competitive moves center on direct sourcing contract negotiations with restaurant chains and cold-chain infrastructure partnerships.
Among integrated aquatic product operators, Zhanjiang Guolian Aquatic Products Co., Ltd. exemplifies the hatchery-to-processing archetype through Pearl River Delta concentration. Joyvio Food Co., Ltd. occupies a branded retail position serving supermarket and e-commerce channels. Tongwei represents the feed-to-food platform model leveraging captive supply economics across cultivation cycles.
| Leading Market Players |
|---|
| China National Fisheries Corp. |
| China Marine Foison Group Co. Ltd |
| Zhanjiang Guolian Aquatic Products Co., Ltd. |
| Joyvio Food Co., Ltd. |
| Dalian Athena Seafood Limited |
| Dandong Grand Ocean Foods Co. Ltd |
| Tongwei |
| Haida |
| CP |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Zhanjiang processing clusters compresses spot pricing for frozen shrimp exports while forcing operators toward long-term offtake contracts with restaurant chains. This utilization squeeze simultaneously erodes margin buffers and accelerates consolidation among mid-scale facilities unable to absorb GB 2762-2022 compliance costs.
Pricing Analysis
GB 2762-2022 heavy metal limits dictate the pricing tier structure across China's crustacean export channels. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified lots from domestic retail grades and institutional food-service bulk. Price differentiation rests on HACCP certification status and cold-chain integrity documentation. Cost compression in standard-tier frozen shrimp is intensifying because MEE wastewater retrofits force capital recovery through volume discounting. Restaurant chains exhibit least price sensitivity due to multi-year direct sourcing commitments, while inland supermarket buyers face highest budget constraints.
Supply Chain Analysis
Single-source vulnerability in Guangdong hatchery infrastructure dominates supply chain risk assessment for industrial-scale operators. Geographic supply concentration centers on China, Vietnam, and Indonesia for broodstock and juvenile inputs. Raw material dependencies draw from soybean meal, fishmeal, and artificial feed formulations. Distribution runs through cold-chain partnerships linking coastal processing clusters to tier-one city retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward restaurant chains as Haidilao and Xiabuxiabu consolidate procurement through direct multi-year contracts, fragmenting traditional wholesale intermediaries.
For Market Incumbents: Harden cold-chain certification capacity against EU and US HACCP timeline pressures by upgrading Zhanjiang testing infrastructure. Secure backward integration into broodstock genetics through partnerships with Hainan research stations. Defend margin position against feed cost volatility by locking long-term soybean meal offtake agreements. For New Entrants and Emerging Players: Sichuan and Hubei vacuum-sealed e-commerce distribution represents the most penetrable entry point for branded crab and lobster products. Target supermarket cold-chain partnerships in Chengdu and Chongqing as anchor accounts. Deploy direct-to-consumer packaging innovation to bypass established wholesale networks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because export certification capacity concentrates in coastal processing clusters while inland distribution remains fragmented. Acquisition targets include mid-scale facilities with SAMR-compliant infrastructure and established restaurant chain relationships. Monitor MEE enforcement intensity as the critical signal for facility viability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | PLI scheme subsidies enable Sichuan and Hubei market penetration beyond coastal zones. |
| Backward Integration into Broodstock | Genetic breeding expertise scarcity makes captive hatchery capacity a defendable moat. |
| Direct Sourcing Contract Negotiation | Haidilao-style multi-year commitments reduce price volatility for premium lobster suppliers. |
| GB 2762-2022 Compliance Investment | Heavy metal testing infrastructure determines EU and US market access eligibility. |
| Recirculating Aquaculture System Deployment | Closed-loop water management shortens grow-out cycles and reduces coastal land dependency. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with hatchery managers, processing facility technical directors, restaurant chain procurement officers, and cold-chain logistics coordinators. Secondary validation drew from SAMR regulatory filings, MEE discharge permit databases, customs export records, and PLI scheme disbursement reports. Bottom-up volume modeling and top-down value triangulation were cross-checked against operating metrics disclosed by listed aquatic product companies.
Calibration against historical price series and capacity utilization rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include species type, end-user category, distribution channel format, and packaging technology tier. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement intensity and infrastructure investment pacing. Forecast inputs incorporated feed cost indices and cold-chain penetration rates by province.
Practitioners should monitor GB standard revision schedules and MEE enforcement intensity for early signals of compliance cost escalation. Forecasts reflect assumptions about PLI scheme continuity and restaurant chain expansion trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Canned Sardines Market
Seafood
Canned Mackerel Market
Seafood
Rainbow Trout Market
Seafood
Canned Fishery Product Market
Seafood
Oyster Meal Market
Seafood
Shellfish Extract Market
Seafood
Cod Fish Market
Seafood
Seafood Processing Market
Seafood
Carp Market
Seafood
United States Plant-Based Seafood Market
Seafood
Fish Protein Market
Seafood
Seafood Flavors Market
Seafood
US Crustacean Market
Seafood
United States Seafood Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Salmon Fish Market