
 Fish Meal Market | 2026-2036
Fish Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Meal Market Intelligence
MarinTrust certification is collapsing the supplier base eligible for premium aquaculture contracts. Omega Protein Corporation leverages vertical integration across Gulf of Mexico menhaden fisheries to sustain volume commitments to North American feed mills. Austevoll Seafood ASA anchors its position through Norwegian and Peruvian processing assets, while Cargill competes via diversified protein sourcing that extends beyond marine ingredients into alternative meals.
Fish meal denotes a protein-rich powder produced by cooking, pressing, drying, and grinding whole fish or fish trimmings, typically containing 60-72% crude protein and 8-12% fat by weight, serving primarily as a high-digestibility feed ingredient for farmed salmon, shrimp, and marine species. Feed-grade fish meal dominates volume flows into aquaculture diets, whereas hydrolyzed fish protein commands margin pools in premium pet food formulations where palatability enhancement justifies higher unit values. Pressure cooking retains the largest share of extraction methods due to lower capital intensity, though steam cooking is displacing legacy approaches in new Peruvian installations.
FDA feed ingredient rules and EU REACH traceability protocols constrain market access for uncertified producers, while Peru's PRODUCE ministry enforces seasonal quota regimes that directly govern global supply availability. Stakeholders must monitor how Chilean and Peruvian quota negotiations reshape raw material access before committing to long-term offtake structures.
Market Dynamics
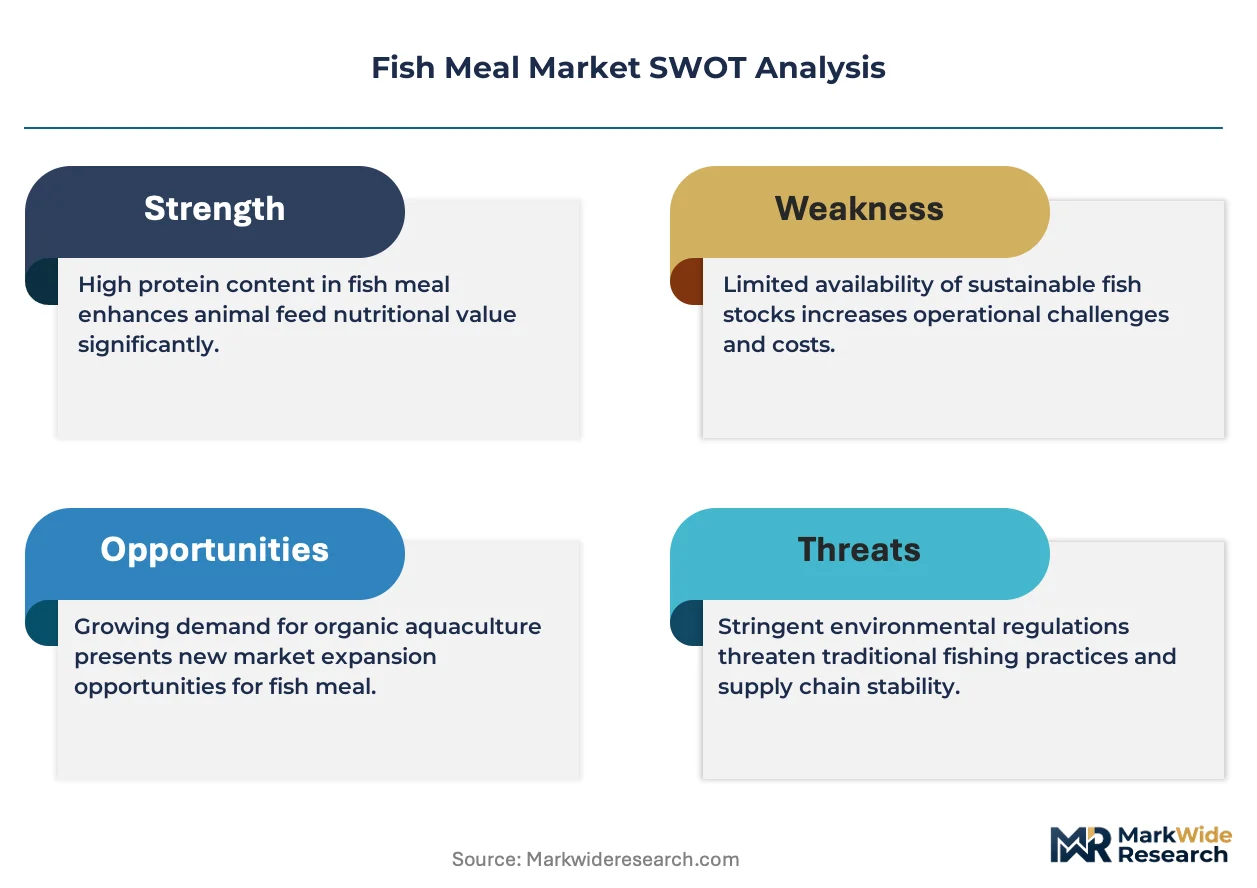
MarinTrust certification requirements are compressing the supplier base eligible for premium aquaculture contracts, forcing uncertified processors toward commodity feed-grade segments or exit. This structural filter is reshaping competitive positioning across extraction, trading, and formulation tiers.
Growth Catalysts
- EU Green Deal traceability mandates:Marine ingredient verification protocols are pulling Southeast Asian aquaculture feed producers toward certified supply chains, expanding offtake from compliant Peruvian and Chilean processors.
- Whole fish meal demand concentration:Premium-grade material from anchovy and menhaden fisheries anchors salmon and shrimp diet formulations where protein digestibility thresholds exclude plant alternatives.
- Pressure cooking capital efficiency:Lower installation costs relative to steam systems sustain capacity expansion in coastal processing clusters, preserving margin structures for mid-scale operators.
Market Restraints
- Anchovy biomass volatility:El Niño Southern Oscillation cycles compress Peruvian quota allocations, injecting supply uncertainty into annual contracting rhythms.
- Plant protein substitution:Fermented soybean meal and insect protein isolates are capturing formulation share in grow-out diets where amino acid profiles permit partial marine ingredient displacement.
- EU REACH registration costs:Small-scale Southeast Asian processors face capital barriers to European market access, consolidating trade flows through certified intermediaries.
Strategic Opportunities
- Hydrolyzed fish protein penetration:Premium pet food palatability enhancement commands unit value multiples over feed-grade material, opening margin pools in companion animal nutrition.
- Norwegian processing asset integration:North Sea fishery byproduct streams offer uncaptured raw material for specialty meal fractions serving marine hatchery diets.
- FDA feed ingredient rule harmonization:Alignment between US and EU safety protocols could streamline dual-market certification, reducing compliance overhead for transatlantic suppliers.
Industry Challenges
- MarinTrust audit timeline compression:Certification backlog delays market access for retrofitting processors, trapping working capital in pre-qualified inventory.
- Legacy steam cooker integration:Peruvian facilities face stranded asset risk as pressure cooking displaces capital-intensive thermal systems in greenfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Meal Market |
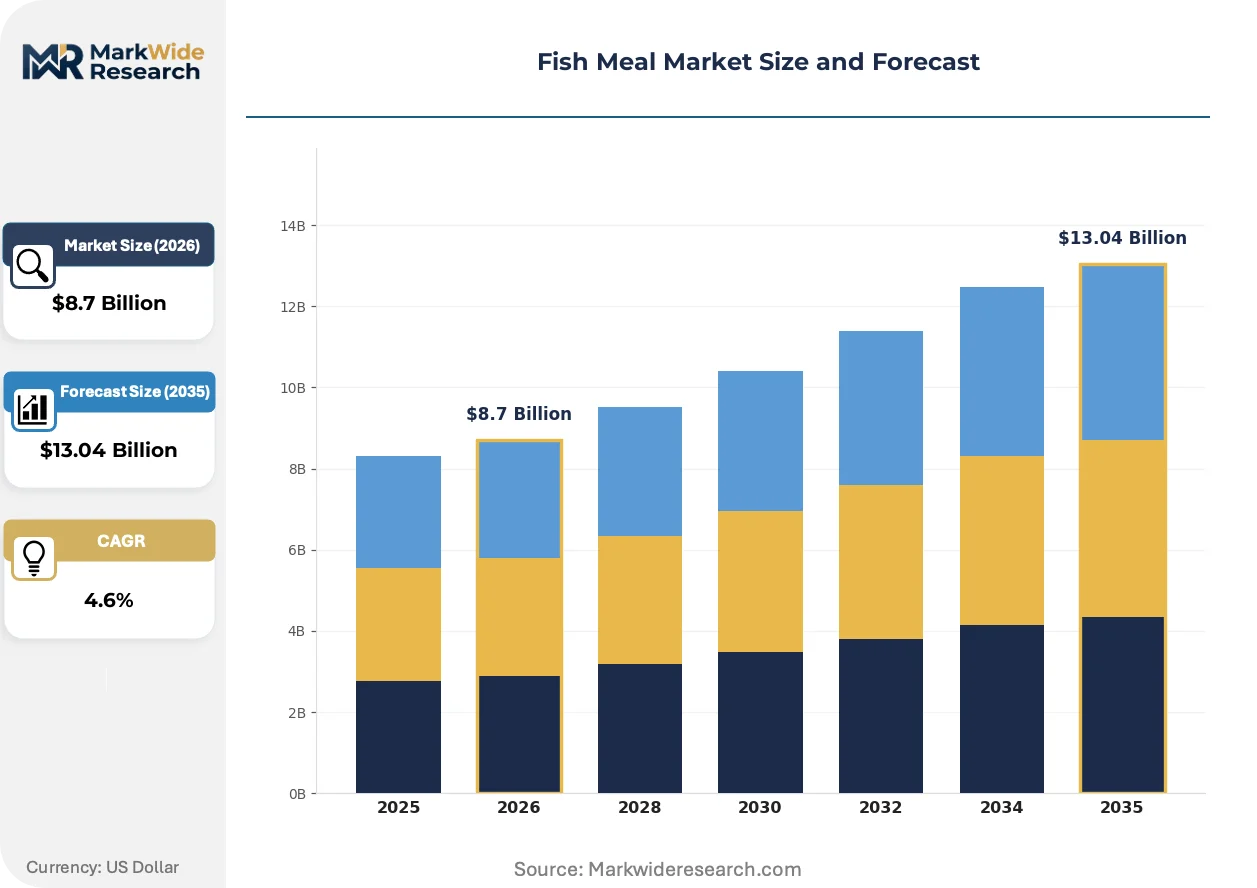
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Meal, By-Product Meal, Hydrolyzed Fish Protein, Fish Flour End Use Industry: Aquaculture, Pet Food, Animal Feed, Fertilizers Extraction Method: Pressure Cooking, Steam Cooking, Drying, Solvent Extraction Quality Grade: Food Grade, Feed Grade, Premium Grade, Standard Grade |
| Companies Covered | Omega Protein Corporation, Nutreco N.V., Austevoll Seafood ASA, Cargill, Inc., Marubeni Corporation, Pesquera Diamante S.A., FF Skagen, The Scoular Company, Oceana Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Meal Market Strategic Shifts & Innovations
Extraction technology is decomposing legacy thermal processing economics while regulatory traceability protocols and procurement consolidation reshape how value flows through marine ingredient supply chains.
Enzymatic hydrolysis is decomposing the traditional whole-meal value proposition by enabling targeted peptide fractionation for species-specific diet formulations. Salmon feed compounders in Norway are adopting these systems at pilot scale. The technology is decomposing commodity pricing structures into tiered product streams where molecular weight distribution determines contract terms.
EU REACH traceability extensions are forcing chain-of-custody documentation from vessel to finished feed, with ECHA registration requirements now covering previously exempt trim-derived meals. Peruvian exporters are responding by integrating GPS-logged catch verification with processing batch records. This regulatory layer most heavily affects small-scale Vietnamese and Indonesian traders lacking integrated fleet assets.
Certification-driven procurement consolidation is compressing supplier lists among Southeast Asian shrimp feed mills, with MarinTrust eligibility replacing spot-price buying as the primary screening criterion. Long-term offtake agreements are displacing quarterly tenders in Thailand and Vietnam. This behavioral shift is most visible in Mekong Delta processing clusters where integrated aquaculture operations internalize meal sourcing decisions.
Fish Meal Market Segmentation
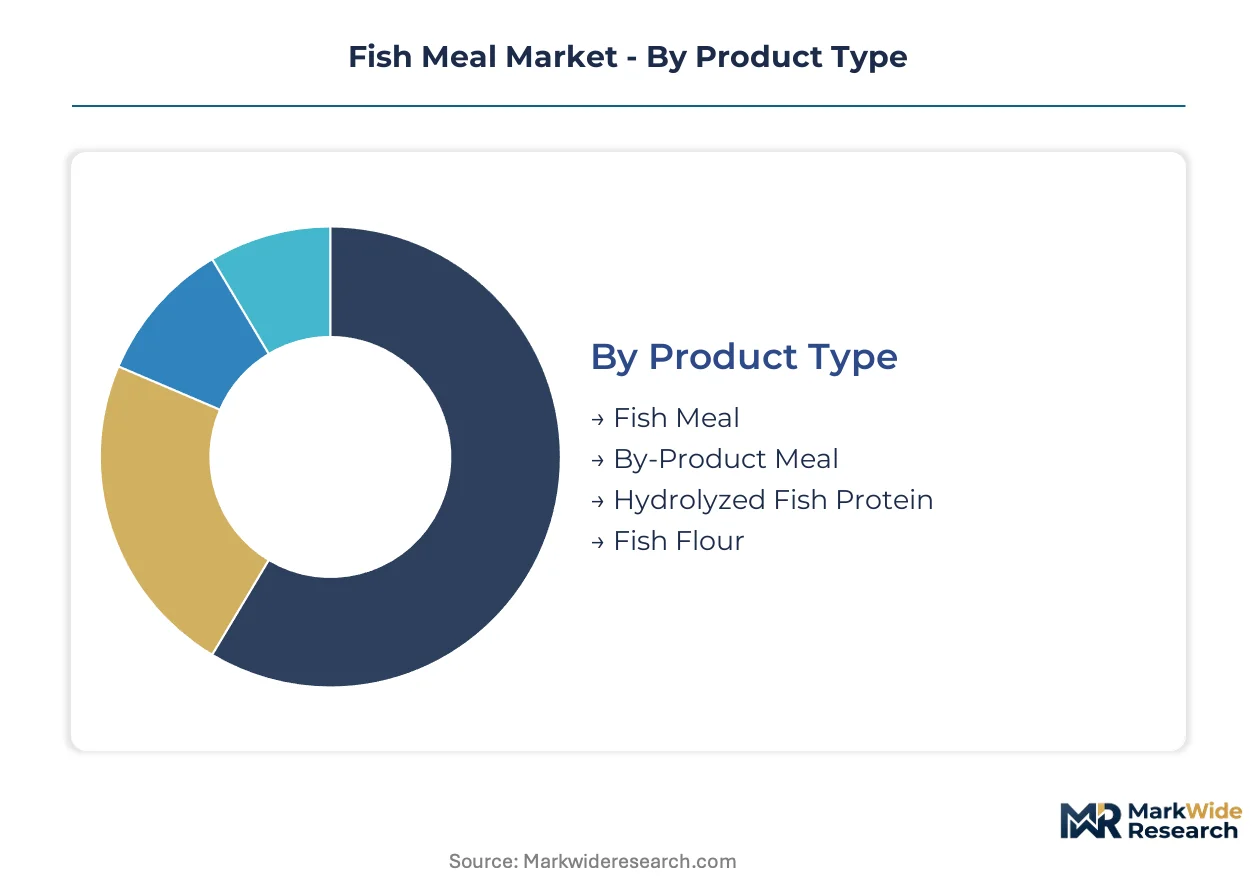
Fish meal segmentation reveals how substitution pressures and certification requirements are fragmenting demand across protein quality tiers. Each dimension—product type, end use, extraction technology, and grade specification—carries distinct margin structures and regulatory exposure that determine supplier viability.
Product Type:
Plant protein and insect meal substitutes are encroaching fastest on commodity whole fish meal, while hydrolyzed fractions retain defensive positioning through functional specificity.
- Fish Meal:Whole fish or trimmings processed through cooking, pressing, and drying yield 60-72% crude protein meal. Norwegian salmon feed compounders and Southeast Asian shrimp mills anchor demand, though fermented soybean meal is capturing grow-out diet share where amino acid thresholds permit.
- Hydrolyzed Fish Protein:Enzymatic breakdown produces low-molecular-weight peptides for species-specific formulations and premium pet food palatability enhancement. North American specialty feed manufacturers and European marine hatchery operations concentrate offtake, with peptide fractionation commanding unit value multiples over standard meal.
- By-Product Meal:Processing residues from filleting operations offer lower-cost protein inputs for non-aquaculture applications.
- Fish Flour:Fine-milled, low-fat derivative serves niche fertilizer and specialty feed applications with limited volume traction.
Fish meal anchors the volume base while hydrolyzed fish protein gains share at the steepest rate.
End Use Industry:
Cost tier stratification separates commodity feed applications from premium formulations where functional performance justifies marine ingredient retention.
- Aquaculture:Salmon and shrimp diets demand 60-72% protein digestibility thresholds that plant alternatives struggle to match. EU Green Deal traceability mandates are pulling Southeast Asian feed producers toward MarinTrust-certified Peruvian and Chilean supply chains, consolidating procurement around eligible processors.
- Pet Food:Palatability enhancement and hypoallergenic positioning drive hydrolyzed protein incorporation in premium companion animal nutrition. North American and European specialty manufacturers concentrate offtake, with peptide-based formulations capturing margin pools unavailable to standard feed-grade material.
- Animal Feed:Poultry and swine operations apply fish meal as a growth promoter and amino acid supplement in starter diets.
- Fertilizers:Organic agriculture certification requirements sustain niche demand for fish-based soil amendments.
Aquaculture commands the dominant volume position while pet food applications expand most quickly.
Extraction Method:
Capital efficiency divides established coastal processors from greenfield installations adopting next-generation thermal systems.
- Pressure Cooking:Lower capital intensity and reduced energy consumption sustain dominance in mid-scale Peruvian and Southeast Asian processing clusters. Coastal facilities leverage this method to preserve margin structures amid volatile raw material costs.
- Steam Cooking:Superior protein digestibility and reduced thermal degradation attract investment in new Peruvian installations serving premium aquaculture contracts. Higher installation costs limit adoption to well-capitalized operators with secured long-term offtake agreements.
- Drying:Ancillary moisture reduction step integrated with primary thermal extraction systems.
- Solvent Extraction:Specialized lipid recovery applications for high-value omega-3 concentrate production.
Pressure cooking retains the installed base while steam cooking climbs the fastest among greenfield investments.
Quality Grade:
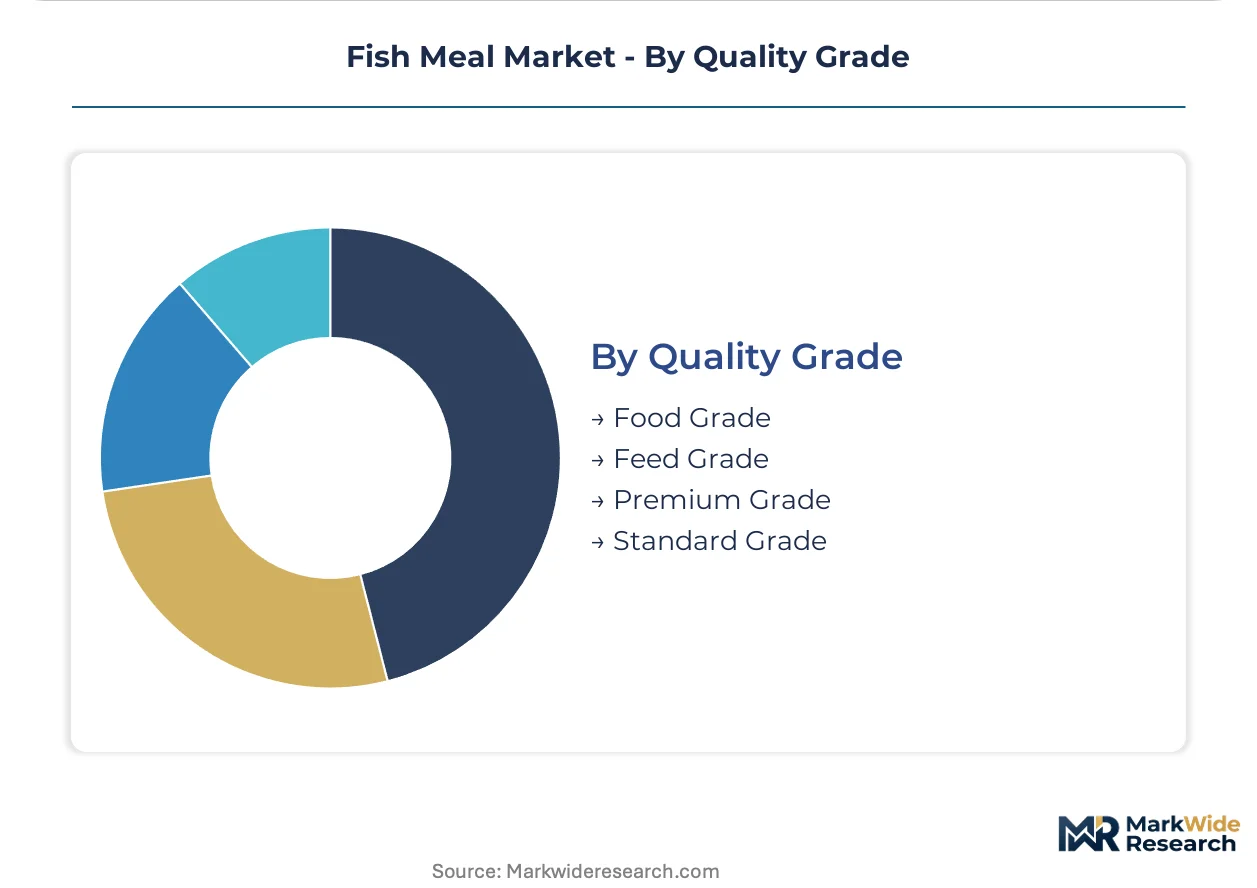
Certification eligibility and customer specification requirements are collapsing the supplier base capable of serving premium contract tiers.
- Feed Grade:Standard protein and fat specifications serve commodity aquaculture and animal feed applications where cost minimization dominates procurement. Southeast Asian shrimp feed mills represent the largest volume concentration, though MarinTrust eligibility is displacing spot-price buying as the primary screening criterion.
- Premium Grade:Elevated protein digestibility, controlled histamine levels, and full traceability documentation command contract premiums from salmon feed compounders in Norway and Chile. EU REACH registration and FDA feed ingredient rule compliance constrain the supplier base eligible for this tier.
- Food Grade:Human consumption applications in specialty nutrition and food processing.
- Standard Grade:Intermediate specification band for non-critical feed applications.
Feed grade carries the volume base while premium grade captures the steepest expansion trajectory among certified supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Callao anchors Peru's export infrastructure, moving over 70% of the country's fish meal shipments to Asian and European aquaculture markets through dedicated bulk handling terminals.
Peru
Anchovy quota negotiations between PRODUCE and industrial fishing associations determine annual supply availability for global salmon feed compounders. Seasonal biomass assessments under the Humboldt Current ecosystem monitoring program constrain harvest windows. Chimbote processing clusters retrofit pressure cooking lines to meet MarinTrust certification deadlines.
Chile
Salmon feed mills in the Los Lagos region consume premium-grade whole fish meal for diets requiring 65%+ protein digestibility. Subsecretaría de Pesca y Acuicultura enforcement of traceability documentation aligns with EU Green Deal import requirements. Puerto Montt logistics hubs consolidate meal shipments from both domestic reduction plants and Peruvian imports.
Norway
North Sea whitefish processing byproduct streams supply specialty meal fractions for marine hatchery diets. Mattilsynet feed safety regulations and ECHA REACH registration requirements filter supplier eligibility for premium contracts. Ålesund processing assets integrate enzymatic hydrolysis capacity for peptide fractionation serving high-value formulations.
United States
Gulf of Mexico menhaden fisheries sustain volume commitments to domestic aquaculture and pet food manufacturers. FDA feed ingredient rules and state-level fishery management plans constrain operational flexibility for reduction plants. Reedville, Virginia processing infrastructure represents the Atlantic coast concentration of thermal extraction capacity.
Vietnam
Mekong Delta shrimp feed mills are consolidating procurement around MarinTrust-certified supply chains as EU import requirements tighten. Directorate of Fisheries traceability mandates push integrated aquaculture operations toward long-term offtake agreements. Cần Thơ industrial zones host the largest concentration of feed compounding capacity dependent on imported Peruvian meal.
Fish Meal Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, with publicly traded entities dominating premium aquaculture contracts while family-owned processors capture commodity feed-grade volumes. The supplier base compresses around MarinTrust eligibility as the primary screening criterion for Southeast Asian procurement. Three archetypes define competitive positioning: vertically integrated fishery-to-meal operators, diversified protein conglomerates with marine ingredient divisions, and specialist traders bridging certified supply with fragmented demand. Capacity expansion and backward integration into controlled fishery assets represent the dominant competitive moves.
Within the integrated fishery-processor tier, Omega Protein Corporation and Austevoll Seafood ASA exemplify archetypes of geographic specialization—Gulf of Mexico menhaden concentration versus Norwegian-Peruvian dual-hemisphere assets. Cargill, Inc. occupies a position representing diversified protein sourcing that extends marine ingredients into alternative meal portfolios. These three entities anchor the competitive structure through contrasting approaches to supply security: captive fishery control, multi-origin processing networks, and broad ingredient substitution capabilities.
| Leading Market Players |
|---|
| Omega Protein Corporation |
| Nutreco N.V. |
| Austevoll Seafood ASA |
| Cargill, Inc. |
| Marubeni Corporation |
| Pesquera Diamante S.A. |
| FF Skagen |
| The Scoular Company |
| Oceana Group Limited |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Peruvian processors and Southeast Asian shrimp feed mills lock in supply access while dampening quarterly price volatility against spot-market anchovy meal fluctuations. These contracts embed MarinTrust certification premiums and seasonal quota adjustment clauses that transfer biomass risk from buyers to suppliers.
Pricing Analysis
Volume-discount tiering structures separate premium-grade whole fish meal from commodity feed-grade material, with salmon feed compounders in Norway and Chile absorbing higher unit costs for 65%+ protein digestibility guarantees. Certification level—specifically MarinTrust eligibility and EU REACH registration—commands price premiums over uncertified Peruvian supply. Cost compression in feed-grade segments is intensifying because fermented soybean meal and insect protein isolates are capturing grow-out diet share. Southeast Asian shrimp mills exhibit the highest price sensitivity, while North American pet food manufacturers show least sensitivity due to palatability-driven formulation requirements.
Supply Chain Analysis
Container availability constraints on the Callao-Ho Chi Minh City trade lane are elevating inbound logistics costs for Mekong Delta feed mills dependent on Peruvian meal imports. Supply concentrates in Peru, Chile, and Norway, with raw material flows drawing from Humboldt Current anchovy fisheries, Gulf of Mexico menhaden stocks, and North Sea whitefish processing byproduct streams. Single-source vulnerability around Peruvian quota allocations under PRODUCE ministry seasonal regimes presents structural risk. Distribution runs through dedicated bulk handling terminals at the Port of Callao, with consolidation at Puerto Montt logistics hubs serving Chilean salmon feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MarinTrust certification capacity is narrowing faster than retrofitting timelines can absorb, creating a bottleneck where certified processing assets command scarcity premiums. This gap separates suppliers capable of EU-compliant documentation from those trapped in commodity price competition.
For Market Incumbents: Consolidate around captive fishery control and backward integration into GPS-verified fleet assets to defend against uncertified processor exit waves. Expand pressure cooking capacity in Chimbote processing clusters to capture margin structures amid steam cooker stranded asset risk. Prioritize enzymatic hydrolysis pilot investments to access peptide fractionation premiums in Norwegian marine hatchery diets. For New Entrants and Emerging Players: Specialty pet food palatability enhancement represents an under-served service layer where hydrolyzed fish protein commands unit value multiples unavailable to commodity feed-grade suppliers. Target North American specialty manufacturers with species-specific peptide formulations. Pursue toll-processing partnerships with Peruvian facilities facing certification backlog delays to bypass capital-intensive greenfield installation requirements. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with dual-hemisphere processing networks and secured MarinTrust eligibility. Long-term viability hinges on controlled fishery access rather than trading margins. Monitor Chilean-Peruvian quota negotiation outcomes as the inflection indicator for raw material cost trajectories across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| MarinTrust Certification Investment | Unlocks premium aquaculture contract eligibility for Peruvian and Chilean processors facing EU Green Deal traceability mandates. |
| Backward Integration into Controlled Fisheries | Secures raw material access against PRODUCE ministry quota volatility for integrated operators like Omega Protein Corporation. |
| Enzymatic Hydrolysis Capacity Addition | Enables peptide fractionation for Norwegian salmon feed compounders adopting species-specific diet formulations. |
| Long-term Offtake Agreement Structuring | Displaces spot-price buying in Mekong Delta shrimp feed mills consolidating procurement around certified supply chains. |
| Geographic Processing Asset Diversification | Spreads El Niño biomass risk across Norwegian-Peruvian dual-hemisphere networks exemplified by Austevoll Seafood ASA. |
Research Approach
Initial hypotheses were tested against primary input from Peruvian processing plant managers, Southeast Asian shrimp feed procurement leads, Norwegian salmon feed compounder technical directors, and EU regulatory affairs specialists, then refined through secondary validation. Primary fieldwork combined structured interviews with customs/trade data, PRODUCE ministry quota announcements, MarinTrust certification registries, and SEC filings from publicly traded marine ingredient processors. Bottom-up volume modeling across extraction technology tiers and top-down macroeconomic triangulation anchored the analytical framework.
Variance-decomposition analysis isolated drivers across product type, quality grade, extraction method, and end-use industry segmentation dimensions. CAGRs were derived from fitted trend projections incorporating anchovy biomass assessment cycles, EU REACH registration compliance timelines, and aquaculture feed formulation substitution elasticities. Modeling inputs included seasonal quota allocation patterns, enzymatic hydrolysis adoption curves, and pet food palatability premium retention rates.
Underlying assumptions cover sustained EU Green Deal traceability enforcement, stable El Niño Southern Oscillation periodicity, and continued plant protein substitution limits in marine hatchery diets, with deviation risk concentrated in Peruvian quota negotiation outcomes and container shipping rate volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Protein Hydrolysate Market
Seafood
United States Lobster Market
Seafood
Striped Bass Market
Seafood
Lobster Market
Seafood
North America Frozen Seafood Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Canned Anchovy Market
Seafood
Japan Lobster Market
Seafood
Edible Seaweed Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Shellfish Extract Market
Seafood
Japan Frozen Seafood Market
Seafood
Global Seafood Market
Seafood
European Frozen Seafood Market