
 Processed Seafood Market | 2026-2036
Processed Seafood Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Seafood Market Analysis
Institutional foodservice buyers is bifurcating demand away from traditional retail channels as contract catering and quick-service chains expand frozen seafood procurement. Thai Union Frozen Products leverages its integrated supply chain from vessel to shelf to sustain volume leadership across European and North American accounts. High Liner Foods anchors its position through deep specialization in breaded and battered whitefish products for the North American foodservice sector. Leroy Seafood Group competes via its dominance in Atlantic salmon farming and value-added processing for premium retail segments.
Processed seafood encompasses fish and shellfish subjected to preservation or transformation through freezing, canning, drying, smoking, or battering, typically requiring temperature-controlled storage between minus 18 and minus 25 degrees Celsius for frozen categories to maintain protein integrity and sensory quality. These products serve commercial food manufacturing, foodservice operations, and retail consumption by extending shelf life, standardizing portion weights, and reducing preparation labor. Frozen fish leads product type value generation due to its alignment with bulk institutional purchasing and extended distribution reach, while smoked seafood commands premium positioning in specialty retail channels. Online retail distribution is expanding fastest among channels as direct-to-consumer cold-chain logistics mature, though supermarkets still occupy the dominant share of volume throughput.
The EU's EFSA and the FDA in the United States enforce Hazard Analysis Critical Control Point protocols and species labeling standards that shape product formulation, import documentation, and facility certification requirements for market access. REACH and RoHS frameworks in Europe additionally govern packaging material composition, pushing processors toward recyclable tray and vacuum pack substrates. Stakeholders must monitor evolving cold-chain energy costs and regulatory shifts toward carbon-accounted fishing quotas as these forces will determine which processing configurations retain cost advantage.
Market Dynamics
Cold-chain energy costs and carbon-accounted fishing quotas are compressing margin structures and forcing processors to reconfigure facility locations and preservation methods.
Growth Catalysts
- EU Common Fisheries Policy traceability mandates:Tightened documentation requirements for imported seafood are accelerating investment in blockchain-enabled supply chain tracking systems across processing facilities.
- Quick-service restaurant chains:Contract catering and fast-casual dining expansion is pulling frozen value-added formats into centralized procurement programs with standardized portion specifications.
- Vietnam and Indonesia processing scale-up:These countries are capturing export volume through labor cost advantages and government-backed industrial zone development for seafood processing.
Market Restraints
- Fuel price volatility:Diesel and marine gasoil cost swings directly compress margins for distant-water fishing fleets and intercontinental refrigerated transport.
- Atlantic salmon supply concentration:Norwegian and Chilean farming operations control critical biomass volumes, creating price-setting power that constrains processor bargaining leverage.
- Plant-based seafood analogues:Improved extrusion and algae-protein formulations are capturing flexitarian consumers in premium retail channels.
Strategic Opportunities
- Direct-to-consumer cold-chain logistics:Mature last-mile refrigerated delivery networks are enabling subscription-based fresh and frozen seafood box services to bypass traditional retail markups.
- EU Green Deal carbon border adjustments:Early certification of low-carbon catch methods will confer preferential market access as embodied emissions become a trade barrier.
- High-pressure processing technology:Non-thermal pasteurization methods are converging with modified atmosphere packaging to extend refrigerated shelf life without freezing damage.
Industry Challenges
- HACCP auditor certification backlog:FDA and EFSA facility approval timelines are stretching to eight months, delaying new plant commissioning and product launches.
- Refrigeration technician scarcity:Ammonia and CO2 cascade system expertise is concentrating with aging workforces, raising maintenance costs and downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Seafood Market |
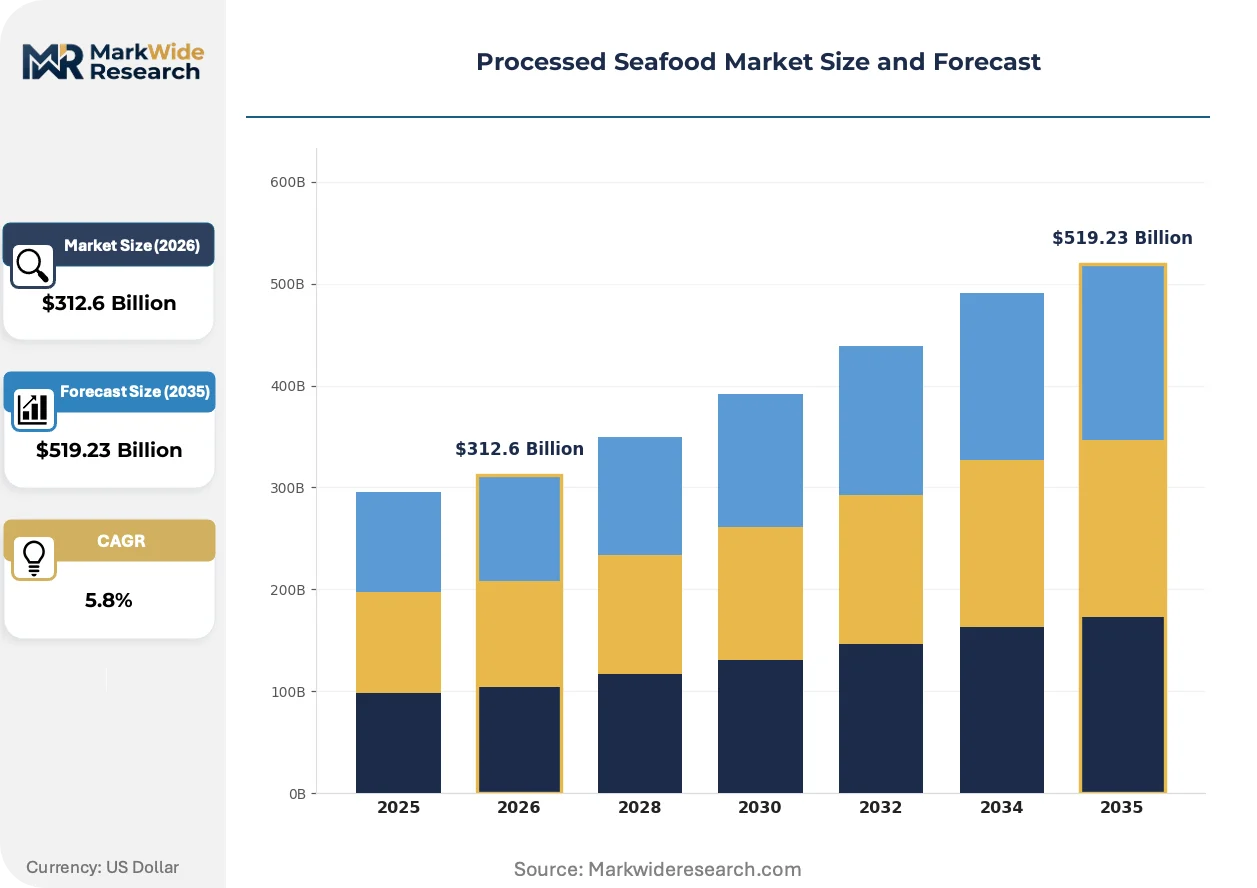
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fish, Canned Seafood, Dried Fish, Smoked Seafood Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Restaurants, Food Processing, Catering Services Packaging Type: Vacuum Packs, Cans, Trays, Bags |
| Companies Covered | High Liner Foods, Pacific Seafood, Thai Union Frozen Products, Iglo Group, Dong Won Fisheries, Mowi, Trident Seafoods, Princes Group, Leroy Seafood Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Seafood Market Emerging Trajectories
Processing technology and preservation science are splitting the market between commodity frozen bulk and premium fresh-chilled segments with diverging equipment requirements and margin profiles.
High-pressure processing is bifurcating the ready-to-eat seafood category between thermally treated shelf-stable products and cold-pasteurized refrigerated formats with superior texture retention. Foodservice distributors in North America are adopting HPP-treated crab and lobster meat for extended holding periods without quality degradation. This technology is compressing the traditional frozen-to-fresh quality gap while commanding price premiums in institutional catering.
REACH and RoHS frameworks in Europe are mandating recyclable tray substrates and eliminating certain plasticizers from vacuum packaging films used for smoked fish. Processors must reformulate packaging specifications and revalidate shelf-life claims under the new material constraints. The smoked salmon segment is absorbing the highest compliance costs due to its dependence on oxygen-barrier film performance.
Institutional buyers are consolidating procurement through specialized seafood purchasing cooperatives that aggregate volume across hospital, university, and corporate catering operations. These cooperatives are displacing traditional broadline foodservice distributors for frozen whitefish and value-added portions. The model is most developed in the United States and United Kingdom where contract catering markets have achieved sufficient scale.
Processed Seafood Market Segmentation
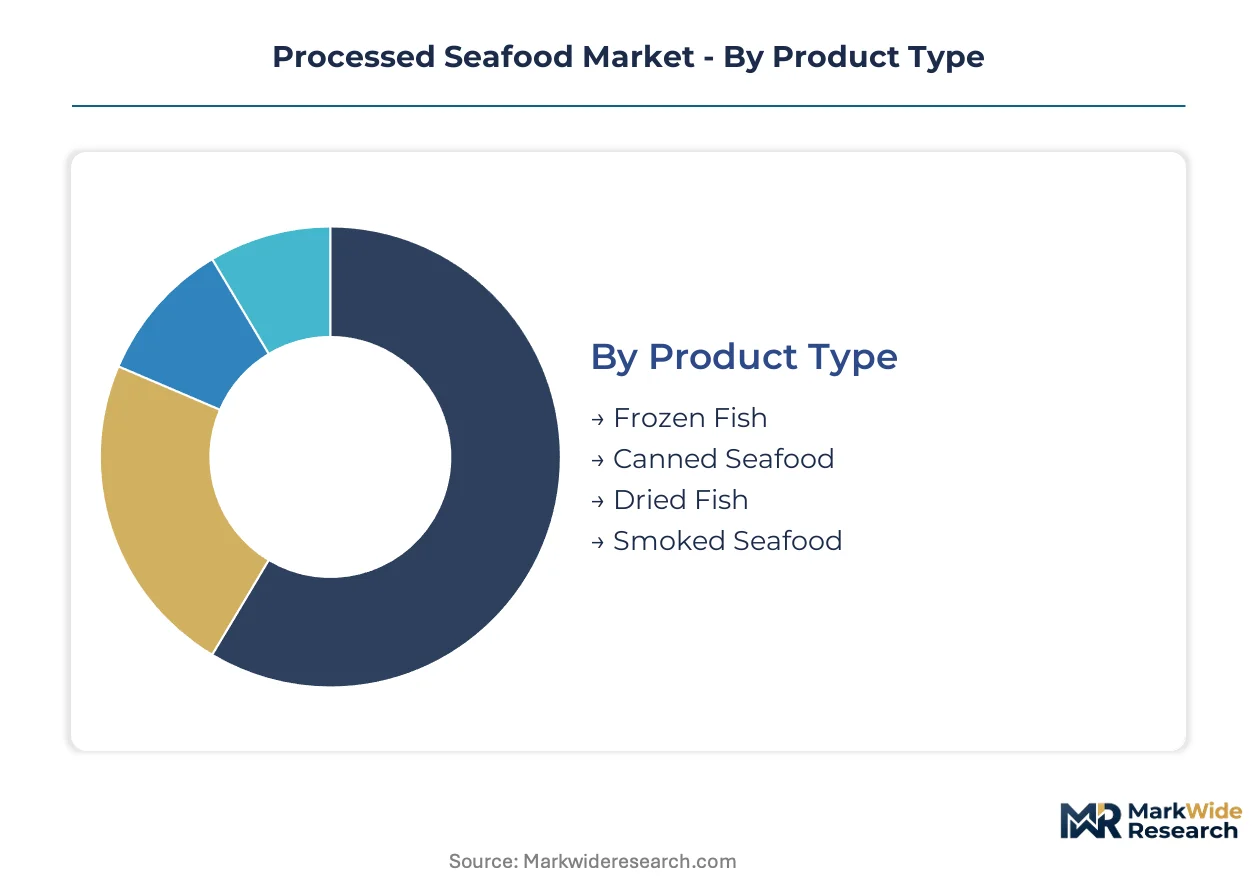
Segmentation in processed seafood reveals how preservation technology, channel economics, and end-use requirements partition margin pools across distinct operational configurations. Understanding these divisions helps processors align capital deployment with where value capture concentrates.
Product Type:
Frozen fish commands the deepest margin pools due to bulk institutional contracting and extended distribution economics, while smoked formats extract premiums through specialty positioning.
- Frozen Fish:Temperature-controlled preservation at minus 18 to minus 25 degrees Celsius maintains protein integrity across extended supply chains. Quick-service restaurant chains in the United States and contract catering operations in the United Kingdom are consolidating procurement of standardized portions, pulling volume away from retail fragmentation.
- Smoked Seafood:Cold-smoking and hot-smoking techniques transform salmon, mackerel, and trout into shelf-stable delicacies with distinct sensory profiles. Specialty retailers in France and Germany absorb compliance costs from REACH packaging mandates while sustaining price premiums through origin certification.
- Canned Seafood:Thermal sterilization in hermetically sealed containers delivers ambient-stable protein for emergency stockpiling and price-sensitive household segments.
- Dried Fish:Moisture reduction through sun-drying or mechanical dehydration concentrates flavor and extends shelf life without refrigeration infrastructure.
The dominant share belongs to frozen fish, while smoked seafood is closing the gap fastest.
Distribution Channel:
Channel selection determines working capital intensity and margin erosion from cold-chain requirements, with digital platforms disrupting traditional throughput economics.
- Supermarkets:Multi-temperature display infrastructure and established supplier relationships sustain volume leadership across European and North American markets. Refrigerated and frozen seafood sections in Tesco, Carrefour, and Kroger stores handle the bulk of household procurement despite shrinking foot traffic.
- Online Retail:Direct-to-consumer subscription models and meal-kit integrations are bypassing traditional retail markups through last-mile refrigerated logistics. Cold-chain maturity in the Netherlands and urban China is enabling same-day delivery of fresh-chilled and frozen formats.
- Convenience Stores:Limited cold-storage capacity restricts assortment to shelf-stable canned and dried categories with higher inventory turns.
- Wholesale:Foodservice distributors aggregate institutional volume through specialized seafood purchasing cooperatives in the United States and United Kingdom.
Supermarkets retain the dominant position, though online retail is expanding most quickly.
End User:
End-use concentration shapes formulation priorities, with foodservice buyers demanding labor-saving value-addition and households prioritizing convenience and transparency.
- Restaurants:Quick-service chains and fast-casual dining operations specify pre-portioned, pre-battered formats that minimize kitchen labor and standardize plate costs. Centralized procurement programs at Yum Brands and McDonald's are displacing broadline distributor relationships.
- Households:Retail consumers gravitate toward vacuum-packed fresh-chilled and frozen formats with clear origin labeling and simplified preparation instructions.
- Food Processing:Manufacturers of ready meals and seafood-based ingredients require bulk frozen blocks and mechanically separated meat for further transformation.
- Catering Services:Hospital, university, and corporate contract caterers aggregate demand through purchasing cooperatives that specify HACCP-certified suppliers.
Restaurants hold the dominant share, while catering services are climbing the fastest.
Packaging Type:
Material specifications under REACH and RoHS frameworks are restructuring cost profiles, with oxygen-barrier performance commanding technical investment.
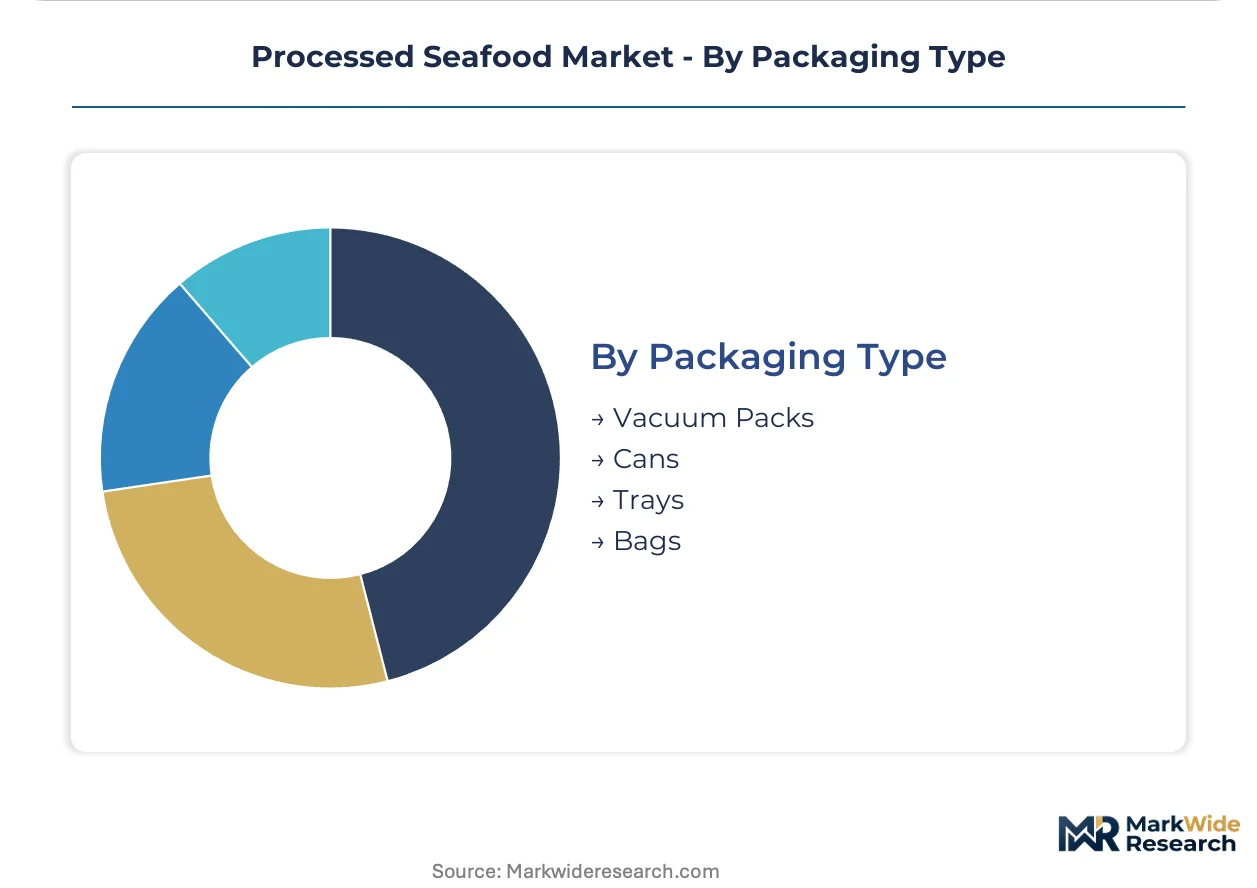
- Vacuum Packs:Multi-layer barrier films exclude oxygen to extend refrigerated shelf life of smoked salmon and fresh-chilled fillets. European processors are reformulating specifications to eliminate restricted plasticizers while maintaining barrier performance.
- Cans:Lacquered steel and aluminum containers deliver hermetic sealing for thermally processed tuna, sardines, and mackerel with ambient stability.
- Trays:Modified atmosphere packaging in rigid or semi-rigid substrates presents retail-ready portions with controlled gas compositions.
- Bags:Flexible laminated structures offer cost-efficient containment for frozen bulk and value-added breaded products.
Vacuum packs dominate premium positioning, while trays are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure anchors European seafood distribution, while Vietnam's Vung Tau processing corridor and Indonesia's Bitung industrial zone drive Asia-Pacific export capacity expansion.
United States
Quick-service restaurant chains and institutional foodservice cooperatives are consolidating frozen seafood procurement through centralized programs. FDA enforces Hazard Analysis Critical Control Point protocols that shape facility certification and import documentation requirements. Seattle anchors Pacific Northwest processing operations where Trident Seafoods maintains integrated vessel-to-shelf capabilities for Alaskan pollock and Pacific cod.
Norway
Atlantic salmon farming operations supply critical biomass for value-added processing across European retail channels. The country's national veterinary regulator enforces strict aquaculture health standards that constrain production expansion and sustain price premiums. Bergen hosts Mowi's headquarters and primary processing facilities, concentrating salmon farming technology development and export logistics coordination.
Thailand
Shrimp aquaculture and tuna canning operations serve contract manufacturing for global retail brands. Government-backed industrial zone development in Samut Sakhon Province accelerates processing capacity expansion with preferential utility pricing. Thai Union Frozen Products leverages integrated operations from vessel procurement to retail shelf placement across European and North American accounts.
Germany
Specialty retailers in Hamburg and Berlin sustain premium positioning for smoked salmon and marinated herring products. REACH and RoHS frameworks mandate recyclable packaging substrates and eliminate restricted plasticizers from vacuum barrier films. Bremerhaven's deep-water port facilities handle bulk frozen whitefish imports for redistribution to Central European foodservice distributors.
Vietnam
Pangasius farming and shrimp processing operations capture export volume through labor cost advantages and EU-Vietnam free trade agreement tariff preferences. The Ministry of Agriculture and Rural Development administers sustainable catch certifications required for European market access. Vung Tau industrial zones concentrate filleting and freezing operations for pangasius destined for North American and European retail channels.
Processed Seafood Market Vendor Landscape
Concentration sits with integrated aquaculture-to-retail conglomerates and specialized frozen foodservice suppliers that control critical biomass or procurement relationships. The vendor base spans three tiers: scale-driven commodity processors with vessel fleets and farming concessions, mid-cap specialists in single-species value-added formats, and regional distributors with cold-chain logistics assets. Competitive moves center on backward integration into farming operations and forward integration into direct retail channels, particularly subscription-based seafood box services.
Within the integrated conglomerate tier, Thai Union Frozen Products and Mowi exemplify contrasting archetypes—one anchored in diversified species procurement and contract manufacturing, the other in captive salmon biomass and premium retail positioning. High Liner Foods occupies a distinct foodservice-specialist position, representing deep specialization in standardized portions for institutional buyers. Leroy Seafood Group sits within the Atlantic salmon farming cluster, exemplifying vertical control from egg production through smoked salmon retail packaging.
| Leading Market Players |
|---|
| High Liner Foods |
| Pacific Seafood |
| Thai Union Frozen Products |
| Iglo Group |
| Dong Won Fisheries |
| Mowi |
| Trident Seafoods |
| Princes Group |
| Leroy Seafood Group |
| Others |
Supply Flow & Price Mechanics
Fleet-scale cold-storage capacity utilization at Thai Union and Mowi processing plants creates nonlinear cost advantages that compress price floors for commodity frozen formats while sustaining premium capture in origin-certified smoked segments. This scale concentration forces mid-cap processors toward specialized species or regional niche positioning to escape margin compression.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with quick-service chains extracting double-digit percentage reductions on frozen whitefish blocks above container-load thresholds while specialty retailers absorb full list pricing for small-batch smoked salmon. Pricing stratifies across premium, standard, and economy tiers based on HACCP certification tier and catch method documentation. Cost compression in the economy tier is intensifying because diesel price volatility feeds directly into distant-water fleet operating costs. Foodservice cooperatives exhibit highest price sensitivity through aggregated tender processes, while premium retail channels demonstrate lowest sensitivity due to origin storytelling and shelf-life performance.
Supply Chain Analysis
Inventory lead times stretch from Norwegian salmon harvest through European smoking facilities to North American retail placement, creating working capital intensity that favors integrated operators with balance-sheet capacity to carry frozen biomass through seasonal price troughs. Geographic supply concentration centers on Norway, Chile, and Vietnam for Atlantic salmon, pangasius, and shrimp respectively. Raw material dependencies rest on marine gasoil for distant-water fleets, ammonia refrigerant for cold-storage infrastructure, and oxygen-barrier films for vacuum packaging. Single-source vulnerability concentrates in Norwegian salmon farming operations that control critical biomass volumes. Distribution runs through Rotterdam's cold-chain hub for European redistribution and Seattle-Tacoma corridor for North American foodservice aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through institutional foodservice cooperatives in the United States and United Kingdom, fragmenting traditional distributor relationships and forcing processors toward direct contracting models that sacrifice margin for volume security.
For Market Incumbents: Shield margin pools by securing backward integration into farming concessions in Vietnam and Indonesia before labor cost advantages erode, while accelerating blockchain-enabled traceability certification to meet EU Common Fisheries Policy documentation mandates that smaller competitors cannot fund. Plant-based seafood analogues represent the most pressing substitute threat in premium retail channels. For New Entrants and Emerging Players: EU-Vietnam free trade agreement tariff preferences offer a certification fast-track for pangasius processors seeking European market access with reduced duty exposure compared to non-FTA origins. The most penetrable white-space sits in direct-to-consumer subscription seafood boxes in urban China and the Netherlands where last-mile cold-chain maturity enables same-day delivery. A go-to-market angle anchored on carbon-accounted catch methods aligns with impending EU Green Deal border adjustments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based seafood box services and institutional foodservice cooperatives with multi-year offtake agreements, suggesting these archetypes warrant premium valuation multiples over transactional spot-market processors. Acquisition targets should prioritize mid-cap specialists with HACCP-certified facilities and established relationships with quick-service restaurant chains. The signal to watch is FDA facility approval timeline compression, which would indicate regulatory capacity expansion and accelerate new plant commissioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Concessions | Captures biomass cost control in Vietnam and Indonesia processing zones. |
| Blockchain Traceability Certification | Satisfies EU Common Fisheries Policy documentation mandates for import access. |
| Direct-to-Consumer Subscription Launch | Bypasses retail markups through mature last-mile cold-chain logistics networks. |
| High-Pressure Processing Technology Adoption | Extends refrigerated shelf life for foodservice crab and lobster meat segments. |
| Carbon-Accounted Catch Certification | Secures preferential EU market access under Green Deal border adjustment mechanisms. |
Methodological Framework
Desk research of customs trade databases, cold-chain logistics operator disclosures, and EU regulatory filings preceded structured interviews with seafood procurement directors at quick-service restaurant chains, plant managers at Vietnamese processing facilities, regulatory affairs leads at salmon farming operations, and category buyers at European supermarket groups. Secondary validation drew from EFSA guidance documents, FDA HACCP facility registries, and ASEAN fisheries development reports. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis.
Variance decomposition across product type, distribution channel, end-user segment, and packaging format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation weighted by baseline value shares. Industry-specific forecast inputs included cold-chain energy cost trajectories and carbon-accounted fishing quota implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU-Vietnam free trade agreement provisions or abrupt fuel price regime shifts would require recalibration. Forecasts reflect documented assumptions regarding processing capacity expansion timelines and regulatory approval velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Herring Market
Seafood
Molluscs Market
Seafood
Oyster Meal Market
Seafood
Saudi Arabia Seafood Market
Seafood
Toothfish Market
Seafood
Processed Seafood and Seafood Processing Equipment Market
Seafood
United States Lobster Market
Seafood
Rainbow Trout Market
Seafood
European Frozen Seafood Market
Seafood
Krill Meal Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Mussel Oil Market
Seafood
Canned Anchovy Market
Seafood
China Crustaceans Market
Seafood
Fish Protein Concentrate Market
Seafood
North America Frozen Seafood Market