
 Food Clamshells Market | 2026-2036
Food Clamshells Market Size, Share, and Industry Trends Forecast 2026-2036
Food Clamshells Market Analysis
EU REACH compliance is rebalancing the cost-of-entry calculus for European food clamshell suppliers by mandating stricter substance restrictions and recyclability thresholds. Dart Container Corporation leverages its captive polystyrene recycling infrastructure to sustain cost advantages across North American quick-service channels. Sabert Corporation anchors its competitive position through bio-based resin partnerships that reduce fossil-derived content in hinged containers. Genpak LLC specializes in thermoformed APET designs that navigate the tension between optical clarity and post-consumer recycled mandates.
Food clamshells are rigid, hinged-lid containers typically thermoformed from polyethylene terephthalate, polystyrene, or molded fiber pulp, designed to protect perishable items through controlled closure integrity and stackable geometry. Their primary commercial purpose centers on extending shelf visibility while containing moisture and oxygen exchange for ready-to-eat meals, berries, and deli portions. The plastic segment still dominates unit volume but faces margin compression as EPR fees expand across jurisdictions, while paperboard clamshells capture premium positioning in organic retail channels where fiber-based aesthetics command shelf price premiums. Bio-based materials represent the fastest-growing structural pocket, though manufacturing scale constraints limit current throughput against quick-service procurement volumes.
The US FDA maintains primary jurisdiction over food-contact substance notifications, while the EPA oversees emerging per- and polyfluoroalkyl substance restrictions that threaten legacy grease-resistant coatings in molded fiber applications. California's SB 54 implementation timeline tightens recycled content minimums, forcing suppliers to certify feedstock provenance or risk exclusion from state-procurement contracts. Stakeholders must monitor how fragmented state-level EPR legislation diverges from federal inaction, creating compliance patchworks that favor multi-jurisdictional operators over regional specialists.
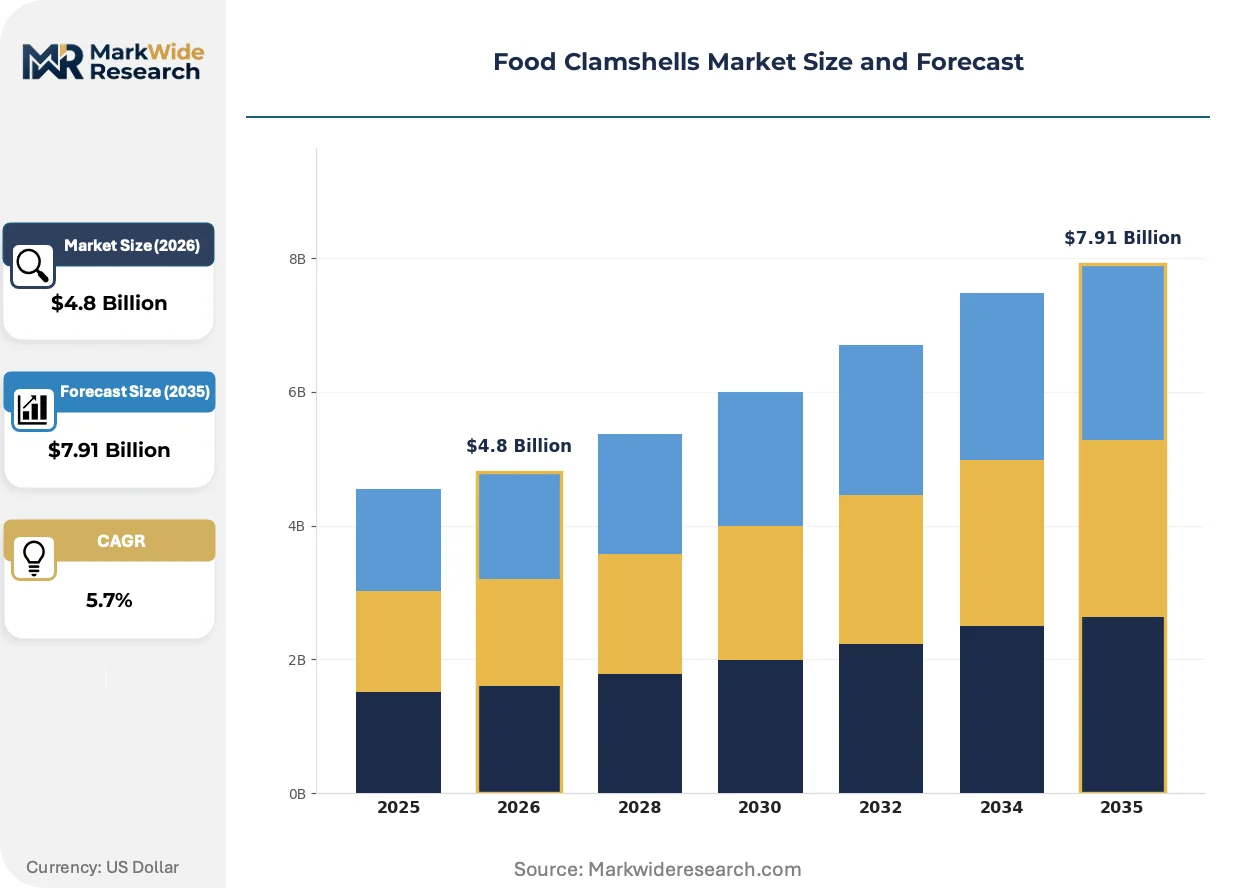
Market Dynamics
Extended producer responsibility fees are restructuring cost allocation across food clamshell supply chains, forcing thermoformers to internalize end-of-life management expenses previously borne by municipal waste systems.
Growth Catalysts
- California SB 54 mandates:Recycled content minimums for single-use packaging create certified feedstock demand that rewards early compliance investments by molded fiber suppliers.
- Quick-service deli counters:Grocery retailers are expanding grab-and-go prepared food sections that require stackable, tamper-evident hinged containers for portion-controlled merchandising.
- PLA resin advances:Bio-based polylactic acid formulations now achieve thermal stability thresholds suitable for hot-fill applications previously restricted to fossil-derived polymers.
Market Restraints
- rPET flake shortages:Post-consumer polyethylene terephthalate collection gaps in the United States limit feedstock availability for clear clamshell production at scale.
- EU REACH substance restrictions:Registration, Evaluation, Authorization and Restriction of Chemicals compliance adds testing costs that disadvantage smaller thermoforming operations without dedicated regulatory staff.
- Per- and polyfluoroalkyl substance bans:Emerging EPA restrictions on PFAS grease-resistant coatings threaten functionality of molded fiber pulp containers for oily prepared foods.
Strategic Opportunities
- Midwest US dairy clusters:Wisconsin and Minnesota cheese packaging operations remain underpenetrated by bio-based hinged-lid suppliers focused on coastal organic channels.
- Deposit-return scheme alignment:Oregon and Maine bottle bill expansions into rigid food containers create infrastructure for closed-loop clamshell recovery that reduces virgin resin dependence.
- Smart-label integration:Time-temperature indicators embedded during thermoforming are converging with RFID traceability to reduce retail shrink for berry and cut-fruit applications.
Industry Challenges
- Thermoforming die engineering:Skilled tool-and-die craftsmanship for multi-cavity hinged-lid molds is concentrating among retiring specialists without adequate apprenticeship pipeline replacement.
- Food-contact notification timelines:US FDA clearance for novel bio-based additives extends 18-24 months, compressing product development windows against fast-moving retail sustainability commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Clamshells Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paperboard, Bio-based, Styrofoam Closure Type: Snap Lock, Hinge, Lidding, Adhesive End User: Food Service, Retail, Catering, Bakery Packaging Size: Single, Double, Multi-compartment, Bulk |
| Companies Covered | Dart Container Corporation, Sabert Corporation, Genpak LLC, Anchor Packaging, Pactiv Evergreen Inc., Sonoco Products, Amcor, VisiPak, Transparent Container, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Clamshells Market Emerging Trajectories
Active material science breakthroughs are dissolving the historical trade-off between optical clarity and compostability in rigid food packaging, enabling new performance tiers that bypass traditional polymer categories entirely.
Thin-wall polypropylene formulations with nucleating agent packages are modularizing production economics for dairy and deli applications previously dominated by amorphous polyethylene terephthalate. Midwest co-packers serving club store private labels are adopting these resins at accelerating rates to reduce unit material weights while maintaining stack strength. The technology is modularizing capital deployment decisions, allowing mid-volume thermoformers to serve multiple end-use specifications from shared extrusion assets without dedicated PET or PS lines.
EU Single-Use Plastics Directive Article 12 labeling requirements are mandating standardized consumer disposal instructions that reshape packaging design briefs across export-oriented North American suppliers. The regulation forces explicit material identification and appropriate waste stream guidance on all rigid food containers placed on European Union markets. Berry shippers in California and Mexico exporting to Dutch and German retail chains are redesigning lid geometries to accommodate mandated labeling zones without compromising closure integrity.
Direct-store-delivery consolidation among bakery and prepared-food distributors is compressing order cycles from weekly to twice-weekly for clamshell replenishment. Regional distributors serving independent grocers in Texas and Florida are unbundling full-truckload minimums in favor of mixed-SKU pallet programs that reward packaging suppliers with multi-product portfolio breadth. This pattern is most visible in the southeastern United States where independent supermarket cooperatives are gaining share against national chains through localized assortment flexibility.
Food Clamshells Market Segmentation
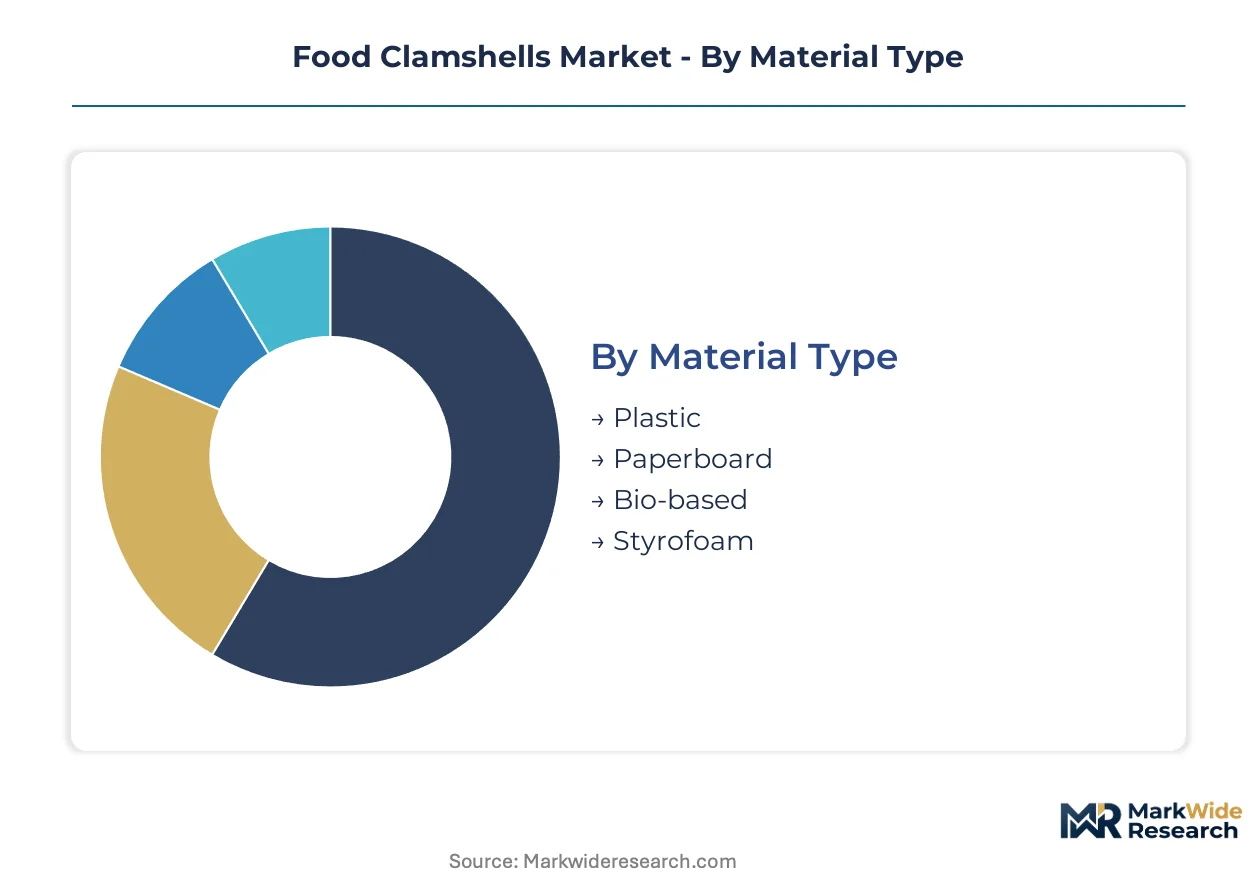
Food clamshell segmentation reveals divergent margin structures across material chemistries and closure geometries. Procurement patterns in quick-service channels favor standardized hinge designs, while premium retail segments reward material differentiation and customized compartment configurations.
Material Type:
Volume concentration tilts toward fossil-derived polymers, yet premium positioning accrues to fiber-based and bio-based alternatives commanding shelf price premiums in organic channels.
- Plastic:Thermoformed PET and polystyrene formulations dominate unit throughput across North American quick-service and deli applications. Clarity and seal integrity requirements in berry packaging sustain demand despite EPR fee compression in California and Oregon jurisdictions.
- Bio-based:Polylactic acid and polyhydroxyalkanoate resins are gaining formulation stability for hot-fill applications previously restricted to conventional polymers. PLA thermal stability advances are unlocking quick-service procurement volumes in coastal states with aggressive recycled content mandates.
- Paperboard:Molded fiber pulp serves prepared foods and bakery segments where grease resistance and compostability align with retailer sustainability commitments. PFAS coating restrictions threaten functionality in oily food applications.
- Styrofoam:Expanded polystyrene retains cost advantages in bulk protein transport and institutional catering, though regulatory bans in New York, Maine, and Maryland are constraining addressable market scope.
Mature deployment sits with Plastic. Newer deployment is concentrated in Bio-based.
Closure Type:
Application requirements dictate geometry selection, with tamper-evidence and resealability driving specification divergence across food service and retail channels.
- Hinge:Integral living hinges dominate retail berry and cut-fruit applications where one-handed opening and reclosure preserve product freshness through multiple use occasions. Stackability requirements in club store distribution reinforce specification stickiness.
- Snap Lock:Audible closure feedback suits deli counter and prepared meal applications where tamper evidence supports food safety protocols. Grocery retailers in Texas and Florida are standardizing snap-lock geometries across private label programs.
- Lidding:Separate film or rigid lids accommodate portion flexibility in catering and institutional settings where mixed-SKU replenishment cycles compress order frequencies.
- Adhesive:Peel-and-seal formulations serve bakery and confectionery segments where reclosure is unnecessary and material cost minimization takes priority.
Hinge configurations anchor current procurement volumes. Snap Lock designs are climbing the fastest among closure categories as tamper-evidence requirements tighten across retail deli segments.
End User:
Customer scale and order frequency create segmentation between high-volume contractual supply and fragmented spot purchasing.
- Food Service:Quick-service chains and institutional cafeterias drive standardized, high-volume procurement with stringent stackability and thermal performance specifications. National account consolidation favors suppliers with multi-plant manufacturing footprints.
- Retail:Supermarket deli counters and produce departments demand optical clarity and printability for brand differentiation. Independent grocers in the southeastern United States are unbundling full-truckload minimums in favor of mixed-SKU pallet programs.
- Catering:Event-based demand exhibits seasonal volatility and customization requirements that disadvantage standardized thermoforming operations.
- Bakery:Moisture retention and grease resistance specifications vary widely across artisan and commercial production scales.
Food Service represents the volume anchor. Retail channels are expanding most quickly as grab-and-go prepared food sections proliferate across grocery formats.
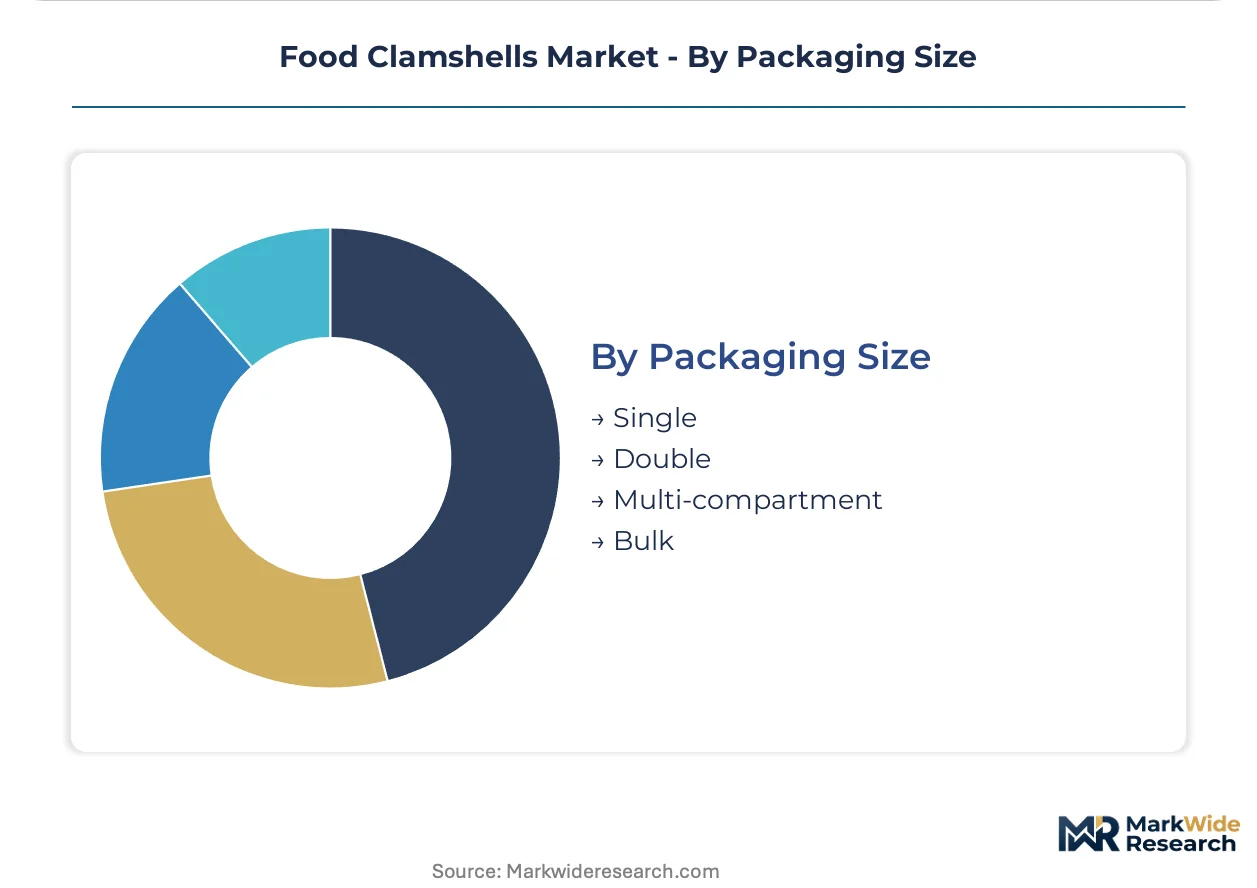
Packaging Size:
Portion control trends and club store formats are reshaping compartment geometry requirements across consumption occasions.
- Single:Individual portion containers serve quick-service value meal bundling and vending machine applications where space efficiency and theft deterrence converge.
- Multi-compartment:Separated chambers for protein, starch, and vegetable components dominate prepared meal and bento-style retail offerings. Wisconsin and Minnesota cheese packaging operations are adopting multi-compartment designs for sampler assortments.
- Double:Two-chamber configurations balance portion flexibility with manufacturing simplicity in sandwich and salad applications.
- Bulk:Large-format containers serve institutional catering and food processor intermediate packaging where downstream repackaging occurs.
Single-serve formats anchor current production capacity. Multi-compartment designs are gaining share fastest as meal-kit and prepared food segments expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest US dairy clusters and California produce corridors concentrate thermoforming capacity through state-level tax incentives for recycled-content manufacturing. Quick-service procurement volumes gravitate toward these zones to minimize logistics costs for hinged-lid containers.
United States
California SB 54 mandates are forcing thermoformers to certify post-consumer recycled feedstock provenance for state procurement contracts. The EPA oversees emerging PFAS restrictions that threaten grease-resistant coatings in molded fiber applications. Wisconsin and Minnesota cheese packaging operations remain underpenetrated by bio-based suppliers focused on coastal organic channels.
Germany
EU REACH compliance is rebalancing cost-of-entry calculus for European suppliers through stricter substance restrictions and recyclability thresholds. The EU Single-Use Plastics Directive Article 12 mandates standardized consumer disposal instructions on all rigid food containers. Dutch and German retail chains are driving redesign of lid geometries to accommodate labeling zones without compromising closure integrity.
France
Organic retail channels command shelf price premiums for fiber-based clamshell aesthetics in Paris and Lyon metropolitan markets. ECHA substance evaluations are extending testing timelines for novel bio-based additives. The Auvergne-Rhône-Alpes region hosts thermoforming operations serving export-oriented berry shippers from Spain and North Africa.
Canada
Ontario and Quebec bottle bill expansions into rigid food containers are creating infrastructure for closed-loop clamshell recovery. Health Canada maintains jurisdiction over food-contact substance notifications parallel to US FDA timelines. Toronto-area distributors are unbundling full-truckload minimums in favor of mixed-SKU pallet programs for independent grocers.
China
Dual carbon goals are accelerating domestic bio-based resin capacity expansion for food-contact applications. SAMR oversees national standards for food packaging safety that increasingly reference EU test methodologies. The Yangtze River Delta concentrates thermoforming equipment manufacturing and export-oriented clamshell production for Southeast Asian quick-service chains.
Food Clamshells Market Vendor Landscape
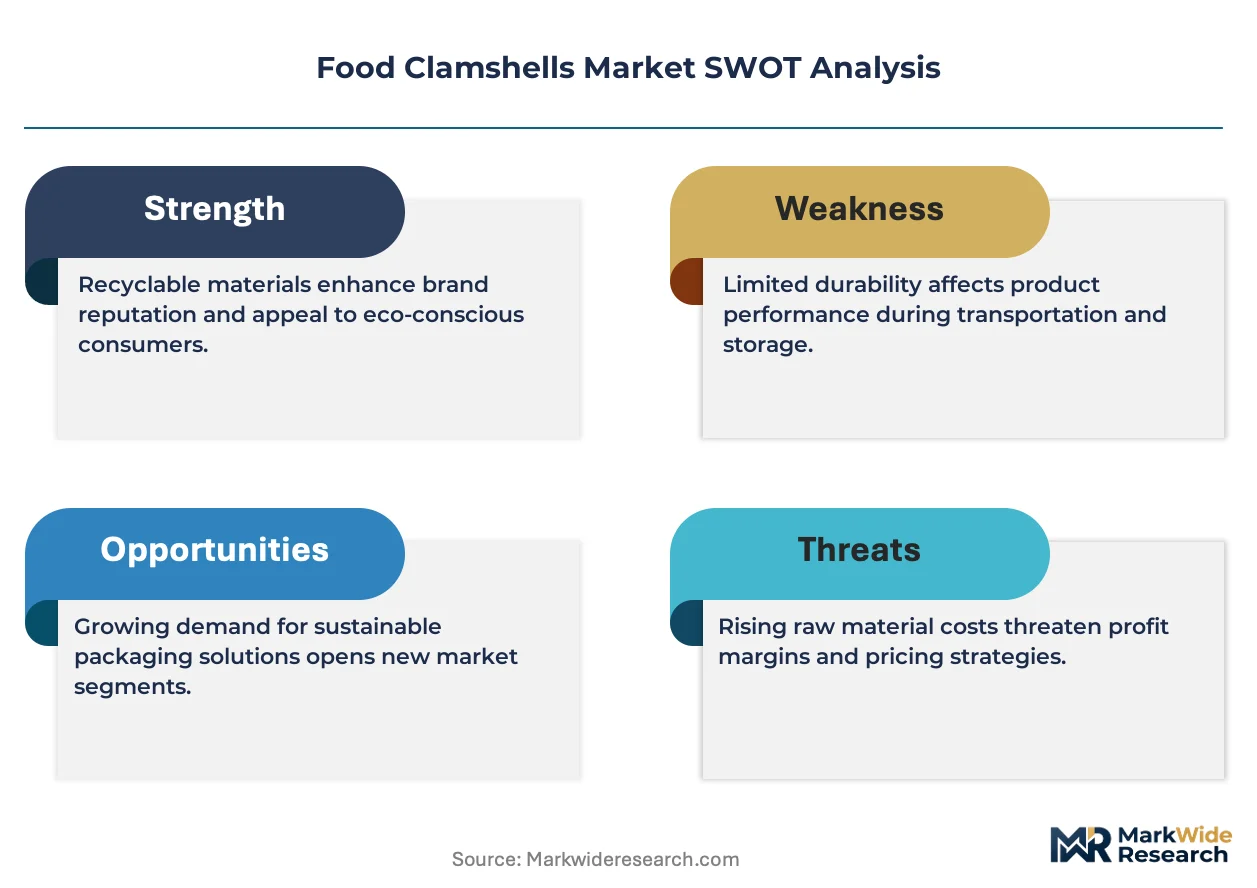
North American producers anchor one tier; European specialists hold regulatory compliance advantages through early REACH investments. The vendor base separates into three tiers: integrated resin-to-container operators, mid-volume thermoformers with regional footprints, and niche bio-based material developers. Strategic moves concentrate on backward integration into recycled feedstock sourcing and multi-jurisdictional certification capacity to navigate fragmented state-level EPR legislation.
Among US-based fabricators, Dart Container Corporation and Sabert Corporation exemplify divergent archetypes—one leveraging captive recycling infrastructure, the other anchoring competitive position through bio-based resin partnerships. Genpak LLC occupies a position within the optical clarity segment, navigating tensions between APET design performance and post-consumer recycled mandates. These three represent the strategic spectrum: scale-driven vertical integration, sustainability-forward material partnerships, and technical specification specialization.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Sabert Corporation |
| Genpak LLC |
| Anchor Packaging |
| Pactiv Evergreen Inc. |
| Sonoco Products |
| Amcor |
| VisiPak |
| Transparent Container |
| Others |
Supply Flow & Price Mechanics
Thin-wall polypropylene nucleation technology is modularizing production economics across mid-volume thermoformers, simultaneously compressing unit material costs and dispersing manufacturing capacity beyond legacy PET and PS strongholds in California and the Midwest. This process innovation rewards suppliers with shared extrusion assets while eroding the premium pricing power historically held by dedicated clear-clamshell specialists serving berry exporters.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with quick-service chains paying markups for two-week replenishment cycles versus standard four-to-six-week schedules. Three-tier pricing structure across premium, standard, and economy levels stratifies by recycled content certification grade and optical clarity performance. Cost compression in standard-grade hinged containers is intensifying because rPET flake shortages force suppliers to blend virgin resin or absorb feedstock premiums. Independent grocers in Texas and Florida exhibit highest price sensitivity, while national quick-service accounts prioritize supply assurance over unit cost.
Supply Chain Analysis
Food-contact notification qualification gates supplier entry, with US FDA clearance timelines stretching 18-24 months for novel bio-based additives. Manufacturing concentrates in the United States, China, and Germany, with thermoforming equipment fabrication anchored in the Yangtze River Delta. Feedstock supply rests on polystyrene resin from Gulf Coast petrochemical corridors, post-consumer PET flake from domestic collection systems, and polylactic acid from Nebraska and Iowa biorefineries. Single-source vulnerability pervades rPET flake procurement due to fragmented municipal collection infrastructure. Distribution runs through direct-store-delivery networks for prepared foods and full-truckload programs for produce shippers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with backward control over recycled feedstock sourcing and multi-jurisdictional certification capacity determining which suppliers survive fragmented state-level EPR legislation.
For Market Incumbents: Hedge against rPET flake volatility by securing long-term offtake agreements with mechanical recycling operators in California and Oregon. Captive polystyrene recycling infrastructure, as demonstrated by Dart Container Corporation, sustains cost advantages against bio-based entrants. Reinforce market position through FDA food-contact notification pipelines that compress rival product development windows.
For New Entrants and Emerging Players: Begin with Wisconsin and Minnesota dairy clusters, where cheese packaging operations remain underpenetrated by coastal bio-based suppliers fixated on organic retail channels. Multi-compartment hinged-lid designs for sampler assortments offer specification differentiation without competing on clear-clamshell optical performance. A direct-store-delivery service model targeting independent grocers bypasses national account procurement consolidation.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-volume thermoformers with multi-plant footprints and established FDA notification portfolios. Long-term viability hinges on suppliers navigating the transition from fossil-derived polymers to bio-based alternatives without sacrificing thermal performance specifications. Watch for Oregon and Maine bottle bill expansions into rigid food containers as the inflection signal for closed-loop recovery infrastructure maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Captive rPET flake supply insulates against California SB 54 compliance cost spikes. |
| Multi-Jurisdictional Certification Capacity | Simultaneous US FDA and EU REACH clearance accelerates product launches across export channels. |
| Smart-Label Integration Partnership | Time-temperature indicator embedding reduces retail shrink for berry and cut-fruit shippers. |
| Midwest Dairy Cluster Penetration | Wisconsin and Minnesota cheese packaging operations offer underserved demand for bio-based hinged lids. |
| Deposit-Return Scheme Alignment | Oregon and Maine bottle bill expansions create infrastructure for closed-loop clamshell recovery. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with thermoforming plant managers, quick-service procurement directors, retail category buyers, FDA regulatory consultants, and resin supply specialists. Secondary sources included FDA food-contact substance notifications, EPA PFAS restriction dockets, California SB 54 implementation guidance, EU REACH substance restriction updates, and US Census Bureau trade data on rigid plastic packaging imports. Bottom-up capacity modeling triangulated against top-down demand estimates from quick-service chain expansion disclosures and grocery deli counter square footage growth.
Granularity-level modeling operated at material chemistry, closure geometry, end-use channel, and packaging size dimensions across the analysis window. Segment-level CAGRs derived from regression analysis of historical volume trends against explanatory variables including EPR fee implementation timelines, recycled content mandate phase-ins, and quick-service outlet expansion rates. Forecast inputs incorporated PLA thermal stability advancement curves, rPET collection infrastructure buildout assumptions, and thermoforming die engineering capacity constraints.
Regulatory enforcement delays, bio-based resin manufacturing scale bottlenecks, and PFAS coating functionality loss in molded fiber applications are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about state-level EPR legislation adoption pace and FDA notification timeline compression. A model refresh is warranted upon material change in California SB 54 recycled content certification requirements or EPA final PFAS restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
North America Frozen Seafood Market
Seafood
Middle East and Africa Canned Seafood Market
Seafood
Oyster Market
Seafood
GCC Seafood Market
Seafood
Surimi Market
Seafood
Cod Fish Market
Seafood
Europe Shrimp Market
Seafood
South America Canned Seafood Market
Seafood
Sea Biscuits Market
Seafood
Fish Protein Concentrate Market
Seafood
Canned Seafood Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Smoked Whiting Market
Seafood
US Crustacean Market
Seafood
Fin Fish Market
Seafood
Fish Protein Market