
 Fish Fermentation Market | 2026-2036
Fish Fermentation Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Fermentation Market Foresight
Multi-source procurement for raw marine biomass is realigning supply economics across the fish fermentation sector. TripleNine Group A/S leverages its North Atlantic fishing fleet to secure consistent input volumes. Kerry Group plc anchors its position through captive flavor extraction capabilities. FMC Corporation competes on fermentation-derived bioactive compounds for nutraceutical channels.
Fish fermentation denotes the anaerobic enzymatic breakdown of marine proteins and lipids by halophilic and lactic acid bacteria, typically occurring at 15-35% salt concentration over 6-18 months to yield amino acid-rich hydrolysates. The process generates umami-active compounds, volatile sulfur molecules, and bioavailable peptides for food and feed applications. Fermented fish sauce commands the dominant value pool due to entrenched culinary penetration across Southeast Asian and diaspora markets. Starter culture fermentation represents the fastest-expanding technology segment as manufacturers seek batch consistency and reduced histamine risk. Ready-to-eat applications attract premium positioning from specialty restaurants and retail consumers seeking authentic ethnic flavor profiles.
FDA seafood HACCP protocols and EFSA biogenic amine thresholds directly constrain process parameters and finished-product specifications for exporters serving North American and European buyers. BIS and FSSAI standards in India govern domestic labeling and additive restrictions, shaping reformulation requirements for multinational suppliers. Codex Alimentarius guidelines on fermented fish products continue evolving, compelling stakeholders to monitor harmonization trajectories that will determine future market access conditions.
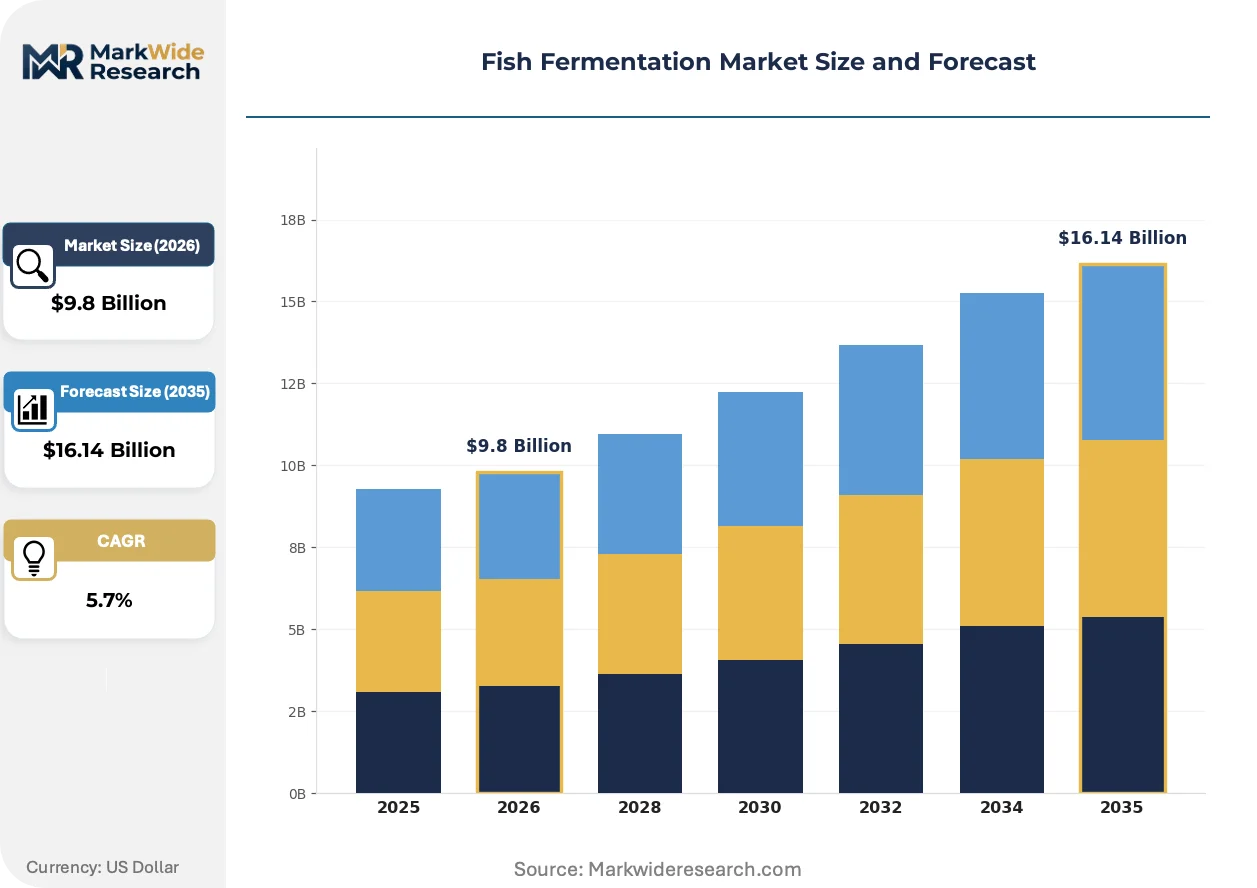
Market Dynamics
Starter culture fermentation technology is compressing batch variability windows while EFSA histamine thresholds force simultaneous process re-engineering across Vietnamese and Thai export corridors.
Growth Catalysts
- EFSA Regulatory Harmonization:Tightening biogenic amine thresholds in European markets are accelerating starter culture adoption as manufacturers seek compliant export pathways.
- Specialty Restaurant Expansion:Southeast Asian fine-dining establishments are integrating premium fermented fish condiments into tasting menus, creating demand for controlled-fermentation supply.
- Mekong Delta Processing Concentration:Vietnam's integrated raw material corridors enable vertical coordination from catch to finished hydrolysate, reducing input transit degradation.
Market Restraints
- Marine Biomass Cost Volatility:North Atlantic and South China Sea catch quotas create inconsistent anchovy and mackerel pricing for fermentation input.
- Supply Concentration Risk:Over half of commercial starter culture strains originate from three biotechnology clusters, creating single-source vulnerability.
- Histamine Detection Limitations:Rapid field testing for biogenic amines remains technically unreliable below 50 ppm thresholds, forcing expensive laboratory verification.
Strategic Opportunities
- Indian Domestic Market Expansion:FSSAI labeling reforms are opening organized retail channels for packaged fish sauce previously confined to unbranded wet markets.
- Nutraceutical Bioactive Extraction:Fermentation-derived peptides are penetrating functional food formulations as manufacturers isolate ACE-inhibitory and antioxidant fractions.
- E-commerce Direct Channels:Diaspora consumer segments in North America and Europe are purchasing heritage-format products through specialized import platforms bypassing traditional distribution.
Industry Challenges
- Halophilic Microbiology Talent Scarcity:Commercial-scale starter culture management requires specialized fermentation science expertise concentrated in limited academic programs.
- Legacy Facility Retrofit Costs:Traditional open-vat operations face capital-intensive enclosure and monitoring system upgrades to meet export-market HACCP documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Fermentation Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented Fish Sauce, Fermented Fish Paste, Dried Fermented Fish, Salted Fermented Fish, Smoked Fermented Fish Fermentation Technology: Natural Fermentation, Starter Culture Fermentation, Mixed Fermentation, Controlled Fermentation Application: Condiments, Ready-to-Eat Products, Culinary Ingredients, Animal Feed Supplements End User: Food Processing Companies, Specialty Restaurants, Retail Consumers, Nutraceutical Manufacturers |
| Companies Covered | Advanced Biotechnologies Inc., FMC Corporation, Kerry Group plc, TripleNine Group A/S, Omega Protein Corporation, Danisco A/S, Associated British Foods plc, Corpesca S.A., LactoSpore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Fermentation Market Shifts & Advancements
Process control technologies and regulatory detection protocols are simultaneously tightening production parameters while opening new application vectors for fermentation-derived ingredients.
Controlled starter culture inoculation is overtaking spontaneous ambient fermentation across commercial operations. Mid-scale Vietnamese and Thai processors are adopting single-strain Lactobacillus and Tetragenococcus protocols to compress variability windows from 12-18 months to 6-9 months. This compression is enabling just-in-time inventory models previously impossible with weather-dependent traditional cycles.
EFSA guidance on biogenic amines in fermented fish products is forcing analytical infrastructure investments across export-oriented facilities. Laboratory accreditation for histamine, cadaverine, and putrescine quantification now gates market access for European-bound shipments. Small-batch artisan producers in Cambodia and Laos are responding by consolidating into cooperative testing pools to share capital burden.
Diaspora procurement patterns are fragmenting traditional wholesale channels. Vietnamese-American and Thai-European consumers are sourcing small-batch heritage products through direct-import platforms rather than ethnic grocery intermediaries. This channel shift is most visible in California, Texas, and Greater London metropolitan zones where subscription-based fermented condiment services are capturing repeat purchase loyalty.
Fish Fermentation Market Segmentation
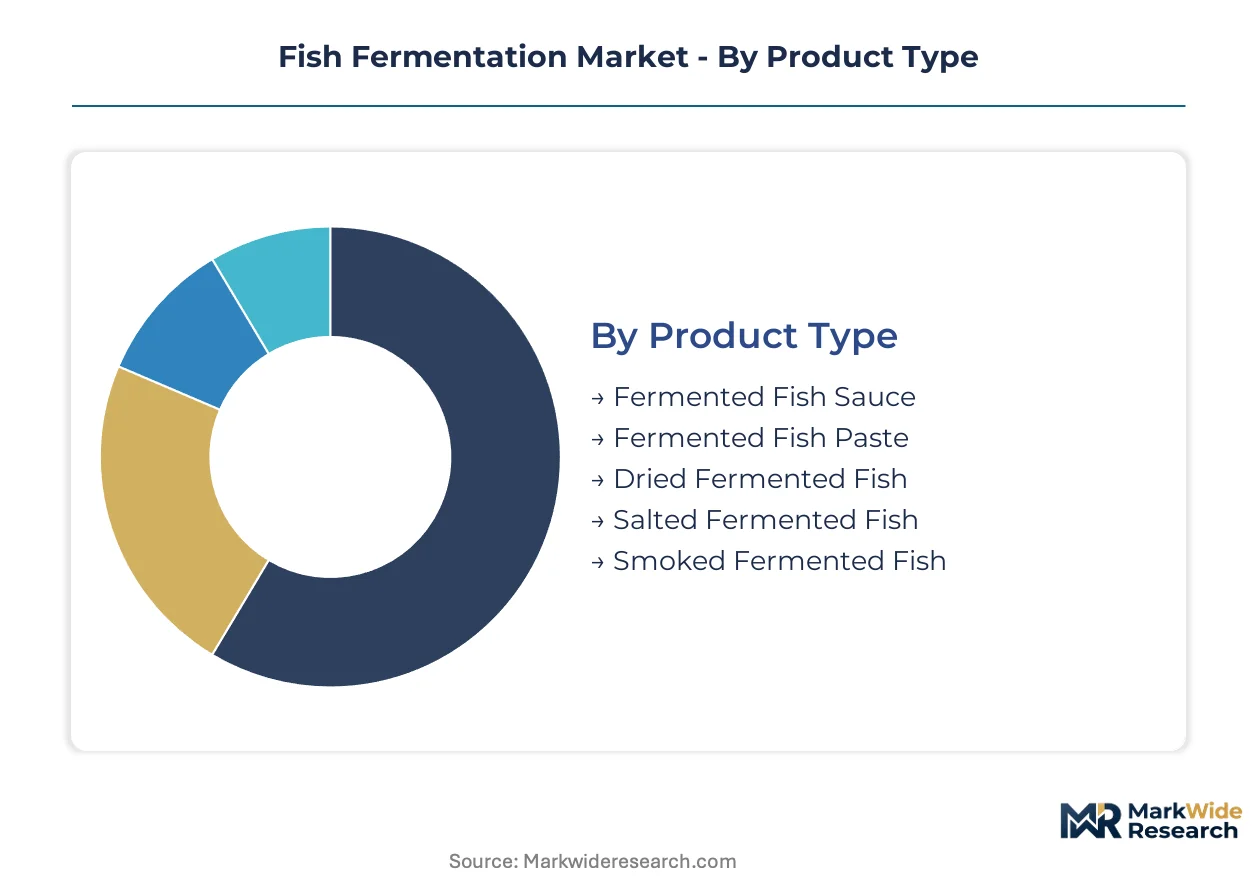
Fish fermentation markets fragment across product formats, process technologies, and buyer specifications that dictate margin structures. Each segment carries distinct regulatory exposure, shelf stability requirements, and geographic demand concentration that shape supplier positioning.
Product Type:
Volume production concentrates in liquid hydrolysates while paste and dried formats command formulation premiums in specialty channels.
- Fermented Fish Sauce:Clear amber liquid containing 20-30% protein hydrolysate with glutamate concentrations above 800 mg/100ml. Demand clusters in Vietnam's Phu Quoc and Thailand's Chonburi provinces where coastal processing infrastructure enables year-round anchovy supply. EFSA histamine thresholds force laboratory verification for European-bound shipments.
- Fermented Fish Paste:Semi-solid emulsion retaining fibrous texture and higher lipid content than sauce equivalents. Specialty restaurants across Bangkok and Ho Chi Minh City specify paste for tableside service and controlled portioning. Starter culture adoption is compressing traditional 18-month cycles to 9 months.
- Dried Fermented Fish:Moisture-reduced shelf-stable format common in Cambodian and Laotian household consumption.
- Salted Fermented Fish:Whole-fish preservation at 25-35% salt concentration for Southeast Asian wet market distribution.
- Smoked Fermented Fish:Dual-process product combining wood-smoke flavor compounds with lactic acid bacterial activity.
Today's leader: Fermented Fish Sauce. Tomorrow's challenger: Fermented Fish Paste.
Fermentation Technology:
Process control sophistication separates export-compliant supply from domestic-grade production.
- Starter Culture Fermentation:Single-strain Tetragenococcus or Lactobacillus inoculation at 10^6 CFU/g initial load. Vietnamese processors in the Mekong Delta corridor are retrofitting open-vat facilities with pH monitoring and temperature control to meet FDA seafood HACCP documentation. This technology enables batch-to-batch consistency previously impossible with ambient methods.
- Controlled Fermentation:Enclosed bioreactor systems with automated salt gradient management and dissolved oxygen monitoring. Thai manufacturers serving European nutraceutical extractors deploy this technology to guarantee peptide bioactivity specifications. Capital intensity limits adoption to facilities above 500-ton annual throughput.
- Natural Fermentation:Ambient microbial succession dependent on seasonal temperature variation.
- Mixed Fermentation:Sequential inoculation combining defined starters with indigenous microflora.
Starter Culture Fermentation captures current investment flows. Controlled Fermentation holds the steepest expansion trajectory for premium extract applications.
Application:
End-use specifications range from sensory-driven condiment formulation to standardized peptide fractions for functional ingredients.
- Condiments:Finished retail products with defined viscosity, color, and amino nitrogen minimums. Vietnam's FSSAI-equivalent labeling reforms are opening organized retail placement for packaged fish sauce previously confined to unbranded channels. Three-tier pricing separates premium island-origin products from standard and economy grades.
- Culinary Ingredients:Industrial-scale hydrolysates for soup base, seasoning blend, and processed food manufacturing. Food processing companies in Thailand specify protein content above 15% and salt below 25% for formulation flexibility. Bulk procurement runs through annual contracts with Mekong Delta processors.
- Ready-to-Eat Products:Pre-formulated meal components requiring no additional preparation.
- Animal Feed Supplements:Fermented protein meals for aquaculture and livestock nutrition.
Condiments anchor current revenue. Culinary Ingredients are gaining share fastest as industrial formulation demand expands.
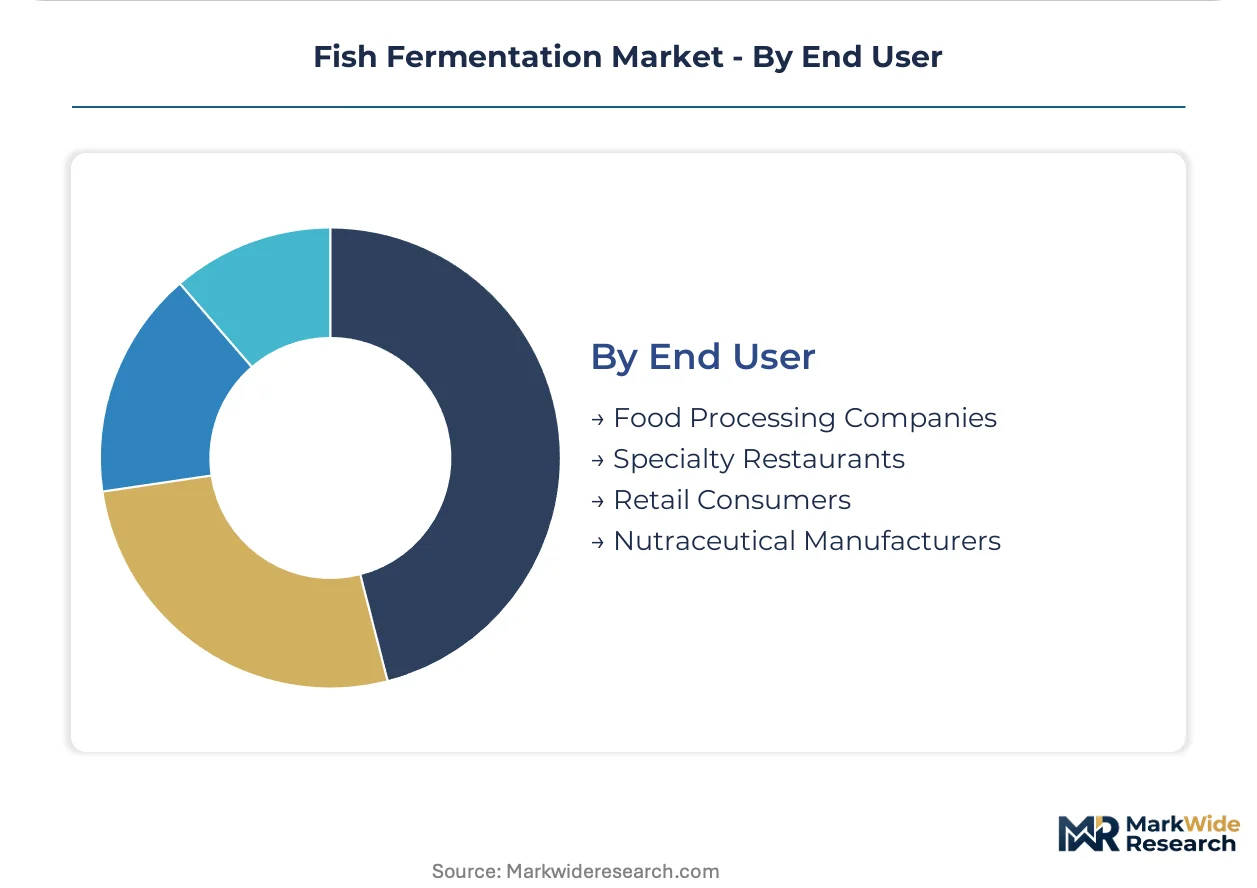
End User:
Buyer sophistication spans from commodity procurement to peptide specification for nutraceutical isolation.
- Food Processing Companies:Volume purchasers requiring consistent amino acid profiles for seasoning base production. These buyers enforce supplier qualification through BIS and FSSAI compliance documentation in India, with audit protocols expanding to cover starter culture traceability.
- Nutraceutical Manufacturers:Specialized buyers isolating ACE-inhibitory and antioxidant peptides for functional food and supplement applications. Kerry Group plc and comparable ingredient houses specify fermentation parameters to maximize bioactive yield. Laboratory quantification of peptide fractions gates supplier approval.
- Specialty Restaurants:Premium segment seeking heritage-format products with defined provenance.
- Retail Consumers:Household purchasers through ethnic grocery and direct-import e-commerce channels.
Food Processing Companies dominate procurement volume. Nutraceutical Manufacturers represent the fastest-growing demand segment as peptide isolation technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mekong Delta processing corridor anchors geographic concentration for fish fermentation capacity, with Vietnam's integrated catch-to-hydrolysate infrastructure commanding dominant export volume. Thai manufacturers compete through controlled fermentation technology serving European nutraceutical extractors. Regulatory divergence between EFSA biogenic amine thresholds and FDA seafood HACCP protocols is forcing corridor-specific compliance investments.
Vietnam
Phu Quoc and Chonburi provinces drive condiment-grade fish sauce output for diaspora markets in California and Texas. FSSAI-equivalent domestic labeling reforms are opening organized retail channels previously confined to wet market distribution. Mekong Delta processors are retrofitting open-vat facilities with pH monitoring and temperature control to meet export-market documentation requirements.
Thailand
Bangkok-based specialty restaurants specify fermented fish paste for tableside service, creating demand for controlled-fermentation supply with compressed 9-month cycles. FDA seafood HACCP audit protocols now cover starter culture traceability for US-bound shipments. Chonburi province coastal infrastructure enables year-round anchovy supply for industrial-scale hydrolysate production.
India
FSSAI labeling reforms are opening organized retail placement for packaged fish sauce previously confined to unbranded channels. BIS standards govern domestic additive restrictions, shaping reformulation requirements for multinational suppliers. Maharashtra and Gujarat processing clusters are developing captive supply chains for culinary ingredient manufacturing.
Cambodia
Small-batch artisan producers are consolidating into cooperative testing pools to share EFSA-mandated analytical infrastructure costs for histamine quantification. Traditional natural fermentation methods face tightening scrutiny under evolving Codex Alimentarius guidelines. Tonle Sap corridor processors are adopting mixed fermentation protocols to balance heritage format authenticity with batch consistency.
Laos
Household consumption of dried fermented fish dominates domestic demand, with limited export-oriented capacity. Rapid field testing limitations below 50 ppm histamine thresholds force expensive laboratory verification for European market access. Vientiane-based cooperatives are exploring starter culture adoption to reduce biogenic amine risk and compress variability windows.
Fish Fermentation Market Competitive Landscape
Global majors compete with regional champions across fermentation technology sophistication and raw material access. The vendor base separates into three tiers: North Atlantic fishing fleet operators securing consistent input volumes, captive flavor extraction houses, and biotechnology specialists supplying defined starter culture strains. Two dominant competitive moves are reshaping positioning: backward integration into marine biomass procurement, and fermentation parameter licensing to guarantee peptide bioactivity specifications for nutraceutical channels.
Within the integrated supply tier, TripleNine Group A/S and Kerry Group plc exemplify contrasting archetypes. TripleNine Group A/S leverages its North Atlantic fishing fleet to anchor raw material security. Kerry Group plc occupies a position defined by captive flavor extraction capabilities serving industrial formulation demand. FMC Corporation represents the biotechnology vector, competing on fermentation-derived bioactive compounds for functional ingredient isolation. These three entities illustrate how geographic origin and corporate structure correlate with strategic emphasis across the value chain.
| Leading Market Players |
|---|
| Advanced Biotechnologies Inc. |
| FMC Corporation |
| Kerry Group plc |
| TripleNine Group A/S |
| Omega Protein Corporation |
| Danisco A/S |
| Associated British Foods plc |
| Corpesca S.A. |
| LactoSpore |
| Others |
Supply & Pricing Matrix
Food processing companies in Thailand and Vietnam enforce contract-based procurement that anchors pricing to anchovy biomass spot markets. This buyer concentration compresses margin buffers for Mekong Delta processors serving European nutraceutical extractors.
Pricing Analysis
Input-cost pass-through from marine biomass volatility dominates pricing structures across fermentation grades. Three-tier pricing structure across premium island-origin, standard Mekong Delta, and economy wet-market tiers reflects certification grade and FDA HACCP documentation status. Pricing pressure stems from EFSA-mandated laboratory verification costs that small-batch Cambodian producers cannot absorb. Retail consumers through ethnic grocery channels exhibit highest price sensitivity, while nutraceutical manufacturers prioritize peptide bioactivity specifications over unit cost.
Supply Chain Analysis
Refrigerated freight costs from coastal catch zones to inland processing facilities consume margin share across Vietnamese and Thai supply corridors. Raw material flows concentrate in Vietnam, Thailand, and Cambodia, with anchovy, salt, and starter culture strains as critical inputs. Single-source vulnerability from three biotechnology clusters supplying commercial Tetragenococcus strains creates supply chain risk. Distribution runs through annual contract arrangements with food processing companies and cooperative testing pools for artisan producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EFSA-regulated European markets and FSSAI-reforming Indian domestic channels creates margin expansion opportunities from divergent compliance cost structures.
For Market Incumbents: Extend backward integration into North Atlantic fishing fleets to secure anchovy supply volumes against South China Sea quota volatility. Invest in captive starter culture production capabilities to reduce dependency on biotechnology cluster concentration. Kerry Group plc and TripleNine Group A/S demonstrate how captive flavor extraction and fleet ownership respectively defend margin position against input cost swings. For New Entrants and Emerging Players: Begin with FSSAI-compliant packaged fish sauce for Indian organized retail channels previously confined to unbranded wet markets. Target Cambodian and Laotian cooperative testing pools as white-space infrastructure for shared EFSA laboratory accreditation. Deploy direct-import e-commerce platforms to capture diaspora consumer segments in California and Greater London metropolitan zones. For Investors and Strategic Acquirers: Nutraceutical ingredient houses are the most active acquirer in this space, seeking fermentation parameter licensing to guarantee peptide bioactivity specifications. Viability over the five-to-ten year horizon rests on starter culture adoption rates compressing traditional cycle variability. Monitor EFSA histamine threshold enforcement consistency as the inflection signal for export-market access conditions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fishing Fleet | TripleNine Group A/S secures anchovy supply volumes against quota-driven price volatility. |
| Starter Culture Technology Licensing | FMC Corporation monetizes fermentation-derived bioactive compound expertise for nutraceutical channels. |
| Cooperative Testing Pool Formation | Cambodian artisan producers share EFSA-mandated histamine laboratory accreditation costs. |
| Direct-to-Consumer E-commerce Launch | Diaspora procurement platforms in California bypass ethnic grocery intermediary margins. |
| FSSAI Compliance Investment | Multinational suppliers reformulate for Indian organized retail placement beyond wet markets. |
Research Methodology
Coverage spans Southeast Asia, South Asia, North America, and Europe, with primary inputs from each region. Fermentation science program directors, Mekong Delta plant managers, FSSAI regulatory affairs leads, and nutraceutical peptide isolation specialists contributed stakeholder perspectives. Secondary validation drew from FDA seafood HACCP guidance documents, EFSA biogenic amine threshold advisories, BIS and FSSAI labeling standards, and Codex Alimentarius fermented fish product guidelines. Bottom-up processor capacity aggregation and top-down condiment market sizing were triangulated.
Rate-of-change decomposition across volume and value dimensions structured the analytical framework over the projection horizon. Segmentation modeling addressed product format, fermentation technology sophistication, application specification, and end-user buyer type. CAGRs were derived from processor retrofit investment cycles, starter culture adoption trajectories, and regulatory harmonization timelines. Peptide bioactivity quantification methods and histamine detection protocol reliability served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including spontaneous natural fermentation batch outcomes and climate-driven anchovy migration pattern shifts. Forecasts reflect assumptions about EFSA enforcement consistency and FSSAI reform implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Protein Concentrate Market
Seafood
Smoked Salmon Market
Seafood
Milkfish Market
Seafood
Herring Market
Seafood
Toothfish Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Striped Bass Market
Seafood
North America Seafood Market
Seafood
Global Shrimp Market
Seafood
Asia-Pacific Seafood Market
Seafood
US Crustacean Market
Seafood
Salmon Market
Seafood
Carp Market
Seafood
Shellfish Extract Market
Seafood
Seafood Processing Market
Seafood
Fried Dace with Salted Black Beans Market