
 Alternative Solar Photovoltaic Technologies Market | 2026-2036
Alternative Solar Photovoltaic Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Solar Photovoltaic Technologies Market Analysis
A shift from outsourced cell sourcing to captive thin-film production is repositioning supply strategies across the sector. First Solar leverages vertical integration in cadmium telluride manufacturing to control feedstock costs. Oxford PV sustains its lead in perovskite-silicon tandem cell development through dedicated R&D facilities. LONGi Solar anchors crystalline silicon scale while exploring heterojunction upgrades to defend its manufacturing position.
Alternative solar photovoltaic technologies encompass non-conventional cell architectures including thin-film semiconductors, perovskite layers, and multi-junction tandem stacks that convert sunlight through bandgap-engineered absorption profiles exceeding single-junction Shockley-Queisser limits. These systems serve commercial and utility-scale deployments where levelized cost of electricity and module efficiency determine project returns. Thin-film segments dominate utility-scale installation pipelines due to lower temperature coefficients and flexible substrate compatibility. Perovskite and tandem technology categories represent the fastest-expanding margin pools as manufacturers resolve stability and encapsulation barriers for 25-year warranted performance. Bifacial applications capture structural growth in ground-mounted arrays where albedo reflection boosts effective yield across desert and snow-prone geographies.
The EU F-Gas Regulation and REACH frameworks restrict fluorinated greenhouse gas use in photovoltaic manufacturing, compelling module suppliers to certify alternative encapsulant chemistries. The EPA oversees end-of-life cadmium recovery protocols for thin-film installations in the United States, while China's MEE enforces dual carbon compliance thresholds for polysilicon and wafer production facilities. Stakeholders must track evolving certification timelines for perovskite commercialization as regulators balance innovation incentives against long-term degradation risk assessments.
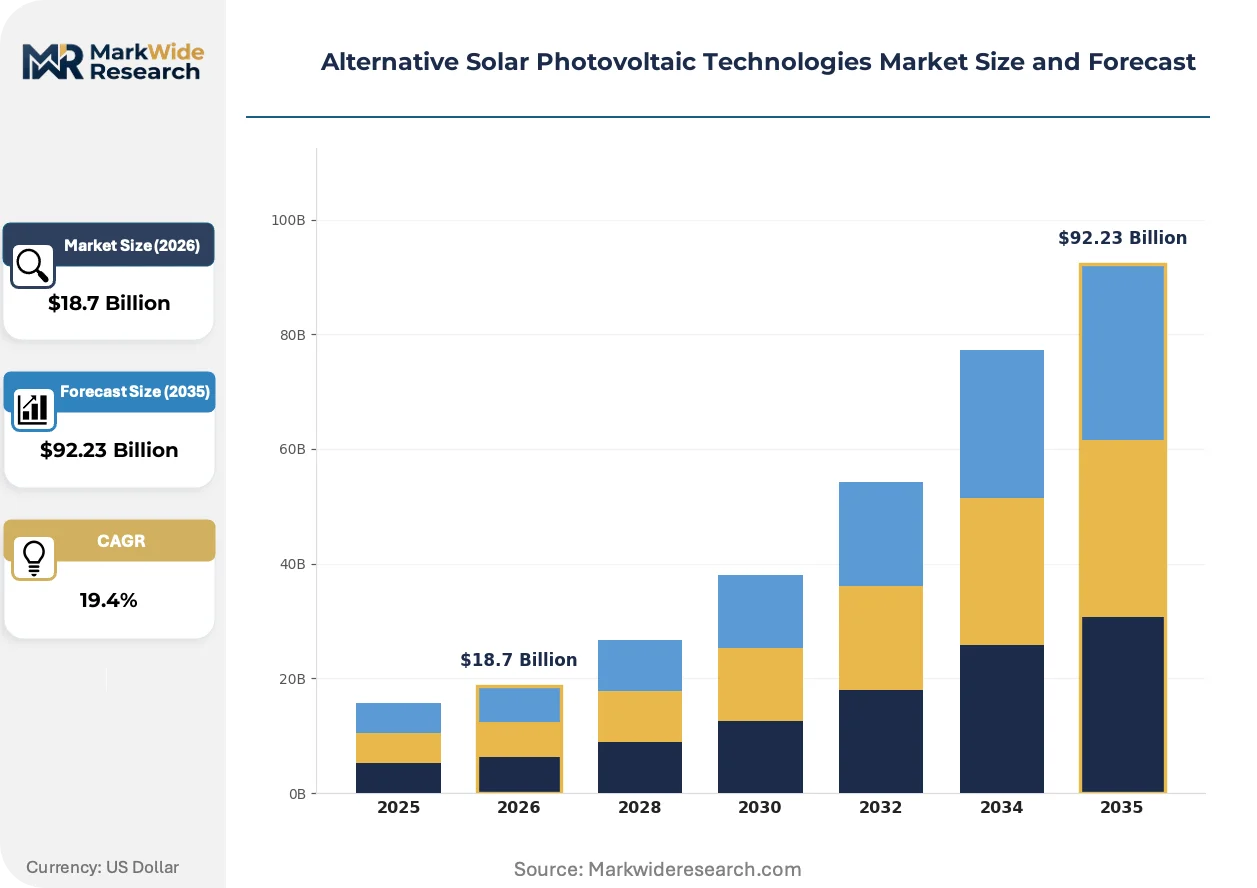
Market Dynamics
Perovskite-silicon tandem cell commercialization is compressing technology lifecycles and forcing crystalline silicon incumbents to accelerate heterojunction and TOPCon migration roadmaps before efficiency premiums erode.
Growth Catalysts
- EU F-Gas Regulation:The regulation's tightening embodied-carbon thresholds for imported modules are compelling European project developers to source thin-film and next-generation architectures that avoid fluorinated greenhouse gas-intensive manufacturing processes.
- Utility-scale power purchasers:Large-scale offtakers in Germany, China, and the United States are scaling procurement of perovskite and tandem architectures to secure levelized cost advantages in competitive auction regimes.
- Bifacial ground-mounted arrays:Desert and snow-prone geographies are capturing structural yield boosts from albedo reflection, driving module specification shifts toward double-glass and frameless designs.
Market Restraints
- Indium and tellurium supply concentration:Critical thin-film feedstock sourcing concentrates in Chinese refining operations, exposing cadmium telluride and copper indium gallium selenide manufacturers to geopolitical disruption and price volatility.
- Perovskite stability barriers:Moisture-induced degradation and ion migration remain unresolved at module scale, limiting bankability and warranty terms below the 25-year threshold required by institutional project finance.
- REACH encapsulant certification:Alternative chemistries replacing fluorinated compounds face extended ECHA registration timelines, delaying commercial rollout of compliant module designs for European deployment.
Strategic Opportunities
- Building-integrated photovoltaics:Flexible thin-film substrates and semi-transparent perovskite layers are penetrating commercial façade and skylight applications where conventional crystalline silicon cannot conform to architectural specifications.
- India's PLI scheme:Production-linked incentive allocations for advanced cell and module manufacturing are attracting capital toward heterojunction and tandem production facilities serving domestic and export markets.
- Agrivoltaic convergence:Lightweight, bifacial thin-film systems are unifying electricity generation with agricultural productivity in water-stressed regions, opening dual-revenue stream models for project developers.
Industry Challenges
- Perovskite process engineering talent:Scarcity of specialists in slot-die coating, vapor deposition, and encapsulation chemistry is constraining manufacturing scale-up at pilot-to-commercial transitions.
- Dual carbon compliance verification:China's MEE enforcement of embodied-carbon thresholds for polysilicon and wafer facilities requires costly third-party auditing and real-time emissions monitoring infrastructure.
- Tandem cell certification timelines:IEC standards development for perovskite-silicon architectures lags laboratory performance demonstrations, creating regulatory uncertainty for product launch scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Solar Photovoltaic Technologies Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Thin-Film, Crystalline Silicon, Bifacial, Concentrated Photovoltaics Application: Residential, Commercial, Utility-scale, Off-grid Installation Type: Roof-mounted, Ground-mounted, Building-integrated, Portable End User: Homeowners, Businesses, Government, NGOs |
| Companies Covered | Saule Technologies, IntriEnergy, First Solar, Icarus RT, Mirai Solar, Oxford PV, Energy Materials Corporation, LONGi Solar, Tandem PV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Solar Photovoltaic Technologies Market Emerging Trajectories
Tandem cell architectures and manufacturing process digitization are compressing efficiency improvement cycles while regulatory pressure on embodied carbon is restructuring module sourcing geography.
Perovskite-silicon tandem stacks are unifying the high-efficiency potential of multi-junction absorption with the manufacturing scalability of silicon substrates. European and North American utility-scale developers are specifying these architectures in next-generation procurement frameworks despite premium pricing. This unifying technology is compressing the competitive window for single-junction crystalline silicon incumbents and accelerating R&D facility investments.
REACH and the EU F-Gas Regulation are restricting fluorinated greenhouse gas deployment in photovoltaic encapsulant and cleaning processes. Module suppliers must certify alternative chemistries through ECHA registration pathways, extending product development timelines. Thin-film and perovskite categories face the most acute compliance pressure as they displace conventional fluoropolymer backsheet materials.
Long-term power purchase agreements with technology-agnostic efficiency clauses are displacing module-specified procurement in utility-scale solar. Project developers in Germany and the southwestern United States are negotiating output-guaranteed contracts that transfer technology risk to EPC and O&M providers. This restructuring concentrates due diligence burden on independent engineering firms and compresses module manufacturer brand premiums.
Alternative Solar Photovoltaic Technologies Market Segmentation
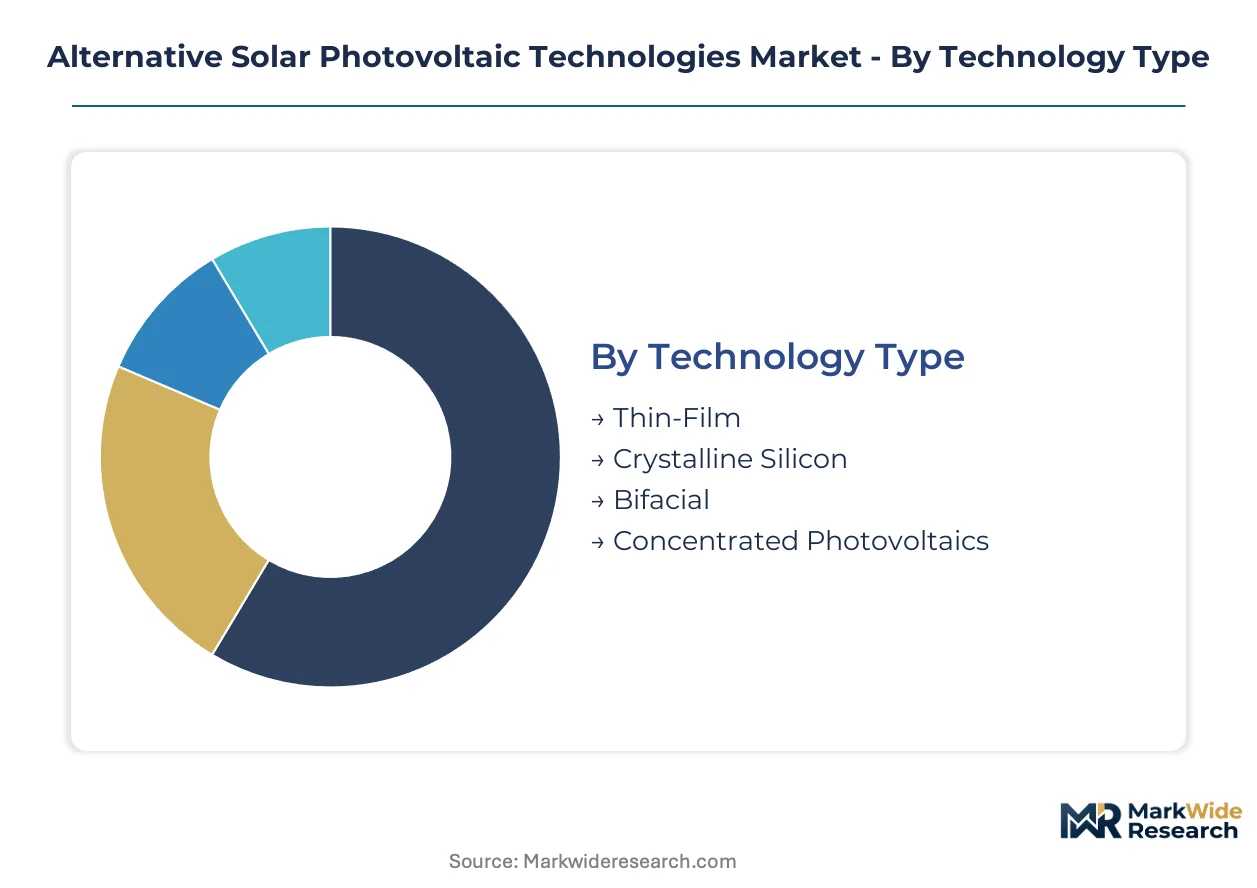
Technology architecture determines capital deployment patterns across the alternative solar photovoltaic sector. Module efficiency thresholds and manufacturing scale requirements create divergent investment profiles that reshape competitive positioning among cell suppliers and project developers.
Technology Type:
Capital intensity varies sharply across cell architectures, with multi-junction stacks and tandem configurations demanding the highest upfront equipment investment.
- Thin-Film:Cadmium telluride and copper indium gallium selenide layers deposit onto flexible glass or polymer substrates through vapor deposition processes. Utility-scale developers in the southwestern United States specify these modules for desert installations where temperature coefficients below 0.3% per degree Celsius preserve summer output.
- Crystalline Silicon:Passivated emitter and rear contact cells plus heterojunction architectures dominate current manufacturing capacity. Chinese wafer producers anchor global supply chains through polysilicon refining integration that compresses feedstock costs.
- Bifacial:Double-glass encapsulation captures direct and reflected irradiance across ground-mounted arrays. Albedo-dependent yield gains of 5-20% attract project finance in snow-prone geographies and high-reflectivity desert surfaces.
- Concentrated Photovoltaics:Multi-junction III-V semiconductors paired with tracking optics target direct normal irradiance above 2000 kWh per square meter annually. Niche deployment concentrates in Middle Eastern utility-scale installations where land availability supports large aperture collectors.
Most installed capacity flows through Crystalline Silicon. Expansion is steepest in Bifacial configurations as double-glass cost premiums compress against single-sided alternatives.
Application:
Project scale determines procurement complexity and technology specification flexibility.
- Residential:Rooftop constraints favor high-efficiency monocrystalline modules below 400 watts to maximize generation per square meter. Net metering policy stability in Germany and Australia drives homeowner adoption of premium-tier products with 25-year performance warranties.
- Commercial:Flat-roof and carport installations balance capital efficiency against demand charge reduction. Power purchase agreement structures in the United States transfer technology risk to third-party owners while businesses secure predictable electricity rates.
- Utility-scale:Competitive auction regimes in India and Brazil prioritize levelized cost of electricity above module brand premiums. Thin-film and bifacial specifications capture procurement share where bifaciality gains offset higher upfront capital.
- Off-grid:Remote industrial sites and rural electrification projects deploy hybrid solar-storage systems. Diesel displacement economics in sub-Saharan Africa and Southeast Asian island communities drive demand for durable modules with minimal degradation.
Utility-scale procurement absorbs the greatest absolute module volume. Off-grid applications are gaining share fastest as storage cost declines unlock rural electrification business models.
Installation Type:
Mounting configuration constrains module form factor and structural loading requirements.
- Roof-mounted:Railed and rail-less attachment systems secure modules to residential and commercial structures. Fire classification and wind uplift certification dominate specification criteria in California and Florida building codes.
- Ground-mounted:Single-axis and dual-axis trackers optimize yield across utility-scale sites. Steel pile foundations and geotechnical assessment costs add 15-25% to balance-of-system expenditure versus fixed-tilt alternatives.
- Building-integrated:Semi-transparent and colored photovoltaic glass replaces conventional façade and skylight materials. European commercial construction mandates under the Energy Performance of Buildings Directive accelerate BIPV specification in Germany and the Netherlands.
- Portable:Foldable and rollable thin-film modules serve military, disaster relief, and recreational applications. Watt-per-kilogram metrics above 200 watts per kilogram distinguish premium products from rigid glass alternatives.
Ground-mounted systems carry the largest cumulative installation base. Building-integrated configurations are expanding most quickly as architectural specification tightens energy efficiency requirements.
End User:
Decision-making authority and risk tolerance diverge across customer categories.
- Homeowners:Distributed generation investment decisions respond to net metering compensation rates and property value considerations. Residential solar tax credits in the United States structure payback period calculations around federal incentive schedules.
- Businesses:Corporate renewable energy procurement targets under Science Based Targets initiative commitments drive direct PPA negotiation. On-site generation versus virtual off-take structures balance physical asset control against portfolio diversification.
- Government:Public sector tenders emphasize domestic content requirements and job creation metrics. India's KUSUM scheme and the European Union's REPowerEU procurement frameworks prioritize local manufacturing capacity.
- NGOs:Development finance institution partnerships structure rural electrification deployment. Pay-as-you-go financing models in East Africa reduce upfront capital barriers for low-income households.
Businesses command the largest procurement value. Government tenders are climbing fastest as sovereign clean energy commitments translate into auction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing geography as producers relocate to jurisdictions with lower embodied-carbon compliance costs. The EU F-Gas Regulation and China's dual carbon mandates are creating divergent cost structures that favor domestic sourcing over import-dependent procurement strategies.
Germany
Utility-scale auction volumes under the EEG framework are accelerating procurement of perovskite and tandem architectures. The EU Green Deal's embodied-carbon thresholds compel project developers to source thin-film modules from certified low-carbon production pathways. Saxony-Anhalt and Brandenburg host emerging manufacturing clusters where pilot-scale perovskite facilities are scaling toward commercial output.
China
The MEE enforces dual carbon compliance thresholds for polysilicon and wafer production, raising operating costs for conventional crystalline silicon manufacturers. Provincial governments in Jiangsu and Zhejiang are channeling subsidies toward heterojunction and tandem cell capacity expansions. The Yangtze River Delta concentrates thin-film feedstock refining operations that supply cadmium telluride and copper indium gallium selenide manufacturers globally.
United States
The Inflation Reduction Act's domestic content bonuses are restructuring procurement patterns for utility-scale developers. The EPA oversees end-of-life cadmium recovery protocols that constrain thin-film deployment logistics in southwestern desert installations. Ohio and Arizona host vertically integrated manufacturing campuses where captive tellurium sourcing insulates production from geopolitical disruption.
India
Production-linked incentive allocations under the PLI scheme are attracting capital toward advanced cell and module manufacturing for heterojunction and tandem production. The Central Electricity Authority mandates domestic content requirements in public sector tenders that favor emerging thin-film and bifacial specifications. Gujarat and Tamil Nadu are developing manufacturing corridors where land and power cost advantages support export-oriented production.
Japan
METI procurement guidelines prioritize high-efficiency modules for rooftop applications where space constraints favor premium-tier technologies. National research consortia are accelerating perovskite stability testing protocols to compress commercialization timelines. The Kansai region maintains specialized coating equipment supply chains that serve slot-die and vapor deposition process development.
Alternative Solar Photovoltaic Technologies Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue tandem and perovskite commercialization pathways. The market structures around three player categories: vertically integrated thin-film specialists with captive feedstock control, crystalline silicon incumbents migrating toward heterojunction architectures, and venture-backed perovskite developers resolving stability barriers. Dominant competitive moves include backward integration into critical mineral refining and strategic partnerships with utility-scale EPC firms to secure offtake commitments.
Among thin-film specialists with upstream control, First Solar exemplifies the vertically integrated archetype through cadmium telluride manufacturing. Oxford PV and LONGi Solar occupy distinct positioning vectors within the tandem cell development landscape, with the former representing European perovskite-silicon integration efforts and the latter anchoring crystalline silicon scale while exploring heterojunction upgrades. These three entities collectively illustrate the competitive tension between incumbent scale advantages and emerging technology premiums.
| Leading Market Players |
|---|
| Saule Technologies |
| IntriEnergy |
| First Solar |
| Icarus RT |
| Mirai Solar |
| Oxford PV |
| Energy Materials Corporation |
| LONGi Solar |
| Tandem PV |
| Others |
Supply Flow & Price Mechanics
Perovskite-silicon tandem cell commercialization is compressing cost economics while concentrating supply control among vertically integrated thin-film specialists. The EU F-Gas Regulation and China's dual carbon mandates are forcing module suppliers to absorb compliance premiums or relocate production, restructuring geographic pricing differentials across the value chain.
Pricing Analysis
Distributor margins on utility-scale module procurement compress against direct-to-EPC volume discounts for multi-hundred-megawatt offtakes. Three-tier pricing structure across premium, standard, and economy levels stratifies by efficiency certification and bankability tier, with IEC 61215-certified bifacial modules commanding sustained premiums over uncertified alternatives. Pricing pressure stems from crystalline silicon incumbents accelerating heterojunction migration to defend share against tandem entrants. Utility-scale developers exhibit highest price sensitivity, while residential rooftop segments absorb efficiency premiums for space-constrained installations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese tellurium and indium refining operations that feed cadmium telluride and copper indium gallium selenide manufacturers globally. Raw material dependencies center on high-purity tellurium, indium metal, and methylammonium lead halide precursors for perovskite deposition. Tariff exposure on Chinese-origin cells and wafers is intensifying as the United States enforces domestic content bonuses under the Inflation Reduction Act. Distribution runs through vertically integrated thin-film producers with captive feedstock control, bypassing merchant wafer markets entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
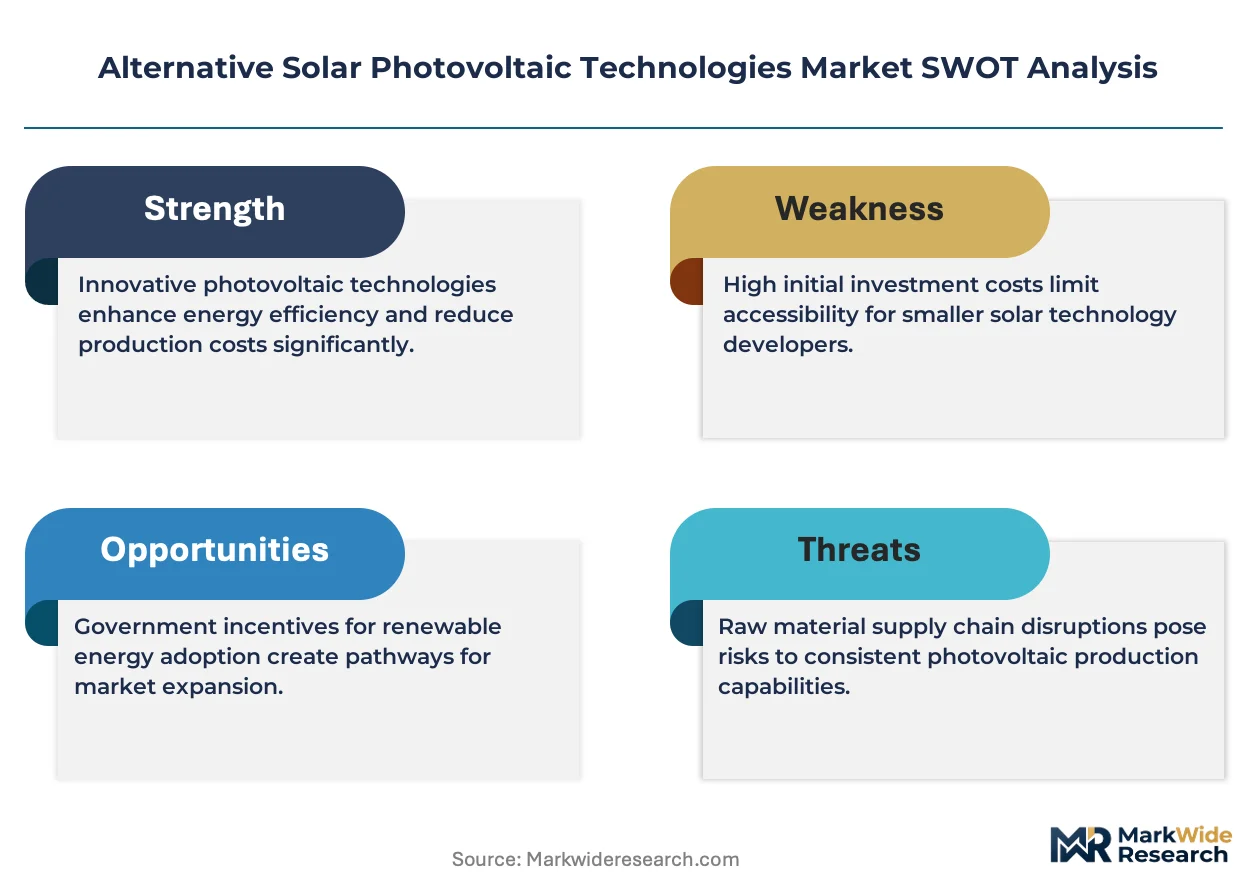
The alternative solar photovoltaic sector functions as a regulatory compounder where the EU Green Deal's embodied-carbon thresholds are accelerating procurement shifts toward certified low-carbon production pathways.
For Market Incumbents: Extend heterojunction and TOPCon capacity additions in Jiangsu and Zhejiang to defend manufacturing scale against perovskite-silicon tandem entrants before efficiency premiums erode. Deepen backward integration into polysilicon refining to compress feedstock costs under China's MEE dual carbon compliance thresholds. Prioritize IEC 61215 certification investments for bifacial module lines to sustain bankability premiums in European utility-scale auctions. For New Entrants and Emerging Players: Capture white-space in building-integrated photovoltaics where semi-transparent perovskite layers penetrate commercial façade applications that crystalline silicon cannot serve. Target India's PLI scheme allocations for heterojunction and tandem manufacturing facilities serving export markets to Southeast Asia and the Middle East. Lead with agrivoltaic convergence pitches to water-stressed region developers seeking dual-revenue stream models. For Investors and Strategic Acquirers: Valuations sit cheapest among thin-film specialists with captive tellurium sourcing and established utility-scale EPC partnerships. Long-term viability across the analysis window hinges on resolving perovskite stability barriers to secure 25-year warranted performance and institutional project finance eligibility. Watch IEC standards development timelines for perovskite-silicon architectures as the critical inflection signal for commercial bankability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Critical Minerals | Captive tellurium and indium refining insulates First Solar from Chinese supply disruption and price volatility. |
| Perovskite Stability Certification Program | Oxford PV's dedicated R&D facilities accelerate IEC standards alignment for 25-year warranted performance. |
| Domestic Content Manufacturing Scale-Up | Ohio and Arizona campuses qualify for Inflation Reduction Act bonuses while satisfying EPA end-of-life recovery protocols. |
| Heterojunction Capacity Expansion | LONGi Solar's Jiangsu facilities defend crystalline silicon scale against tandem cell efficiency compression. |
| Agrivoltaic Project Development Partnership | Lightweight bifacial thin-film systems unlock dual-revenue streams in water-stressed geographies under emerging EPC alliances. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility-scale EPC contractors, thin-film manufacturing plant managers, project finance officers at development banks, and regulatory affairs leads at module suppliers with secondary validation against EIA generation data, IEA technology roadmaps, FERC interconnection filings, and EU ECHA registration databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic scenario analysis.
Historical reference periods spanning crystalline silicon cost curves, thin-film deployment cycles, and perovskite laboratory efficiency trajectories anchored the projection horizon across technology architecture, application scale, installation type, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion constraints, incorporating polysilicon price volatility, embodied-carbon compliance cost trajectories, and auction regime pricing dynamics as industry-specific forecast inputs.
Perovskite stability breakthrough failures, indium supply disruption from Chinese refining concentration, and REACH encapsulant certification delays are the dominant revision risks that could compress or extend commercialization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Spain Solar Energy Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Half-Cell Solar Module Market