
 Rapid Test Cards Market | 2026-2036
Rapid Test Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Test Cards Market Analytics
Aftermarket service revenue for calibration and reader-device maintenance is rewriting margin allocation across the rapid diagnostics value chain. Abbott Laboratories leverages its installed base of digital readers to sustain recurring consumable pull-through. bioMérieux SA anchors its competitive stance in European reference laboratories through specialized multiplex card production. Siemens Healthineers dominates hospital procurement channels with integrated platform-to-card bundling strategies.
Rapid test cards are single-use diagnostic cartridges, typically constructed from nitrocellulose membranes bonded to plastic housings, that deliver qualitative or semi-quantitative results within minutes through capillary-driven reagent migration. Lateral flow assay technology occupies the highest production volume tier due to its low cost and minimal equipment requirements, though microfluidics formats are gaining traction in settings demanding higher analytical sensitivity. Antigen test cards lead infectious disease applications, while multi-detection test cards command premium positioning in emergency department triage workflows. Home care channels represent the fastest-growing end-user segment as self-testing protocols expand beyond pregnancy and glucose monitoring.
The FDA regulates rapid test cards as Class II or III medical devices depending on intended use and analyte complexity, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for self-testing variants. WHO prequalification standards shape procurement eligibility for products targeting low-resource health systems. Stakeholders must monitor evolving harmonization between national emergency-use pathways and permanent marketing authorization frameworks.
Market Dynamics
Decentralized diagnostic infrastructure is restructuring procurement authority away from centralized hospital laboratories toward point-of-care networks and retail pharmacy chains, compressing traditional distribution hierarchies and forcing manufacturers to reconfigure service architectures around lower-volume, higher-velocity fulfillment patterns.
Growth Catalysts
- India's PLI scheme for medical devices:Production-linked incentives are accelerating domestic manufacturing capacity for lateral flow formats, reducing import dependency for government health programs targeting rural screening expansion.
- Capillary-driven microfluidics:Advances in passive pumping mechanisms are enabling multiplex detection capabilities without active instrumentation, opening emergency department triage applications previously reserved for laboratory analyzers.
- Over-the-counter regulatory pathways:The FDA's evolving framework for self-testing devices is shortening time-to-market for home-use infectious disease panels, expanding addressable consumer segments beyond pregnancy and glucose monitoring.
Market Restraints
- Nitrocellulose membrane supply concentration:Three specialized chemical manufacturers control the majority of high-purity membrane substrate production, creating vulnerability to input cost volatility and allocation constraints during demand surges.
- WHO prequalification complexity:Stringent stability testing and lot-release documentation requirements for low-resource health system eligibility create multi-year certification timelines that freeze out smaller manufacturers.
- Laboratory analyzer substitution:Compact benchtop immunoassay systems with quantitative readout capabilities are capturing hospital laboratory volume that might otherwise migrate to rapid card formats.
Strategic Opportunities
- Sub-Saharan African public procurement:National malaria and HIV elimination programs are consolidating demand into multi-year tenders for high-volume rapid diagnostic contracts, rewarding suppliers with established cold-chain logistics networks.
- Pharmacy chain direct distribution:Bypassing traditional medical distributor layers to fulfill retail shelf-stock requirements for self-test categories is capturing margin previously allocated to intermediary wholesalers.
- EU MDR self-testing variant pathways:Stricter clinical evidence requirements for home-use devices under the Medical Device Regulation are creating competitive moats for manufacturers with established notified body relationships and post-market surveillance infrastructure.
Industry Challenges
- Multiplex assay development expertise:Shortage of biochemists with experience in competitive and sandwich immunoassay optimization on shared membrane substrates is extending product development cycles and inflating R&D compensation costs.
- Legacy reader system integration:Hospital procurement committees are demanding backward compatibility with existing digital reader installations, forcing manufacturers to maintain multiple firmware branches and complicating hardware refresh strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Test Cards Market |
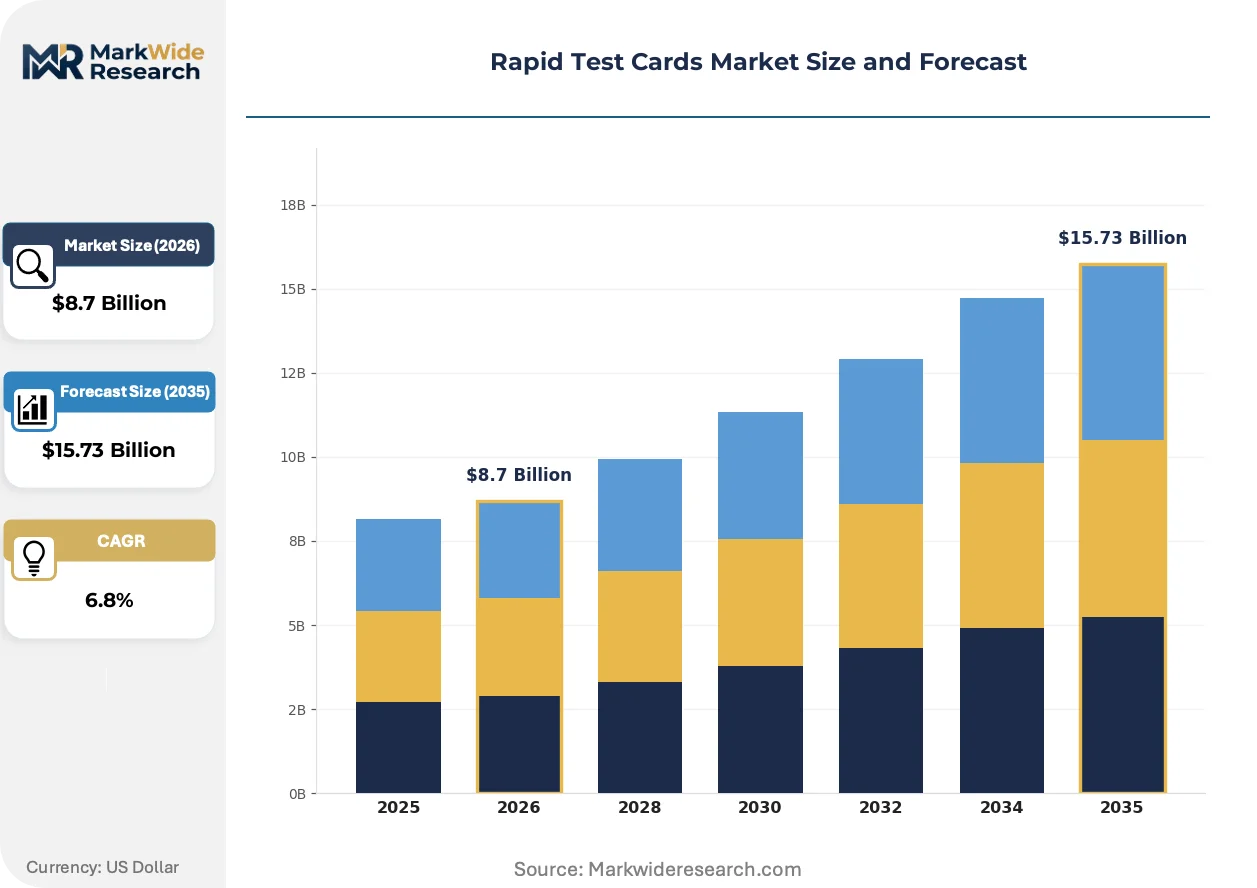
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Test Cards, Antibody Test Cards, Nucleic Acid Test Cards, Multi-Detection Test Cards Technology: Lateral Flow Assay, Microfluidics, Enzyme-Linked Immunosorbent Assay, Digital Immunoassay End User: Hospitals, Laboratories, Home Care, Point-of-Care Facilities Application: Infectious Disease Testing, Pregnancy Testing, Drug Screening, Cardiovascular Testing |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., bioMérieux SA, Becton, Dickinson and Company, Thermo Fisher Scientific, Inc., Danaher Corporation, Siemens Healthineers, Quidel Corporation, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Test Cards Market Evolving Landscape
Convergence between passive fluidics and active signal amplification is redefining performance thresholds for instrument-free diagnostics, while regulatory harmonization efforts are compressing the gap between emergency-use and permanent authorization pathways.
Quantum dot nanocrystal reporters are hybridizing with conventional gold nanoparticle lateral flow architectures to deliver tenfold sensitivity improvements for low-abundance analyte detection. Reference laboratories in European health systems are piloting these formats for sepsis biomarker screening where analytical performance requirements previously mandated centralized laboratory processing. The technology is hybridizing competitive positioning between rapid test manufacturers and traditional immunoassay platform vendors, forcing concessions on reader-device bundling terms.
The EU Medical Device Regulation's clinical evidence requirements for self-testing variants are elevating documentation burdens specifically for pregnancy and fertility rapid tests previously cleared under lighter notified body scrutiny. Manufacturers are responding by consolidating variant development pipelines to amortize clinical study costs across multiple analyte configurations. Home-use infectious disease panels targeting influenza and respiratory syncytial virus are experiencing the most pronounced timeline compression as notified bodies apply consistent evidentiary standards across self-testing categories.
Pharmacy chains are consolidating shelf-space authority for self-test categories into centralized category management functions, displacing the fragmented store-level purchasing that historically characterized retail diagnostic distribution. This concentration is forcing manufacturers to negotiate annual volume commitments and promotional calendar coordination rather than transactional reorder fulfillment. The United Kingdom's Boots and Superdrug networks exemplify this pattern, with category managers now controlling access to over-the-counter placement for pregnancy, ovulation, and infectious disease self-tests.
Rapid Test Cards Market Segmentation
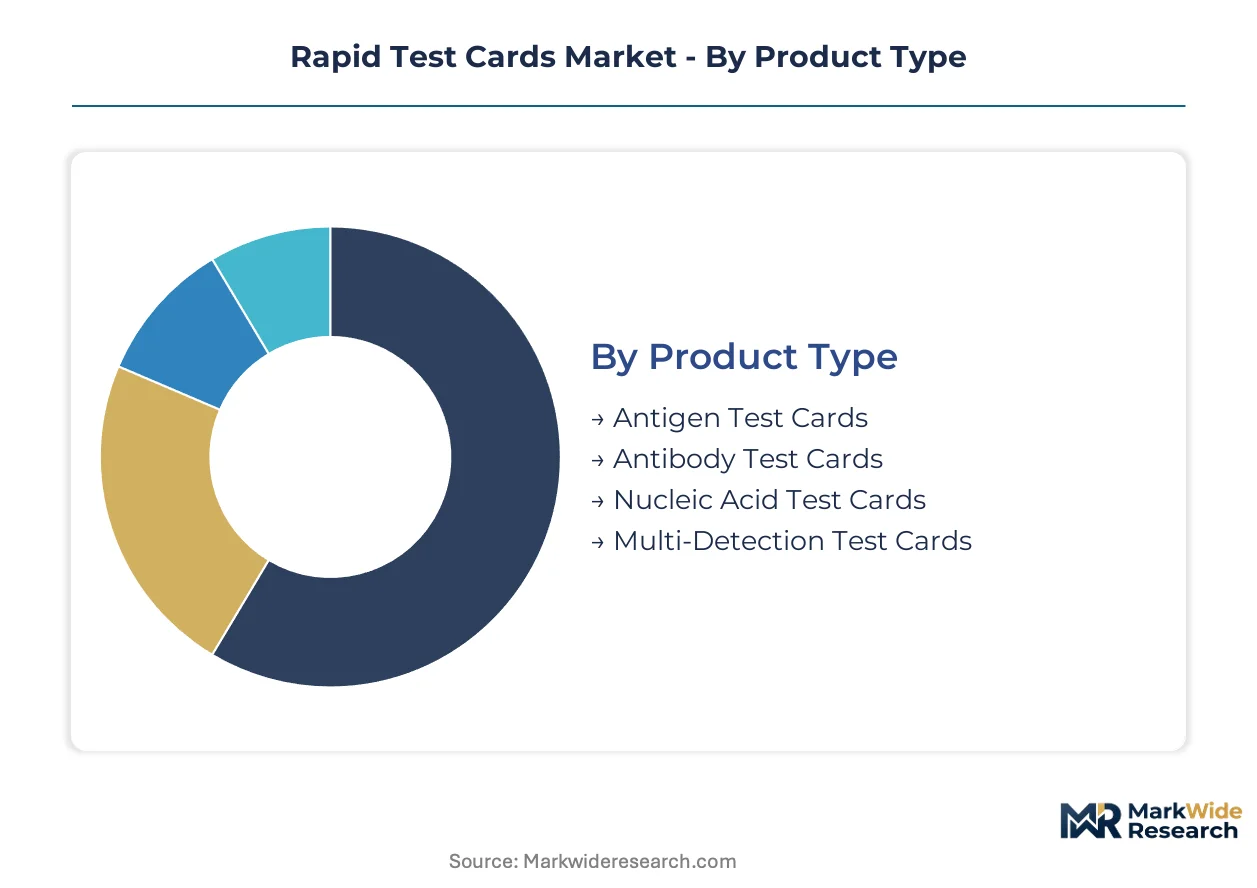
Segmentation in rapid test cards determines procurement pathways, margin structures, and regulatory compliance burdens. Product format dictates manufacturing scale and substrate sourcing requirements. Technology choice separates instrument-dependent from instrument-free deployment scenarios.
Product Type:
Use-case spectrum spans infectious disease screening at population scale to specialized cardiac biomarker detection in emergency settings.
- Antigen Test Cards:Nitrocellulose membrane cartridges detecting viral surface proteins through antibody-antigen binding. Demand concentrates in India's government health schemes targeting decentralized rural screening infrastructure, constrained by nitrocellulose membrane supply concentration among three specialized chemical manufacturers.
- Multi-Detection Test Cards:Multiplex configurations enabling simultaneous analyte identification on shared substrates. Emergency department triage workflows in European reference laboratories drive premium positioning, supported by capillary-driven microfluidics advances eliminating active instrumentation requirements.
- Antibody Test Cards:Serological formats detecting host immune response markers. Blood bank screening protocols and occupational health programs sustain procurement volumes.
- Nucleic Acid Test Cards:Isothermal amplification cartridges for RNA/DNA target detection. Field epidemiology deployments and outbreak response stockpiling shape intermittent demand patterns.
Established volume favors Antigen Test Cards; emerging adoption favors Multi-Detection Test Cards.
Technology:
Cost tier separation runs from passive capillary systems to instrument-integrated quantitative platforms.
- Lateral Flow Assay:Capillary-driven reagent migration through nitrocellulose membranes bonded to plastic housings. India's PLI scheme for medical devices accelerates domestic manufacturing capacity expansion for this format, reducing import dependency for government health programs.
- Microfluidics:Precision-molded channels enabling controlled fluid manipulation without external pumps. Emergency department triage applications previously reserved for laboratory analyzers are opening as passive pumping mechanisms advance multiplex capabilities.
- Enzyme-Linked Immunosorbent Assay:Colorimetric detection requiring plate readers or spectrophotometers. Centralized laboratory workflows with quantitative readout requirements sustain this segment.
- Digital Immunoassay:Reader-dependent systems with fluorescence or electrochemical signal transduction. Hospital procurement committees demanding backward compatibility with existing installations complicate hardware refresh strategies.
Manufacturers with installed digital reader bases capture recurring consumable pull-through; passive formats penetrate lowest-resource settings.
End User:
Customer type determines distribution architecture, with centralized laboratory procurement diverging sharply from retail pharmacy fulfillment patterns.
- Home Care:Self-testing protocols expanding beyond pregnancy and glucose monitoring into infectious disease panels. FDA's evolving over-the-counter regulatory pathways shorten time-to-market for home-use applications.
- Hospitals:Integrated platform-to-card bundling dominates procurement, with Siemens Healthineers leveraging channel control. Laboratory analyzer substitution threats from compact benchtop immunoassay systems constrain rapid card volume capture.
- Point-of-Care Facilities:Rural health networks expanding procurement of rapid diagnostic formats. India's government health schemes prioritize decentralized screening infrastructure in this channel.
- Laboratories:Reference facilities requiring quantitative readout capabilities and lot-release documentation. WHO prequalification standards shape procurement eligibility for products targeting low-resource health systems.
Pharmacy chain category management consolidation favors Home Care; traditional distributor relationships favor Hospitals.
Application:
Maturity gradient separates decades-established pregnancy testing from emerging cardiovascular biomarker formats.
- Infectious Disease Testing:Antigen and antibody formats for respiratory, sexually transmitted, and vector-borne pathogens. Sub-Saharan African public procurement for malaria and HIV elimination programs consolidates demand into multi-year tenders rewarding established cold-chain logistics networks.
- Pregnancy Testing:hCG detection cards with decades of consumer familiarity. EU MDR clinical evidence requirements elevate documentation burdens specifically for this category previously cleared under lighter notified body scrutiny.
- Drug Screening:Workplace and forensic applications for metabolite detection. Employment screening mandates and rehabilitation program monitoring sustain institutional demand.
- Cardiovascular Testing:Troponin and natriuretic peptide detection for acute coronary syndrome and heart failure assessment. Emergency department triage workflows drive adoption as sensitivity thresholds improve.
Volume concentration remains with Infectious Disease Testing; steepest expansion trajectory belongs to Cardiovascular Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys rapid test cards primarily for decentralized rural screening infrastructure, while the United States channels volume through pharmacy retail and home-use self-testing protocols, and Germany concentrates procurement within reference laboratory networks requiring higher analytical sensitivity.
United States
FDA's evolving over-the-counter diagnostic pathways shorten time-to-market for home-use infectious disease panels. Pharmacy chain category management consolidates shelf-space authority for self-test products. The Boston-Cambridge corridor anchors digital immunoassay reader development clusters.
Germany
EU Medical Device Regulation imposes stricter clinical evidence requirements for self-testing variants. Reference laboratories in Bavaria and Baden-Württemberg pilot quantum dot nanocrystal reporter formats for sepsis biomarker screening. Siemens Healthineers leverages integrated platform-to-card bundling across hospital procurement channels.
India
Production-linked incentives under the PLI scheme for medical devices accelerate domestic manufacturing capacity for lateral flow formats. Government health schemes prioritize decentralized screening infrastructure in rural health networks. Gujarat and Maharashtra host expanding nitrocellulose membrane substrate fabrication facilities.
United Kingdom
Boots and Superdrug pharmacy networks consolidate category management functions for over-the-counter diagnostic placement. MHRA alignment with EU MDR clinical evidence standards elevates documentation burdens for pregnancy and fertility rapid tests. The Oxford-Cambridge arc supports microfluidics research commercialization.
Brazil
ANVISA regulatory frameworks shape import authorization timelines for rapid diagnostic devices targeting public health programs. Sub-Saharan African procurement spillover benefits established Brazilian distributors with cold-chain logistics networks. São Paulo state concentrates medical device import and distribution infrastructure.
Rapid Test Cards Market Competitive Landscape
Capability concentration sits with specialized multiplex assay developers; scale advantage sits with diversified diagnostics conglomerates. The market structures around three tiers: installed-base platform vendors capturing recurring consumable pull-through, reference laboratory specialists commanding premium positioning, and regional fabricators serving government tender programs. Dominant competitive moves include backward integration into nitrocellulose membrane substrate production and pharmacy chain direct distribution partnerships bypassing traditional wholesale layers.
Among diversified diagnostics conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions defined by installed digital reader bases and hospital procurement channel control. bioMérieux SA exemplifies the reference laboratory specialist archetype, anchoring competitive stance through European notified body relationships and post-market surveillance infrastructure. These three entities represent distinct strategic postures: platform-driven recurring revenue, bundled system-to-consumable integration, and regulatory-complexity specialization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| bioMérieux SA |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific, Inc. |
| Danaher Corporation |
| Siemens Healthineers |
| Quidel Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Value Network & Pricing Analysis
The Nhava Sheva-Mundra freight corridor from India to East Africa carries nitrocellulose membrane substrates and finished rapid test cards, with freight cost volatility amplifying margin compression for manufacturers dependent on three specialized chemical suppliers while enabling price differentiation between government tender volumes and retail pharmacy shelf-stock tiers.
Pricing Analysis
Long-term offtake contracts dominate government health program procurement in India, locking in volume commitments for lateral flow formats at compressed margins, while spot-market transactions govern retail pharmacy replenishment for self-testing categories where brand premium and FDA clearance tier separate premium positioning from economy alternatives. Pricing pressure stems from nitrocellulose membrane supply concentration among three manufacturers, forcing mid-tier producers toward cost absorption. Hospital procurement committees exhibit lowest price sensitivity due to bundled platform-to-card integration, whereas rural point-of-care networks demonstrate highest sensitivity to per-unit landed cost.
Supply Chain Analysis
Export control regimes restricting microfluidics fabrication equipment constrain capacity expansion outside established manufacturing clusters, with nitrocellulose membrane production anchoring in Germany, the United States, and India while plastic housing molding and final assembly concentrate in China, Malaysia, and Mexico. Raw material dependencies span high-purity cellulose esters, antibody reagents from South Korean biotech suppliers, and specialized adhesives from Japanese chemical manufacturers. Single-source vulnerability permeates membrane substrate allocation, particularly during demand surges for infectious disease panels. Distribution runs through medical device distributors for hospital channels, pharmacy chain direct fulfillment for self-testing, and government tender logistics contractors for public health programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rapid test cards market is recovering from pandemic-era demand volatility, with cyclical normalization in government health program procurement budgets stabilizing volume forecasting for lateral flow manufacturers.
For Market Incumbents: Build regulatory moats through EU MDR notified body relationships and post-market surveillance infrastructure to defend against emerging entrants lacking clinical evidence documentation capabilities. Deepen backward integration into nitrocellulose membrane substrate production to reduce exposure to supply concentration among three chemical manufacturers. Anchor hospital procurement channel control through firmware backward compatibility commitments that complicate hardware refresh strategies for competitors.
For New Entrants and Emerging Players: Pursue pharmacy chain direct distribution partnerships in the United Kingdom and United States, bypassing traditional wholesale layers to capture margin previously allocated to medical device distributors. Target Sub-Saharan African public procurement tenders for malaria and HIV rapid diagnostics, where established cold-chain logistics networks represent the primary barrier to entry rather than manufacturing scale. Position microfluidics-based multiplex formats for emergency department triage workflows as the most penetrable white-space segment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified diagnostics conglomerates seeking to divest non-core rapid test card portfolios amid portfolio rationalization pressures. Long-term viability centers on recurring consumable pull-through from installed digital reader bases rather than transactional card sales. Watch WHO prequalification approval timelines as the critical inflection indicator for low-resource health system procurement eligibility and valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrate Production | Captive nitrocellulose supply from Gujarat facilities insulates Abbott and domestic Indian manufacturers against allocation constraints. |
| Pharmacy Chain Direct Distribution Partnership | Boots and Superdrug category management consolidation in the UK rewards suppliers bypassing traditional wholesale layers with shelf-space access. |
| EU MDR Self-Testing Variant Certification | Notified body relationships and post-market surveillance infrastructure create competitive moats as clinical evidence requirements elevate. |
| Quantum Dot Nanocrystal Reporter Development | Tenfold sensitivity improvements from hybridized gold nanoparticle architectures open sepsis biomarker screening in Bavarian reference laboratories. |
| WHO Prequalification Pathway Investment | Stability testing and lot-release documentation capabilities unlock multi-year tenders for malaria and HIV elimination programs across Sub-Saharan Africa. |
Research Methodology
The analysis maps lateral flow assay, microfluidics, enzyme-linked immunosorbent assay, and digital immunoassay technology tiers, each validated through procurement managers at hospital systems, regulatory affairs specialists at notified bodies, biomedical engineers at point-of-care facilities, and category buyers at pharmacy chains, cross-referenced against FDA 510(k) filings, EU MDR technical documentation, WHO prequalification lists, and Indian PLI scheme beneficiary disclosures, with bottom-up manufacturing capacity assessments triangulated against top-down government health program budget allocations.
Assumptions held fixed include current FDA over-the-counter regulatory pathway timelines and EU MDR clinical evidence requirements for self-testing variants, while variables included India's PLI scheme disbursement rates and nitrocellulose membrane supply allocation policies. Segmentation dimensions spanned product format, technology type, end-user channel, and application area, with CAGRs derived from volume-demand modeling tied to infectious disease screening program expansion and cardiovascular biomarker adoption curves. Forecast inputs incorporated government health scheme procurement pipeline visibility and pharmacy chain shelf-space expansion commitments.
Sensitivities concentrate around WHO prequalification timeline acceleration, nitrocellulose membrane supply disruption events, and FDA regulatory pathway revisions for home-use infectious disease panels. Forecasts reflect documented assumptions regarding decentralized diagnostic infrastructure deployment rates and reader-device backward compatibility demands. Material shifts in EU MDR notified body capacity constraints or Indian PLI scheme eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Urinalysis Test Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Anti-Nuclear Antibody (ANA) Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Self-Testing Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Europe IVD Regulatory Affairs Outsourcing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Toxicity Testing Outsourcing Market
Testing Services
Radiographic Testing Market
Testing Services
Global Coagulation Testing Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market