
 Anti-Asthma TDM Assay Kits Market | 2026-2036
Anti-Asthma TDM Assay Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Asthma TDM Assay Kits Market Outlook
European reagent manufacturers is rebalancing supply chains toward chemiluminescent substrate production after raw material bottlenecks constrained ELISA output. Merck KGaA leverages its captive supply of high-purity antibodies to dominate European hospital tenders. Thermo Fisher Scientific anchors North American distribution through direct sales teams embedded in major health systems. F. Hoffmann-La Roche Ltd. competes on instrument-integrated assay menus that lock in recurring revenue streams.
Anti-asthma therapeutic drug monitoring assay kits are in vitro diagnostic reagents that quantify serum or plasma concentrations of asthma therapeutics such as omalizumab, mepolizumab, and theophylline through antigen-antibody binding reactions, typically achieving detection thresholds below 0.1 µg/mL. These kits enable clinicians to optimize dosing, prevent toxicity, and verify patient adherence in severe asthma management. Chemiluminescent assay formats command premium positioning due to their superior dynamic range and throughput on automated analyzers, while lateral flow assays are gaining traction in point-of-care settings where rapid turnaround outweighs sensitivity requirements. Enzyme-linked immunosorbent assay remains the workhorse format in research institutions and smaller diagnostic laboratories where capital constraints limit platform upgrades.
The FDA's in vitro diagnostic guidance and the EU's In Vitro Diagnostic Regulation together reshape product registration pathways, forcing assay developers to generate expanded clinical evidence for Class C devices. ISO 13485 quality management certification has become a non-negotiable threshold for supplier qualification by multinational distributors. Stakeholders must weigh the capital intensity of automated platform partnerships against the margin compression inherent in commoditized ELISA segments.
Market Dynamics
FDA's tightened guidance on immunosuppressant assay validation is compressing the competitive set toward higher-sensitivity chemiluminescent platforms, forcing mid-tier ELISA manufacturers into costly platform migrations or exit.
Growth Catalysts
- Specialist respiratory center expansion:Hospital laboratories across the United States, Germany, and Japan are scaling therapeutic drug monitoring programs for biologic asthma therapies, creating dedicated assay procurement streams.
- IVDR compliance deadlines:The EU's In Vitro Diagnostic Regulation mandates expanded clinical evidence for Class C devices, accelerating replacement cycles among laboratories seeking future-proof platforms.
- Biologic therapy proliferation:Omalizumab and mepolizumab patient volumes are expanding the addressable sample base requiring quantitative monitoring.
Market Restraints
- High-purity antibody supply concentration:European reagent manufacturers face raw material bottlenecks constraining ELISA output, with chemiluminescent substrate production requiring scarce specialized chemical feedstocks.
- Capital intensity of platform migration:Automated analyzer partnerships demand substantial upfront investment, locking smaller diagnostic laboratories into legacy formats.
- ISO 13485 certification barriers:Quality management certification has become a non-negotiable threshold for supplier qualification by multinational distributors, filtering out regional players.
Strategic Opportunities
- Point-of-care lateral flow expansion:Rapid turnaround requirements in emergency departments and specialist clinics are creating demand for portable assay formats with relaxed sensitivity thresholds.
- Research institution ELISA retention:Capital-constrained academic laboratories represent a stable volume base for conventional format manufacturers facing hospital laboratory automation pressure.
- Instrument-integrated assay menus:Locked recurring revenue streams through analyzer-specific reagent contracts offer defensible positioning against commoditization.
Industry Challenges
- Assay validation timeline compression:FDA guidance updates require regenerating clinical evidence portfolios, stretching regulatory affairs capacity across product lines.
- Legacy system integration friction:Hospital laboratory information systems demand customized data interchange protocols, complicating automated analyzer deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Asthma TDM Assay Kits Market |
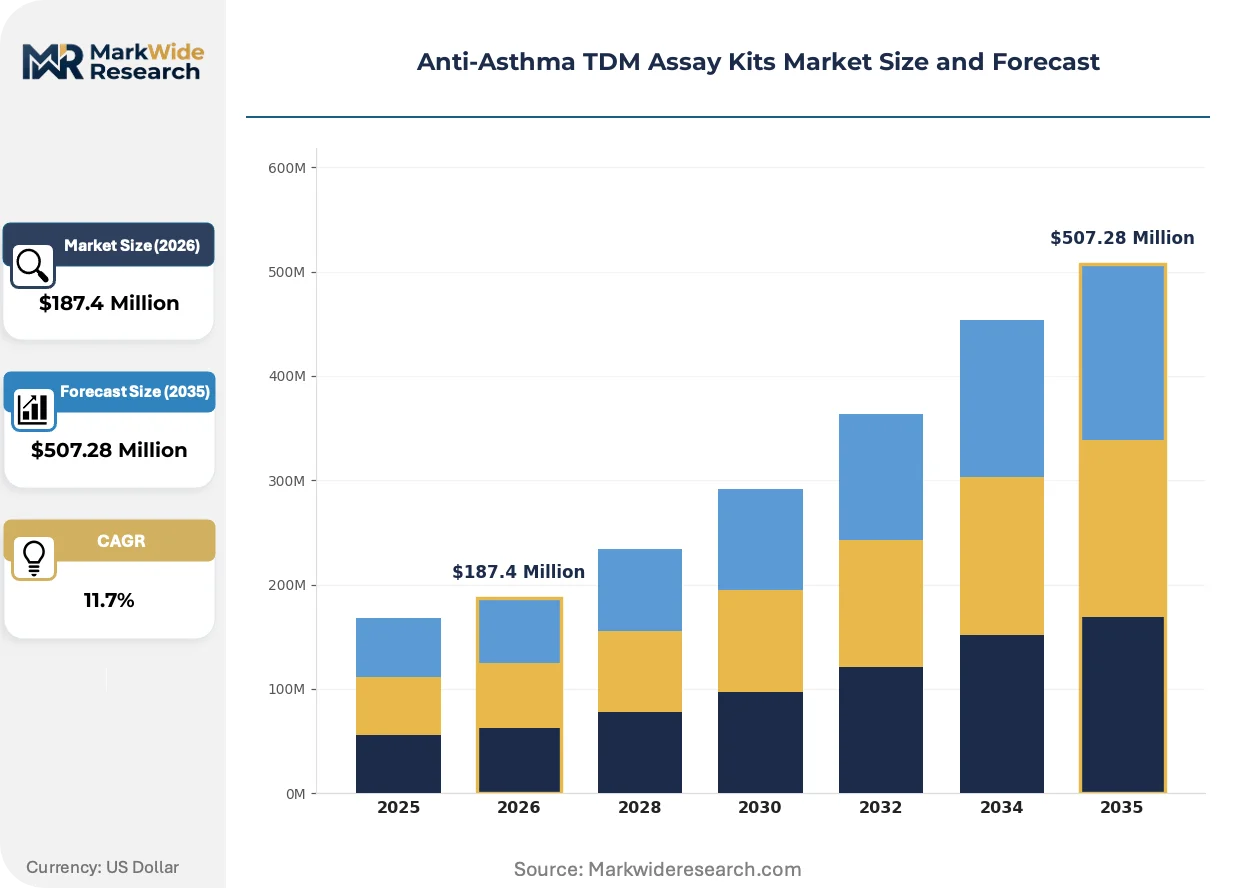
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assay, Chemiluminescent Assay, Lateral Flow Assay, Fluorescent Immunoassay End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Healthcare Services Application: Therapeutic Drug Monitoring, Clinical Trials, Patient Management, Pharmacokinetics Distribution Channel: Online Retail, Direct Sales, Distributors, Medical Supply Stores |
| Companies Covered | Merck KGaA, Eagle Biosciences Inc., F. Hoffmann-La Roche Ltd., Creative Diagnostics, Elabscience Biotechnology Inc., Thermo Fisher Scientific Inc., Svar Life Science AB, MyBioSource Inc., Bio-Techne Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Asthma TDM Assay Kits Market Strategic Shifts
Chemiluminescent detection architectures are consolidating market preference as laboratories prioritize throughput and dynamic range over capital economy, reshaping manufacturer R&D allocation and partnership strategies.
Multiplexed assay panels are integrating cytokine quantification alongside therapeutic drug levels, enabling comprehensive asthma phenotype characterization from single sample draws. Specialist respiratory centers in the United States are adopting these platforms fastest, compressing demand for standalone single-analyte kits. This convergence is integrating inflammatory biomarker workflows into routine therapeutic drug monitoring protocols.
The EU's In Vitro Diagnostic Regulation is mandating expanded performance studies and post-market surveillance for Class C devices. Manufacturers must generate clinical evidence across intended use populations before CE marking, extending product development timelines. Assay developers are responding by prioritizing menu breadth on approved platforms over novel analyte introduction.
Health system consolidation is centralizing procurement decisions at integrated delivery network headquarters, displacing laboratory-level purchasing autonomy. Group purchasing organizations are capturing contract negotiation authority, compressing vendor margins through volume aggregation. This concentration is most visible in United States metropolitan markets where hospital mergers have created super-regional laboratory networks.
Anti-Asthma TDM Assay Kits Market Segmentation
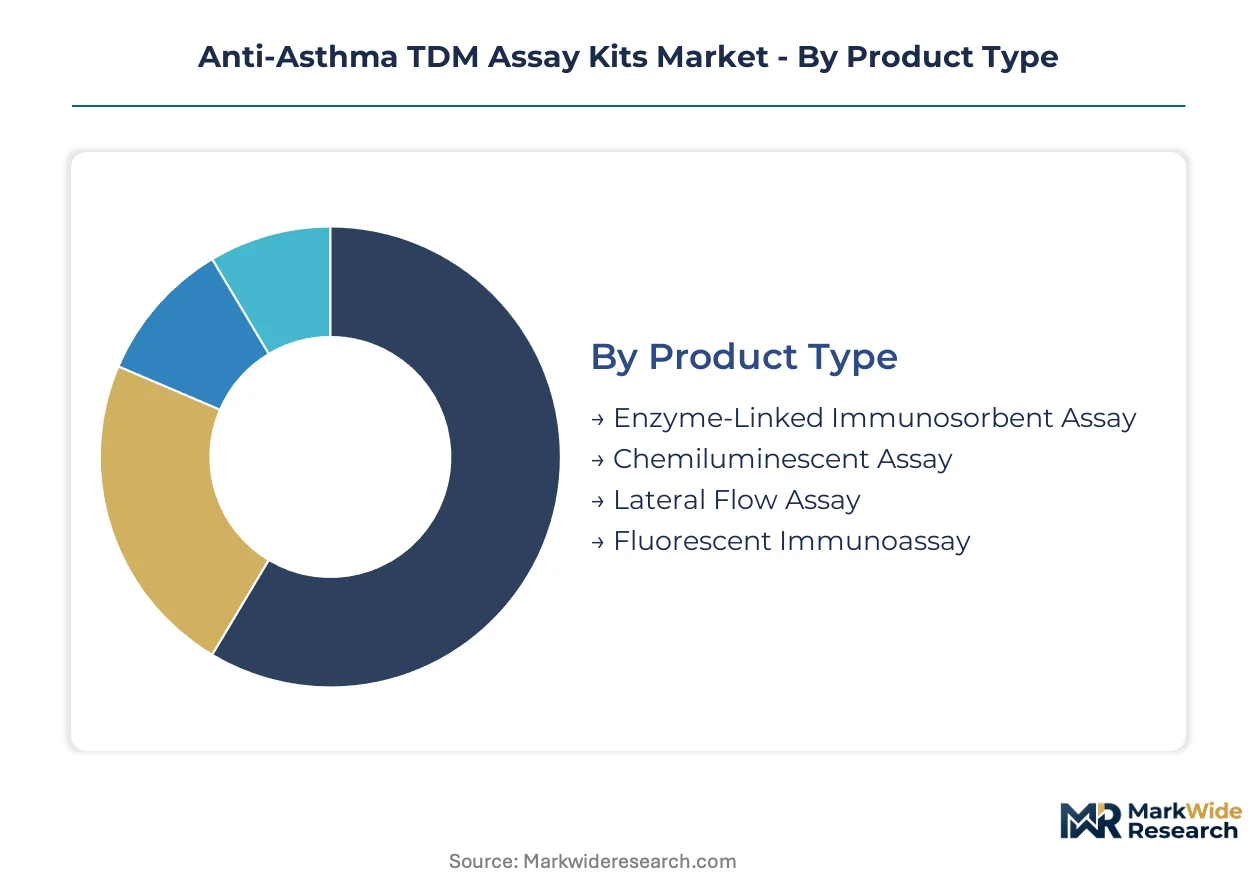
Segmentation in the Anti-Asthma TDM Assay Kits Market reveals how assay format capabilities, procurement pathways, and end-user infrastructure constraints shape commercial outcomes. Manufacturers must align platform specifications with laboratory automation readiness and regulatory compliance timelines across distinct customer archetypes.
Product Type:
Technology sophistication separates hospital laboratories seeking throughput from research institutions prioritizing capital economy over sensitivity specifications.
- Chemiluminescent Assay:Automated detection architectures achieve sub-0.1 µg/mL sensitivity on high-throughput analyzers, commanding premium positioning in United States hospital networks where FDA validation requirements favor platform consolidation. Specialist respiratory centers in Germany and Japan are standardizing on these formats to accommodate expanding biologic therapy volumes.
- Enzyme-Linked Immunosorbent Assay:Manual or semi-automated colorimetric detection remains the default in academic and smaller diagnostic settings where capital constraints delay analyzer upgrades. Research institutions across multiple countries retain substantial ELISA procurement for non-regulated studies.
- Lateral Flow Assay:Point-of-care formats trade sensitivity for rapid turnaround in emergency departments and specialist clinics.
- Fluorescent Immunoassay:Quantitative fluorescence detection occupies niche positions in mid-tier laboratories seeking sensitivity without full chemiluminescence capital commitment.
Volume sits with Chemiluminescent Assay in automated hospital networks; growth tilts toward Lateral Flow Assay in point-of-care expansion.
End User:
Procurement authority concentration distinguishes integrated health systems from fragmented purchasing in academic and home settings.
- Hospitals:Centralized laboratory services within merged health systems drive analyzer-integrated assay contracts, with procurement decisions shifting to integrated delivery network headquarters in United States metropolitan markets. ISO 13485 certification and IVDR compliance documentation are mandatory for vendor qualification.
- Diagnostic Laboratories:Independent reference laboratories and regional networks balance sensitivity requirements against reagent cost, often retaining ELISA workflows for lower-volume analytes while adopting chemiluminescence for high-throughput biologic monitoring.
- Research Institutions:Capital-constrained academic laboratories represent stable demand for conventional formats, prioritizing assay flexibility over regulatory certification.
- Home Healthcare Services:Emerging demand for patient self-monitoring creates opportunities for simplified lateral flow formats with reduced analytical performance requirements.
Procurement volume clusters in Hospitals; Research Institutions offer defensive positioning against automation-driven format displacement.
Application:
Regulatory evidence requirements and reimbursement pathways separate clinical diagnostics from exploratory research use.
- Therapeutic Drug Monitoring:Quantitative measurement of omalizumab, mepolizumab, and theophylline serum concentrations to optimize dosing and verify adherence dominates hospital laboratory workflows. FDA guidance on immunosuppressant assay validation is compressing the competitive set toward higher-sensitivity platforms.
- Clinical Trials:Bioanalytical support for pharmaceutical development demands rigorous validation documentation and cross-site standardization, favoring established manufacturers with regulatory affairs capacity.
- Patient Management:Longitudinal monitoring protocols in severe asthma centers integrate assay data with phenotypic assessment.
- Pharmacokinetics:Specialized absorption-distribution-metabolism-excretion studies require customized assay development for novel biologic entities.
Revenue concentrates in Therapeutic Drug Monitoring; Clinical Trials applications are expanding most quickly with biologic pipeline maturation.
Distribution Channel:
Customer scale and relationship intensity determine whether direct sales investment or third-party logistics delivers superior unit economics.
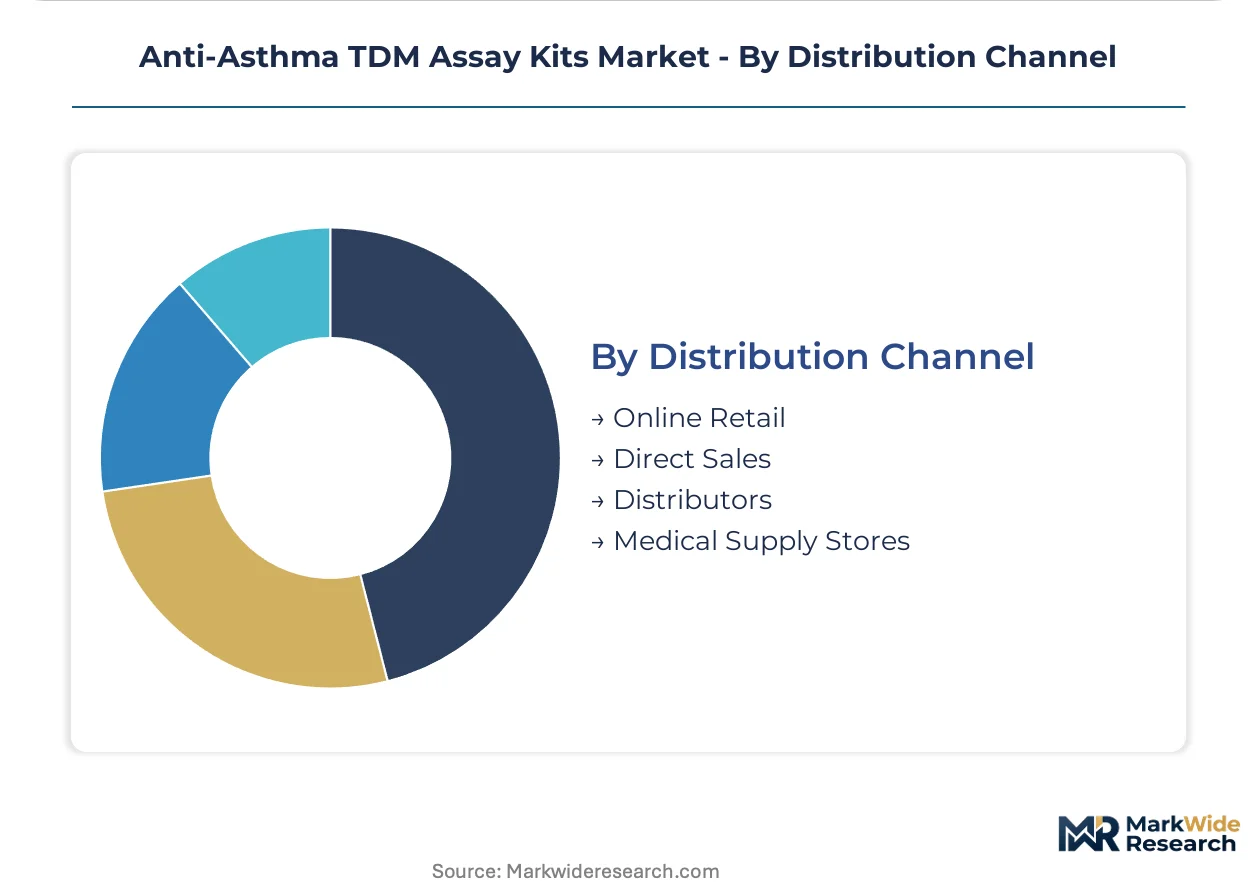
- Direct Sales:Embedded field teams negotiate multi-year analyzer-reagent contracts with major health systems, locking in recurring revenue through platform-specific assay menus. Thermo Fisher Scientific anchors North American penetration through this channel.
- Distributors:Regional and national distributors serve mid-tier laboratories and international markets where direct presence is uneconomical, though margin compression from group purchasing organization aggregation is intensifying.
- Online Retail:E-commerce platforms capture research-grade reagent procurement from small academic laboratories and individual investigators.
- Medical Supply Stores:Traditional channel for point-of-care and home healthcare products with limited technical support requirements.
Contract value concentrates in Direct Sales; Online Retail is gaining share fastest among research segment fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity antibody production concentrates in Germany and Switzerland, anchoring European reagent supply for chemiluminescent assay manufacturing while North American health system consolidation reshapes procurement geography.
United States
Specialist respiratory centers in Boston and New York Metro are scaling therapeutic drug monitoring programs for biologic asthma therapies. FDA guidance on immunosuppressant assay validation is compressing hospital laboratory vendor selection toward higher-sensitivity platforms. Integrated delivery network headquarters in metropolitan markets now control multi-year analyzer-reagent contract negotiations.
Germany
Merck KGaA leverages captive high-purity antibody supply to dominate European hospital tenders for chemiluminescent substrates. The EU In Vitro Diagnostic Regulation mandates expanded clinical evidence for Class C devices, accelerating replacement cycles among laboratories in Bavaria and North Rhine-Westphalia seeking future-proof platforms.
Japan
PMDA regulatory frameworks align with IVDR-equivalent evidence requirements for in vitro diagnostics. Specialist respiratory centers in Tokyo and Osaka are standardizing on automated detection architectures to accommodate expanding omalizumab and mepolizumab patient volumes requiring quantitative monitoring.
United Kingdom
NHS consolidation is centralizing laboratory procurement decisions at regional network headquarters, displacing hospital-level purchasing autonomy. London and Southeast England clusters are adopting multiplexed assay panels integrating cytokine quantification alongside therapeutic drug levels for comprehensive asthma phenotype characterization.
China
NMPA regulatory pathways are tightening clinical evidence requirements for imported diagnostic devices. Research institutions in Beijing-Tianjin-Hebei and Yangtze River Delta regions retain substantial ELISA procurement for non-regulated studies, creating stable demand for conventional assay formats.
Anti-Asthma TDM Assay Kits Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue point-of-care lateral flow expansion and research-grade reagent niches. The competitive set compresses toward instrument-integrated assay menus that lock in recurring revenue through platform-specific contracts. Three archetypes dominate: diversified life science conglomerates with captive antibody supply, specialized diagnostic reagent manufacturers, and platform-anchored instrument vendors. Strategic moves center on automated analyzer partnerships and ISO 13485 certification acquisition to qualify for multinational distributor networks.
Among diversified conglomerates, Merck KGaA and Thermo Fisher Scientific Inc. exemplify scale-driven positioning through embedded supply chain control and direct health system sales presence. F. Hoffmann-La Roche Ltd. occupies the instrument-integrated tier, representing the archetype of locked recurring revenue through analyzer-specific reagent contracts. These three anchors demonstrate how competitive advantage flows from either upstream raw material security or downstream platform captivity rather than standalone reagent innovation.
| Leading Market Players |
|---|
| Merck KGaA |
| Eagle Biosciences Inc. |
| F. Hoffmann-La Roche Ltd. |
| Creative Diagnostics |
| Elabscience Biotechnology Inc. |
| Thermo Fisher Scientific Inc. |
| Svar Life Science AB |
| MyBioSource Inc. |
| Bio-Techne Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive antibody production in Germany and Switzerland anchors both supply security and pricing power for European reagent manufacturers, while outsourced chemiluminescent substrate sourcing exposes mid-tier competitors to margin volatility. This integration choice separates premium-positioned suppliers commanding multi-year analyzer contracts from price-pressed ELISA vendors facing raw material bottlenecks.
Pricing Analysis
Service-bundling separates instrument-integrated contracts from standalone reagent sales, with multi-year analyzer partnerships embedding calibration support and regulatory documentation while research-grade ELISA ships unbundled. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification status and FDA validation tier, with hospital laboratories showing lowest price sensitivity due to locked platform commitments and academic buyers driving hard volume discounts. Cost compression in the ELISA tier is intensifying because high-purity antibody supply concentration limits supplier switching, while chemiluminescent premium tiers defend margins through captive substrate production.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from integrated delivery networks, while regional distributors serve mid-tier diagnostic laboratories and online platforms capture fragmented research procurement. Geographic supply concentrates in Germany, Switzerland, and the United States for high-purity antibodies and chemiluminescent substrates, with raw material dependencies spanning monoclonal antibody cell lines, specialized chemical feedstocks, and precision optical components. Single-source vulnerability in chemiluminescent substrate production creates bottleneck risk, as European manufacturers draw from limited qualified suppliers for acridinium ester derivatives and luminol analogs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-purity antibody production capacity constraints prop pricing power for integrated manufacturers, while outsourced reagent vendors face persistent margin compression from supply bottlenecks.
For Market Incumbents: Lock in analyzer-reagent contracts through embedded field teams before IVDR compliance deadlines accelerate hospital laboratory platform consolidation. Defend against emerging lateral flow entrants by expanding cytokine multiplex menus that exploit chemiluminescence dynamic range advantages. Prioritize backward integration into chemiluminescent substrate production to reduce dependency on scarce specialized chemical feedstocks. For New Entrants and Emerging Players: Begin with point-of-care lateral flow formats targeting emergency departments and specialist clinics where rapid turnaround outweighs sensitivity requirements. Research institutions in China and India offer the most penetrable geography, as capital constraints delay analyzer upgrades and ELISA retention creates stable demand. Pursue online retail distribution to bypass entrenched direct sales relationships dominating hospital procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified life science conglomerates seeking captive antibody supply and platform-anchored instrument vendors expanding assay menus. Long-term viability favors manufacturers with ISO 13485 certification and IVDR-compliant clinical evidence portfolios. Monitor FDA guidance updates on immunosuppressant assay validation as inflection indicators for platform migration timing and replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Pathway | CE marking for Class C devices requires expanded clinical evidence, extending development timelines for assay developers. |
| Analyzer Partnership Lock-in | Multi-year reagent contracts with Thermo Fisher and Roche instruments secure recurring revenue against commoditization pressure. |
| Multiplexed Panel Expansion | Cytokine integration alongside therapeutic drug levels differentiates platforms in specialist respiratory centers. |
| Point-of-Care Format Development | Lateral flow assays address emergency department demand for rapid turnaround with relaxed sensitivity thresholds. |
| Captive Substrate Production | In-house chemiluminescent chemical manufacturing reduces dependency on scarce specialized feedstock suppliers. |
Study Parameters
Regulatory filings from FDA, EMA, and PMDA, hospital procurement databases, and GPO contract repositories formed the secondary backbone for this analysis. Primary interviews with clinical laboratory directors, regulatory affairs specialists at IVD manufacturers, biomedical engineers, and GPO contracts managers combined with secondary validation through ISO 13485 certification records and IVDR technical documentation. Bottom-up assay format demand modeling and top-down health system spending triangulation anchored volume estimates.
Historical trendline analysis of biologic therapy patient volumes and therapeutic drug monitoring program expansion across United States, German, and Japanese hospital networks informed growth trajectory assumptions. Segmentation dimensions modeled include assay format technology tier, end-user infrastructure automation readiness, regulatory compliance status, and distribution channel relationship intensity. CAGRs derived from fitted growth curves incorporating biologic pipeline maturation and replacement cycle timing, with sensitivity testing against FDA guidance implementation pace and IVDR transition deadlines.
Underlying measurement precision varies by segment; chemiluminescent assay forecasts carry tighter precision than lateral flow projections due to consolidated hospital procurement visibility. Forecasts reflect assumptions regarding biologic therapy adoption curves, regulatory timeline adherence, and health system consolidation pace. Practitioners should monitor FDA immunosuppressant assay guidance revisions, EU IVDR notified body capacity constraints, and high-purity antibody supplier expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Mycological Testing Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Medical Device Testing Services Market
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
Pneumonia Testing Market
Testing Services
Healthcare Testing, Inspection, and Certification Outsourcing Market
Testing Services
ATP Assays Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Endocrine Peptides Test Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Global Molecular Quality Controls Market