
 Metrology and Inspection Equipment Market | 2026-2036
Metrology and Inspection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Metrology and Inspection Equipment Market Analytics
Feature-size shrinkage in logic and memory fabrication is narrowing the tolerance window between process control and final yield. KLA Corporation dominates reticle inspection and wafer defect review through captive supply of deep-ultraviolet systems. Applied Materials, Inc. leverages its process equipment installed base to cross-sell integrated metrology modules. Carl Zeiss anchors extreme-ultraviolet optics qualification for next-generation lithography nodes.
Metrology and inspection equipment encompasses coordinate measuring machines, optical comparators, surface roughness testers, and 3D scanners that quantify dimensional deviation, surface topology, and material composition against engineered specifications, typically achieving sub-micron repeatability through interferometric or tactile probing methods. These systems verify conformance in quality control, R&D, process validation, and dimensional inspection workflows across precision manufacturing. Laser technology leads in non-contact speed for automotive body-in-white verification while X-Ray systems capture the fastest expansion in electronics package inspection for void detection in advanced flip-chip interconnects.
FDA 21 CFR Part 820, EU MDR, and ISO 13485 collectively mandate design verification and process validation records that manufacturers generate through automated inspection equipment. The EPA and OSHA frameworks in the United States additionally govern workplace exposure limits around X-Ray and laser-based systems, shaping equipment enclosure and interlock design requirements. Stakeholders must weigh capital intensity against the risk of yield excursions when selecting between in-line and off-line inspection architectures.
Market Dynamics
Sub-7nm lithography nodes are compressing defect tolerance windows below single-digit nanometers, forcing fabs to deploy multi-beam electron microscopy and optical inspection systems that must resolve atomic-scale variations while sustaining wafer throughput above 100 wafers per hour.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers in Germany and Ireland now require automated coordinate measuring machines for dimensional validation records, expanding metrology procurement across orthopedic implant and cardiovascular device production lines.
- Advanced packaging proliferation:Heterogeneous integration in Taiwan and South Korea is driving X-ray inspection demand for void detection in 2.5D and 3D chiplet interconnects, particularly for high-bandwidth memory stacks.
- Automotive electrification:Battery cell manufacturers in Michigan and Bavaria deploy laser radar systems for electrode coating uniformity verification, with gigafactories specifying sub-micron thickness control for lithium-ion anode layers.
Market Restraints
- Extreme-ultraviolet optics scarcity:Single-source dependence on Germanium-arsenide mirror substrates from two specialized foundries in Germany and Japan creates supply bottlenecks for next-generation lithography qualification systems.
- Technical throughput ceiling:Electron-beam inspection systems face fundamental speed limitations when resolving sub-5nm defects, requiring parallel beam architectures that multiply capital cost per inspection station.
- Substitution pressure from computational metrology:Machine-learning inference on process tool data streams is displacing physical measurement for certain inline monitoring applications in mature node fabs.
Strategic Opportunities
- India semiconductor ecosystem:Gujarat and Karnataka fabs under construction will require complete metrology suites for 28nm and 40nm process qualification, representing greenfield equipment deployment without legacy system integration burden.
- Regulatory tailwind from FDA 21 CFR Part 820:Automated inspection documentation requirements for design history files are pushing US contract manufacturers toward integrated dimensional validation platforms with electronic record capture.
- Convergence of optical and X-ray modalities:Hybrid systems combining computed tomography with structured light scanning are opening non-destructive inspection workflows for ceramic matrix composites in aerospace turbine blade production.
Industry Challenges
- Metrology engineer scarcity:Specialized expertise in interferometric calibration and electron optics alignment is concentrated among retiring technicians in Japan and Germany, constraining system deployment velocity.
- Legacy MES integration complexity:Brownfield fabs in Texas and Arizona face protocol translation barriers when connecting new inspection equipment to 1990s-era manufacturing execution systems lacking SEMI standards compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metrology and Inspection Equipment Market |
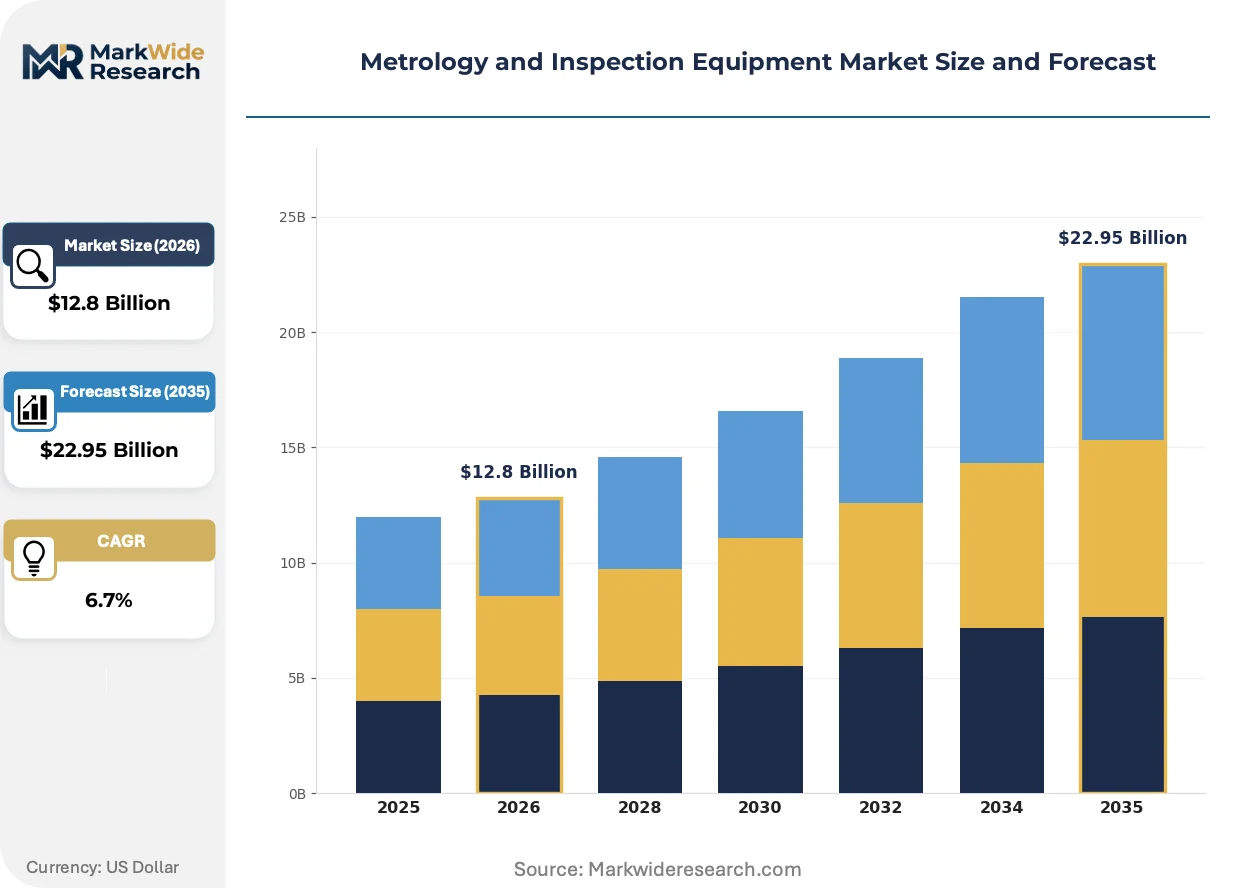
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coordinate Measuring Machine, Optical Comparator, Surface Roughness Tester, 3D Scanner End User: Aerospace, Automotive, Electronics, Medical Device Technology: Laser, Optical, Contact, X-Ray Application: Quality Control, R&D, Process Validation, Dimensional Inspection |
| Companies Covered | KLA Corporation, Applied Materials, Inc., Hexagon AB, Carl Zeiss AG, Nikon Corporation, Thermo Fisher Scientific Inc., Hitachi High-Tech Corporation, ASML Holding N.V., Onto Innovation, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metrology and Inspection Equipment Market Evolving Landscape
Digital twin architectures are virtualizing physical inspection workflows, compressing the feedback loop between process deviation detection and corrective action while reducing reliance on physical reference artifacts.
Computational metrology software is virtualizing traditional hardware-dependent measurement workflows by reconstructing dimensional data from process tool telemetry rather than dedicated inspection stations. Memory fabs in South Korea are adopting these inference-based approaches for blanket film thickness monitoring, reducing capital intensity per 100,000 wafer starts. This virtualization is compressing the addressable market for standalone optical thickness gauges in commodity DRAM production.
EU AI Act risk classification frameworks are mandating validation documentation for machine-learning models embedded in automated defect classification systems. Equipment suppliers must now provide algorithmic transparency packages and performance benchmarking against human expert annotations. Medical device inspection systems sold into European markets face the most stringent conformity assessment requirements, with notified bodies demanding retraining protocols and drift detection mechanisms.
After-sales service unbundling is accelerating as fabs in Taiwan and Arizona negotiate à-la-carte maintenance contracts separate from original equipment purchases. Third-party service providers specializing in electron column refurbishment and laser interferometer recalibration are capturing contract value previously retained by original manufacturers. This disintermediation is most pronounced in mature node facilities where equipment depreciation schedules extend beyond manufacturer support lifecycles.
Metrology and Inspection Equipment Market Segmentation
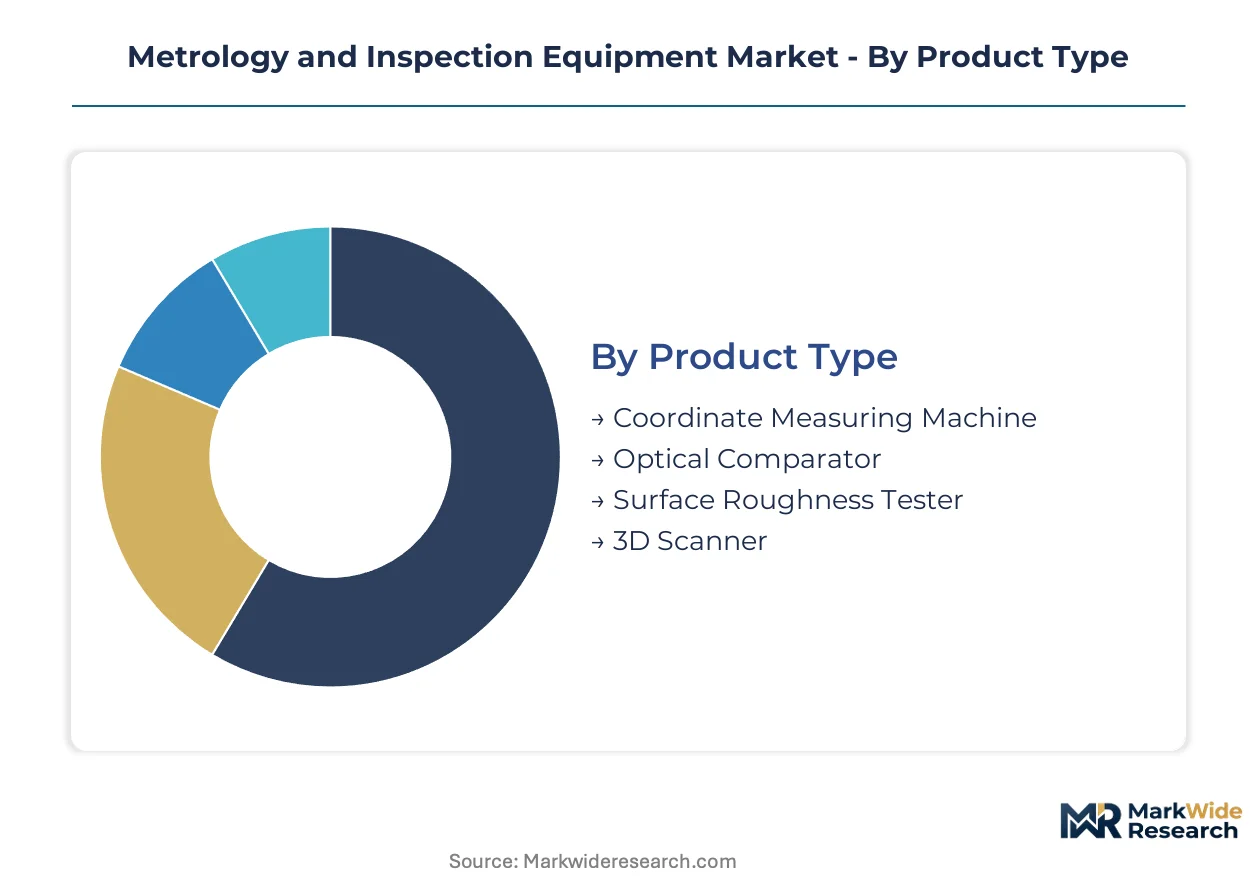
Segmentation in metrology and inspection equipment reveals divergent capital cycles across product categories. Semiconductor fabs refresh electron-beam systems on 4-year depreciation schedules while automotive suppliers run coordinate measuring machines for 15 years. Understanding these replacement rhythms shapes inventory planning and service contract structuring for equipment vendors.
Product Type:
Replacement cycles stretch from 3 years for portable 3D scanners to 20 years for granite-bed coordinate measuring machines, creating fundamentally different revenue models across this category.
- Coordinate Measuring Machine:Granite-bridge and gantry architectures deliver sub-micron repeatability through tactile probing or non-contact laser scanning. German automotive suppliers in Bavaria and Baden-Württemberg anchor demand for large-volume systems verifying powertrain casting geometries against CAD models.
- 3D Scanner:Structured light and laser triangulation systems capture millions of surface points per second for reverse engineering and first-article inspection. Electronics contract manufacturers in Shenzhen and Dongguan drive portable unit procurement for rapid tooling verification in consumer product launches.
- Optical Comparator:Shadow-graph projection systems remain standard for thread form and gear tooth verification in legacy aerospace machine shops.
- Surface Roughness Tester:Stylus profilometers and optical interferometers quantify finish parameters for bearing races and sealing surfaces in medical implant finishing operations.
Coordinate measuring machines dominate installed base. 3D scanners are where expansion concentrates.
End User:
Capital intensity per inspection station varies 10x across end-use sectors, from medical device validation suites to commodity automotive spot-checking.
- Electronics:Wafer fabs and advanced packaging facilities deploy multi-beam electron microscopes and optical inspection systems resolving sub-7nm defects. Taiwan Semiconductor Manufacturing Company and Samsung Electronics in Hsinchu and Pyeongtaek drive the highest-value procurement for lithography qualification.
- Medical Device:Orthopedic implant manufacturers in Warsaw, Indiana and Raynham, Massachusetts require automated coordinate measuring machines generating FDA 21 CFR Part 820-compliant dimensional validation records for design history files.
- Automotive:Battery gigafactories in Michigan and Nevada deploy laser radar systems for electrode coating uniformity verification, specifying sub-micron thickness control for lithium-ion anode layers.
- Aerospace:Turbine blade foundries in Derby, UK and Evendale, Ohio utilize X-ray computed tomography for internal void detection in single-crystal superalloy castings.
Electronics commands the highest equipment value per square meter of cleanroom. Medical device is climbing the fastest on regulatory documentation requirements.
Technology:
Non-contact modalities command price premiums over tactile methods, though contact probing retains irreplaceable accuracy for internal feature measurement.
- X-Ray:Computed tomography systems penetrate sealed electronics packages and composite structures for void detection without destructive sectioning. Taiwan and South Korea packaging houses drive demand for high-resolution systems detecting micro-bump voids in 2.5D chiplet interconnects.
- Laser:Time-of-flight and triangulation sensors enable high-speed surface mapping for automotive body-in-white verification and battery electrode coating inspection.
- Optical:Bright-field and dark-field microscopy systems remain workhorses for semiconductor wafer defect review and reticle qualification.
- Contact:Tactile probing with ruby or silicon nitride styli delivers traceable accuracy for gauge block calibration and critical dimension reference measurements.
X-Ray claims the steepest expansion trajectory on advanced packaging proliferation. Contact probing retains irreplaceable share in calibration laboratories.
Application:
Workflow integration depth separates inline process monitoring from offline quality gates, with R&D applications demanding the highest measurement uncertainty specifications.
- Quality Control:Statistical process control sampling at production lines requires rapid throughput with documented traceability to national measurement institutes. German automotive suppliers deploy automated optical systems at body-in-white welding stations.
- Process Validation:FDA and EU MDR mandate dimensional verification records before manufacturing release, driving automated inspection procurement for medical device production lines in Ireland and Minnesota.
- R&D:New product introduction workflows demand sub-nanometer resolution and comprehensive uncertainty budgeting for patent documentation and design verification.
- Dimensional Inspection:First-article and incoming inspection routines verify supplier conformance against geometric dimensioning and tolerancing specifications.
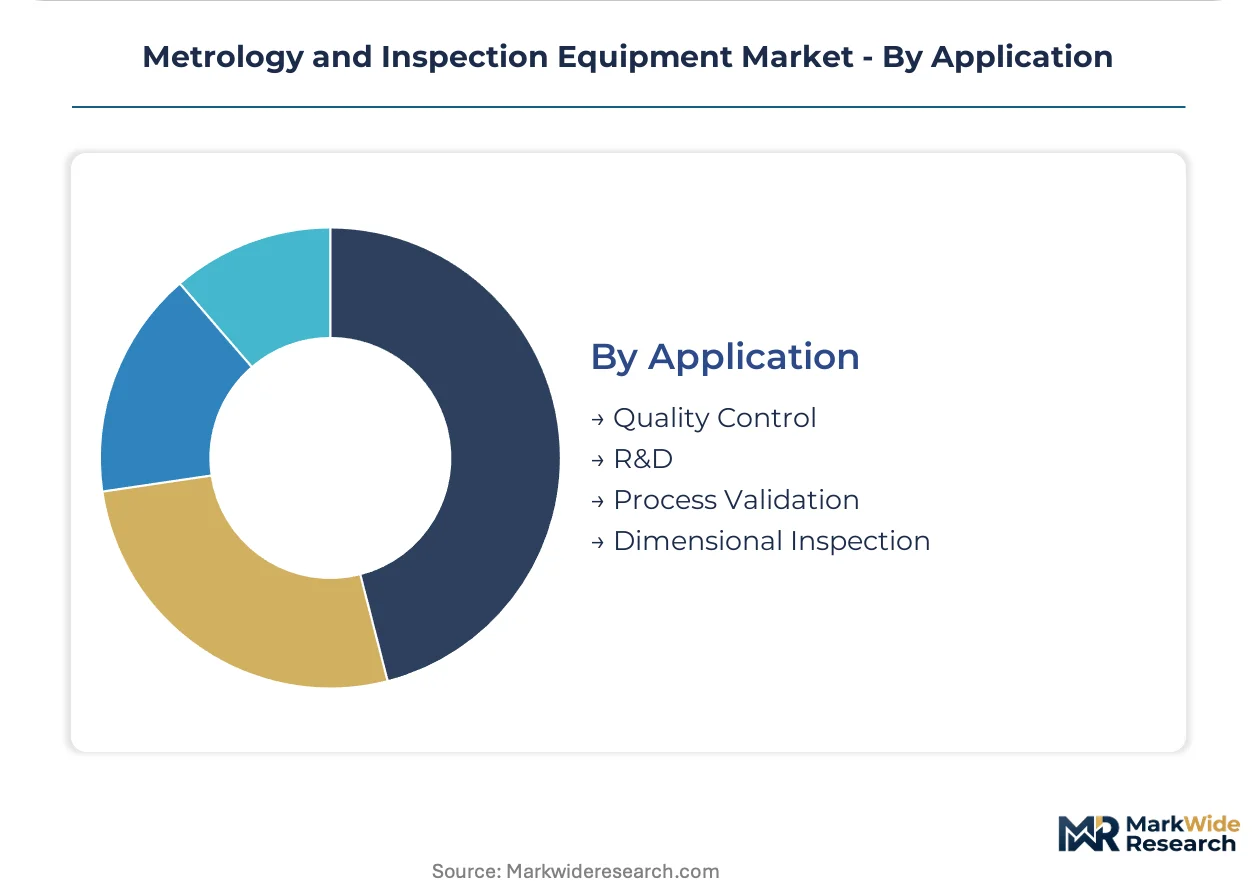
Quality control dominates unit shipments. Process validation is gaining share fastest on regulatory mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in metrology and inspection equipment tilt heavily toward East Asian manufacturing clusters, with Taiwan, South Korea, and Japan running substantial trade surpluses in high-value semiconductor inspection systems while the United States and Germany remain net importers of advanced electron-beam platforms.
United States
Domestic fabs in Arizona and Texas drive procurement of multi-beam electron microscopes for sub-7nm process qualification. FDA 21 CFR Part 820 mandates automated dimensional validation for medical device production lines in Minnesota and Massachusetts. Intel's expanding presence in Chandler and Samsung's Taylor facility anchor capital spending on lithography metrology suites.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg deploy large-volume coordinate measuring machines for powertrain casting verification. The EU MDR traceability framework compels orthopedic manufacturers in Ireland-adjacent supply chains to automate dimensional documentation. Carl Zeiss anchors extreme-ultraviolet optics qualification from its Oberkochen headquarters.
China
Domestic memory and logic fabs in Shanghai and Beijing accelerate procurement of optical inspection systems for mature node production. MIIT localization directives prioritize indigenous metrology equipment for 28nm and above processes. Yangtze Memory Technologies and SMIC drive retrofit demand in the Yangtze River Delta cluster.
Japan
Equipment manufacturers in Tokyo and Osaka supply electron-beam and optical systems to global semiconductor fabs. METI technology roadmaps coordinate public-private investment in next-generation inspection platforms. Nikon and Hitachi High-Tech anchor production in the Chubu and Kanto regions respectively.
South Korea
Samsung Electronics and SK Hynix in Pyeongtaek and Icheon deploy X-ray inspection for high-bandwidth memory stack void detection. MFDS medical device regulations align with EU MDR standards, driving metrology adoption in Gyeonggi-do biotech corridors. Advanced packaging facilities concentrate in the Seoul Capital Area.
Metrology and Inspection Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated lithography-metrology platforms, standalone inspection specialists, and precision measurement instrument fabricators. Strategic archetypes include captive equipment divisions of process tool conglomerates, independent metrology pure-plays, and diversified industrial automation suppliers. Dominant competitive moves encompass technology licensing partnerships for extreme-ultraviolet optics and backward integration into specialized sensor subcomponents.
Within the semiconductor-centric tier, KLA Corporation and Applied Materials, Inc. occupy positions reflecting divergent strategic postures toward integrated versus modular architectures. Among diversified precision measurement specialists, Hexagon AB exemplifies the industrial automation conglomerate model. Carl Zeiss AG anchors the optics-qualification specialist archetype from its German foundation.
| Leading Market Players |
|---|
| KLA Corporation |
| Applied Materials, Inc. |
| Hexagon AB |
| Carl Zeiss AG |
| Nikon Corporation |
| Thermo Fisher Scientific Inc. |
| Hitachi High-Tech Corporation |
| ASML Holding N.V. |
| Onto Innovation, Inc. |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from Germanium-arsenide mirror substrate shortages directly into lithography metrology pricing, while Taiwan-based fabs exploit scale procurement to extract tiered service bundling concessions that compress margins for European precision optics suppliers serving mid-volume medical device manufacturers.
Pricing Analysis
Next-generation extreme-ultraviolet qualification systems command three-to-four-fold premiums over deep-ultraviolet platforms, while legacy optical comparators face commoditization pressure from Chinese manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates lithography-grade interferometers from automotive CMMs and portable 3D scanners. Price differentiation hinges on ISO 17025 calibration certification and geographic proximity to service hubs. Cost compression in economy-tier portable scanners is intensifying because of Shenzhen manufacturing scale. Contract manufacturers in Dongguan exhibit highest price sensitivity; Taiwan semiconductor fabs demonstrate lowest sensitivity due to yield-loss risk.
Supply Chain Analysis
Extended payment terms from Taiwan and South Korea fabs now stretch to 180 days, forcing German and Japanese component suppliers to access supply-chain finance facilities. Germanium-arsenide mirror substrates draw from specialized foundries in Germany and Japan; electron column assemblies rest on precision machining in Switzerland and the United States. Single-source vulnerability concentrates in extreme-ultraviolet optics qualification. Distribution runs through direct OEM sales teams for semiconductor equipment and authorized distributor networks for industrial metrology.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from electron column refurbishment and interferometer recalibration is expanding faster than hardware shipments, as fabs in Arizona and Taiwan negotiate à-la-carte maintenance contracts that disaggregate original manufacturer bundles.
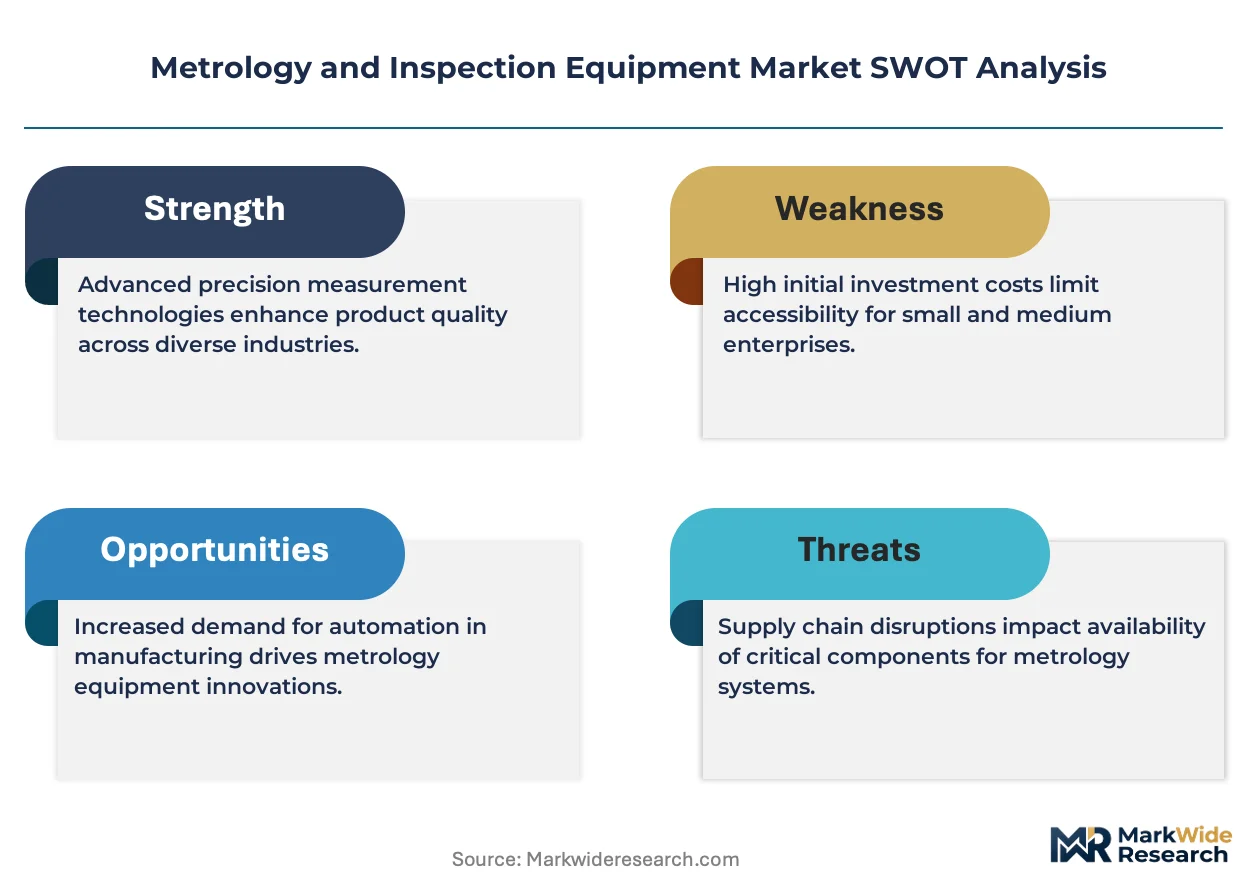
For Market Incumbents: Build captive service networks as the defensive moat. KLA Corporation and Applied Materials should deepen backward integration into specialized sensor subcomponents to lock supply against Germanium-arsenide bottlenecks. Incumbents must invest in FDA 21 CFR Part 820 documentation automation to defend against computational metrology substitution in medical device validation workflows. For New Entrants and Emerging Players: Pursue greenfield 28nm and 40nm fab metrology suites in Gujarat and Karnataka, where legacy MES integration burdens are absent. The India semiconductor ecosystem represents the most penetrable geography. New entrants should anchor go-to-market through third-party service provider partnerships, capturing contract value from equipment depreciation schedules that extend beyond manufacturer support lifecycles. For Investors and Strategic Acquirers: Independent metrology pure-plays with EU AI Act algorithmic transparency packages command strategic premium. Long-term viability favors suppliers with installed base density in medical device corridors where FDA and EU MDR documentation mandates create switching costs. Watch electron-beam throughput breakthroughs as the inflection signal for next-generation lithography qualification equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Subcomponents | Mitigates Germanium-arsenide supply vulnerability for EUV optics manufacturers. |
| Algorithmic Transparency Package Development | Secures EU AI Act conformity assessment for automated defect classification systems. |
| Third-Party Service Network Expansion | Captures refurbishment value from mature node fabs in Texas and Arizona. |
| Greenfield India Fab Partnership | Positions equipment suites for 28nm process qualification without legacy integration. |
| Hybrid Optical-X-Ray System Launch | Opens non-destructive inspection for ceramic matrix composites in aerospace turbine production. |
Research Methodology
The analysis maps semiconductor metrology, industrial precision measurement, and medical device validation segments, each validated through equipment procurement directors, fab operations managers, and regulatory affairs leads at orthopedic implant manufacturers. Primary interviews with aftermarket service heads and electron optics technicians combine with secondary validation from SEMI equipment market data, FDA 510(k) filings, and EU MDR notified body documentation. SEC 10-K segment disclosures and customs trade flows provide triangulation between bottom-up equipment shipment tracking and top-down capital expenditure analysis.
Assumptions around EU MDR enforcement timelines, China MIIT localization directives, and sub-7nm lithography node ramps were held fixed while wafer throughput requirements and computational metrology adoption rates were stress-tested across scenarios. Segmentation dimensions modeled include product architecture, end-use sector, technology modality, and application workflow depth. CAGRs derive from equipment replacement cycle analysis and capital intensity per inspection station benchmarks. Forecast inputs incorporate electron-beam resolution-speed tradeoffs and X-ray computed tomography penetration rates in advanced packaging.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or medical device reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions around regulatory mandate expansion and technology substitution timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Signal Generator Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Oscilloscope Market
Test and Measurement
Semiconductor Assembly and Testing Services Market
Test and Measurement
Metrology Software Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Flow Meter Market
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
AI-Enabled Testing Tools Market