
 Surface Haptic Technology Market | 2026-2036
Surface Haptic Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Haptic Technology Market Outlook
East Asian actuator manufacturing is shifting toward electrostatic and ultrasonic module production for next-generation vehicle cabins. TDK Corporation leverages its ferrite and piezoelectric material expertise to anchor supply chains for automotive tier-one suppliers. Immersion Corporation sustains extensive patent licensing networks across mobile and gaming peripherals. Synaptics Incorporated differentiates through integrated touch-and-haptic controller silicon that reduces bill-of-materials complexity for OEMs.
Surface haptic technology encompasses programmable tactile feedback systems that modulate friction or generate localized vibration across flat glass or polymer surfaces, typically operating at frequencies between 100 Hz and 500 Hz with displacement amplitudes below 10 micrometers to simulate texture, button edges, or pressure confirmation without mechanical travel. The technology serves critical commercial purposes in automotive dashboard safety, surgical robotics precision control, and immersive gaming environments where visual attention must remain fixed. Touchscreens and automotive interfaces command the dominant revenue share due to OEM integration timelines and regulatory safety mandates, while wearable applications represent the fastest-expanding margin pool as fitness and medical device makers seek differentiated user experiences. Electrostatic technology leads in unit economics for large-format displays, whereas piezoelectric solutions capture premium positioning in medical and industrial applications requiring precise force feedback.
FCC certification governs electromagnetic emissions for haptic actuators deployed in US consumer electronics, while EU REACH and RoHS frameworks restrict hazardous substances in piezoelectric ceramics and electrode coatings used across automotive and medical supply chains. China's GB standards and MIIT regulations mandate electromagnetic compatibility testing for domestically manufactured touch interfaces, creating parallel compliance pathways for exporters and local producers. Stakeholders must monitor evolving automotive safety regulations in multiple jurisdictions that increasingly prescribe haptic confirmation for critical vehicle controls previously reliant on physical switches.
Market Dynamics
Automotive safety mandates are forcing a structural transition from mechanical switches to programmable haptic surfaces, compressing OEM integration timelines and rewiring tier-one supplier relationships across vehicle cockpit electronics.
Growth Catalysts
- NHTSA distraction-reduction protocols:US vehicle safety rules now prescribe tactile confirmation for touchscreen controls, accelerating haptic module procurement by Detroit and European automotive headquarters.
- Electrostatic friction modulation:This technology enables texture simulation on flat glass without mechanical travel, opening unit-economic viability for large-format displays in consumer electronics manufacturing corridors.
- Shenzhen-Dongguan cluster concentration:China's consumer electronics assembly ecosystem generates concentrated demand for integrated touch-haptic controller silicon, pulling supply chain investment toward Pearl River Delta component fabrication.
Market Restraints
- Piezoelectric ceramic input volatility:Lead zirconate titanate and barium titanate prices fluctuate with rare earth access, compressing margins for medical-grade actuator producers.
- East Asian supply concentration:Ferrite and piezoelectric material refining capacity clusters in Japan and China, exposing automotive tier-ones to single-source disruption risk.
- Ultrasonic frequency interference:Haptic systems operating above 20 kHz face electromagnetic compatibility constraints under FCC Part 15 and EU RED frameworks, limiting deployment in dense RF environments.
Strategic Opportunities
- Surgical robotics force feedback:Laparoscopic and teleoperated systems require sub-millimeter tactile precision, opening premium positioning for piezoelectric solutions in medical device supply chains.
- Wearable health monitoring interfaces:Fitness and medical device makers seek differentiated user experiences through localized vibration patterns for glucose alerts and arrhythmia notifications.
- EU Green Deal material compliance:REACH and RoHS restrictions on hazardous substances in electrode coatings are accelerating substitution toward lead-free piezoelectric formulations, rewarding early reformulation investments.
Industry Challenges
- Multiphysics simulation expertise scarcity:Designing electrostatic and ultrasonic haptic systems requires coupled electrical-mechanical-acoustic modeling capability that sits with a limited pool of specialized engineering consultancies.
- Cross-jurisdiction certification timelines:Simultaneous FCC electromagnetic emissions validation, EU REACH substance documentation, and China GB standards compliance extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Haptic Technology Market |
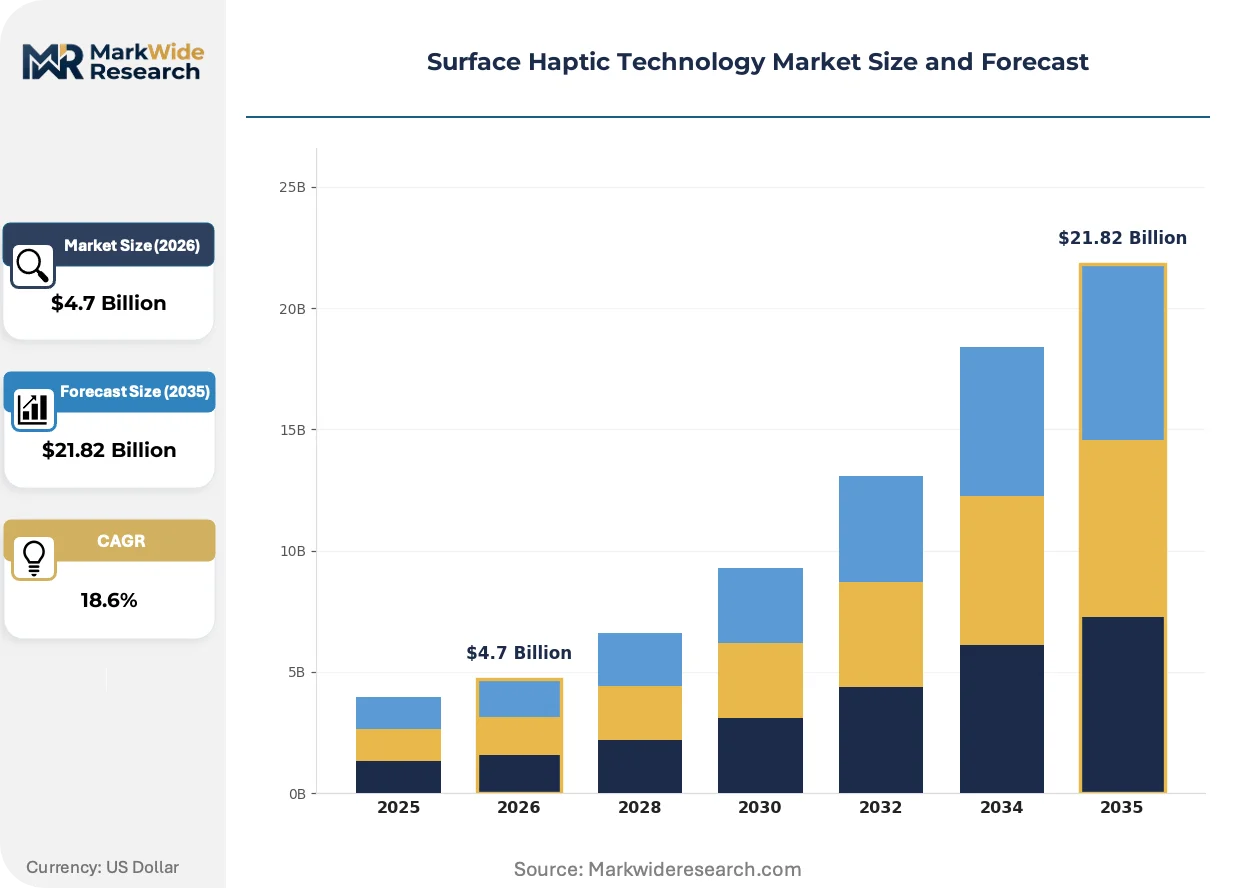
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreens, Wearables, Automotive Interfaces, Game Controllers Technology: Electrostatic, Piezoelectric, Electromagnetic, Ultrasonic Application: Consumer Electronics, Medical Devices, Automotive Systems, Gaming End User: Manufacturers, Developers, OEMs, Retailers |
| Companies Covered | TDK Corporation, Johnson Electric Holdings Limited, Immersion Corporation, hap2U, Boreas Technologies, Texas Instruments Incorporated, Synaptics Incorporated, Ultraleap, AAC Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Haptic Technology Market Strategic Shifts
Surface haptic technology is fragmenting into application-specific architectures, with automotive, medical, and gaming verticals diverging in performance requirements and procurement patterns. Three forces are actively restructuring competitive positioning.
Ultrasonic phased-array actuation is decentralizing haptic feedback generation across vehicle dashboard surfaces. This technology modulates friction through high-frequency surface vibration without localized mechanical components. German and Japanese automotive OEMs are adopting it for steering wheel and center console applications. The shift is compressing supplier hierarchies by enabling tier-ones to source complete haptic surface modules rather than discrete actuator assemblies.
EU automotive safety regulations are tightening tactile confirmation requirements for critical vehicle controls previously reliant on visual feedback. The framework extends existing distraction-reduction mandates to cover all secondary interface interactions. Premium vehicle segments face the steepest compliance deadlines. Suppliers are responding by accelerating integrated touch-haptic controller development to reduce OEM integration complexity.
Medical device procurement is fragmenting toward specialized haptic subsystem vendors capable of ISO 13485-certified force feedback calibration. Hospital purchasing committees now specify programmable tactile response profiles as distinct from generic vibration motors. This pattern is most visible in US and German surgical robotics procurement, where original equipment manufacturers unbundle haptic specification from primary system contracts.
Surface Haptic Technology Market Segmentation
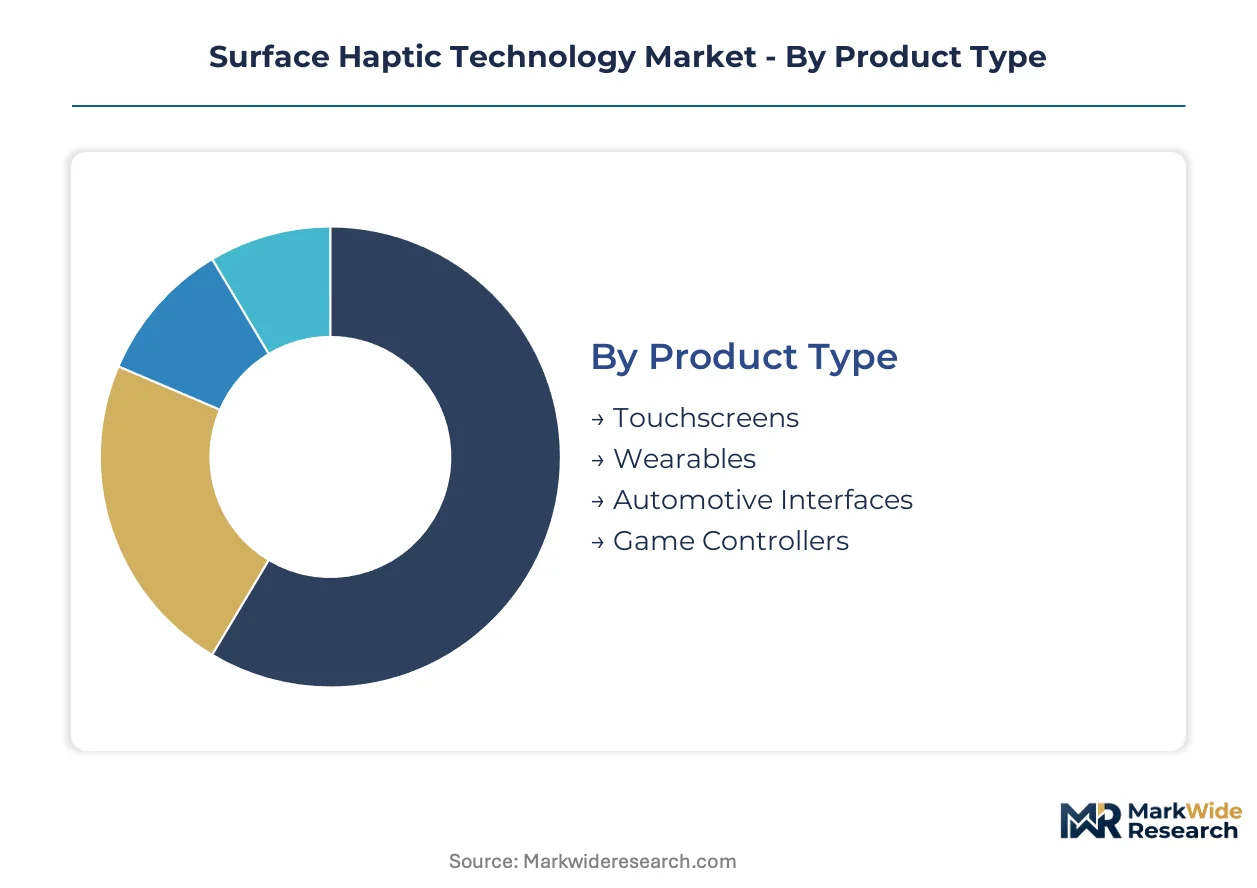
Surface haptic technology fragments into distinct commercial architectures where capital requirements, regulatory exposure, and integration complexity vary dramatically across product categories. Understanding these structural differences guides procurement strategy and partnership selection for component buyers and system integrators.
Product Type:
Capital intensity peaks in automotive interface development where electromagnetic compatibility validation and safety certification consume the largest upfront investment pools.
- Touchscreens:Electrostatic friction modulation dominates this segment, requiring precision electrode patterning on glass substrates. Demand concentrates in China's Shenzhen-Dongguan manufacturing corridor where consumer electronics OEMs source integrated touch-haptic controller silicon for smartphones and tablets. FCC Part 15 electromagnetic emissions compliance adds certification cost layers for US-bound shipments.
- Automotive Interfaces:Ultrasonic phased-array actuation enables programmable feedback across curved dashboard surfaces without mechanical travel. German and Japanese OEM procurement is accelerating under NHTSA and EU safety mandates that prescribe tactile confirmation for touchscreen controls. Tier-one suppliers face compressed integration timelines as vehicle cockpit electronics rewire around haptic surfaces.
- Wearables:Miniaturized piezoelectric actuators deliver localized vibration for fitness and medical alerts. Battery constraints and skin-contact biocompatibility requirements shape component selection.
- Game Controllers:Electromagnetic and eccentric rotating mass motors provide force feedback through mechanical displacement. Peripheral manufacturers prioritize cost optimization over texture simulation precision.
Automotive interfaces absorb the bulk of installed capacity; wearables are expanding most quickly.
Technology:
Margin profiles diverge sharply between mature electromagnetic solutions and emerging ultrasonic architectures that command premium positioning in medical and automotive verticals.
- Electrostatic:Capacitive coupling between finger and electrode array modulates friction through controlled attraction forces. This technology leads unit economics for large-format displays in consumer electronics manufacturing, though humidity sensitivity limits outdoor automotive deployment.
- Piezoelectric:Lead zirconate titanate ceramics generate sub-millimeter displacement with microsecond response times. Surgical robotics manufacturers in the US and Germany specify these actuators for ISO 13485-certified force feedback systems where tactile precision directly impacts procedural outcomes. Rare earth price volatility in barium titanate and PZT supply chains compresses margins for medical-grade producers.
- Electromagnetic:Voice-coil actuators produce mechanical vibration through Lorentz force interaction. Gaming peripheral and basic automotive notification applications dominate volume.
- Ultrasonic:Surface acoustic waves create localized friction reduction zones through high-frequency substrate vibration. Phased-array configurations enable programmable haptic fields across curved vehicle interior surfaces.
Piezoelectric solutions capture the steepest pricing premium; electrostatic technologies move the highest unit volumes.
Application:
Customer procurement patterns separate into specification-driven medical device purchasing versus price-sensitive consumer electronics sourcing with diverging contract structures and qualification timelines.
- Consumer Electronics:Smartphone, tablet, and laptop manufacturers drive the largest absolute demand for integrated haptic modules. China's MIIT electromagnetic compatibility regulations and GB standards create parallel compliance pathways for domestic and export production.
- Automotive Systems:Steering wheel and center console applications require functional safety validation under ISO 26262. EU distraction-reduction mandates and NHTSA protocols are forcing structural transition from mechanical switches to programmable surfaces.
- Medical Devices:Laparoscopic and teleoperated surgical systems demand programmable tactile response profiles distinct from generic vibration motors. Hospital purchasing committees in Germany and the US now unbundle haptic specification from primary robotics contracts.
- Gaming:Immersive environment developers seek texture simulation and pressure confirmation that maintains visual attention on screen content. Controller manufacturers prioritize rapid actuator response over fine force gradation.
Consumer electronics commands current revenue concentration; medical devices are climbing the fastest.
End User:
Technical capability requirements stratify between vertically integrated OEMs with in-house haptic engineering teams and downstream retailers dependent on module suppliers.
- OEMs:Automotive and medical device original equipment manufacturers specify subsystem performance parameters and manage tier-one supplier qualification. These buyers drive architectural decisions around electrostatic versus ultrasonic technology selection.
- Manufacturers:Contract electronics manufacturers in China's Pearl River Delta execute surface haptic module assembly from supplied controller silicon and actuator components. REACH and RoHS substance restrictions on electrode coatings govern material sourcing.
- Developers:Software engineers at gaming studios and industrial interface designers program haptic effect libraries for specific application contexts. API standardization remains fragmented across hardware platforms.
- Retailers:Consumer electronics distributors and aftermarket automotive parts channels stock replacement haptic modules with limited technical configuration support.
OEMs control the specification pathway; manufacturers execute the physical production burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's ferrite and piezoelectric material refining capacity anchors the upstream supply chain for haptic actuator production. German automotive OEMs and Chinese consumer electronics manufacturers pull demand from opposite ends of the value chain. Regulatory divergence across NHTSA, EU safety mandates, and China's MIIT frameworks shapes parallel compliance pathways.
United States
NHTSA distraction-reduction protocols now mandate tactile confirmation for touchscreen vehicle controls, accelerating haptic module procurement by Detroit automotive headquarters. FCC Part 15 electromagnetic emissions certification governs consumer electronics deployment. Austin and San Jose host concentrated engineering talent pools for multiphysics simulation and haptic controller silicon design.
Germany
EU automotive safety regulations are extending tactile confirmation requirements to all secondary vehicle interface interactions, compressing tier-one supplier integration timelines. KBA vehicle-type approval processes incorporate ISO 26262 functional safety validation for programmable cockpit surfaces. Stuttgart and Munich anchor premium OEM engineering centers where ultrasonic phased-array actuation specifications are being finalized.
China
MIIT electromagnetic compatibility regulations and GB standards mandate parallel compliance pathways for domestic and export-bound touch interface production. Shenzhen and Dongguan concentrate consumer electronics assembly ecosystems that generate the largest absolute demand for integrated touch-haptic controller silicon. Local actuator fabrication capacity is expanding to serve both smartphone OEMs and emerging automotive interface programs.
Japan
METI industrial policy supports advanced material refining capacity for lead zirconate titanate and barium titanate ceramics that feed medical-grade actuator supply chains. JIS standards govern piezoelectric component specifications for surgical robotics applications. Tokyo and Osaka host tier-one supplier engineering centers coordinating with German and US automotive OEMs on next-generation vehicle cabin programs.
South Korea
MFDS medical device regulations are shaping haptic subsystem requirements for domestic surgical robotics manufacturers seeking ISO 13485-certified force feedback calibration. Seoul Capital Area concentrates display panel production where electrostatic friction modulation technology integrates into large-format consumer electronics. Local OEMs are expanding procurement of integrated touch-haptic controllers for premium smartphone segments.
Surface Haptic Technology Market Competitive Environment
Global majors compete with regional champions across material science, controller silicon, and system integration capabilities. The vendor base stratifies into three tiers: diversified electronics conglomerates with captive material supply, specialized haptic technology licensors, and automotive-focused actuator subsystem suppliers. Two dominant competitive moves are reshaping positioning: strategic partnerships between tier-one automotive suppliers and controller silicon vendors to compress integration timelines, and technology licensing networks that extend patent coverage across mobile and gaming peripheral ecosystems.
Within the diversified conglomerate tier, TDK Corporation and AAC Technologies occupy positions anchored by ferrite and piezoelectric material expertise. Specialized haptic technology developers including Immersion Corporation and Synaptics Incorporated exemplify the intellectual-property-centric archetype, sustaining extensive patent licensing networks and integrated touch-haptic controller silicon offerings respectively. Texas Instruments Incorporated represents the semiconductor vendor archetype supplying analog and embedded processing components that enable programmable tactile feedback systems.
| Leading Market Players |
|---|
| TDK Corporation |
| Johnson Electric Holdings Limited |
| Immersion Corporation |
| hap2U |
| Boreas Technologies |
| Texas Instruments Incorporated |
| Synaptics Incorporated |
| Ultraleap |
| AAC Technologies |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between ISO 13485-validated medical actuators and consumer-grade electrostatic modules manifests in both pricing power and supply chain sourcing patterns. Premium piezoelectric solutions command service-bundled contracts with calibration warranties, while commodity touchscreen controllers compete on unit economics in Shenzhen assembly corridors.
Pricing Analysis
Warranty and calibration service bundling separates medical-grade piezoelectric actuators from unbundled consumer electronics modules. Three-tier pricing structure across premium, standard, and economy levels tracks ISO certification status and force feedback precision. Pricing pressure stems from rare earth volatility in barium titanate supply chains compressing margins for PZT ceramic producers. Automotive OEMs exhibit lowest price sensitivity given NHTSA compliance deadlines, while smartphone manufacturers drive hardest unit-cost negotiations.
Supply Chain Analysis
Domestic-content mandates in China's MIIT frameworks and EU Green Deal material rules are reshaping electrode coating sourcing toward lead-free formulations. Ferrite refining capacity concentrates in Japan, piezoelectric ceramic production in China, and controller silicon fabrication in the United States. Raw material dependencies span rare earth oxides, glass substrates, and precision electrode alloys. Single-source vulnerability sits with East Asian rare earth processing. Distribution runs through tier-one automotive suppliers and Pearl River Delta contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized multiphysics simulation capability scarcity props pricing for haptic subsystem vendors across automotive and medical verticals. Limited engineering consultancies with coupled electrical-mechanical-acoustic modeling expertise create capacity bottlenecks that sustain margin structures.
For Market Incumbents: Anchor patent licensing networks in mobile and gaming peripheral ecosystems against emerging ultrasonic module competitors. Deepen backward integration into lead-free piezoelectric ceramic formulations ahead of EU REACH restrictions. Prioritize captive supply of ferrite materials to defend against Japanese refining concentration risk.
For New Entrants and Emerging Players: The price-point gap between premium surgical robotics actuators and economy-grade gaming controllers opens white-space targeting. Wearable health monitoring interfaces represent the most penetrable segment given battery constraint tolerance for new architectures. Pursue ISO 13485 certification partnerships with German hospital purchasing committees as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized haptic subsystem vendors given EU automotive safety mandate acceleration. Long-term viability favors firms with dual automotive-medical certification pathways. Watch NHTSA rulemaking expansion to secondary vehicle controls as the inflection signal for tier-one procurement volume.
| Strategic Initiative | Industry Significance |
|---|---|
| Lead-Free Piezoelectric Reformulation | EU REACH compliance secures automotive tier-one qualification pipelines ahead of substance restrictions. |
| Ultrasonic Phased-Array Module Launch | German OEM steering wheel programs validate friction modulation without mechanical travel. |
| Integrated Touch-Haptic Controller Partnership | Synaptics-style silicon consolidation reduces OEM bill-of-materials complexity. |
| Surgical Robotics Force Feedback Certification | ISO 13485 validation unbundles haptic specification from primary system contracts. |
| Pearl River Delta Manufacturing Footprint | Shenzhen-Dongguan proximity aligns with smartphone OEM procurement clusters. |
Study Parameters
Independent corroboration across tier-one automotive supplier procurement leads, biomedical engineering directors at surgical robotics OEMs, and Pearl River Delta contract manufacturing executives underwrites the qualitative findings. Primary interviews with haptic controller silicon architects, multiphysics simulation specialists, and hospital purchasing committee members combined with secondary validation from FCC Part 15 filings, EU REACH substance databases, and China GB standards documentation. Bottom-up actuator shipment estimates and top-down automotive electronics content analysis provided triangulation anchors.
Comparable historical reference periods spanning pre-regulatory mandate and post-mandate implementation phases anchored the forecast window construction. Segmentation modeling across product type, technology architecture, application vertical, and end-user procurement authority dimensions structured the analytical framework. CAGRs derived from fitted growth curves incorporating NHTSA compliance timeline acceleration, MIIT electromagnetic compatibility enforcement patterns, and medical device ISO certification backlog durations.
Inputs from automotive OEM platform engineering disclosures and surgical robotics FDA submission databases were available through the study window; gaps in real-time rare earth oxide pricing transparency introduce uncertainty bands around piezoelectric cost projections. Forecasts reflect documented assumptions regarding regulatory implementation pacing and tier-one supplier qualification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Portable Iris Recognition Scanner Market
Sensors
Smart Mat Market
Sensors
Cloud Camera Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
IO-Link Technology Market
Sensors
Bluetooth Beacons Market
Sensors
Drain Camera Market
Sensors
Facial Tracking Solution Market
Sensors
Smart Barcode Readers Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
RFID Smart Cabinet Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Asia-Pacific Remote Sensing Technology Market
Sensors
Wireless RFID Readers Market
Sensors
Micro Location Technology Market
Sensors
Asia Pacific RFID Market