
 Spatial Mass Spectrometry Market | 2026-2036
Spatial Mass Spectrometry Market Size, Share, and Industry Trends Forecast 2026-2036
Spatial Mass Spectrometry Market Analytics
The gap between spatial resolution and throughput in mass spectrometry imaging is narrowing as MALDI-TOF platforms integrate with high-speed laser optics. Thermo Fisher Scientific leverages its Orbitrap architecture to anchor premium positioning in high-resolution tissue imaging workflows. Bruker Corporation sustains competitive intensity through specialized MALDI instrumentation for clinical pathology laboratories. Danaher Corporation navigates the segment via its Leica microscopy-to-mass-spec integration strategy.
Spatial mass spectrometry maps molecular distributions across tissue surfaces by ionizing analytes at discrete coordinates and detecting mass-to-charge ratios with micron-scale precision, primarily serving pharmaceutical target validation and clinical biomarker localization. Matrix-Assisted Laser Desorption Ionization occupies the dominant installed base due to mature workflows in proteomics imaging, while Desorption Electrospray Ionization represents the fastest-expanding modality for ambient ionization of metabolites in native tissue environments. Reagents and consumables command recurring revenue streams that software increasingly penetrates through AI-assisted ion image reconstruction.
The FDA regulates spatial mass spectrometry devices under in vitro diagnostic pathways when deployed for clinical decision-making, while ISO 13485 quality management standards govern manufacturing systems for instrument OEMs. The European Union's In Vitro Diagnostic Regulation intensifies conformity requirements for clinical mass spectrometry platforms entering European laboratories. Stakeholders must monitor evolving reimbursement frameworks for spatial molecular diagnostics as health technology assessment bodies weigh evidence standards for image-based biomarker quantification.
Market Dynamics
Resolution-throughput tradeoffs in MALDI-TOF platforms are collapsing as high-repetition-rate laser systems and AI-assisted ion image reconstruction compress analytical cycles from hours to minutes, forcing vendors to recalibrate R&D roadmaps and pricing architectures around speed rather than raw precision alone.
Growth Catalysts
- FDA's 21st Century Cures Act:Accelerated approval pathways for precision medicine diagnostics expand reimbursement eligibility for spatial molecular profiling in oncology and neurology clinical trials.
- NIH spatial omics infrastructure grants:United States federal funding for transcriptomics and proteomics core facilities drives instrument procurement at academic medical centers and research institutes.
- High-speed laser optics integration:Next-generation MALDI platforms achieve pixel acquisition rates exceeding 50 pixels per second, enabling pharmaceutical toxicology screening at tissue-section scale.
Market Restraints
- Helium supply concentration:Mass spectrometer vacuum systems depend on helium imports from Qatar and the United States, with price volatility affecting OEM service contract economics.
- EU IVDR conformity timelines:Extended notified body review periods for clinical mass spectrometry platforms delay European commercialization by 18-24 months versus predecessor directive pathways.
- Fluorinated matrix compound substitution:Environmental pressure to replace perfluorinated ionization matrices creates workflow revalidation burdens for proteomics laboratories.
Strategic Opportunities
- India CDSCO diagnostic pathway expansion:Emerging regulatory clarity for mass spectrometry-based clinical assays opens access to a pathology laboratory base exceeding 100,000 registered facilities.
- Ambient ionization-metabolomics convergence:Desorption Electrospray Ionization integration with high-resolution mass analyzers enables intraoperative metabolite mapping for surgical margin assessment.
- Cloud-native AI reconstruction platforms:Subscription-based ion image analysis software penetrates mid-tier research institutions previously priced out of on-premise high-performance computing.
Industry Challenges
- Mass spectrometry histology technician shortage:Specialized training programs for tissue preparation and matrix application lag instrument installation growth, creating operational bottlenecks.
- ISO 13485 certification complexity:Dual quality system maintenance for research-use-only and in-vitro diagnostic product lines strains mid-size manufacturer compliance resources.
- LIMS-MS imaging data integration:Legacy laboratory information management systems lack native support for multi-terabyte spatial datasets, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spatial Mass Spectrometry Market |
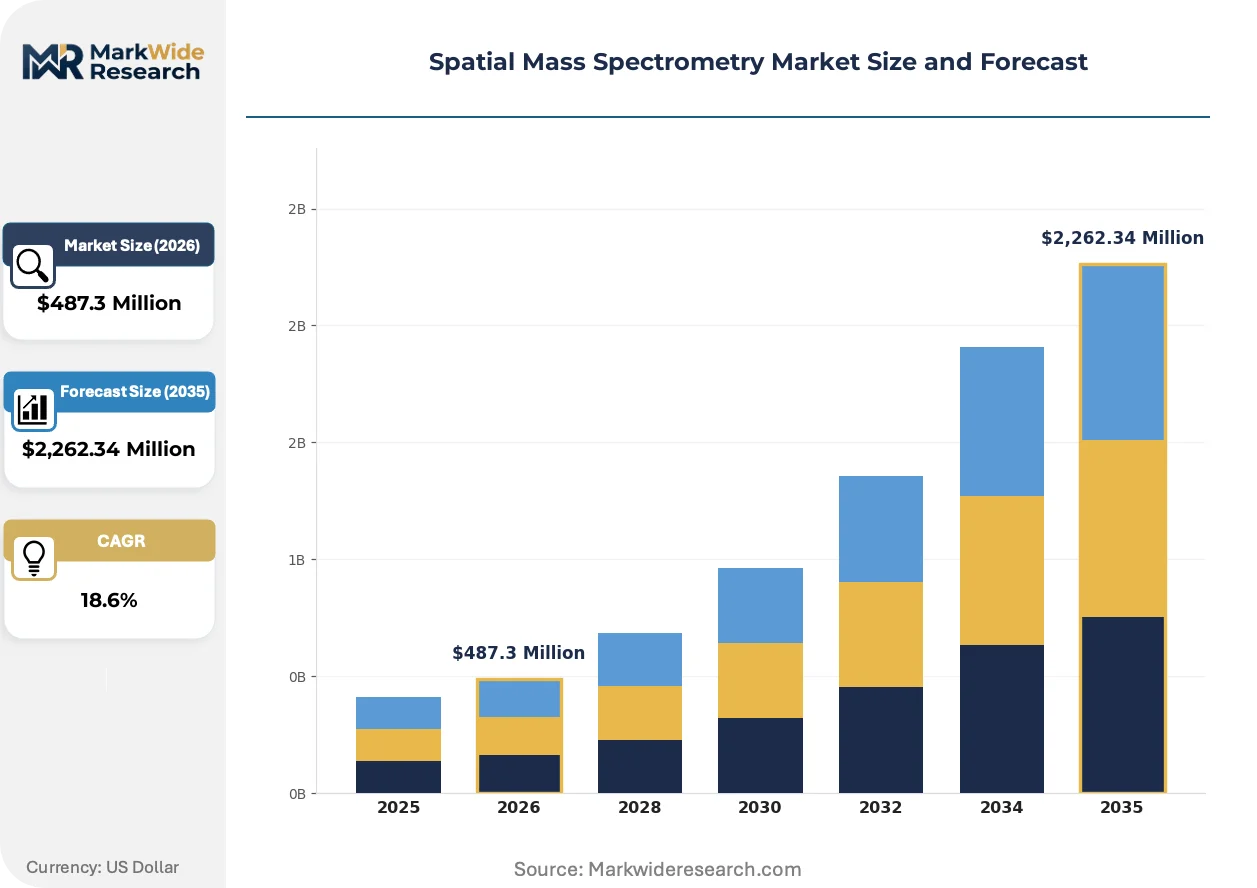
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Matrix-Assisted Laser Desorption Ionization, Secondary Ion Mass Spectrometry, Laser Ablation Mass Spectrometry, Desorption Electrospray Ionization End User: Pharmaceuticals, Academia, Clinical Laboratories, Environmental Testing Application: Proteomics, Metabolomics, Imaging Mass Spectrometry, Drug Development Product Type: Instruments, Reagents, Software, Consumables |
| Companies Covered | Thermo Fisher Scientific, Shimadzu Corporation, Agilent Technologies, Bruker Corporation, Danaher Corporation, PerkinElmer, Waters Corporation, JEOL Ltd., Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spatial Mass Spectrometry Market Evolving Landscape
Spatial mass spectrometry workflows are converging with adjacent imaging modalities and computational platforms, eroding traditional boundaries between mass-spec core facilities and digital pathology departments while creating new vendor partnership configurations.
Laser ablation electrospray ionization is hybridizing with optical microscopy guidance systems to enable real-time tissue targeting during ion acquisition. Pharmaceutical toxicology groups at contract research organizations adopt these platforms for rapid compound distribution screening in rodent studies. The technology is hybridizing what were previously discrete histology and mass spectrometry workflows into unified molecular pathology pipelines.
REACH restrictions on per- and polyfluoroalkyl substances are compelling matrix manufacturers to reformulate ionization aids for proteomics imaging. Industrial chemical suppliers face substance registration deadlines that compress reformulation timelines to 24 months. European proteomics core facilities are responding by stockpiling legacy matrices while validating biodegradable alternatives.
Consolidated procurement by multi-site health systems is displacing individual laboratory purchasing autonomy for capital mass spectrometry platforms. United States academic medical centers increasingly centralize spatial omics instrumentation at designated core facilities rather than distributing units across departments. This concentration pattern is most visible in the Northeast corridor, where NIH-funded institutions share access models across hospital networks.
Spatial Mass Spectrometry Market Segmentation
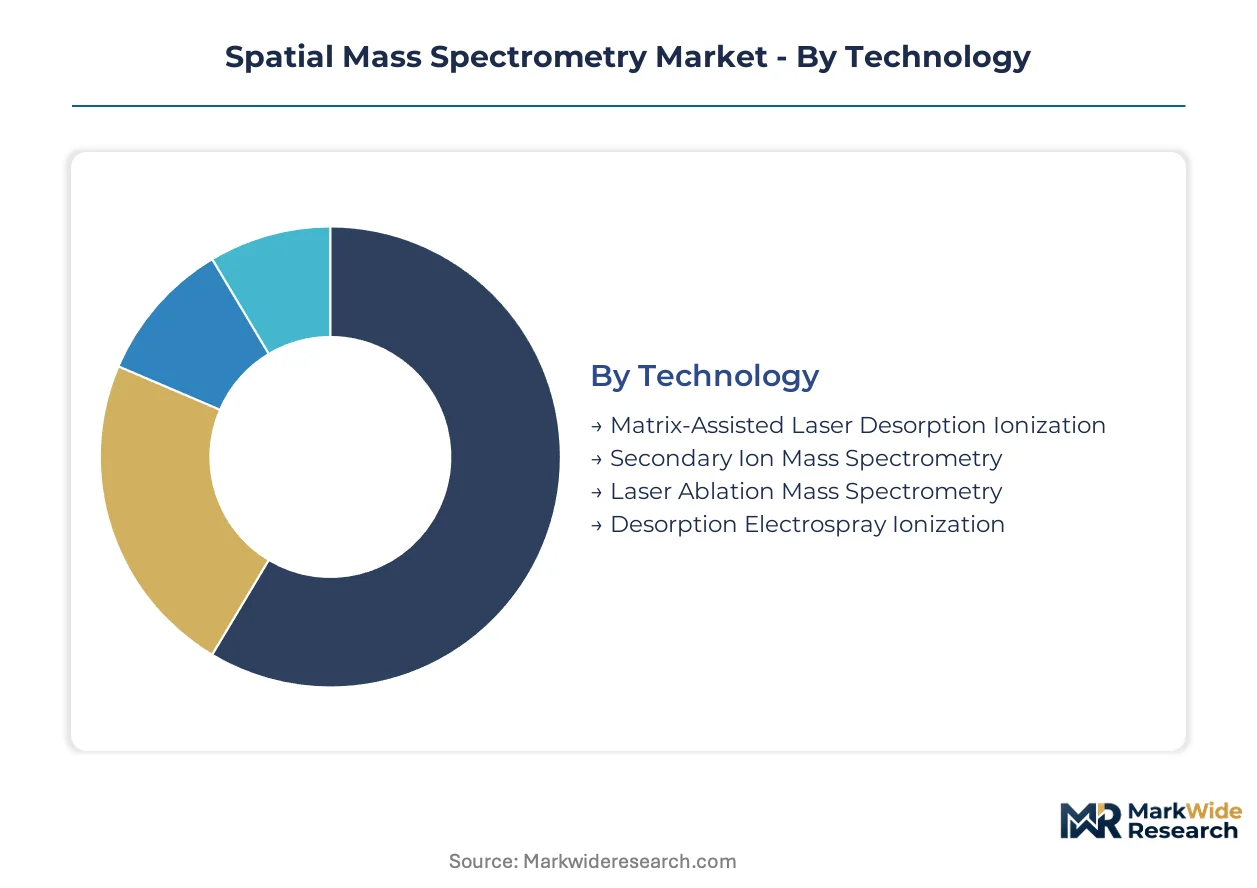
Spatial mass spectrometry vendors configure product portfolios around distinct technology-performance tiers and end-use workflows. Segmentation reveals where procurement concentrates versus where emerging applications are reshaping demand patterns.
Technology:
Cost tier differentiation in ionization platforms separates mature high-throughput systems from premium-resolution instruments and emerging ambient technologies.
- Matrix-Assisted Laser Desorption Ionization:Mature ionization using organic matrix compounds enables routine proteomics imaging with established sample preparation protocols. Pharmaceutical toxicology groups in the United States deploy MALDI-TOF platforms for compound distribution studies in rodent tissue sections, driven by FDA 21st Century Cures Act funding for precision medicine biomarker programs.
- Desorption Electrospray Ionization:Ambient ionization eliminates matrix application for native tissue metabolite analysis. Academic medical centers in Germany and France adopt DESI for intraoperative surgical margin assessment, constrained by EU IVDR conformity timelines extending European commercialization cycles.
- Secondary Ion Mass Spectrometry:High-resolution surface analysis using primary ion beams achieves sub-micron lateral resolution for semiconductor and materials science applications.
- Laser Ablation Mass Spectrometry:Direct solid sampling without matrix requirements suits elemental imaging in environmental and geological specimens.
MALDI commands the established base. The steepest expansion runs through DESI as ambient workflows penetrate clinical pathology laboratories.
End User:
Application maturity varies sharply across customer types, with regulatory certification requirements filtering access to clinical segments.
- Pharmaceuticals:Contract research organizations and large pharma houses drive capital equipment procurement for target validation and toxicology screening. United States-based firms leverage NIH spatial omics infrastructure grants to anchor imaging mass spectrometry at designated core facilities.
- Clinical Laboratories:Anatomic pathology departments adopt MALDI imaging for biomarker localization in oncology diagnostics. ISO 13485 certification complexity constrains mid-size manufacturer entry into this segment.
- Academia:Research institutes and university core facilities represent the traditional installed base for technology evaluation and methods development.
- Environmental Testing:Regulatory laboratories employ laser ablation platforms for elemental mapping in contaminated soil and water specimens.
Pharmaceuticals anchor current revenue concentration. Clinical laboratories are gaining share fastest as reimbursement frameworks mature for spatial molecular diagnostics.
Application:
Workflow integration depth determines where software and consumables attach to instrument sales versus standalone analytical services.
- Proteomics:Peptide and protein imaging dominates published literature and established core facility workflows. REACH restrictions on perfluorinated matrices in Europe compel reformulation investments by reagent suppliers.
- Metabolomics:Small-molecule spatial mapping expands fastest through DESI ambient ionization. High-speed laser optics integration enables pharmaceutical toxicology screening at tissue-section scale in United States CROs.
- Imaging Mass Spectrometry:The foundational workflow category spans all ionization modalities for molecular histology applications.
- Drug Development:Compound distribution studies in preclinical species support regulatory submission packages for new molecular entities.
Proteomics holds the deepest installed base. Metabolomics is climbing the fastest as ambient ionization collapses sample preparation barriers.
Product Type:
Margin structure and customer lifetime value diverge between capital equipment and recurring revenue streams.
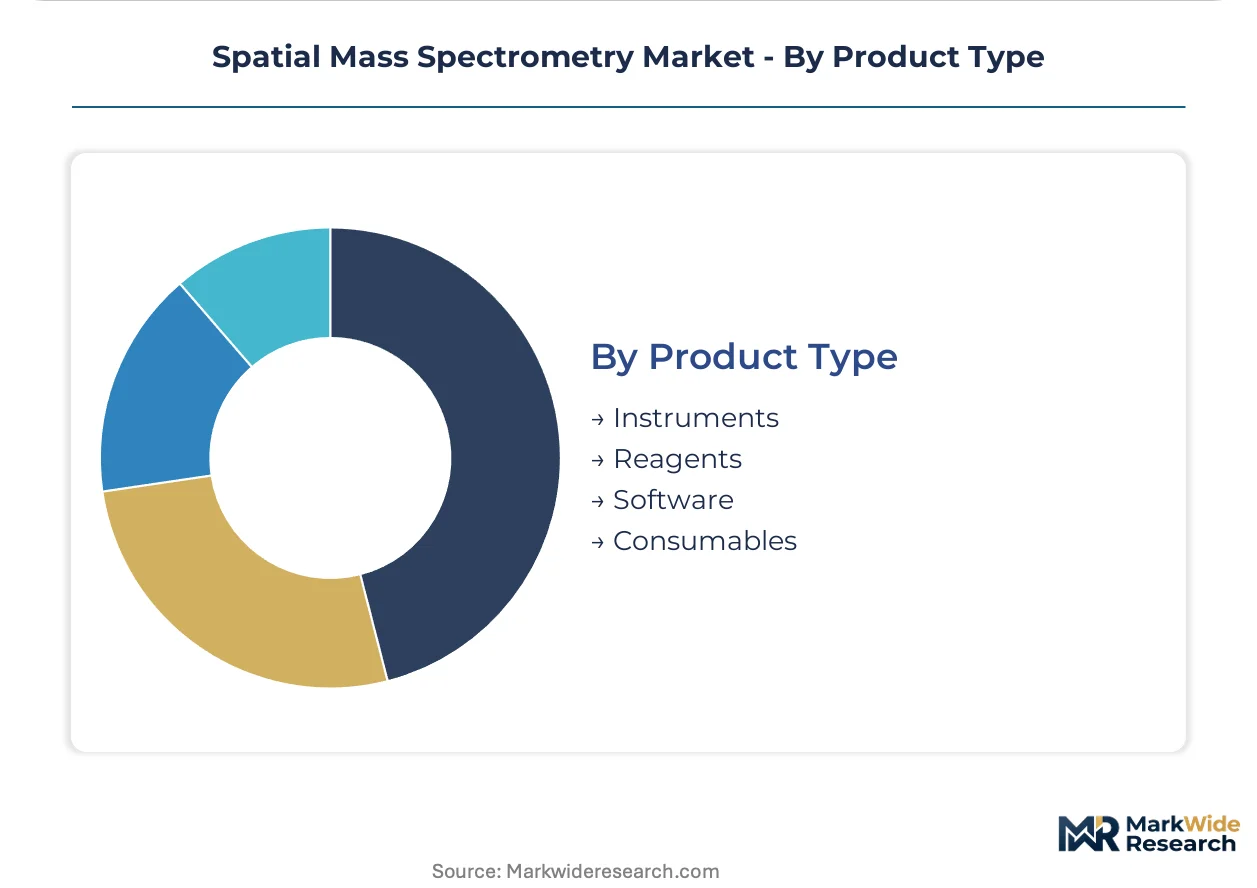
- Instruments:MALDI-TOF and Orbitrap platforms represent seven-figure capital commitments with 5-7 year replacement cycles. Consolidated procurement by United States academic medical centers concentrates purchasing authority at designated core facilities.
- Software:AI-assisted ion image reconstruction penetrates mid-tier research institutions through cloud-native subscription models previously priced out of on-premise high-performance computing.
- Reagents:Matrix compounds, calibrants, and sample preparation kits generate recurring revenue with 60-70% gross margins.
- Consumables:Target plates, ion sources, and vacuum system components attach to service contract renewals.
Instruments anchor the revenue base. Software subscriptions are expanding most quickly as computational analysis shifts from capital expenditure to operating expense models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German instrument manufacturers export high-resolution mass spectrometry platforms to United States academic medical centers, while Japanese analytical equipment flows into pharmaceutical contract research organizations across North America and Europe.
United States
NIH spatial omics infrastructure grants drive instrument procurement at designated core facilities in Boston and San Francisco. FDA's 21st Century Cures Act accelerates precision medicine regulatory pathways favoring spatial molecular profiling technologies. Pharmaceutical toxicology groups in the Research Triangle Park region deploy MALDI-TOF platforms for compound distribution studies in rodent tissue sections.
Germany
Academic medical centers in Heidelberg and Munich adopt DESI ambient ionization for intraoperative surgical margin assessment workflows. EU IVDR conformity timelines extend notified body review periods, delaying European commercialization cycles for clinical mass spectrometry platforms. The Baden-Württemberg industrial corridor hosts specialized MALDI instrumentation manufacturers serving clinical pathology laboratories.
Japan
Pharmaceutical houses in Tokyo and Osaka leverage high-speed laser optics integration for pharmaceutical toxicology screening at tissue-section scale. METI funding for advanced analytical instrumentation supports domestic manufacturing of Orbitrap-architecture platforms. The Kansai region concentrates proteomics imaging core facilities developing AI-assisted ion image reconstruction methods.
India
CDSCO diagnostic pathway expansion for mass spectrometry-based clinical assays opens access to a pathology laboratory base exceeding registered facilities in Maharashtra and Gujarat. Central Drugs Standard Control Organization regulatory clarity accelerates spatial molecular diagnostics adoption. Bengaluru's biotech cluster attracts cloud-native AI reconstruction platform deployments for mid-tier research institutions.
United Kingdom
London and Cambridge academic networks share NIH-funded spatial omics instrumentation access models across hospital networks. MHRA alignment with FDA accelerated approval pathways supports precision medicine diagnostic reimbursement frameworks. The Oxford-London corridor concentrates contract research organizations integrating imaging mass spectrometry into target validation workflows.
Spatial Mass Spectrometry Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. The vendor base separates into consolidated analytical instrumentation conglomerates, mid-size mass spectrometry specialists, and emerging ambient ionization technology developers. Strategic archetypes include platform-anchored full-line suppliers, modality-focused precision instrument builders, and software-forward computational analysis providers. Dominant competitive moves center on microscopy-to-mass-spec integration strategies and cloud-native AI reconstruction platform licensing.
Among United States-based analytical conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify platform-anchored full-line supplier archetypes, while Bruker Corporation represents the modality-focused precision instrument builder tier. These three entities occupy positions spanning premium-resolution Orbitrap architectures, specialized MALDI clinical pathology instrumentation, and microscopy integration strategies. Japanese manufacturers Shimadzu Corporation and JEOL Ltd. sit within the precision instrument builder category alongside Rigaku Corporation, with Waters Corporation and Agilent Technologies representing additional full-line supplier positions. PerkinElmer occupies a distinct software-forward tier emphasizing computational analysis workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| Agilent Technologies |
| Bruker Corporation |
| Danaher Corporation |
| PerkinElmer |
| Waters Corporation |
| JEOL Ltd. |
| Rigaku Corporation |
| Others |
Value Network & Pricing Analysis
The Baden-Württemberg industrial corridor anchors specialized MALDI instrumentation manufacturing, with capacity constraints in high-resolution vacuum system assembly translating into premium pricing power for German OEMs serving United States academic medical centers.
Pricing Analysis
Next-generation MALDI-TOF platforms command three-to-four-fold premiums over prior-generation systems, while economy-tier refurbished instruments penetrate mid-tier research institutions. Pricing stratifies across premium, standard, and economy tiers based on resolution specifications and ISO 13485 certification status. Cost compression in the standard tier is intensifying because cloud-native AI reconstruction software displaces on-premise computational bundles. Pharmaceutical contract research organizations exhibit lowest price sensitivity due to FDA 21st Century Cures Act reimbursement eligibility, while Indian pathology laboratories face acute budget constraints.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement relationships between Japanese analytical equipment manufacturers and United States academic medical centers. Vacuum system components draw from Germany, Japan, and the United States, while high-speed laser optics sources concentrate in Japan and Germany. Single-source vulnerability in helium supply from Qatar and the United States threatens service contract economics. Distribution runs through designated core facility procurement consortia rather than individual laboratory purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the vendor base creates entry niches as consolidated procurement by multi-site health systems displaces traditional departmental autonomy and rewards specialized compliance capabilities.
For Market Incumbents: Pre-empt DESI ambient ionization encroachment by embedding AI-assisted reconstruction into existing MALDI service contracts. Acquire ISO 13485-certified component suppliers in Germany to secure vacuum system capacity. Channel control through microscopy-to-mass-spec integration partnerships with Leica distributors anchors replacement cycle visibility. For New Entrants and Emerging Players: Build out cloud-native ion image analysis platforms targeting mid-tier Indian research institutions priced out of on-premise high-performance computing. CDSCO diagnostic pathway clarity in Maharashtra and Gujarat offers the most penetrable regulatory entry point. Go-to-market leverage rests on subscription-based SaaS pricing that converts capital expenditure to operating expense. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-forward computational analysis providers over capital-heavy instrument manufacturers. Five-to-ten year viability hinges on recurring revenue attachment rates rather than replacement cycle depth. Acquisition targets should demonstrate FDA 21st Century Cures Act reimbursement traction. The signal to monitor is EU IVDR conformity acceleration for clinical mass spectrometry platforms.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Ion Image Reconstruction Platform Launch | Cloud-native penetration of mid-tier research institutions converts capital expenditure to recurring subscription revenue. |
| ISO 13485 Certification Investment | Clinical pathology laboratory access requires quality management compliance under FDA in vitro diagnostic pathways. |
| Microscopy-to-Mass-Spec Integration Partnership | Leica distribution channels anchor replacement cycle visibility for MALDI-TOF platform vendors. |
| CDSCO Diagnostic Pathway Registration | Regulatory clarity opens Maharashtra and Gujarat pathology laboratory base exceeding registered facilities. |
| Helium Supply Diversification Agreement | Qatar and United States import concentration threatens vacuum system service contract economics. |
Research Methodology
Initial hypotheses were tested against primary input from spatial omics core facility directors, clinical pathology laboratory managers, pharmaceutical toxicology group leaders, and mass spectrometry instrument procurement officers and refined through secondary validation against FDA 510(k) filings, NIH grant award databases, EU IVDR notified body guidance documents, and SEC 10-K instrument revenue disclosures. Bottom-up instrument installation tracking and top-down addressable market sizing were triangulated to anchor demand estimates.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across ionization modality, end-user type, application workflow, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating NIH spatial omics infrastructure grant trajectories and EU IVDR commercialization timeline delays. Industry-specific inputs included helium price volatility indices and DESI ambient ionization adoption curves in German academic medical centers.
Stress conditions across NIH funding continuity, EU IVDR notified body capacity, and helium supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement framework maturation and precision medicine regulatory pathway acceleration. Macroeconomic contraction, regulatory timeline extension, or breakthrough ambient ionization substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
XRF Analyzer Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Infrared Thermometers Market