
 Absorption Spectrometers Market | 2026-2036
Absorption Spectrometers Market Size, Share, and Industry Trends Forecast 2026-2036
Absorption Spectrometers Market Analysis
Research-grade spectral resolution is bifurcating the competitive landscape into precision-focused and cost-optimized tiers. Thermo Fisher Scientific leverages its North American service infrastructure to sustain long-term contracts with pharmaceutical quality control departments. Shimadzu Corporation anchors its position in Asia-Pacific academic markets through localized manufacturing and regional calibration centers. PerkinElmer differentiates by specializing in food safety applications with dedicated UV-Visible product lines for contaminant detection workflows.
Absorption spectrometers are analytical instruments that measure the quantity of light absorbed by a sample at specific wavelengths, typically operating across ultraviolet, visible, and infrared ranges with resolution thresholds reaching sub-nanometer precision. These systems serve primary industrial purposes in quantitative chemical analysis, material composition verification, and regulatory compliance testing across manufacturing and research environments. UV-Visible systems occupy the largest installed base due to their established role in pharmaceutical quality control and environmental water testing protocols. FTIR segments command premium pricing in chemical analysis applications where molecular fingerprinting demands rapid, non-destructive identification. Near Infrared platforms represent the fastest-growing category as food and beverage producers adopt at-line process analytical technology for real-time composition monitoring.
FDA 21 CFR Part 11 electronic records requirements and EMA GMP Annex 15 qualification standards shape instrument validation protocols, compelling manufacturers to embed audit-trail software and automated calibration routines in new platform releases. EPA Method 1664 and ISO 17025 accreditation frameworks further dictate sensitivity benchmarks and traceability documentation for environmental monitoring deployments. REACH compliance in Europe restricts certain optical component materials, pushing suppliers toward halogen-free detector architectures and redesigned monochromator assemblies. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP chapters, as divergent wavelength accuracy tolerances threaten to fragment instrument specification requirements across major pharmaceutical export markets.
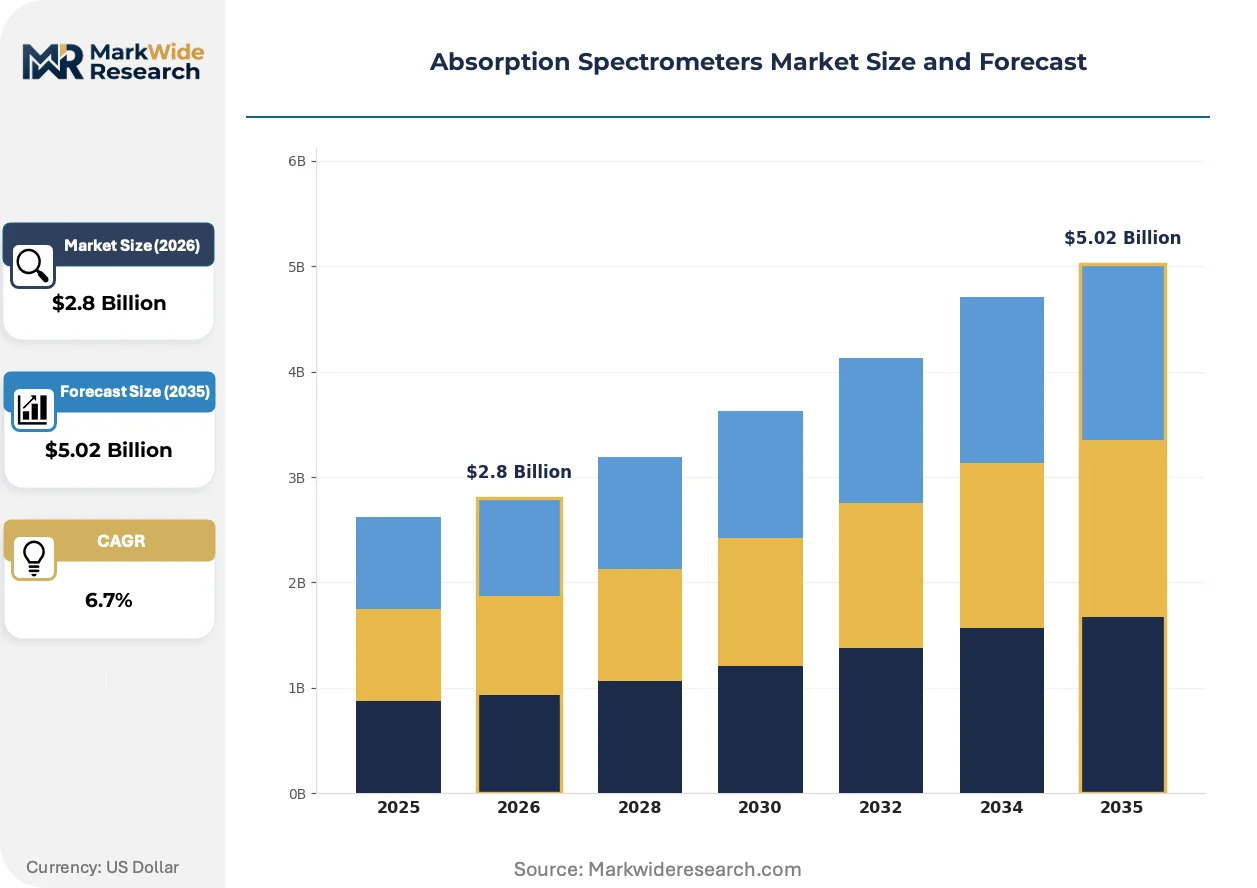
Market Dynamics
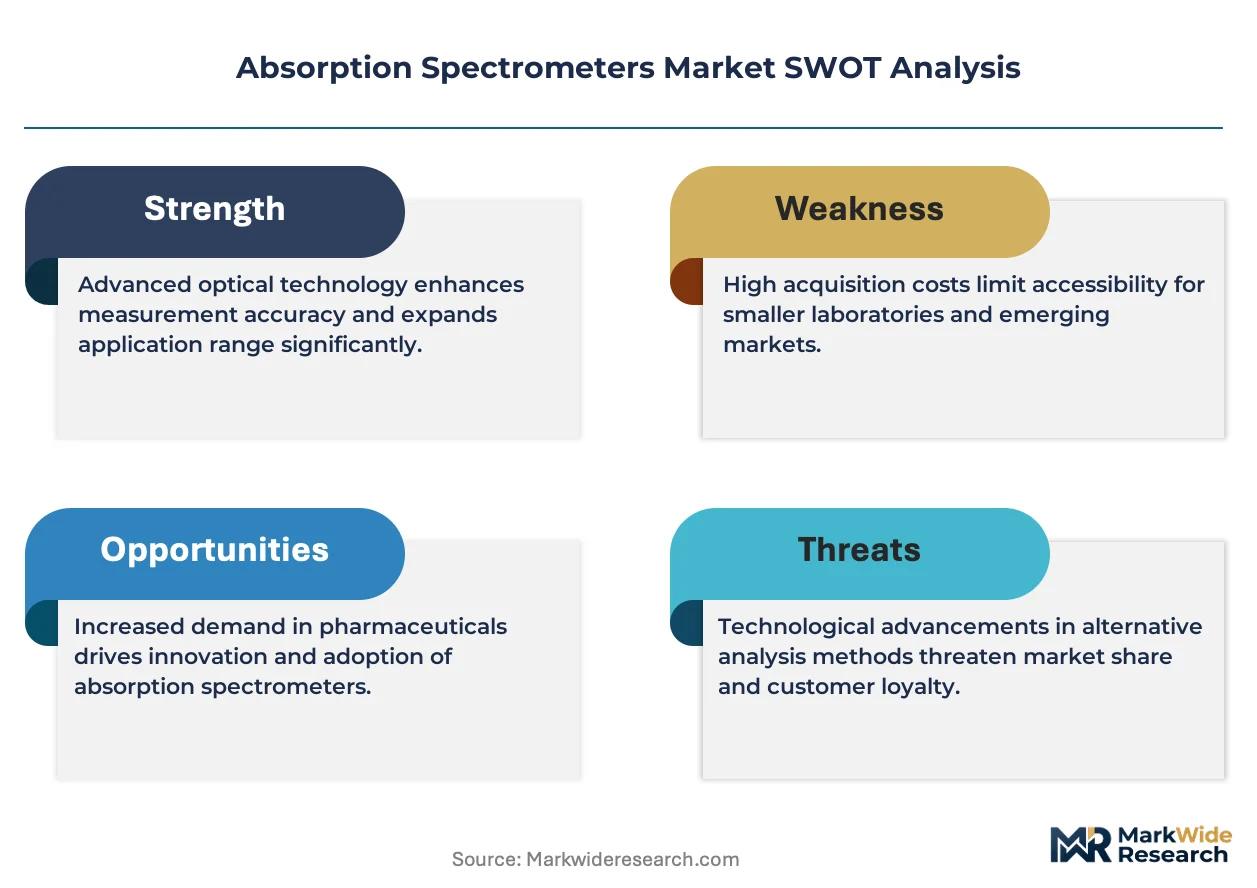
Pharmaceutical purity verification mandates under FDA 21 CFR Part 11 and EMA GMP Annex 15 are compressing replacement cycles for legacy UV-Visible and FTIR platforms, forcing manufacturers to embed audit-trail software and automated calibration routines as standard features rather than premium add-ons.
Growth Catalysts
- EMA GMP Annex 15 Qualification Standards:European pharmaceutical manufacturers must validate analytical instruments for electronic records compliance, accelerating fleet upgrades in Germany and Switzerland.
- At-line Process Analytical Technology:Food and beverage producers deploy Near Infrared platforms for real-time composition monitoring, displacing offline laboratory workflows.
- ISO 17025 Accreditation Frameworks:Environmental testing laboratories in Japan and Australia pursue certification to secure government monitoring contracts, driving sensitivity benchmark improvements.
Market Restraints
- Deuterium Lamp Supply Concentration:Three specialized manufacturers in Japan control 80% of UV-Visible source production, creating vulnerability to semiconductor material allocation disruptions.
- REACH Compliance Costs:European restrictions on halogenated optical components force complete redesigns of detector architectures and monochromator assemblies, extending R&D timelines.
- Raman Spectroscopy Substitution:Non-destructive molecular identification without sample preparation is capturing applications previously served by FTIR fingerprinting.
Strategic Opportunities
- India's CDSCO Expansion:Domestic pharmaceutical manufacturing under Production-Linked Incentive schemes requires quality control infrastructure, opening instrument deployment opportunities.
- AI-Enabled Spectral Interpretation:Machine learning algorithms trained on pharmaceutical impurity databases reduce operator training requirements and accelerate method development.
- Service Contract Unbundling:Independent calibration providers in Brazil and Mexico are capturing aftermarket revenue previously retained by original equipment manufacturers.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergent wavelength accuracy tolerances between USP, EP, and JP chapters force manufacturers to maintain multiple instrument specifications for export markets.
- Specialized Technician Scarcity:FTIR maintenance and interferometer alignment require expertise concentrated in aging workforce pools across German chemical manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorption Spectrometers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV-Visible, Near Infrared, FTIR, Circular Dichroism Application: Chemical Analysis, Environmental Monitoring, Quality Control, Food Safety End User: Pharmaceuticals, Academic Research, Food & Beverage, Environmental Agencies Technology: Optical Sensors, Wireless Transmission, Automation, Digital Readouts |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, PerkinElmer, Bruker, Aurora Biomed, Shimadzu Corporation, Analytik Jena AG, Hitachi High-Tech Corporation, GBC Scientific Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorption Spectrometers Market Emerging Trajectories
Portable and handheld absorption spectrometers are compressing the addressable market for benchtop systems while opening field-deployable applications in environmental monitoring and pharmaceutical supply chain verification.
Micro-electromechanical systems (MEMS) based Michelson interferometers are fragmenting the FTIR category into palm-sized units capable of 4 cm⁻¹ resolution. Customs inspection agencies in the Netherlands and Singapore deploy these units for rapid chemical identification at ports of entry. The technology is compressing price points for entry-level chemical analysis and enabling non-specialist operators to perform molecular fingerprinting previously requiring laboratory-trained technicians.
REACH restrictions on halogen-containing flame retardants are forcing optical bench redesigns across European-sourced instruments. Manufacturers substitute aluminum housing architectures for legacy polymer composites, adding weight but eliminating restricted substances. German environmental compliance testing laboratories face the steepest transition costs as they operate the densest installed bases of legacy platforms requiring component-level retrofitting.
Pharmaceutical quality control departments are unbundling service contracts from instrument purchases, soliciting independent calibration providers for annual qualification protocols. This pattern concentrates in North American generic drug manufacturing facilities where procurement teams prioritize operational expenditure reduction over capital bundling. Thermo Fisher Scientific and PerkinElmer respond with modular service tiers, separating software support from hardware maintenance to retain contract attach rates.
Absorption Spectrometers Market Segmentation
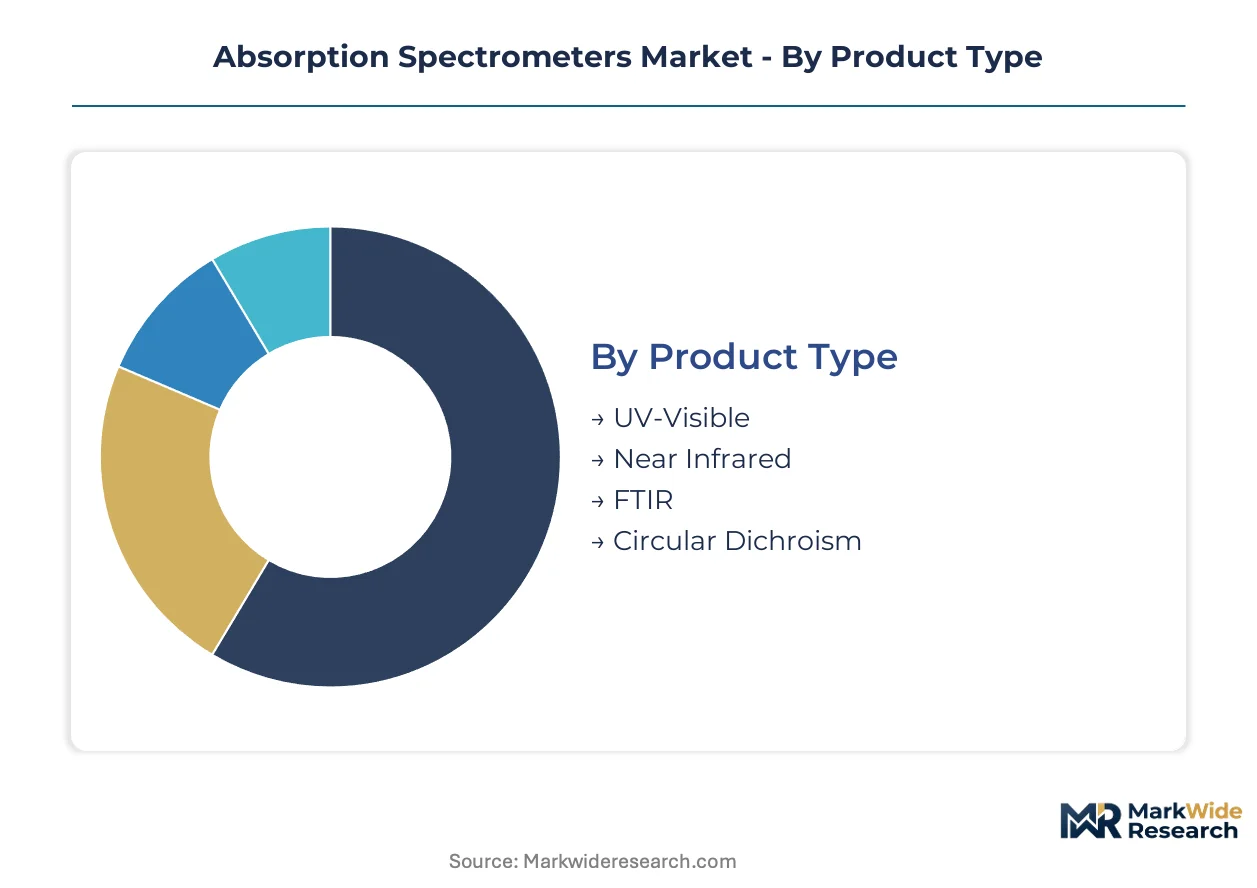
Segmentation in absorption spectrometers reveals how technology specifications map to regulatory requirements and end-use workflows. Product architecture, application protocols, and user sophistication levels create distinct procurement patterns across laboratory and industrial settings.
Product Type:
UV-Visible systems dominate domestic replacement cycles in Germany and Switzerland where pharmaceutical quality control departments face compressed validation timelines under EMA GMP Annex 15. Near Infrared platforms drive export-led demand from Netherlands and Singapore as customs agencies deploy handheld units for port-of-entry screening.
- UV-Visible:These systems operate across 190-1100 nm wavelength ranges with deuterium and tungsten-halogen source combinations. German chemical manufacturing clusters in Ludwigshafen and Leverkusen account for dense installed bases requiring audit-trail software upgrades under FDA 21 CFR Part 11 pressure.
- Near Infrared:Operating at 780-2500 nm with diffuse reflectance capabilities, these platforms enable at-line process analytical technology. Food and beverage producers in Netherlands and Singapore deploy handheld MEMS-based units for real-time composition monitoring, displacing offline laboratory workflows.
- FTIR:Fourier-transform platforms achieve sub-4 cm⁻¹ resolution through Michelson interferometry for molecular fingerprinting.
- Circular Dichroism:Specialized systems measure differential absorption of left and right circularly polarized light for chiral compound analysis.
UV-Visible holds the largest share; momentum sits with Near Infrared.
Application:
Cost tier differentiation separates premium validated systems for regulatory compliance from economy units for screening workflows. Chemical analysis commands highest specification requirements while environmental monitoring drives volume through distributed sensor networks.
- Chemical Analysis:Molecular fingerprinting applications demand sub-nanometer resolution and automated calibration routines. German REACH compliance testing laboratories require complete optical bench redesigns to eliminate halogenated components, extending replacement cycles.
- Environmental Monitoring:EPA Method 1664 and ISO 17025 accreditation frameworks dictate sensitivity benchmarks for water and air quality testing. Australian and Japanese government monitoring contracts drive demand for traceable documentation capabilities.
- Quality Control:Pharmaceutical purity verification mandates compress replacement cycles for legacy platforms.
- Food Safety:Contaminant detection workflows favor dedicated UV-Visible product lines with simplified operator interfaces.
Chemical analysis commands premium pricing; environmental monitoring expands most quickly through distributed deployment.
End User:
Customer sophistication determines service contract structures and software integration requirements. Pharmaceutical manufacturers demand validated systems with electronic records compliance while academic users prioritize modular upgrade paths.
- Pharmaceuticals:Quality control departments under FDA and EMA jurisdiction require embedded audit-trail software and automated calibration routines as standard features. North American generic drug facilities increasingly unbundle service contracts to reduce operational expenditure.
- Academic Research:Asia-Pacific universities drive demand for localized manufacturing and regional calibration centers through Shimadzu's established infrastructure.
- Food & Beverage:Producers adopt at-line process analytical technology for real-time composition monitoring.
- Environmental Agencies:Certification to ISO 17025 accreditation frameworks secures government monitoring contracts in Japan and Australia.
Pharmaceuticals anchor revenue concentration; food and beverage gains share fastest through process analytical technology adoption.
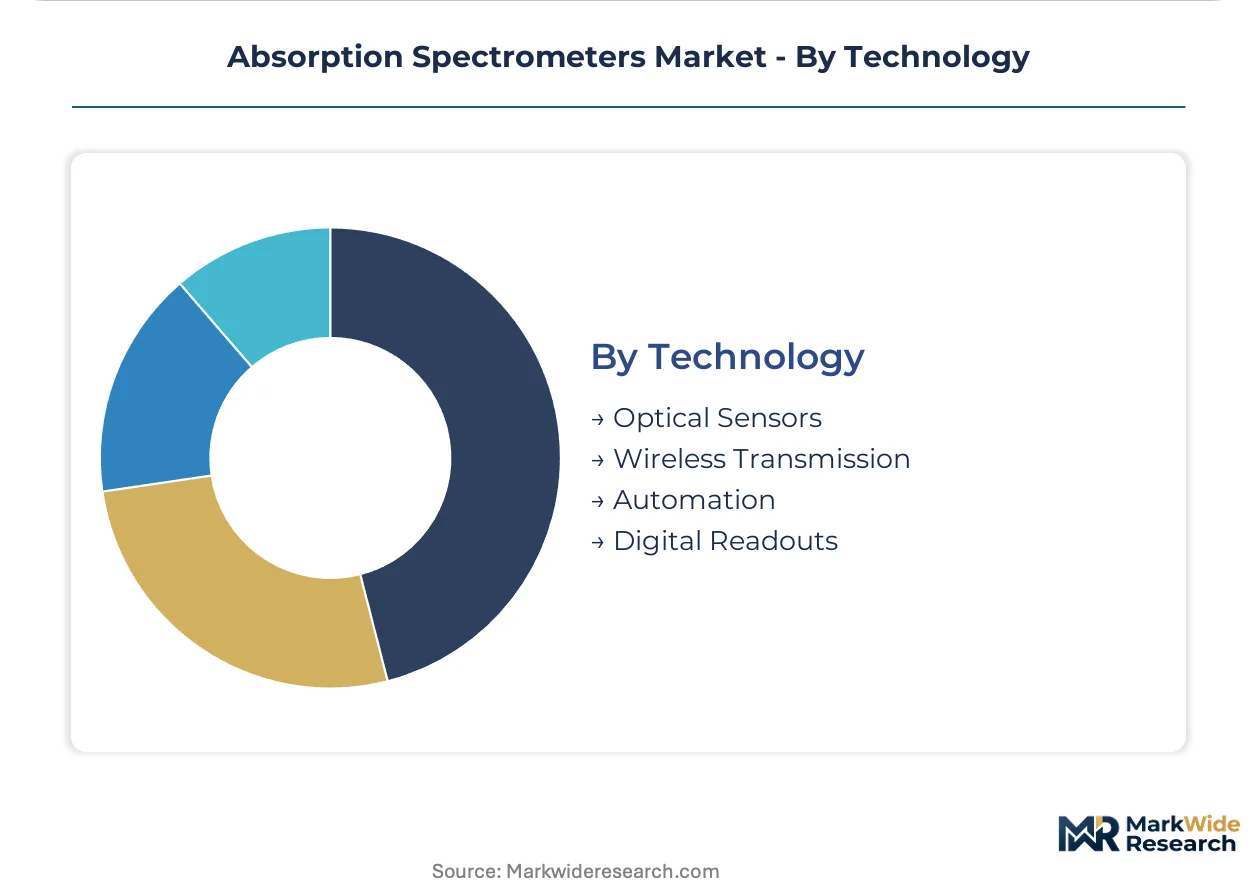
Technology:
Integration depth separates fully automated platforms from manual systems requiring operator intervention. Wireless transmission capabilities enable distributed sensor networks while optical sensor miniaturization drives handheld form factors.
- Optical Sensors:Detector architectures face redesign pressure from REACH restrictions on halogenated materials. German environmental compliance testing laboratories bear steepest transition costs from legacy polymer composite housings to aluminum alternatives.
- Wireless Transmission:Field-deployable units in environmental monitoring and pharmaceutical supply chain verification require secure data protocols. Customs inspection agencies in Netherlands and Singapore prioritize rapid chemical identification without laboratory infrastructure.
- Automation:Embedded calibration routines reduce operator training requirements and accelerate method development.
- Digital Readouts:Simplified interfaces enable non-specialist operation of portable absorption spectrometers.
Optical sensors constitute the core technology layer; wireless transmission climbs the fastest through port-of-entry deployment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German suppliers dominate critical optical component manufacturing, concentrating deuterium lamp production and precision interferometer assembly in specialized industrial corridors. This supply-side pattern shapes procurement vulnerability and replacement cycle timing across downstream markets.
United States
Generic drug manufacturers in North Carolina and New Jersey compress validation timelines under FDA 21 CFR Part 11 mandates, forcing audit-trail software retrofits on legacy UV-Visible platforms. Procurement teams increasingly unbundle service contracts to reduce operational expenditure. The Research Triangle Park cluster hosts dense pharmaceutical quality control operations requiring embedded calibration automation.
Germany
Chemical manufacturing clusters in Ludwigshafen and Leverkusen drive replacement cycles for high-resolution FTIR systems under REACH compliance pressure. EMA GMP Annex 15 qualification standards accelerate fleet upgrades for electronic records validation. Environmental compliance testing laboratories face steepest transition costs from halogenated optical component restrictions.
Japan
Three specialized manufacturers control deuterium lamp production for UV-Visible systems, creating semiconductor material allocation vulnerability. METI-supported academic research infrastructure sustains demand for localized manufacturing and regional calibration centers. The Kanto region anchors precision optical component supply chains serving Asia-Pacific instrument assembly.
Singapore
Customs inspection agencies deploy handheld MEMS-based absorption spectrometers for rapid chemical identification at port-of-entry screening operations. Food and beverage producers adopt at-line process analytical technology for real-time composition monitoring. The city-state's trade facilitation role drives demand for field-deployable units with wireless transmission capabilities.
India
Domestic pharmaceutical manufacturing under CDSCO Production-Linked Incentive schemes requires quality control infrastructure expansion. Maharashtra and Gujarat pharmaceutical corridors open instrument deployment opportunities for purity verification workflows. BIS accreditation frameworks for testing laboratories drive sensitivity benchmark improvements in environmental monitoring applications.
Absorption Spectrometers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision-focused specialists commanding premium pricing against mass-market manufacturers optimizing for replacement volume. The vendor base separates into three strategic tiers: integrated analytical instrument conglomerates with full portfolio coverage, regional specialists concentrating on localized service networks, and component-level suppliers capturing aftermarket revenue through independent calibration provision. Competitive moves center on unbundling service contracts to retain attach rates and geographic expansion through regional manufacturing licensing.
Among diversified analytical instrument conglomerates, Thermo Fisher Scientific and PerkinElmer occupy positions exemplifying the premium-tier service integration model, while Shimadzu Corporation represents the Asia-Pacific regional specialist archetype with localized manufacturing infrastructure. These three anchors demonstrate how competitive positioning stratifies across geographic coverage depth versus application specialization breadth.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| PerkinElmer |
| Bruker |
| Aurora Biomed |
| Shimadzu Corporation |
| Analytik Jena AG |
| Hitachi High-Tech Corporation |
| GBC Scientific Equipment |
| Others |
Supply Flow & Price Mechanics
Deuterium lamp manufacturing scale in Japan's specialized industrial corridors establishes minimum viable production thresholds that concentrate optical source supply among three producers, compressing price floors for UV-Visible systems while elevating procurement risk premiums for buyers seeking dual-source security.
Pricing Analysis
FDA 21 CFR Part 11 and EMA GMP Annex 15 dictate the pricing tier structure across pharmaceutical-grade absorption spectrometers, separating validated systems with embedded audit-trail software from economy screening units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling intensity. Cost compression in standard-tier FTIR platforms is intensifying because MEMS-based interferometers displace legacy Michelson architectures. Generic drug manufacturers in North America exhibit highest price sensitivity, while environmental compliance laboratories in Germany show lowest sensitivity due to REACH-mandated replacement urgency.
Supply Chain Analysis
Strait of Malacca transit underwrites component flows for Asia-Pacific instrument assembly, yet deuterium lamp production concentrates in Japan, precision interferometer manufacturing anchors in Germany, and detector substrate fabrication centers in South Korea. Raw material dependencies include semiconductor-grade silicon for MEMS fabrication, rare-earth-doped crystals for NIR sources, and halogen-free polymer composites for REACH-compliant housings. Single-source vulnerability in UV-Visible lamp supply creates exposure to semiconductor material allocation disruptions. Distribution runs through authorized distributor networks for validated pharmaceutical systems and direct OEM channels for portable field-deployable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Absorption spectrometer demand is recovering from cyclical compression as pharmaceutical capital expenditure budgets reopen under FDA and EMA compliance deadlines, with replacement cycle timing now synchronized to regulatory enforcement waves rather than organic equipment aging.
For Market Incumbents: Shield installed base revenue by embedding automated calibration routines as standard features rather than premium add-ons, neutralizing independent calibration providers in Brazil and Mexico. Accelerate backward integration into halogen-free detector architectures to preempt REACH supply disruptions. Prioritize service contract modularization to retain attach rates among North American generic drug manufacturers pursuing operational expenditure reduction.
For New Entrants and Emerging Players: Differentiate on AI-enabled spectral interpretation capabilities that reduce operator training requirements for pharmaceutical quality control departments. Target India's CDSCO Production-Linked Incentive pharmaceutical corridors where quality control infrastructure expansion outpaces established vendor presence. Pursue at-line process analytical technology deployments in food and beverage applications as the most penetrable segment displacing offline laboratory workflows.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-integrated instrument conglomerates with pharmaceutical validation expertise, suggesting long-term viability over a multi-year window rests on contractual attach rates rather than transactional hardware margins. Acquisition target archetype: regional specialists with localized calibration infrastructure in Asia-Pacific growth corridors. Signal to watch: pharmacopeial harmonization progress between USP, EP, and JP chapters as inflection indicator for specification consolidation and pricing power recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Spectral Interpretation | Machine learning algorithms trained on pharmaceutical impurity databases reduce operator training requirements and accelerate method development cycles. |
| Halogen-Free Detector Architecture | REACH-compliant optical bench redesigns eliminate restricted substances while extending R&D timelines for European-sourced instruments. |
| Service Contract Modularization | Separating software support from hardware maintenance retains contract attach rates among procurement teams prioritizing operational expenditure reduction. |
| MEMS Interferometer Miniaturization | Palm-sized FTIR units enable customs inspection agencies in Netherlands and Singapore to perform rapid chemical identification without laboratory infrastructure. |
| Regional Calibration Center Expansion | Localized manufacturing and service infrastructure captures Asia-Pacific academic demand through reduced lead times and qualification protocol familiarity. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and instrument manufacturer disclosures to establish market size and growth trajectory. Primary interviews engaged quality control directors at pharmaceutical manufacturers, environmental laboratory managers, academic research procurement officers, and aftermarket calibration service providers. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA GMP Annex 15 qualification standards, EPA Method 1664 protocols, and ISO 17025 accreditation frameworks. Bottom-up unit shipment estimates triangulate against top-down expenditure analysis across end-use segments.
Segmentation dimensions modeled include product type, application protocol, end-user sophistication tier, and technology integration depth across the projection horizon. Growth rate derivation incorporated replacement cycle timing under regulatory compliance pressure, at-line process analytical technology adoption curves in food and beverage manufacturing, and customs inspection agency deployment schedules for handheld units. Industry-specific forecast inputs include deuterium lamp supply capacity constraints and REACH restriction implementation timelines for halogenated optical components.
Material uncertainties — semiconductor material allocation disruptions, pharmacopeial harmonization delays, and Raman spectroscopy substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement intensity and capital expenditure budget availability in pharmaceutical manufacturing. Practitioners should keep alternative scenarios live as EMA GMP Annex 15 qualification deadlines and FDA 21 CFR Part 11 audit priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
Headspace Gas Analyzers Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
Europe Mass Spectroscopy Market