
 Next Generation Mass Spectrometer Market | 2026-2036
Next Generation Mass Spectrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Mass Spectrometer Market Foresight
North American precision instrument manufacturers is recalibrating production schedules to address backlogs in high-resolution systems. Thermo Fisher Scientific leverages its captive supply of Orbitrap components to secure long-term contracts with academic institutions. Shimadzu Corporation anchors its position in Asia through manufacturing scale advantages in triple-quadrupole platforms.
Next generation mass spectrometers are analytical instruments that ionize chemical species and sort the resulting ions by mass-to-charge ratio, achieving resolution exceeding 100,000 FWHM in Orbitrap configurations and detection limits in the femtogram range for proteomic applications. Their primary purpose is to enable molecular identification and quantification in complex biological, environmental, and synthetic matrices. Quadrupole systems dominate installed base economics due to lower capital thresholds and standardized service protocols, while Orbitrap configurations capture disproportionate margin pools from pharmaceutical analysis contracts. Liquid Chromatography-Mass Spectrometry technology leads technology adoption in clinical research settings where sample throughput requirements are most stringent.
FDA bioanalytical method validation guidelines and EPA testing protocols for environmental contaminants shape instrument specifications and software compliance requirements in the United States, while REACH chemical registration rules in Europe and NMPA pharmaceutical quality standards in China create parallel certification demands. ISO 17025 laboratory accreditation requirements further constrain vendor qualification pathways. Stakeholders must monitor how regulatory convergence on data integrity standards reshapes competitive barriers for instrument suppliers.
Market Dynamics
Pharmaceutical contract research organizations are consolidating instrument procurement around high-resolution platforms capable of meeting tightened FDA bioanalytical accuracy thresholds, compressing vendor qualification timelines and reshaping competitive positioning among precision instrument suppliers.
Growth Catalysts
- EMA bioanalytical guideline harmonization:European alignment with FDA accuracy standards creates cross-Atlantic certification efficiency for instrument vendors, reducing duplicate validation costs for pharmaceutical clients operating in both jurisdictions.
- Proteomics sample complexity:Biopharma pipelines generate femtogram-scale detection requirements that quadrupole systems cannot satisfy, forcing upgrade cycles toward Orbitrap configurations in clinical research settings.
- China NMPA pharmaceutical quality enforcement:Domestic manufacturers face mandatory high-resolution testing for biologics registration, generating localized demand for imported precision instruments despite tariff friction.
Market Restraints
- Superconductor magnet supply concentration:Niobium-titanium wire production concentrates among three Japanese and German suppliers, exposing Orbitrap manufacturers to input cost volatility and extended lead times.
- ISO 17025 laboratory accreditation timelines:Certification cycles stretching 18-24 months delay revenue recognition for instrument vendors and extend customer qualification pipelines.
- Quadrupole platform longevity:Existing installed bases in environmental testing laboratories satisfy EPA protocol minimums without replacement, suppressing upgrade demand in mature application segments.
Strategic Opportunities
- Cell and gene therapy quality control:Viral vector characterization requires mass spectrometry platforms with resolution exceeding 100,000 FWHM, opening specialized application white space beyond traditional small-molecule analysis.
- India CDSCO biologics pathway expansion:Regulatory streamlining for biosimilar approvals creates instrument demand among domestic contract manufacturers previously excluded from high-resolution testing capabilities.
- Artificial intelligence spectral interpretation:Machine learning deconvolution of complex proteomic data is converging with hardware advances, enabling automated quantification that reduces specialist labor requirements.
Industry Challenges
- Orbitrap field service engineer scarcity:Superconducting magnet maintenance requires cryogenic system certification that fewer than 200 technicians globally currently hold, constraining vendor expansion capacity.
- Legacy data system migration:Pharmaceutical laboratories face 12-18 month integration timelines when replacing quadrupole platforms with high-resolution systems, delaying contract execution and revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Mass Spectrometer Market |
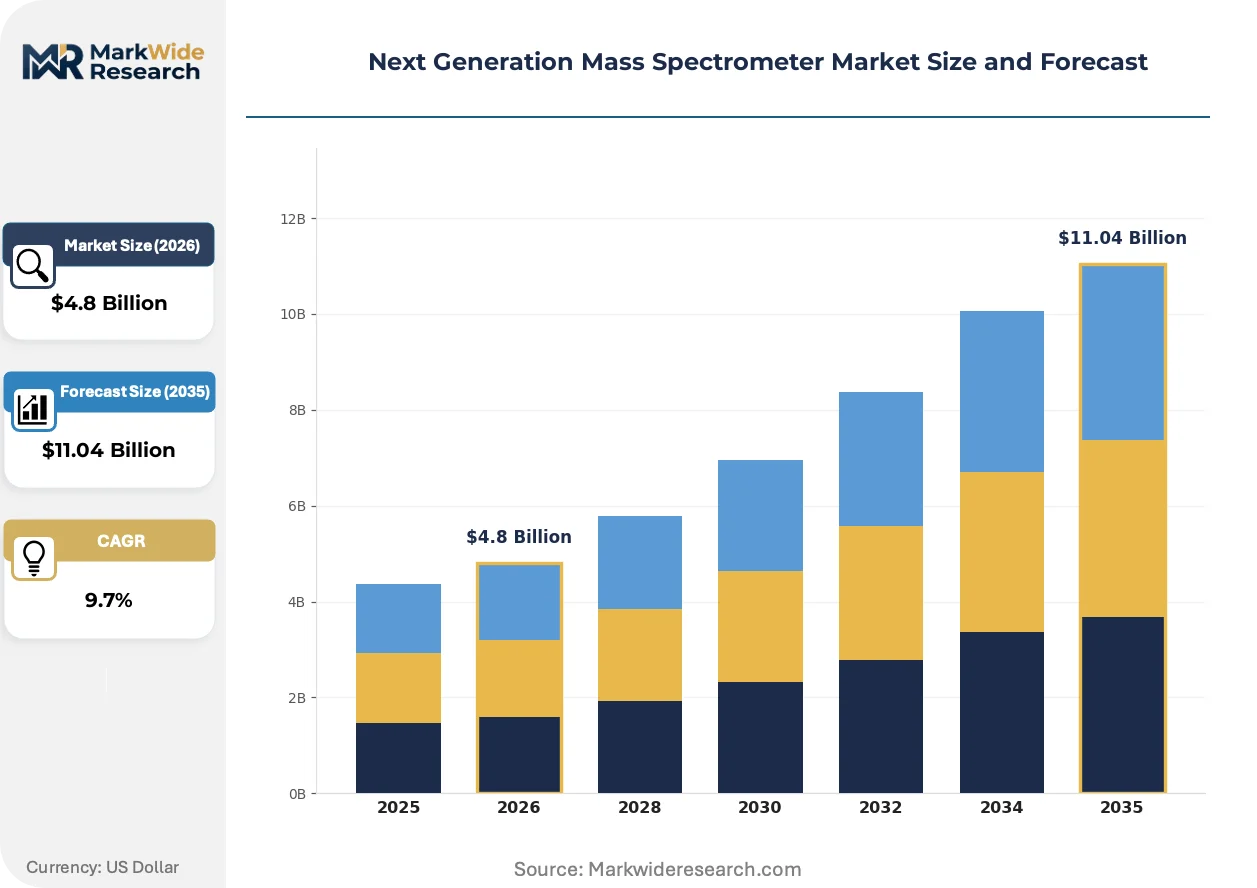
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadrupole, Time-of-Flight, Orbitrap, Ion Trap Technology: Gas Chromatography-Mass Spectrometry, Liquid Chromatography-Mass Spectrometry, Direct Analysis in Real Time, Matrix-Assisted Laser Desorption/Ionization Application: Clinical Research, Environmental Testing, Food Safety, Pharmaceutical Analysis End User: Academic Institutions, Contract Research Organizations, Pharmaceutical Companies, Hospitals |
| Companies Covered | Thermo Fisher Scientific, Inc., Shimadzu Corporation, Waters Corporation, Bruker Corporation, Agilent Technologies, Inc., Danaher Corporation, PerkinElmer, Inc., Rigaku Corporation, JEOL Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Mass Spectrometer Market Shifts & Advancements
Artificial intelligence spectral deconvolution and miniaturized ion source architectures are compressing the performance gap between benchtop and floor-standing systems, enabling new deployment models in distributed testing environments.
Native ion mobility spectrometry is converging with high-resolution mass detection to enable structural characterization of intact protein complexes without denaturation. Biopharma quality control laboratories in Switzerland and Massachusetts are adopting these configurations for monoclonal antibody aggregate analysis. The technology is converging with automated sample preparation robotics, reducing per-analysis labor hours by half in high-throughput screening operations.
REACH chemical registration requirements in Europe now mandate non-targeted screening for unknown substances in consumer products, forcing environmental testing laboratories to acquire high-resolution platforms previously considered unnecessary for compliance work. The regulation expands addressable instrument demand beyond pharmaceutical verticals into industrial chemical sectors. German and French testing consortia are consolidating procurement to secure volume pricing on Orbitrap configurations.
Service contract unbundling is accelerating as academic institutions with internal engineering capabilities reject comprehensive maintenance agreements in favor of parts-only coverage and remote diagnostic subscriptions. University core facilities in California and Bavaria now represent the leading edge of this procurement model shift. The pattern is most visible in United States research markets where endowment pressures constrain operational budgets.
Next Generation Mass Spectrometer Market Segmentation
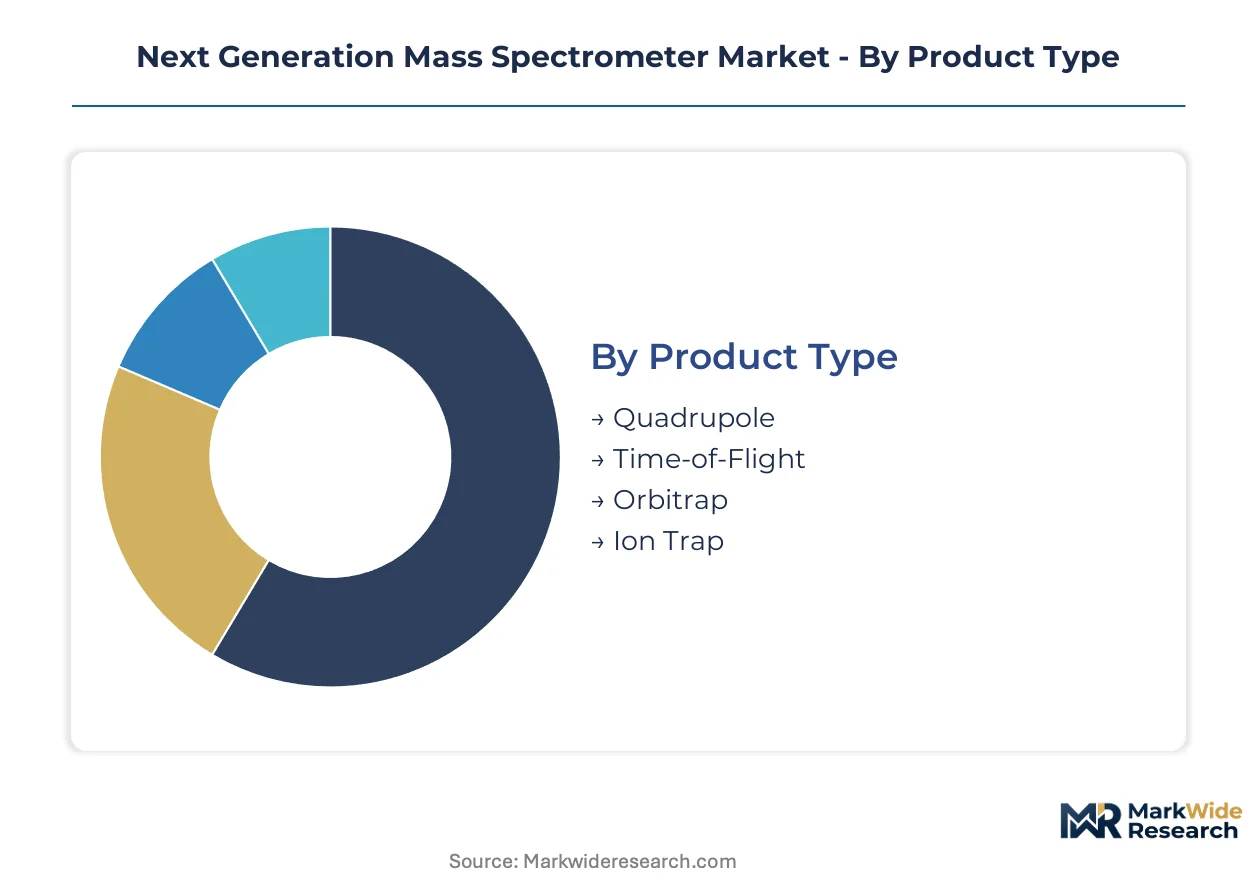
Mass spectrometer procurement patterns diverge sharply across technical specifications, analytical workflows, and compliance requirements. Understanding these segment boundaries reveals where vendor specialization creates pricing power versus where standardization erodes margins.
Product Type:
Standardization dominates at the quadrupole tier while Orbitrap configurations demand extensive customization for superconducting magnet integration and cryogenic system architecture.
- Quadrupole:Four-rod mass filter architecture using radio-frequency electric fields to isolate ions by mass-to-charge ratio. Pharmaceutical quality control laboratories in Germany and the United States deploy these systems for routine bioanalytical screening where FDA method validation requirements prioritize reproducibility over resolution. Lower capital thresholds and standardized service protocols sustain installed base economics despite resolution limitations.
- Orbitrap:Electrostatic ion trap achieving resolution exceeding 100,000 FWHM through orbital frequency mass measurement. Biopharma pipelines in Switzerland and Massachusetts drive femtogram-scale detection requirements that force upgrade cycles from legacy platforms. Superconductor magnet supply concentration among Japanese and German wire manufacturers constrains production scaling.
- Time-of-Flight:Pulsed ion acceleration with drift tube separation enables rapid full-spectrum acquisition for metabolomic profiling.
- Ion Trap:Three-dimensional quadrupole field configuration supports multi-stage fragmentation for structural elucidation in academic research settings.
Most installed capacity flows through Quadrupole systems. Expansion is steepest in Orbitrap configurations.
Technology:
Capital intensity and consumables revenue potential separate chromatography-coupled platforms from ambient ionization methods.
- Liquid Chromatography-Mass Spectrometry:Reversed-phase separation interfaced with electrospray ionization dominates clinical research throughput requirements. Contract research organizations in the United States consolidate procurement around these platforms to meet tightened FDA bioanalytical accuracy thresholds. Automated sample preparation robotics integration reduces per-analysis labor hours by half in high-throughput screening operations.
- Gas Chromatography-Mass Spectrometry:Volatile and semi-volatile compound analysis via electron impact ionization serves environmental testing laboratories satisfying EPA protocol minimums. German and French testing consortia consolidate procurement to secure volume pricing on high-resolution configurations for REACH chemical registration compliance.
- Matrix-Assisted Laser Desorption/Ionization:Pulsed laser desorption from co-crystallized matrix enables intact protein and polymer analysis with minimal fragmentation.
- Direct Analysis in Real Time:Ambient ionization without chromatographic separation supports rapid screening applications with reduced sample preparation overhead.
Revenue concentration clusters in Liquid Chromatography-Mass Spectrometry. Direct Analysis in Real Time is gaining share fastest in field-deployable applications.
Application:
Regulatory stringency and sample complexity create divergent performance requirements across vertical markets.
- Pharmaceutical Analysis:Bioanalytical method validation for small molecules and biologics demands resolution exceeding 100,000 FWHM for impurity profiling. China's NMPA pharmaceutical quality enforcement mandates high-resolution testing for biologics registration, generating localized demand for imported precision instruments. Viral vector characterization for cell and gene therapy quality control opens specialized application white space beyond traditional small-molecule analysis.
- Clinical Research:Proteomic sample complexity drives femtogram-scale detection requirements in biomarker discovery workflows. Academic institutions in California and Bavaria reject comprehensive maintenance agreements in favor of parts-only coverage and remote diagnostic subscriptions under endowment pressure.
- Environmental Testing:EPA testing protocols for contaminants and REACH non-targeted screening mandates force laboratory upgrades to high-resolution platforms.
- Food Safety:Pesticide residue and veterinary drug monitoring requires robust quantitative performance at trace concentration levels.
Margin pools concentrate in Pharmaceutical Analysis. Clinical Research shows the steepest expansion trajectory as biopharma pipelines mature.
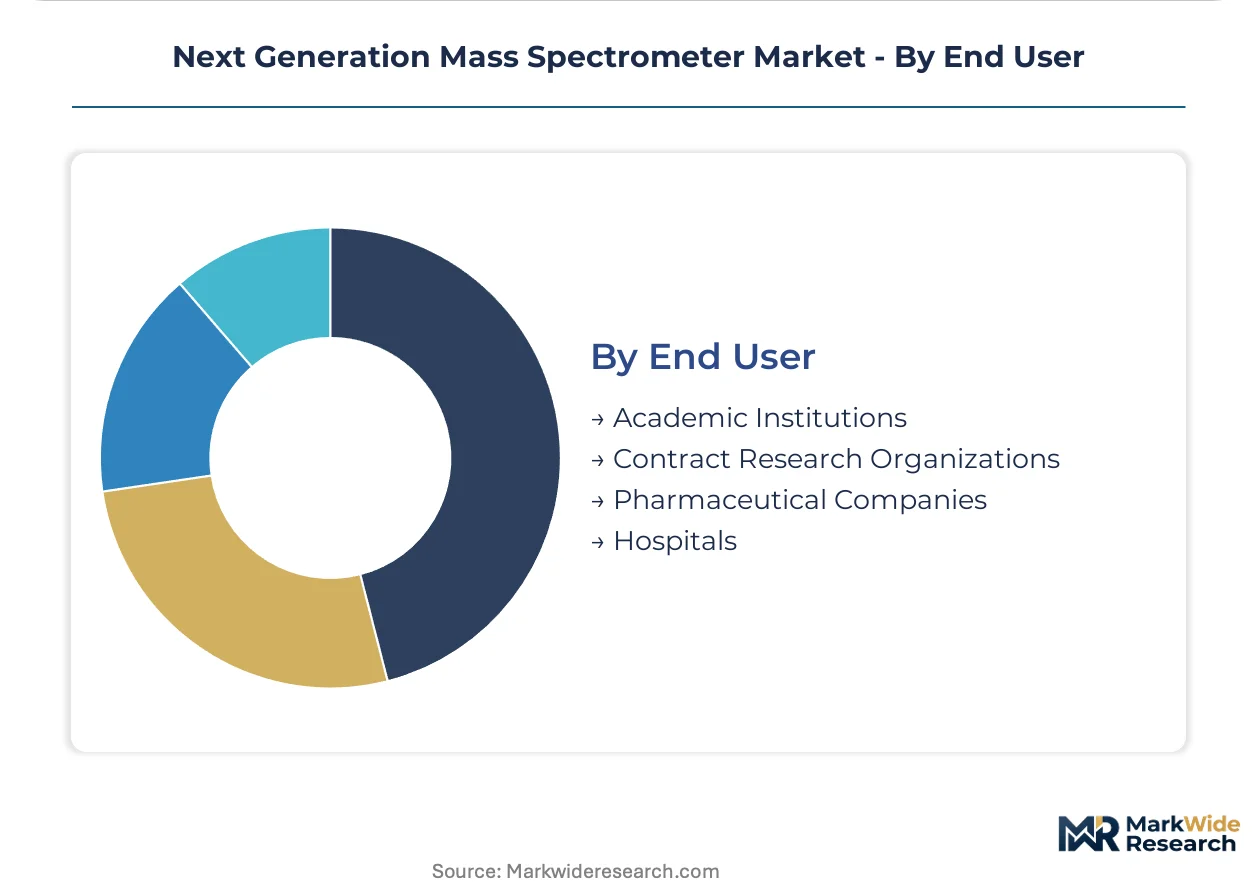
End User:
Procurement sophistication and service contract negotiating leverage separate institutional categories.
- Contract Research Organizations:Consolidated instrument procurement around high-resolution platforms compresses vendor qualification timelines. CROs operating across FDA and EMA jurisdictions benefit from European alignment with FDA accuracy standards that reduces duplicate validation costs.
- Academic Institutions:Internal engineering capabilities enable service contract unbundling and remote diagnostic subscription models. University core facilities represent the leading edge of procurement model shift away from comprehensive maintenance agreements.
- Pharmaceutical Companies:In-house bioanalytical laboratories face 12-18 month integration timelines when replacing quadrupole platforms with high-resolution systems.
- Hospitals:Clinical diagnostic applications require regulatory clearance pathways that constrain platform selection to pre-validated configurations.
Contract Research Organizations command the largest aggregate procurement volume. Academic Institutions are expanding fastest in ambient ionization platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as vendors migrate assembly to jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between FDA-aligned and emerging regulatory regimes are accelerating regional specialization in instrument manufacturing.
United States
FDA bioanalytical method validation guidelines tighten accuracy thresholds for pharmaceutical contract research organizations. Academic core facilities in California and Massachusetts reject comprehensive maintenance agreements under endowment pressure. Greater Boston biopharma clusters drive femtogram-scale detection requirements for proteomic applications.
Germany
REACH chemical registration mandates non-targeted screening for unknown substances in consumer products. German testing consortia consolidate procurement to secure volume pricing on high-resolution configurations. Bavarian university engineering capabilities enable service contract unbundling and remote diagnostic adoption.
China
NMPA pharmaceutical quality enforcement mandates high-resolution testing for biologics registration among domestic manufacturers. Tariff friction complicates instrument importation despite localized demand expansion. Yangtze River Delta contract manufacturers face mandatory upgrades for biosimilar production compliance.
Switzerland
Swissmedic standards for biologics quality control exceed baseline EMA requirements. Basel-area pharmaceutical headquarters concentrate viral vector characterization demand. Geneva and Zurich academic medical centers adopt native ion mobility configurations for monoclonal antibody aggregate analysis.
Japan
PMDA alignment with FDA bioanalytical guidelines reduces duplicate validation costs for multinational pharmaceutical clients. Superconductor magnet supply concentrates among domestic niobium-titanium wire manufacturers. Tokyo and Osaka metropolitan areas anchor precision instrument service engineer training pipelines.
Next Generation Mass Spectrometer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ambient ionization and artificial intelligence spectral interpretation. The vendor base stratifies between scale-driven quadrupole manufacturers and specialized Orbitrap configuration providers. Three archetypes dominate: diversified life science conglomerates with captive component supply, precision instrument specialists with cryogenic system expertise, and chromatography-coupled platform integrators. Competitive moves concentrate on strategic partnerships for artificial intelligence software integration and geographic expansion through localized service networks.
Among diversified life science conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven archetypes with integrated supply chain control. Shimadzu Corporation occupies a position within the precision instrument specialist tier. Waters Corporation represents the chromatography-coupled platform integrator archetype. These three anchors demonstrate how vendor qualification timelines compress around high-resolution capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Shimadzu Corporation |
| Waters Corporation |
| Bruker Corporation |
| Agilent Technologies, Inc. |
| Danaher Corporation |
| PerkinElmer, Inc. |
| Rigaku Corporation |
| JEOL Ltd. |
| Others |
Supply & Pricing Matrix
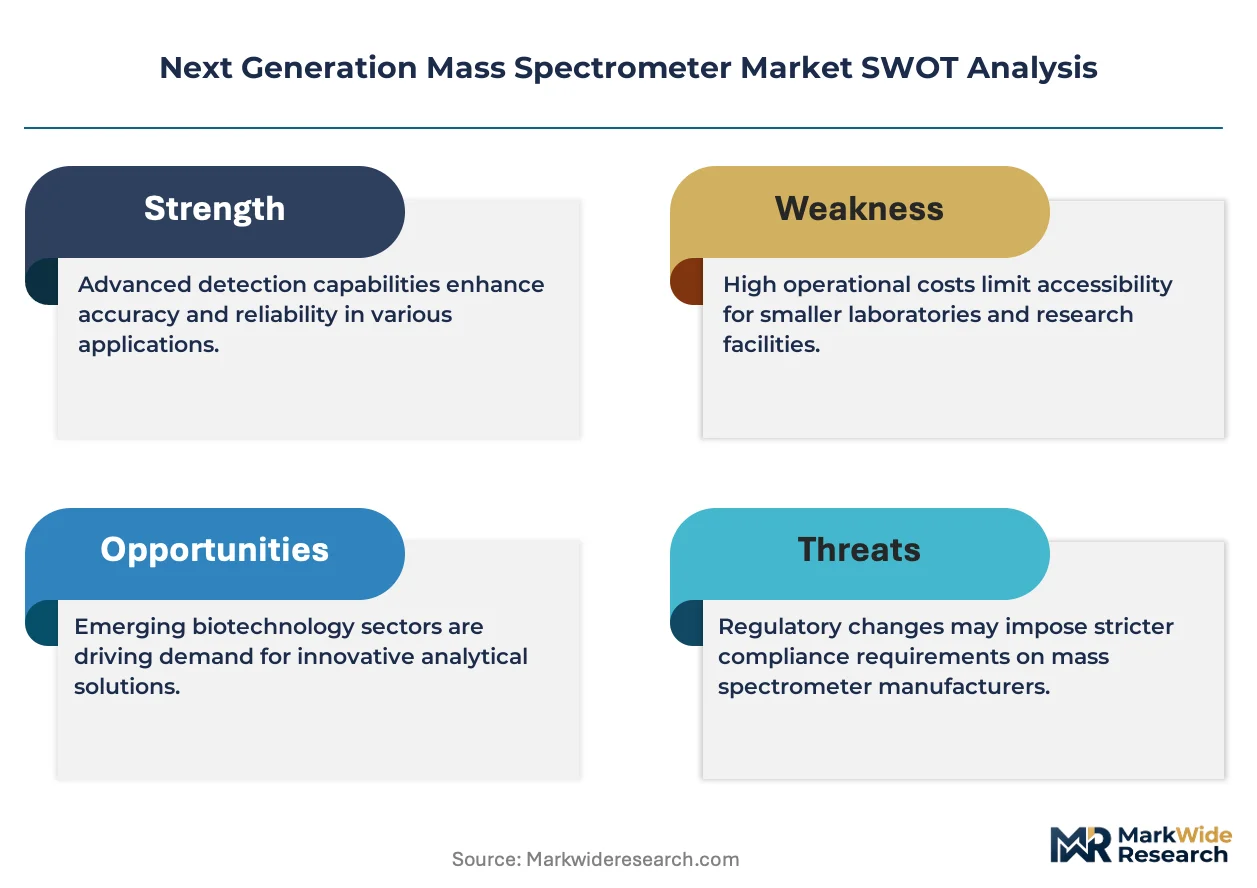
Niobium-titanium wire costs cascade through Orbitrap system pricing tiers, with superconductor magnet feedstock originating from Japanese and German specialty metal producers before accumulating cryogenic engineering margins at precision instrument assemblers in the United States and Switzerland. Pharmaceutical contract research organizations absorb premium positioning for femtogram-scale detection capabilities while academic institutions in California and Bavaria negotiate stripped-down service contracts that compress vendor margin pools.
Pricing Analysis
Distributor margins compress most aggressively in quadrupole platform segments where standardized service protocols enable procurement consolidation by German and United States environmental testing consortia. Three-tier pricing structure across premium, standard, and economy levels separates Orbitrap configurations with superconducting magnet integration from benchtop quadrupole systems and refurbished legacy installations. Cost compression in standard-tier quadrupole segments is intensifying because REACH-mandated laboratory upgrades force price competition among vendors chasing finite environmental testing budgets. Academic institutions exhibit highest price sensitivity, rejecting comprehensive maintenance agreements for parts-only coverage, while cell and gene therapy quality control laboratories demonstrate lowest sensitivity given viral vector characterization requirements.
Supply Chain Analysis
Superconductor magnet supply rests on niobium-titanium wire production concentrated among three Japanese and German suppliers, with cryogenic system architecture assembly centering on United States and Swiss precision manufacturing facilities. Raw material dependencies span rare earth element processing for ion source components, specialized ceramic substrates for detector arrays, and high-purity gas supplies for mass spectrometry consumables. Single-source vulnerability in superconducting wire production exposes Orbitrap manufacturers to input cost volatility and extended qualification timelines. Distribution runs through direct OEM relationships with pharmaceutical companies and contract research organizations, supplemented by specialized life science distributors serving academic core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The next generation mass spectrometer market represents a late-cycle quality story as biopharma pipelines force upgrade cycles toward Orbitrap configurations capable of femtogram-scale detection. FDA and EMA bioanalytical guideline harmonization redirects procurement toward high-resolution platforms that satisfy tightened accuracy thresholds across both jurisdictions.
For Market Incumbents: Deepen captive supply control over superconducting magnet components to defend against niobium-titanium wire production bottlenecks that constrain Orbitrap scaling. Expand cryogenic system certification training pipelines in Tokyo and Osaka metropolitan areas to address field service engineer scarcity that limits installation capacity. Lock long-term service contracts with pharmaceutical contract research organizations before academic procurement model shifts strip recurring revenue streams. For New Entrants and Emerging Players: Remote diagnostic subscription platforms offer the lowest-friction entry path into academic core facilities in California and Bavaria that have already rejected comprehensive maintenance agreements. Target India CDSCO biologics pathway expansion among domestic contract manufacturers previously excluded from high-resolution testing capabilities. Pursue artificial intelligence spectral interpretation partnerships that reduce specialist labor requirements and differentiate against established hardware-centric vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where cryogenic system expertise concentrates among fewer than 200 globally certified technicians, creating scarcity value for precision instrument specialists with established training pipelines. Five-to-ten year viability favors vendors with backward integration into superconducting magnet supply and software companion development for automated spectral deconvolution. Monitor NMPA pharmaceutical quality enforcement intensity in China as inflection indicator for localized demand expansion despite tariff friction.| Strategic Initiative | Industry Significance |
|---|---|
| Artificial Intelligence Spectral Integration | Machine learning deconvolution reduces specialist labor requirements in proteomic data analysis workflows. |
| Cryogenic System Certification Expansion | Field service engineer training pipelines in Japan address scarcity constraining Orbitrap installation capacity. |
| Academic Procurement Model Adaptation | Remote diagnostic subscriptions align with university core facility rejection of comprehensive maintenance agreements. |
| India CDSCO Biologics Pathway Entry | Regulatory streamlining for biosimilar approvals creates instrument demand among domestic contract manufacturers. |
| Superconducting Magnet Supply Security | Captive niobium-titanium wire sourcing defends against production bottlenecks from Japanese and German suppliers. |
Research Methodology
Direct dialogue with pharmaceutical bioanalytical laboratory directors, contract research organization procurement leads, academic core facility managers, and precision instrument field service engineers grounded qualitative findings in operational reality. Secondary validation drew from FDA bioanalytical method validation guideline documents, EMA regulatory submissions, EPA testing protocol publications, and ISO 17025 accreditation records. Bottom-up instrument shipment tracking and top-down pharmaceutical R&D expenditure analysis enabled cross-verification of demand estimates across the analysis window.
Top-down pharmaceutical pipeline analysis and bottom-up vendor shipment data converged in a segmented modeling framework spanning product type, technology coupling, application vertical, and end-user procurement sophistication. CAGRs were derived from regression analysis against biologics registration volumes, environmental testing mandate expansion, and academic research funding trajectories. Cryogenic system installation capacity constraints and superconducting magnet lead time assumptions shaped supply-side boundary conditions throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for ambient ionization miniaturization would alter the outlook if benchtop performance compression accelerates beyond current trajectories. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, tariff regime stability, and superconductor magnet supply continuity. A small set of named triggers warrants ongoing watch: NMPA biologics quality mandate expansion, REACH non-targeted screening enforcement depth, and artificial intelligence spectral interpretation regulatory acceptance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Array Instruments Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
Global UV Spectroscopy Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Disintegration Analyzer Market