
 Tourniquet Cuffs Market | 2026-2036
Tourniquet Cuffs Market Size, Share, and Industry Trends Forecast 2026-2036
Tourniquet Cuffs Market Analytics
Emergency medical services are redrawing procurement priorities across the tourniquet cuffs landscape. Stryker Corporation leverages its orthopedic device distribution network to sustain hospital channel dominance in North America. Zimmer Biomet Holdings Inc. anchors its position through integrated surgical suite offerings that bundle pneumatic cuff systems with arthroscopy platforms. VBM Medizintechnik GmbH specializes in precision-engineered rigid cuffs for German and Austrian trauma centers.
Tourniquet cuffs are inflatable or elastic constriction devices, typically manufactured from nylon-reinforced rubber bladders with neoprene contact surfaces, designed to temporarily occlude arterial blood flow during limb surgery or hemorrhage control. Pneumatic cuffs dominate the product type landscape due to their pressure precision and compatibility with automated inflation systems, while digital cuffs represent the fastest-growing segment as microprocessor-controlled pressure feedback reduces nerve injury risk. Hospitals capture the largest end-user value pool, though military units command premium pricing for battlefield-hardened portable configurations.
The FDA regulates surgical tourniquets as Class II medical devices under 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates clinical evidence for pneumatic systems sold under CE marking. ISO 13485 quality management certification shapes supplier qualification criteria for hospital procurement committees. Stakeholders must monitor evolving pressure-safety thresholds in international standards and calibrate R&D roadmaps against regional reimbursement timelines.
Market Dynamics
Pneumatic-to-digital migration is compressing replacement cycles across hospital systems, as microprocessor-controlled pressure feedback systems displace legacy mechanical gauges in trauma and surgical suites.
Growth Catalysts
- EU Medical Device Regulation (MDR) clinical evidence mandates:The MDR's tightened requirements for pneumatic tourniquet CE marking are accelerating hospital upgrades to digitally-verified systems that demonstrate superior nerve protection profiles.
- Military trauma units:Battlefield-hardened portable configurations command premium procurement budgets as defense medical services prioritize rapid hemorrhage control capabilities.
- Silicone-bladder materials:Advanced elastomer formulations with enhanced biocompatibility are extending cuff lifecycles and reducing latex-allergy complications in surgical environments.
Market Restraints
- Specialized polymer supply concentration:Medical-grade neoprene and nylon-reinforced rubber bladder production clusters in East Asian chemical processing zones, creating input vulnerability.
- FDA 510(k) pathway friction:Pre-market notification requirements for Class II surgical tourniquet devices impose documentation burdens that delay smaller manufacturer market entry.
- Manual elastic band substitutes:Low-cost windlass tourniquets retain dominant share in civilian first-responder kits, limiting pneumatic system penetration in price-sensitive emergency segments.
Strategic Opportunities
- India's surgical infrastructure expansion:Government hospital modernization programs and medical tourism hub development are creating demand for mid-tier pneumatic systems with localized service support.
- Integrated surgical suite ecosystems:Arthroscopy platform OEMs are bundling pressure-controlled cuff systems with visualization equipment, opening channel access for subsystem specialists.
- ISO 13485 certification acceleration:Quality management standard adoption is becoming a procurement gatekeeper, rewarding suppliers with established certification infrastructure.
Industry Challenges
- Biomedical engineering talent scarcity:Pressure-control algorithm development and clinical validation expertise concentrates in established orthopedic device hubs, constraining R&D scaling.
- Legacy pneumatic system integration:Hospital IT departments face complexity connecting digital cuff interfaces with existing anesthesia information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourniquet Cuffs Market |
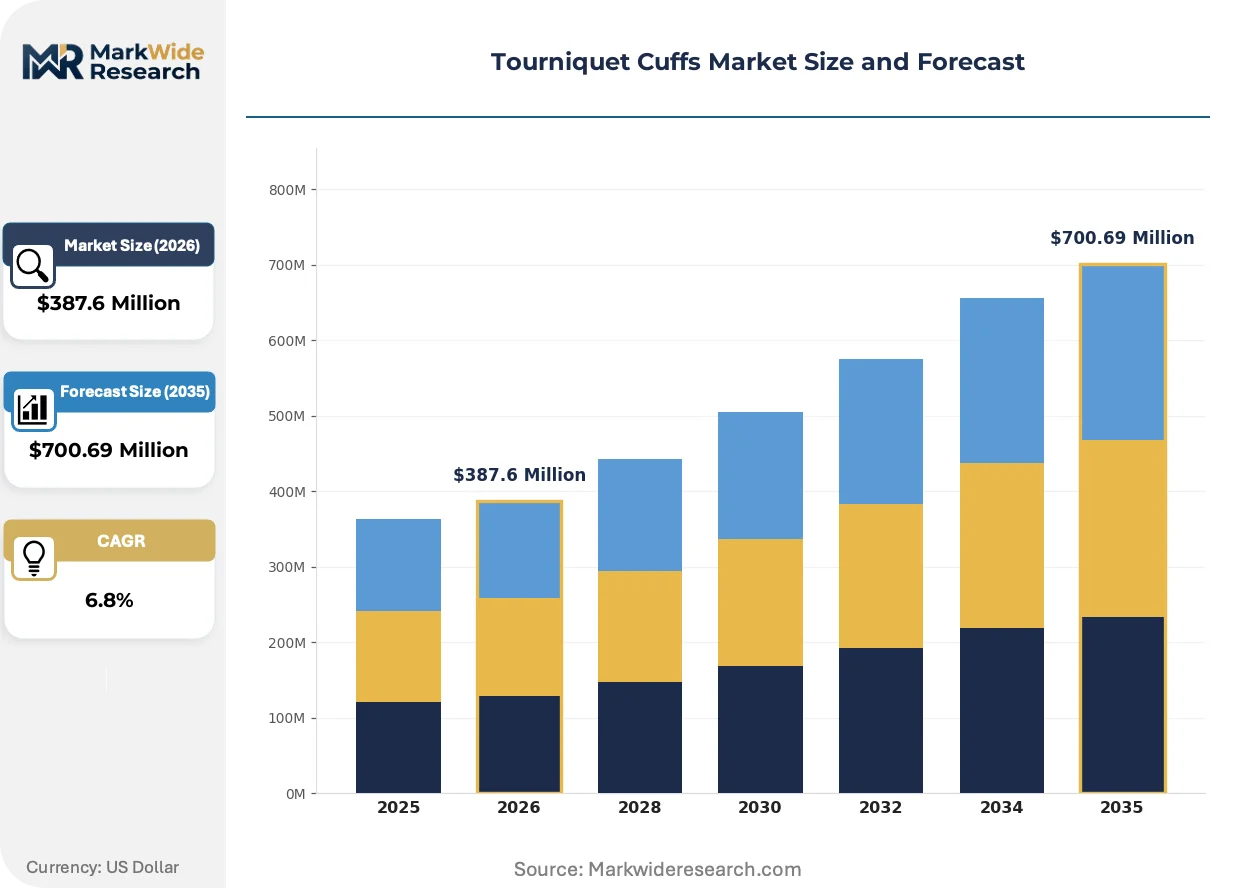
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Cuffs, Pneumatic Cuffs, Rigid Cuffs, Digital Cuffs End User: Hospitals, Emergency Medical Services, Military Units, Sports Teams Material: Rubber, Nylon, Polyester, Neoprene Delivery Mode: Manual, Automated, Portable, Integrated |
| Companies Covered | VBM Medizintechnik GmbH, AneticAid Ltd, Stryker Corporation, SourceMark Medical, Hammarplast Medical AB, Zimmer Biomet Holdings Inc., Ulrich Medical, OHK Medical Devices, Delfi Medical Innovations Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourniquet Cuffs Market Evolving Landscape
Sensor-embedded pressure monitoring is compressing the gap between surgical precision and patient safety, while regulatory harmonization efforts and procurement centralization are restructuring how tourniquet systems reach end-users.
Microelectromechanical pressure transducers are miniaturizing within cuff bladder assemblies to enable real-time tissue pressure mapping. Orthopedic surgical suites in Germany and Japan are piloting these systems to reduce tourniquet-related nerve injuries. The technology is miniaturizing hardware footprints while expanding data capture capabilities for post-operative liability documentation.
CE marking transition deadlines under the EU MDR are forcing pneumatic tourniquet manufacturers to generate clinical performance evidence previously exempt under the Medical Device Directive. German notified bodies are processing backlog delays that extend certification timelines by 12-18 months. Mid-sized suppliers are responding by consolidating product portfolios to focus resources on highest-margin platform configurations.
Hospital procurement committees are consolidating supplier relationships around full-suite vendors capable of delivering pressure devices, maintenance contracts, and disposable sleeve components through single-source agreements. Group purchasing organizations in the United States are displacing independent distributor networks for high-volume surgical consumables. This concentration is most visible in integrated delivery networks across Texas and California, where standardization mandates override individual surgeon equipment preferences.
Tourniquet Cuffs Market Segmentation
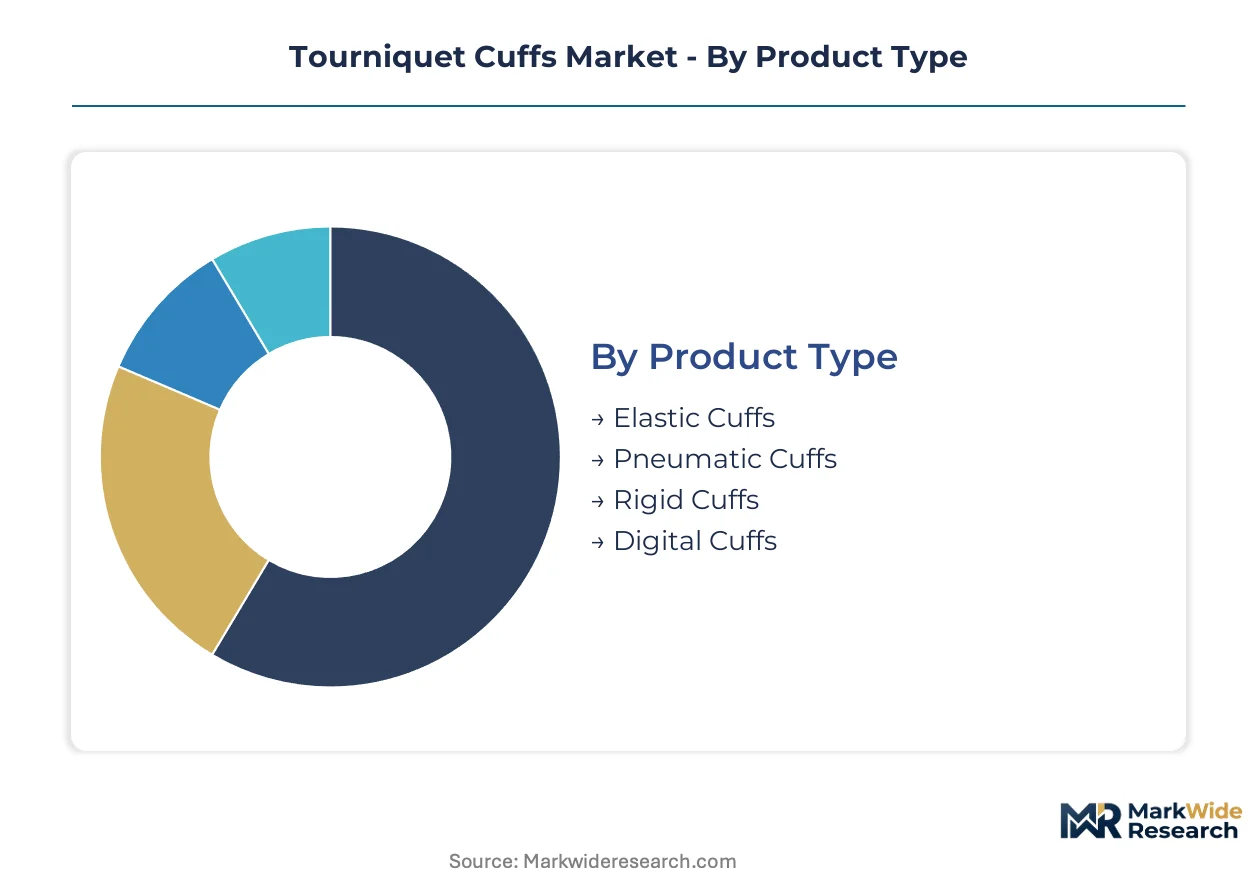
Tourniquet cuff segmentation reveals how regulatory pressure and clinical workflow requirements split demand across technical specifications. Each dimension carries distinct compliance burdens and procurement criteria that reshape supplier positioning.
Product Type:
FDA 510(k) clearance pathways and EU MDR clinical evidence mandates create divergent validation requirements across pneumatic and digital systems versus legacy elastic formats.
- Pneumatic Cuffs:Nylon-reinforced rubber bladders with calibrated inflation systems deliver pressure precision within 5 mmHg tolerance. Hospital surgical suites in Germany and Japan concentrate procurement around automated inflation compatibility. The FDA's Class II device classification imposes pre-market notification documentation that compresses replacement cycles toward digitally-verified platforms.
- Digital Cuffs:Microprocessor-controlled pressure feedback systems embed MEMS transducers for real-time tissue pressure mapping. Trauma centers in the United States pilot these configurations to reduce nerve injury liability. EU MDR transition deadlines force manufacturers to generate clinical performance evidence previously exempt under the Medical Device Directive.
- Elastic Cuffs:Windlass-based mechanical constriction devices dominate civilian first-responder kits due to sub-$15 unit economics and minimal training requirements.
- Rigid Cuffs:Precision-engineered metal or composite frame systems anchor German and Austrian trauma center protocols for orthopedic limb surgery.
Pneumatic cuffs handle the majority of throughput; digital cuffs are climbing the fastest on share.
End User:
Procurement budget tiers and performance requirements stratify demand across institutional buyers with radically different operational constraints.
- Hospitals:Integrated delivery networks in Texas and California mandate standardization across surgical suites, consolidating supplier relationships around full-suite vendors capable of delivering pressure devices, maintenance contracts, and disposable sleeve components through single-source agreements.
- Military Units:Battlefield-hardened portable configurations command premium procurement budgets as defense medical services prioritize rapid hemorrhage control capabilities. These systems require ruggedized housings and battery-independent mechanical backup.
- Emergency Medical Services:Ambulance and air-medical crews balance weight constraints against pressure precision, driving adoption of hybrid manual-automated systems.
- Sports Teams:Professional athletic organizations deploy rapid-application elastic systems for on-field hemorrhage control, with procurement decisions driven by liability insurance requirements rather than clinical outcome data.
Hospitals dominate absolute volume; military units capture the highest margin per unit.
Material:
Biocompatibility certification and supply chain geography concentrate production of medical-grade elastomers in East Asian chemical processing zones.
- Neoprene:Chloroprene rubber formulations with enhanced biocompatibility profiles extend cuff lifecycles and reduce latex-allergy complications in surgical environments. Japanese manufacturers lead formulation refinement for extended-duration procedures.
- Rubber:Natural and synthetic latex compounds retain cost advantage in disposable single-use segments, though allergy liability drives substitution toward synthetic alternatives.
- Nylon:Reinforced woven fabrics provide structural integrity for pneumatic bladder containment, with fiber grade determining pressure tolerance thresholds.
- Polyester:Woven strap materials dominate windlass tourniquet construction for civilian emergency applications due to abrasion resistance and moisture tolerance.
Neoprene commands the premium tier; rubber maintains volume leadership in cost-sensitive segments.
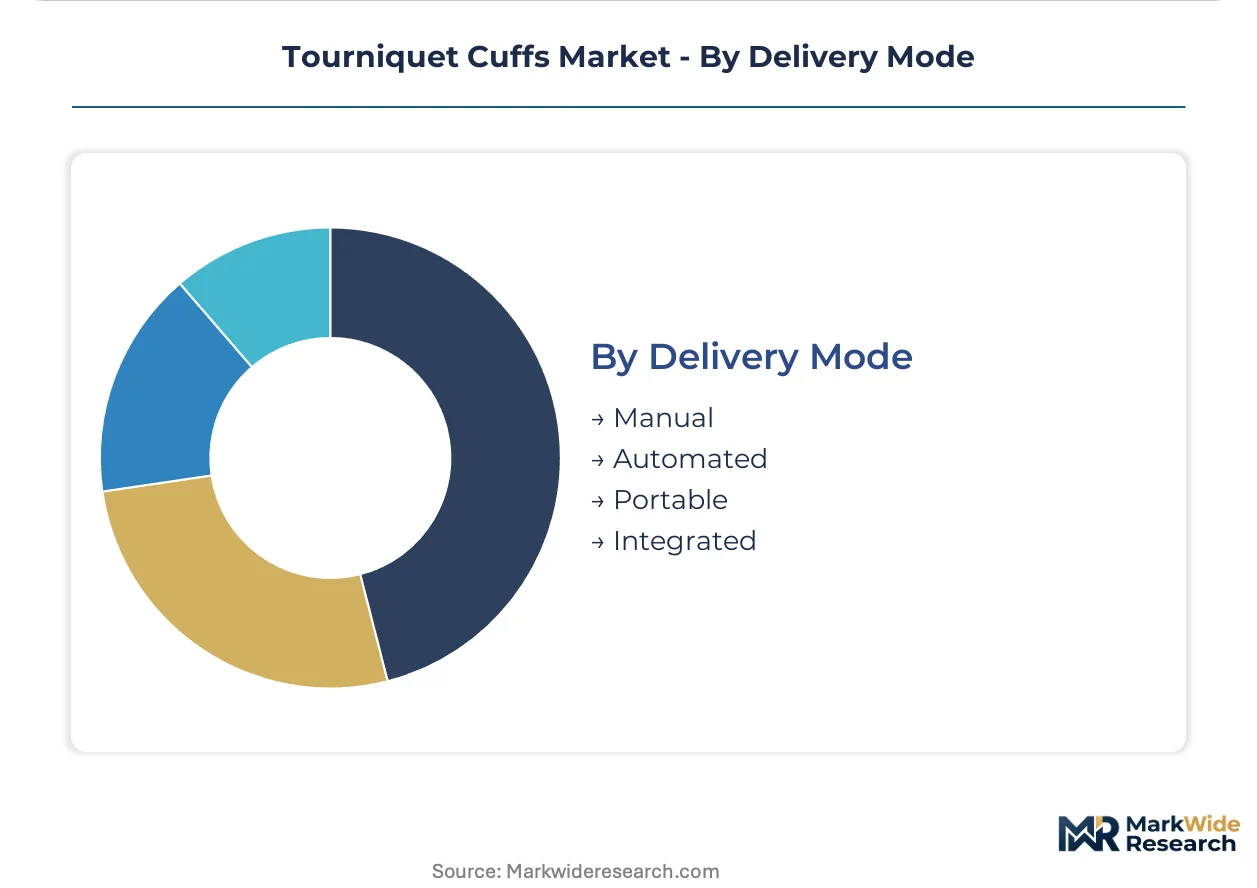
Delivery Mode:
Integration complexity with existing anesthesia information management systems shapes hospital IT department preferences and implementation timelines.
- Automated:Electronic inflation systems with preset pressure protocols reduce operator error in high-volume orthopedic suites. German surgical centers prioritize these configurations for arthroscopy platform bundling.
- Integrated:Direct connectivity to anesthesia information management systems enables automated documentation of tourniquet application timing and pressure parameters. Hospital IT departments face complexity connecting digital cuff interfaces with legacy infrastructure.
- Manual:Hand-operated inflation bulbs retain dominance in resource-constrained settings and backup scenarios where electrical supply is unreliable.
- Portable:Battery-powered standalone units serve military and emergency medical services requiring field deployment without fixed infrastructure.
Automated systems anchor hospital procurement; integrated configurations are expanding most quickly as connectivity standards mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's central role in European medical device distribution, connecting Rhine-Ruhr manufacturing clusters to global supply chains for pneumatic cuff components.
United States
Military trauma centers in San Antonio and Bethesda drive procurement of battlefield-hardened portable configurations. FDA's 510(k) premarket notification requirements for Class II surgical tourniquets compress replacement cycles toward digitally-verified platforms. The Texas Medical Center in Houston anchors hospital system standardization mandates across integrated delivery networks.
Germany
Notified bodies in Tübingen and Munich process CE marking transitions under EU MDR deadlines, extending certification timelines for pneumatic systems. The EU Medical Device Regulation's clinical evidence mandates accelerate hospital upgrades to microprocessor-controlled pressure feedback systems. VBM Medizintechnik GmbH in Sulz anchors precision-engineered rigid cuff production for trauma centers across Bavaria and Austria.
Japan
PMDA's quality management reviews shape supplier qualification criteria for orthopedic surgical suites in Tokyo and Osaka. METI's medical device reimbursement timelines calibrate R&D roadmaps for domestic manufacturers. The Kansai region's arthroscopy platform OEMs bundle pressure-controlled cuff systems with visualization equipment, creating integrated surgical suite ecosystems.
India
Government hospital modernization programs under Ayushman Bharat create demand for mid-tier pneumatic systems with localized service support. CDSCO's medical device registration requirements filter import channels for foreign manufacturers. Medical tourism hubs in Chennai and Hyderabad drive replacement cycles in aging surgical infrastructure across Tamil Nadu and Telangana.
United Kingdom
NHS procurement frameworks consolidate supplier relationships around full-suite vendors capable of delivering maintenance contracts and disposable components. MHRA's post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for cuff manufacturers. The Oxford-Cambridge arc concentrates biomedical engineering talent for pressure-control algorithm development.
Tourniquet Cuffs Market Competitive Landscape
Listed leaders compete with private specialists across distribution reach and regulatory certification depth, creating a tiered structure where scale advantages in hospital channels meet agility in trauma center customization. The vendor base clusters around three strategic archetypes: diversified orthopedic conglomerates bundling cuff systems with surgical platforms, mid-cap pneumatic specialists defending position through ISO 13485 certification infrastructure, and battlefield-focused fabricators commanding premium pricing for ruggedized portable configurations. Dominant competitive moves include portfolio consolidation around integrated surgical suite ecosystems and geographic expansion through notified body relationships in EU MDR transition markets.
Within the diversified orthopedic tier, Stryker Corporation and Zimmer Biomet Holdings Inc. occupy positions that exemplify hospital channel dominance through arthroscopy platform bundling. VBM Medizintechnik GmbH represents the mid-cap precision specialist archetype, anchoring German-speaking trauma center procurement with rigid cuff configurations. These three entities illustrate how competitive positioning stratifies across scale-driven platform integration versus specialization in regulatory-intensive niche segments.
| Leading Market Players |
|---|
| VBM Medizintechnik GmbH |
| AneticAid Ltd |
| Stryker Corporation |
| SourceMark Medical |
| Hammarplast Medical AB |
| Zimmer Biomet Holdings Inc. |
| Ulrich Medical |
| OHK Medical Devices |
| Delfi Medical Innovations Inc. |
| Others |
Value Network & Pricing Analysis
Scale economies in medical-grade elastomer compounding anchor cost structures across pneumatic cuff manufacturing, concentrating production in East Asian chemical processing zones where multi-product polymer facilities achieve minimum efficient scale. This geographic concentration shapes price floors for neoprene-bladder systems while creating tiered procurement dynamics between integrated hospital networks and fragmented emergency medical services.
Pricing Analysis
Volume-discount tiering structures separate integrated delivery network contracts from spot purchases by independent trauma centers. Three-tier pricing stratifies across premium digital systems with MEMS transducers, standard automated pneumatic configurations, and economy manual-inflation alternatives. Price differentiation rests on ISO 13485 certification grade and bundled maintenance service depth. Cost compression in mid-tier pneumatic systems is intensifying as Indian government hospital modernization programs drive localized manufacturing requirements. Emergency medical services exhibit highest price sensitivity due to constrained municipal procurement budgets, while military units accept premium positioning for battlefield-hardened specifications.
Supply Chain Analysis
Just-in-time inventory preferences dominate hospital procurement for disposable sleeve components, whereas strategic stockpiling characterizes military and disaster-response procurement for complete portable systems. Medical-grade neoprene and nylon-reinforced rubber bladder production clusters in China, Japan, and South Korea. Raw material dependencies draw from chloroprene rubber feedstocks, woven nylon structural fabrics, and microelectromechanical pressure sensors. Single-source vulnerability concentrates in specialized polymer compounding capabilities. Distribution runs through orthopedic device distributors in North America, hospital supply consortia in Germany, and government tender channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressure-control algorithm expertise and clinical validation infrastructure constitute binding constraints on R&D scaling, with biomedical engineering talent clustering in established orthopedic device hubs. This capability scarcity favors incumbents with embedded regulatory affairs teams and notified body relationships.
For Market Incumbents: Compound channel control through arthroscopy platform bundling agreements that displace standalone cuff suppliers from integrated surgical suite procurement. Deepen backward integration into medical-grade elastomer compounding to offset East Asian supply concentration risks. Prioritize FDA 510(k) pathway expertise as a defensive moat against mid-sized competitors facing documentation burdens.
For New Entrants and Emerging Players: Anchor in India's mid-tier pneumatic segment where government hospital modernization programs create demand for localized service support without premium digital specifications. Target emergency medical services hybrid manual-automated configurations where incumbent bundling power remains weakest. Pursue CDSCO registration partnerships with established Indian distributors to bypass direct regulatory navigation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineered rigid cuff specialists with established EU MDR certification infrastructure and trauma center relationships in German-speaking markets. Five-to-ten year viability hinges on digital migration capture rates in orthopedic surgical suites. Watch for inflection when MEMS transducer cost curves enable mid-tier digital system penetration below current premium thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Clinical evidence generation for pneumatic systems accelerates hospital upgrade cycles toward digitally-verified platforms. |
| Hospital System Partnership | Single-source agreements with integrated delivery networks in Texas and California displace independent distributor channels. |
| Backward Integration into Elastomers | In-house medical-grade neoprene compounding reduces exposure to East Asian chemical processing zone concentration. |
| Software Companion Development | Anesthesia information management system connectivity expands data capture capabilities for post-operative liability documentation. |
| Reimbursement Strategy | METI medical device timelines in Japan and CMS Medicare data in the United States calibrate R&D roadmaps for domestic manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital purchasing committees, biomedical engineers designing pressure-control algorithms, GPO contracts managers, and military medical procurement officers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR CE marking transition records, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled product type segmentation by pneumatic, digital, elastic, and rigid configurations alongside end-user stratification across hospitals, military units, emergency medical services, and sports teams. Material grade tiers and delivery mode integration complexity provided additional segmentation dimensions. CAGRs were derived from installed base replacement cycle analysis and penetration rate assumptions for microprocessor-controlled systems. Forecast inputs incorporated PMDA quality management review timelines and CDSCO medical device registration processing velocities.
Material uncertainties — regulatory deadline extensions, polymer supply disruptions, and algorithm validation failures — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline stability and reimbursement pathway continuity. Revision becomes warranted when EU MDR notified body backlog durations or FDA 510(k) review velocity cross threshold deviations from historical baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market