
 N95 Respirators Market | 2026-2036
N95 Respirators Market Size, Share, and Industry Trends Forecast 2026-2036
N95 Respirators Market Outlook
The performance gap between premium and commodity N95 tiers is broadening as healthcare systems demand higher filtration consistency and extended wear comfort while industrial buyers prioritize unit cost. 3M Company leverages its NIOSH certification breadth and material science portfolio to sustain pricing power in hospital contracts. Honeywell International anchors its position through industrial distribution networks that compete on volume throughput rather than clinical validation.
N95 respirators are tight-fitting particulate-filtering facepiece respirators certified to filter at least 95% of airborne particles 0.3 microns in diameter, utilizing electrostatically charged polypropylene melt-blown layers bonded to spun-bond outer and inner shells. Their primary purpose is to protect wearers from hazardous aerosols in healthcare, construction, and manufacturing environments where source control or exposure reduction is mandated. Molded cup designs dominate industrial procurement due to structural rigidity and breathability advantages in high-exertion settings, while flat-fold formats lead healthcare adoption because of storage efficiency and compatibility with facial fit testing protocols. The emergency response application represents the fastest-growing segment as government stockpile programs expand beyond pandemic influenza to encompass wildfire smoke and chemical release scenarios.
NIOSH certification under 42 CFR Part 84 remains the gateway standard for US market access, with FDA emergency use authorizations layering additional clinical requirements for surgical N95 variants. OSHA's Respiratory Protection Standard mandates annual fit testing, medical clearance, and training programs that institutionalize recurring demand cycles among employer purchasers. Stakeholders must monitor how the transition from EUA pathways to permanent FDA device classifications reshapes validation costs and competitive entry barriers.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating filtration performance requirements, forcing manufacturers to choose between clinical validation investments and industrial volume plays. This bifurcation is redrawing competitive boundaries across the N95 value chain.
Growth Catalysts
- OSHA Respiratory Protection Standard:Annual fit testing mandates create recurring institutional demand cycles among employer purchasers in healthcare and construction sectors.
- Wildfire smoke emergency protocols:Western United States municipalities are expanding respirator stockpiles beyond pandemic planning to address particulate exposure from intensifying fire seasons.
- Electrostatic melt-blown media:Advances in charge retention technology extend functional wear time, reducing per-shift consumption rates in high-exposure clinical environments.
Market Restraints
- Polypropylene resin concentration:Feedstock supply clusters in Gulf Coast petrochemical corridors expose manufacturers to hurricane disruption and price volatility.
- NIOSH certification queue:Testing laboratory capacity constraints create six-to-nine month validation backlogs that deter new market entrants.
- Surgical mask substitution:Lower-cost ASTM Level 3 alternatives capture non-aerosolizing procedure demand in cost-constrained outpatient settings.
Strategic Opportunities
- Home healthcare expansion:Post-acute care settings currently lack standardized respiratory protection protocols, creating first-mover advantage for protocol-defining suppliers.
- Chemical release preparedness:Industrial safety managers are integrating N95s into multi-hazard response kits beyond traditional particulate applications.
- Reusable elastomeric compatibility:Filter cartridge standardization opens retrofit markets for users seeking to reduce disposable waste without sacrificing NIOSH-validated protection.
Industry Challenges
- Fit tester technician scarcity:OSHA-qualified practitioners command premium wages, constraining compliance program scalability for mid-sized employers.
- Legacy ERP integration:Hospital systems struggle to embed respirator inventory into existing personal protective equipment procurement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N95 Respirators Market |
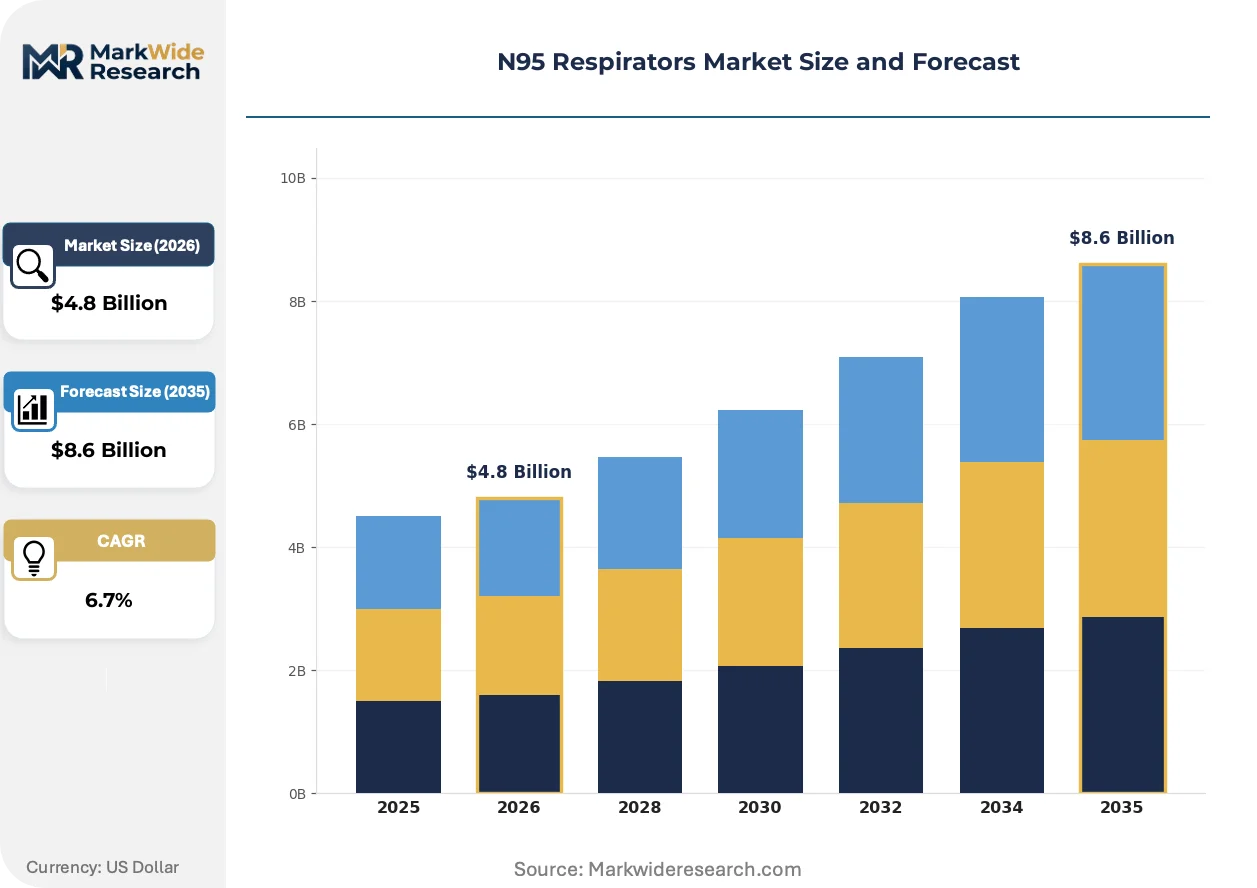
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat-Fold, Molded Cup, Valved, Non-Valved Application: Healthcare, Construction, Manufacturing, Emergency Response End User: Hospitals, Clinics, Laboratories, Industrial Workers Distribution Channel: Direct Sales, Online Retail, Wholesale, Pharmacy |
| Companies Covered | 3M Company, Honeywell International, Kimberly-Clark Corporation, Cardinal Health, Moldex-Metric, Ansell Limited, Alpha Pro Tech, Gerson, Prestige Ameritech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N95 Respirators Market Strategic Shifts
Material science advances are collapsing the historical trade-off between filtration efficiency and breathability resistance, enabling extended-wear designs that challenge traditional shift-based consumption models. This technical convergence is reshaping product architecture and procurement economics simultaneously.
Multi-layer gradient density media is unifying high-efficiency particulate capture with pressure-drop reduction in a single substrate. Hospital systems in California and Washington are piloting eight-hour continuous-use protocols. The technology is unifying previously separate premium and standard product tiers into a single performance-validated offering.
FDA's transition from Emergency Use Authorization pathways to permanent surgical N95 device classifications is elevating quality management system requirements. Manufacturers must now maintain ISO 13485 compliance rather than streamlined EUA documentation. Surgical N95 variants face the steepest compliance cost increases, accelerating consolidation among clinical-focused suppliers.
Consolidated purchasing cooperatives are displacing individual hospital contracting for high-volume stockpile replenishment. Group purchasing organizations now negotiate multi-year supply agreements with performance guarantees. This concentration is most visible in the Northeast, where state-level stockpile coordination has collapsed dozens of discrete procurement decisions into single-source awards.
N95 Respirators Market Segmentation
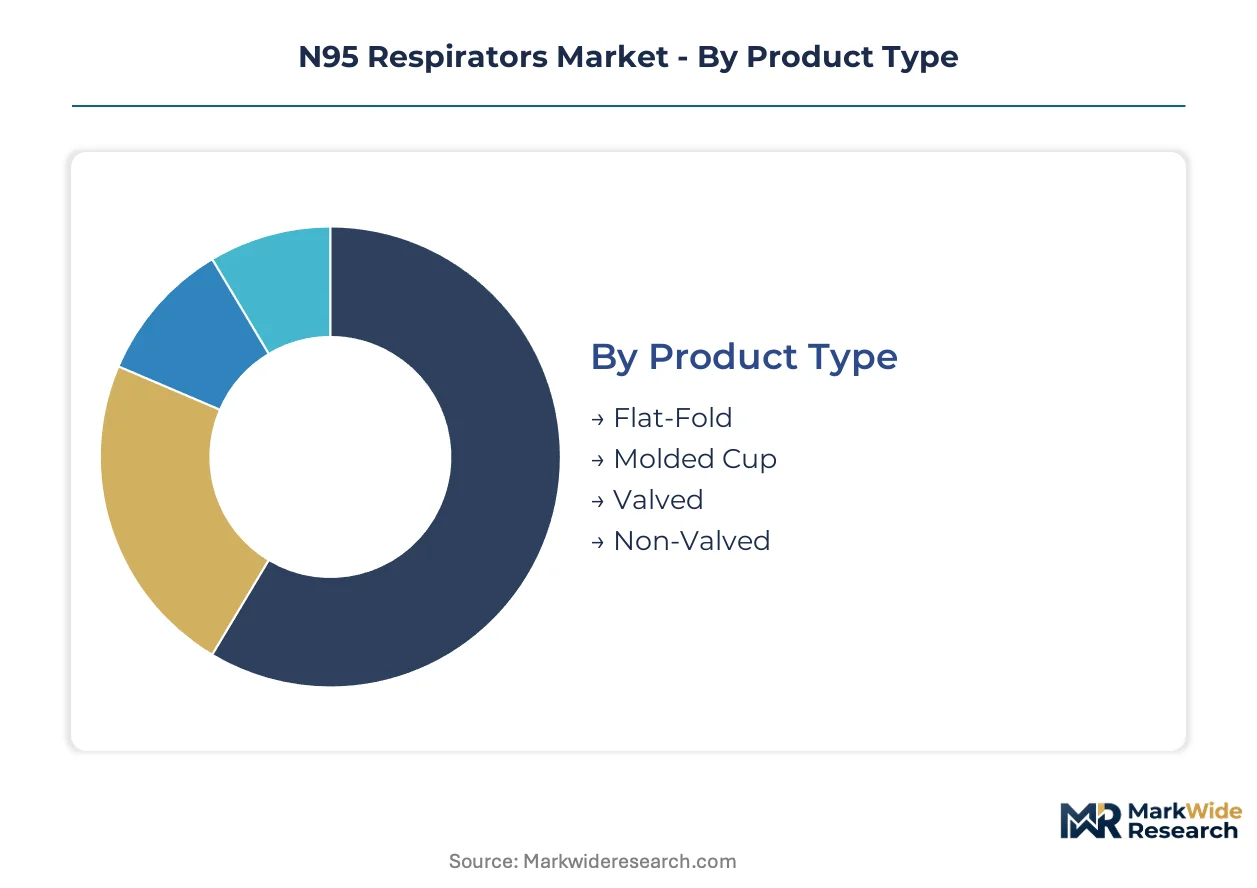
N95 respirator segmentation reflects divergent supply chain configurations across clinical and industrial channels. Product architecture and distribution pathways determine margin structure, certification burden, and inventory velocity for manufacturers competing across multiple end-use contexts.
Product Type:
Supply concentration in melt-blown media production favors manufacturers with captive electrostatic charging capabilities, segmenting competitive position by format complexity.
- Flat-Fold:Multi-layer polypropylene construction with pleated geometry enables compact storage and facial fit testing compatibility. Hospital procurement in California and Washington drives demand as these systems pilot extended-wear protocols requiring storage efficiency.
- Molded Cup:Rigid thermoplastic shells maintain structural integrity during high-exertion industrial tasks. Construction sector procurement across OSHA-regulated sites concentrates demand where breathability and shape retention outweigh unit cost considerations.
- Valved:Exhalation valves reduce breathing resistance and moisture accumulation for extended industrial wear. Manufacturing facilities with heat-stress protocols specify valved designs despite higher per-unit pricing.
- Non-Valved:Unidirectional filtration meets surgical N95 requirements for source control in sterile environments. FDA device classification transitions are elevating quality system costs for this variant.
Flat-Fold absorbs the bulk of installed capacity; Emergency Response applications are expanding most quickly.
Application:
Cost tier stratification separates clinical validation investments from volume-driven industrial plays, reshaping manufacturer portfolio priorities.
- Healthcare:Surgical N95 variants require dual NIOSH-FDA compliance with ISO 13485 quality systems. Hospital procurement consolidation in the Northeast compresses vendor margins while elevating performance guarantees.
- Construction:OSHA respiratory protection mandates create recurring demand cycles tied to annual fit testing programs. Western United States wildfire smoke protocols are expanding stockpile requirements beyond baseline compliance.
- Manufacturing:High-exertion environments prioritize breathability resistance and structural durability over filtration consistency. Industrial distribution networks compete on volume throughput rather than clinical validation.
- Emergency Response:Government stockpile programs encompass pandemic influenza, wildfire smoke, and chemical release scenarios. Multi-hazard preparedness is driving format standardization across federal, state, and municipal procurement tiers.
Healthcare commands premium pricing; Emergency Response is climbing the fastest.
End User:
Customer type determines compliance infrastructure requirements, from medical clearance protocols to fit tester technician availability.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements with performance guarantees and consolidated purchasing. Group purchasing organizations displace individual hospital contracting in high-volume stockpile replenishment.
- Clinics:Cost-constrained outpatient settings substitute ASTM Level 3 surgical masks for non-aerosolizing procedures. This substitution pressure constrains N95 penetration in ambulatory care.
- Laboratories:Biosafety level protocols mandate respirator compatibility with additional PPE layers including face shields and goggles. Flat-fold formats dominate due to integration with facial fit testing equipment.
- Industrial Workers:Mid-sized employers face fit tester technician scarcity that constrains compliance program scalability. OSHA-qualified practitioners command premium wages, limiting program expansion.
Hospitals anchor procurement volume; Laboratories are gaining share fastest.
Distribution Channel:
Margin structure varies sharply by channel control, with direct sales capturing relationship value and wholesale ceding pricing power to intermediaries.
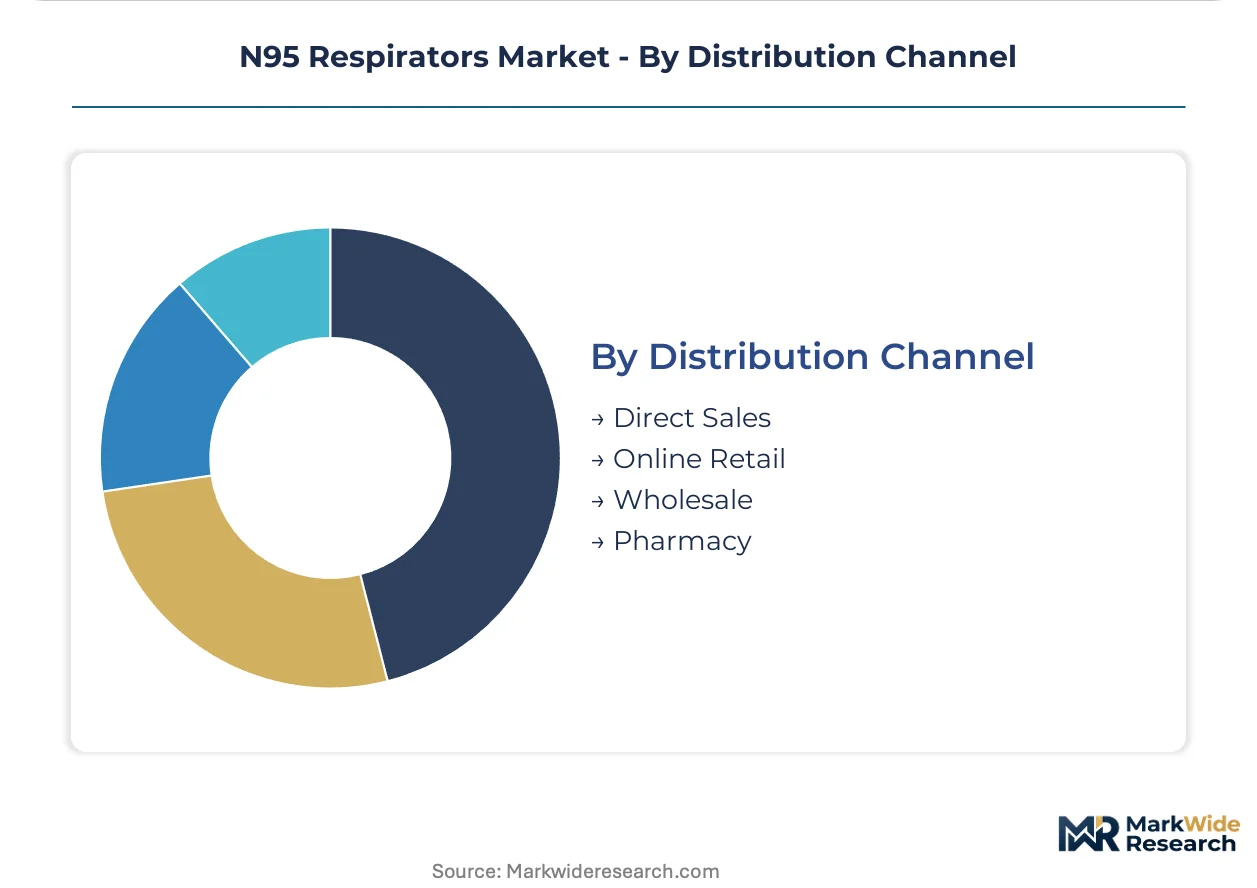
- Direct Sales:Manufacturer-hospital contracts embed inventory management and performance guarantees. Consolidated purchasing cooperatives in the Northeast negotiate these arrangements for state-level stockpile coordination.
- Online Retail:Post-pandemic consumer familiarity enables individual and small-employer procurement outside institutional channels. Quality verification challenges persist given counterfeit proliferation.
- Wholesale:Industrial distribution networks anchor Honeywell's competitive position through volume throughput. These channels prioritize unit cost and availability over clinical validation documentation.
- Pharmacy:Retail pharmacy chains serve home healthcare and individual preparedness demand with limited SKU breadth. Post-acute care settings currently lack standardized respiratory protection protocols, creating first-mover opportunity.
Direct Sales captures the bulk of contract value; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston's petrochemical corridor anchors North American polypropylene feedstock supply for melt-blown media production, while NIOSH-certified manufacturing clusters concentrate in the Midwest and Southeast industrial zones.
United States
Hospital procurement consolidation across the Northeast and California drives premium-tier demand for surgical N95 variants. OSHA's Respiratory Protection Standard mandates annual fit testing programs that institutionalize recurring purchase cycles among employer purchasers. The Minneapolis-Saint Paul corridor hosts multiple NIOSH-certified production facilities serving domestic healthcare contracts.
Germany
Industrial safety distributors prioritize breathability-optimized cup designs for manufacturing and construction applications. The country's national occupational safety regulator enforces strict conformity assessment procedures that exceed baseline EU PPE regulation requirements. The Ruhr industrial region maintains concentrated demand from chemical processing and heavy manufacturing facilities.
China
Domestic manufacturers supply flat-fold formats for export markets while building NIOSH certification capabilities for direct US market access. The national medical products administration tightened quality management system requirements for respiratory protective equipment in 2023. The Yangtze River Delta corridor hosts electrostatic charging equipment clusters serving regional melt-blown media producers.
Japan
Aging healthcare infrastructure drives replacement demand for storage-efficient respirator formats compatible with limited facility space. The Ministry of Economy, Trade and Industry promotes domestic production resilience for critical pandemic preparedness stockpiles. The Chubu region around Nagoya concentrates precision manufacturing capabilities for high-consistency filtration media.
India
Cost-constrained hospital systems favor standard-tier N95 variants over surgical-grade alternatives for non-critical aerosol procedures. The national standards body accelerated PPE certification timelines following pandemic supply disruptions. The Maharashtra-Gujarat industrial corridor hosts emerging domestic manufacturers targeting government stockpile tenders.
N95 Respirators Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification breadth and clinical validation depth. Hospital procurement consolidation favors manufacturers with dual NIOSH-FDA compliance infrastructure, while industrial channels reward volume throughput and distribution density. Three archetypes dominate: diversified conglomerates with material science portfolios, respiratory protection specialists with captive certification expertise, and regional fabricators competing on unit cost. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers position for post-EUA regulatory transitions.
Within the diversified conglomerate tier, 3M Company and Honeywell International exemplify contrasting channel strategies. 3M anchors premium positioning through hospital-direct contracting and NIOSH certification breadth. Honeywell occupies a position emphasizing industrial distribution networks and volume-scale manufacturing. Moldex-Metric represents the specialist archetype with focused respiratory protection expertise.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International |
| Kimberly-Clark Corporation |
| Cardinal Health |
| Moldex-Metric |
| Ansell Limited |
| Alpha Pro Tech |
| Gerson |
| Prestige Ameritech |
| Others |
Value Chain & Pricing Dynamics
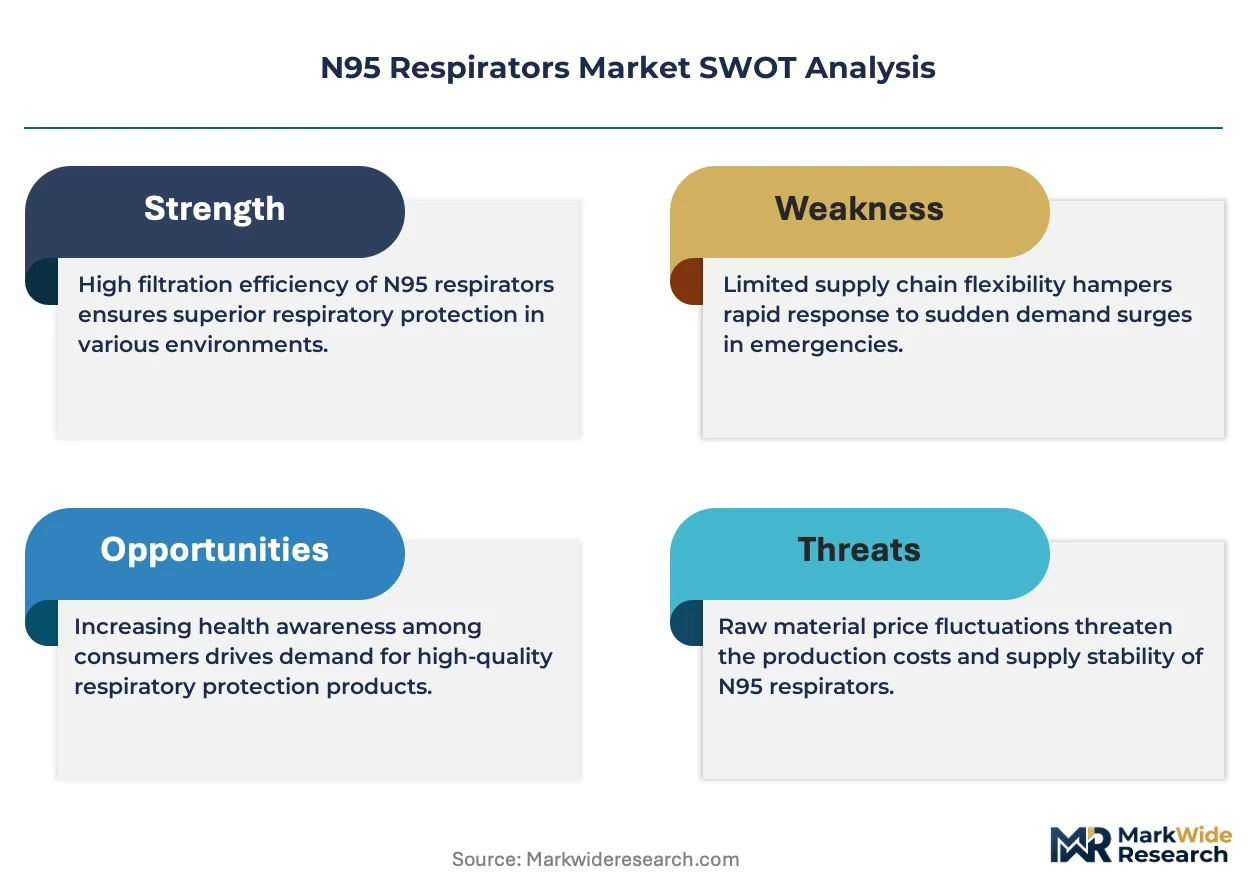
Captive electrostatic charging capabilities anchor supply position and pricing power for melt-blown media producers, creating tiered margin structures that separate hospital-direct contracts from industrial volume plays. Polypropylene resin clusters in Gulf Coast corridors tether cost volatility to hurricane exposure, while NIOSH certification backlogs extend validation timelines that defend incumbent pricing.
Pricing Analysis
Performance-guarantee contracts anchor value-based pricing for surgical N95 variants, with ISO 13485 compliance and dual NIOSH-FDA certification commanding premium positioning against standard industrial tiers. Price differentiation hinges on clinical validation depth and annual fit testing bundling, with hospital procurement consolidation intensifying cost compression in the Northeast. Pricing pressure stems from ASTM Level 3 surgical mask substitution in outpatient settings. Industrial buyers exhibit highest price sensitivity; integrated delivery networks least.
Supply Chain Analysis
Filter cartridge refurbishment flows remain nascent but signal emerging circularity pressure as elastomeric compatibility programs expand. Production draws from United States, China, and Germany, with electrostatic charging equipment clusters concentrating in Yangtze River Delta and Chubu regions. Feedstock dependency centers on polypropylene resin, melt-blown media, and spun-bond shells. Single-source vulnerability runs through Gulf Coast petrochemical corridors. Distribution runs through consolidated purchasing cooperatives and industrial distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA's Respiratory Protection Standard erects a cost-of-compliance moat that rewards NIOSH-certified incumbents while deterring speculative entrants lacking validation infrastructure.
For Market Incumbents: Deploy certification breadth as a defensive lever to secure multi-year hospital contracts before FDA device classification transitions elevate quality system costs. Capacity expansion in Minneapolis-Saint Paul corridors reinforces proximity to healthcare procurement clusters. Consolidate position against emerging domestic Chinese manufacturers building NIOSH capabilities. For New Entrants and Emerging Players: The premium-to-economy price-point gap in home healthcare respiratory protection offers accessible white-space entry. Post-acute care settings lack standardized protocols, creating first-mover advantage for protocol-defining suppliers. Target pharmacy retail channels with limited-SKU preparedness offerings. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified conglomerates seeking clinical validation depth to complement industrial volume positions. Long-term viability favors manufacturers with captive melt-blown media production and dual NIOSH-FDA infrastructure. Watch NIOSH certification queue clearance rates as inflection signal for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NIOSH Certification Expansion | Testing laboratory capacity investments reduce validation backlogs that constrain new entrant supply. |
| Electrostatic Charge Retention R&D | Extended functional wear time collapses per-shift consumption rates in California hospital pilots. |
| Group Purchasing Organization Partnership | Multi-year supply agreements with performance guarantees lock in Northeast procurement consolidation. |
| Backward Integration into Melt-Blown Media | Captive polypropylene processing defends margin position against Gulf Coast feedstock volatility. |
| Home Healthcare Protocol Development | First-mover positioning in post-acute respiratory protection creates channel control before standardization. |
Study Parameters
Hospital procurement databases, OSHA regulatory filings, and NIOSH certification records formed the secondary backbone, supplemented by primary interviews with GPO contracts managers, biomedical engineers, hospital purchasing committees, and industrial safety directors. Customs data and SEC 10-K disclosures provided trade flow and capacity indicators. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Historical trendline analysis of hospital stockpile replenishment cycles and industrial fit testing mandates established baseline demand patterns across the projection horizon. Modeled dimensions span product format, application context, end-user compliance infrastructure, and distribution channel control. CAGRs derived from segment-level volume trajectories and value-per-unit shifts, with wildfire smoke protocol expansion and EUA-to-permanent-FDA-transition timelines as key inputs.
Inputs from hospital procurement systems and NIOSH testing laboratories were available through the study window; gaps in real-time inventory velocity data introduce uncertainty bands around stockpile replenishment timing assumptions. Practitioners should monitor OSHA fit tester technician wage inflation and FDA device classification transition announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsic Safety Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Face Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market