
 Tourniquet Market | 2026-2036
Tourniquet Market Size, Share, and Industry Trends Forecast 2026-2036
Tourniquet Market Outlook
Modular tourniquet kits bundling pneumatic cuffs with pressure monitoring accessories is realigning procurement patterns across hospital systems. Stryker Corporation leverages its orthopedic surgical ecosystem to sustain integrated tourniquet-OR table positioning. Zimmer Biomet anchors its presence through specialized pneumatic systems for extremity procedures. Medline Industries competes on distribution scale, controlling supply chain reach across outpatient surgery centers.
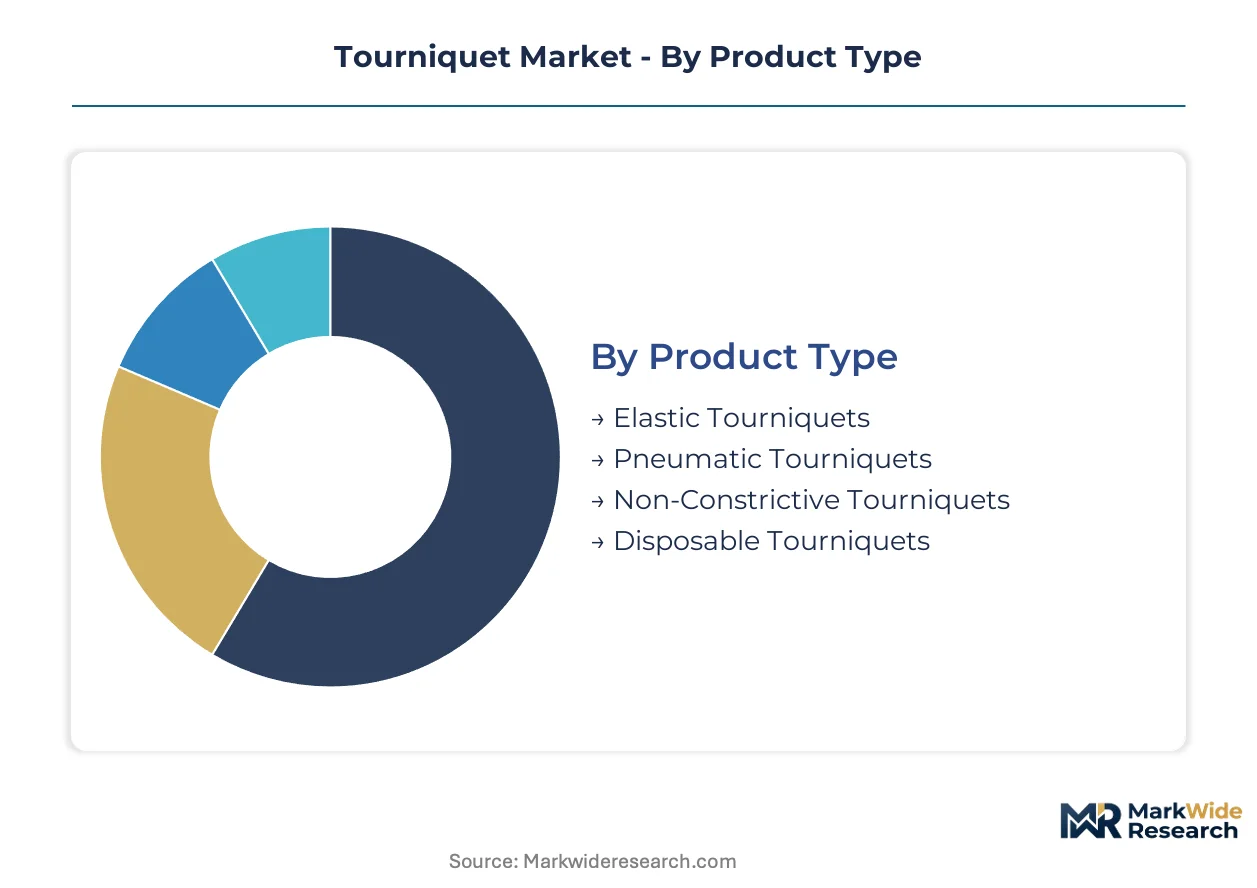
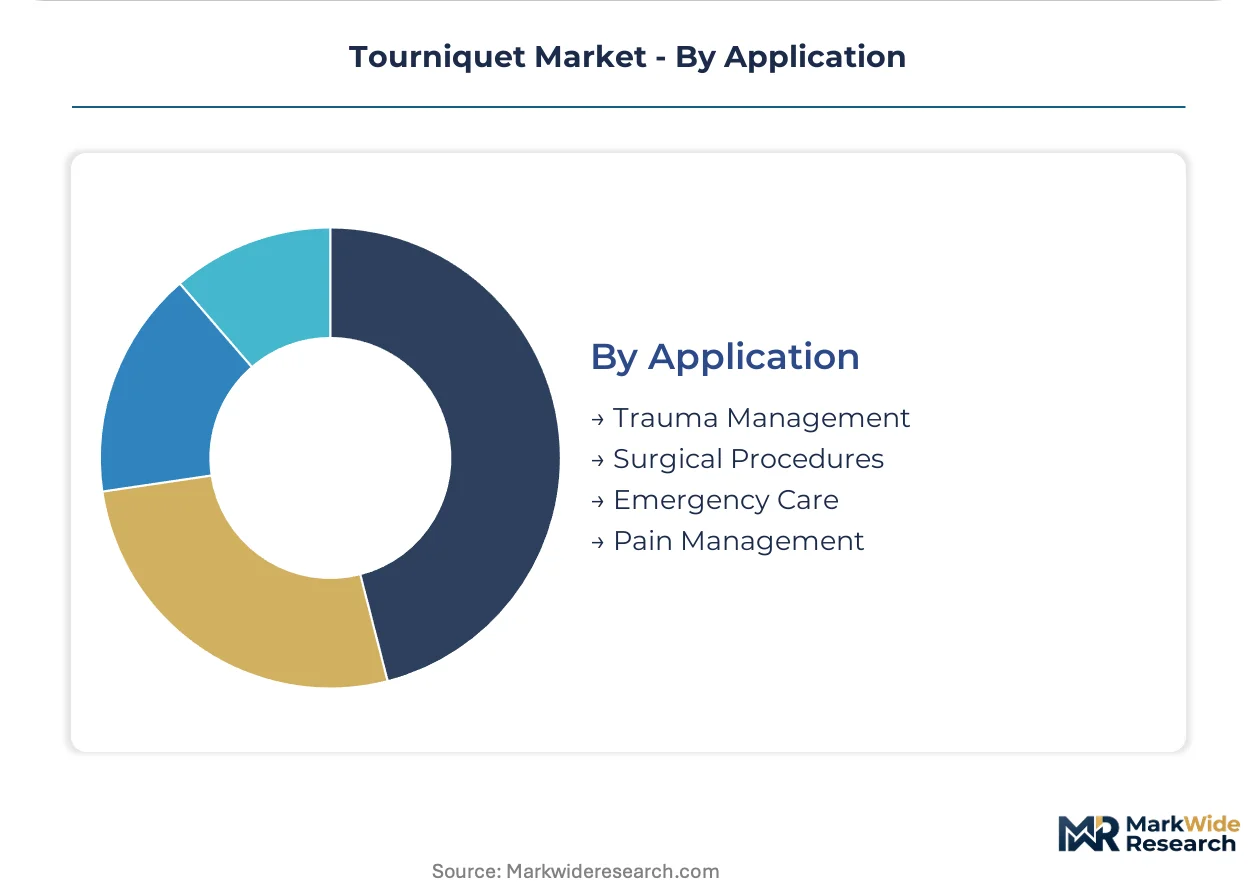
A tourniquet is a mechanical compression device that applies circumferential pressure to a limb to temporarily occlude arterial blood flow, typically constructed from woven polyester or latex-blend fabrics with pneumatic inflation systems achieving pressures of 250-350 mmHg for surgical hemostasis. Its primary purpose is to create a bloodless operative field during orthopedic, podiatric, and plastic surgery procedures while minimizing ischemic tissue damage through controlled inflation cycles. Pneumatic tourniquets dominate the product type landscape due to their precision pressure regulation and integration with electronic monitoring systems, while disposable tourniquets capture expanding share in ambulatory settings where infection control protocols prioritize single-use devices. The emergency care application segment shows the steepest trajectory as pre-hospital trauma protocols standardize tourniquet deployment for hemorrhage control.
FDA Class II device regulations govern pneumatic tourniquet safety performance standards, including pressure accuracy thresholds and alarm system requirements, while ISO 13485 quality management frameworks shape manufacturer certification pathways for international market access. The EU Medical Device Regulation (MDR) is elevating clinical evidence requirements for reusable tourniquet systems, extending conformity assessment timelines for European market entry. Stakeholders must monitor evolving battlefield trauma doctrine integration with civilian emergency medical protocols, as military specification standards increasingly influence commercial product development roadmaps.
Market Dynamics
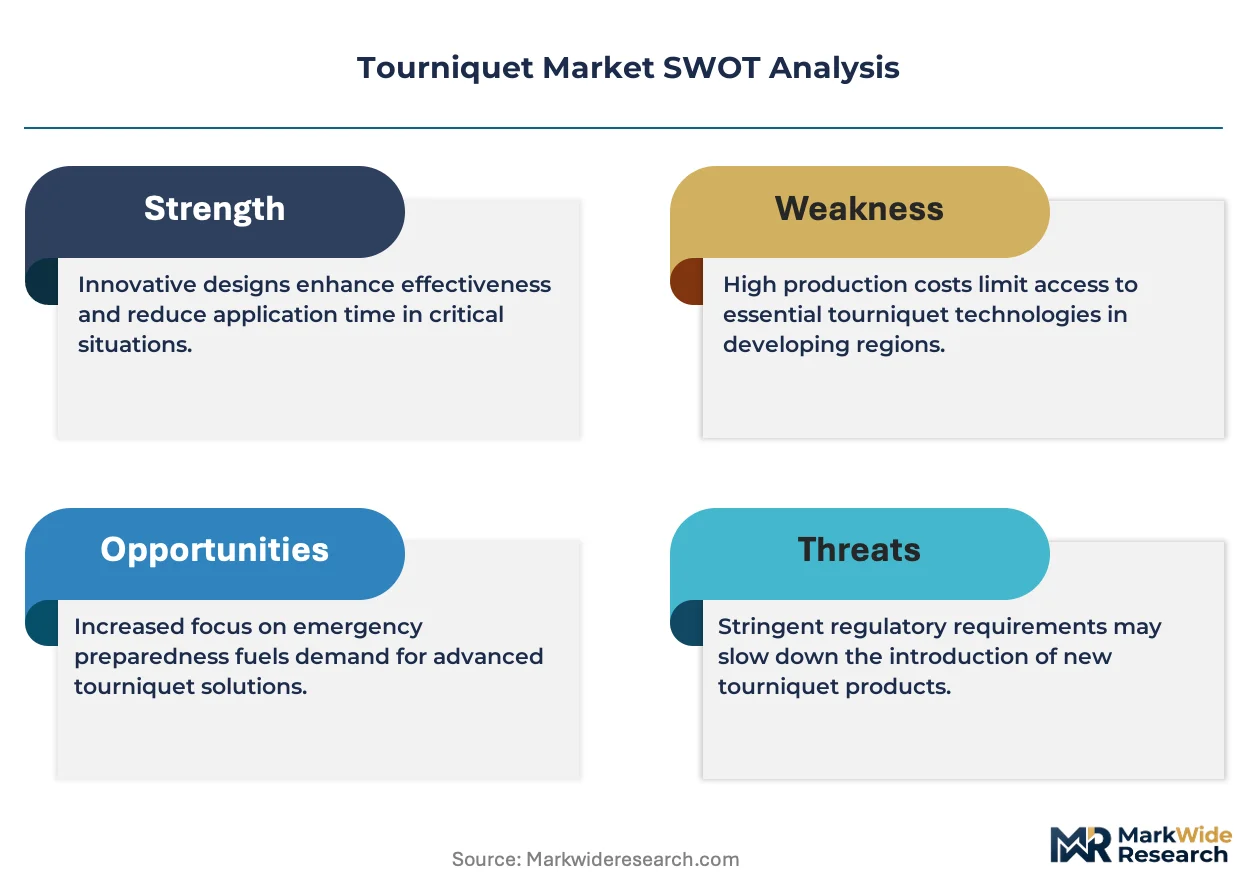
The Tourniquet Market is undergoing structural compression as FDA Class II validation requirements force manufacturers toward integrated pneumatic systems with electronic pressure monitoring, eliminating standalone mechanical cuff suppliers from hospital procurement lists.
Growth Catalysts
- Battlefield Trauma Protocol Evolution:Military specification standards for hemorrhage control are migrating into civilian emergency medical services training curricula, creating specification pull-through for pneumatic tourniquets in municipal ambulance fleets.
- EU MDR Conformity Timelines:Extended clinical evidence requirements for reusable systems are accelerating hospital transitions to single-use pneumatic cuffs, expanding addressable volume in ambulatory surgery centers.
- Orthopedic Surgical Robotics:Integration of tourniquet pressure data with robotic positioning systems is creating bundled procurement specifications that favor manufacturers with OR table ecosystem partnerships.
Market Restraints
- Latex-Blend Material Volatility:Synthetic rubber feedstock price instability compresses margin structures for disposable cuff manufacturers dependent on petroleum-derived elastomers.
- Supply Concentration in Southeast Asian Textile Weaving:Woven polyester cuff fabrication relies on a narrow supplier base in Vietnam and Thailand, exposing procurement continuity to regional logistics disruptions.
- Mechanical Tourniquet Substitution Ceiling:Windlass-style combat tourniquets retain cost advantage in mass-casualty stockpiling scenarios, limiting pneumatic system penetration in federal emergency preparedness contracts.
Strategic Opportunities
- Rural EMS Network Modernization:Underpenetrated county-level emergency services in the United States are receiving trauma system upgrade grants that specify electronic pressure-monitoring tourniquets.
- Podiatric Surgery Center Expansion:Freestanding extremity procedure facilities are adopting specialized lower-limb pneumatic systems with calibrated ankle cuffs for bunionectomy and hammertoe correction volume.
- ISO 13485 Certification Arbitrage:Manufacturers achieving quality management certification ahead of EU MDR enforcement windows capture temporary supply gaps as competitors extend conformity assessment timelines.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Pneumatic system design requires cross-functional expertise in fluid dynamics and clinical ergonomics that outpaces university program output.
- FDA 510(k) Submission Compression:Tightened predicate device equivalence standards for pressure alarm accuracy are extending regulatory clearance timelines and deferring revenue recognition.
- Legacy Hospital Inventory Integration:Electronic monitoring system adoption requires retrofitting OR infrastructure with data capture ports, creating capital budget friction in aging surgical suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourniquet Market |
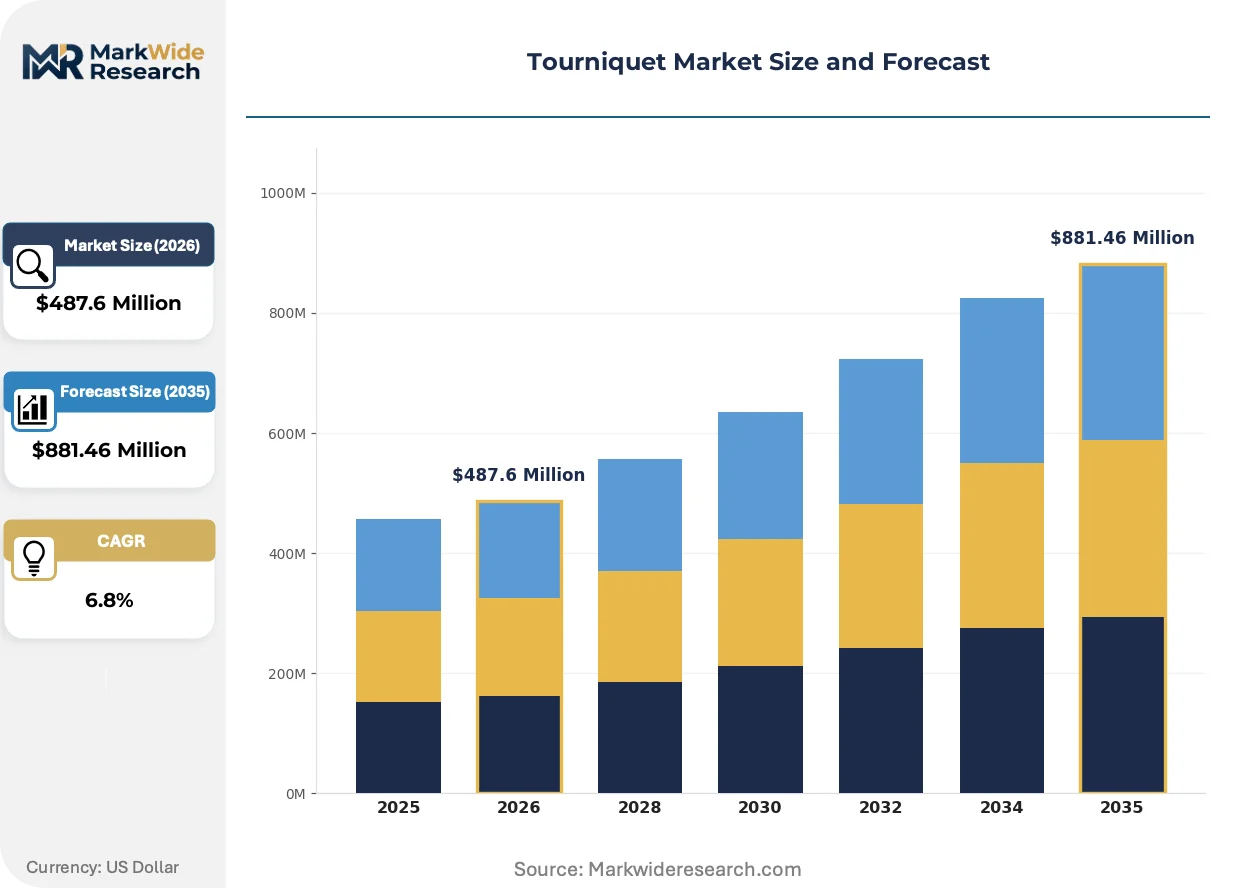
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Tourniquets, Pneumatic Tourniquets, Non-Constrictive Tourniquets, Disposable Tourniquets End User: Hospitals, Emergency Medical Services, Sports Clinics, Home Healthcare Material: Latex, Polyester, Rubber, Nylon Application: Trauma Management, Surgical Procedures, Emergency Care, Pain Management |
| Companies Covered | Ulrich Medical, Hammarplast Medical AB, Zimmer Biomet, OHK Medical Devices, Anetic Aid Ltd., Stryker Corporation, VBM Medizintechnik GmbH, Medline Industries, Delfi Medical Innovations Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourniquet Market Strategic Shifts
Digital pressure sensing and wireless data transmission are redefining tourniquet functionality beyond mechanical occlusion, creating new competitive dimensions around perioperative monitoring integration.
Bluetooth-enabled pressure transducers embedded in pneumatic cuffs are consolidating surgical workflow data capture. Orthopedic service lines in tertiary hospitals are adopting these systems to populate electronic health records with inflation duration and pressure threshold metrics. This capability is consolidating vendor selection criteria around health information technology interoperability rather than standalone device performance.
FDA's updated guidance on pneumatic tourniquet alarm system reliability is tightening validation protocols for pressure deviation detection. Manufacturers must now demonstrate redundant sensor architectures and fail-safe deflation mechanisms to maintain 510(k) clearance eligibility. Surgical device divisions are responding by reallocating R&D resources toward software verification engineering and away from materials innovation.
Hospital supply chain directors are unbundling tourniquet procurement from traditional surgical pack aggregators. Direct manufacturer contracts with pressure-monitoring data sharing provisions are displacing distributor-mediated purchasing for high-volume orthopedic centers. This pattern is most pronounced in United States health systems pursuing value-based care contracts that require procedural outcome documentation.
Tourniquet Market Segmentation
Tourniquet procurement specifications diverge sharply across clinical environments, with surgical suites demanding precision pressure regulation while emergency responders prioritize rapid deployment speed. Material selection and sterilization protocols further fragment supplier qualification requirements across hospital systems and ambulatory networks.
Product Type:
Hospital capital committees weigh pressure accuracy thresholds against total cost of ownership when specifying tourniquet systems for surgical service lines.
- Pneumatic Tourniquets:Electronic pressure regulation systems achieve 250-350 mmHg precision with integrated alarm monitoring. United States orthopedic centers specify these for robotic surgery compatibility and EHR data capture requirements.
- Disposable Tourniquets:Single-use pneumatic cuffs eliminate cross-contamination risk in ambulatory surgery centers. EU MDR extended conformity timelines accelerate hospital transitions toward this category for reusable system replacements.
- Elastic Tourniquets:Woven mechanical bands serve phlebotomy and intravenous access in outpatient settings where pressure precision remains secondary to cost efficiency.
- Non-Constrictive Tourniquets:Venous occlusion devices maintain arterial flow for blood draws in dialysis centers and oncology infusion clinics.
Volume sits with pneumatic systems in tertiary hospitals; growth tilts toward disposable variants in freestanding surgical facilities.
End User:
Procurement authority and reimbursement pathways reshape vendor engagement strategies across institutional categories.
- Hospitals:Integrated delivery networks negotiate enterprise contracts bundling tourniquet systems with orthopedic table positioning equipment. FDA Class II validation requirements filter supplier pools to manufacturers with 510(k) cleared electronic monitoring architectures.
- Emergency Medical Services:Municipal ambulance fleets standardize windlass-style combat tourniquets for hemorrhage control. Military trauma protocol migration into civilian training curricula elevates specification stringency for pneumatic alternatives in advanced life support units.
- Sports Clinics:Athletic training facilities utilize elastic and non-constrictive varieties for acute injury management and cryotherapy adjunct applications.
- Home Healthcare:Post-surgical patients receive disposable pneumatic systems for limb compression therapy under remote nursing supervision.
Revenue concentrates in hospital procurement; expansion accelerates fastest in EMS network modernization programs.
Material:
Raw material sourcing geography and sterilization compatibility determine manufacturing cost structures and regulatory filing strategies.
- Polyester:Woven synthetic fabric dominates reusable cuff fabrication with gamma sterilization tolerance. Vietnam and Thailand textile suppliers concentrate woven substrate supply, exposing continuity risk to regional logistics disruptions.
- Latex:Natural rubber elastomers deliver elasticity in elastic tourniquet bands. Synthetic rubber feedstock price volatility compresses margin structures for manufacturers dependent on petroleum-derived compounds.
- Nylon:High-tensile strength polymers reinforce pneumatic cuff construction for repeated inflation cycles in high-volume surgical environments.
- Rubber:Blended elastomer compounds provide inflation bladder integrity in disposable pneumatic systems.
Procurement volume clusters around polyester substrates; material substitution toward nylon accelerates in premium system segments.
Application:
Clinical outcome documentation requirements and procedural reimbursement codes shape technology adoption intensity across use cases.
- Surgical Procedures:Orthopedic, podiatric, and plastic surgery suites require bloodless operative fields with ischemia time tracking. Bluetooth-enabled pressure transducers populate EHR systems with inflation metrics for value-based care contracting.
- Emergency Care:Pre-hospital trauma protocols standardize tourniquet deployment for extremity hemorrhage control. Battlefield doctrine integration drives specification convergence between military and civilian EMS equipment.
- Trauma Management:Mass casualty preparedness stockpiling maintains demand for mechanical windlass devices in federal emergency reserves.
- Pain Management:Regional anesthesia procedures utilize tourniquet isolation for intravenous limb blocks in outpatient pain clinics.
Procedure volume concentrates in surgical applications; emergency care specifications expand most quickly through protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Southeast Asian textile clusters while procurement authority rests with United States hospital systems and European regulatory bodies. This geographic split shapes investment flows and compliance strategies across the value chain.
United States
Defense contracts and civilian trauma system upgrades accelerate replacement cycles for electronic pressure-monitoring systems. FDA Class II medical device guidance tightens validation requirements for pneumatic tourniquet manufacturers. Orthopedic surgical robotics integration in tertiary hospitals around Boston and Minneapolis drives bundled procurement specifications.
Germany
EU MDR conformity assessment timelines extend market entry for reusable system suppliers, accelerating transitions to single-use alternatives. EMA coordination with notified bodies elevates clinical evidence requirements for pneumatic cuff manufacturers. Medical technology clusters in Baden-Württemberg and North Rhine-Westphalia concentrate R&D investment in pressure sensor architectures.
China
NMPA medical device registration reforms streamline approval pathways for domestic pneumatic system manufacturers. Yangtze River Delta textile suppliers dominate woven polyester substrate production for reusable cuff fabrication. Shanghai and Suzhou medical device parks attract foreign joint ventures seeking manufacturing cost advantages.
Japan
PMDA quality management inspections enforce ISO 13485 certification standards for imported pneumatic tourniquet systems. METI industrial policy supports domestic production of electronic pressure monitoring components. Tokyo and Osaka metropolitan hospital networks specify Bluetooth-enabled data capture for EHR integration.
United Kingdom
NHS supply chain consolidation favors manufacturers with 510(k) clearance reciprocity for emergency medical services procurement. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards. London and Manchester trauma centers standardize pneumatic tourniquet deployment in advanced life support protocols.
Tourniquet Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated vendor structure. Hospital capital committees filter supplier pools through FDA 510(k) clearance and EU MDR certification requirements, compressing the addressable vendor base. Three archetypes dominate: integrated surgical ecosystem providers, specialized pneumatic system fabricators, and distribution-scale medical supply aggregators. Competitive moves center on strategic partnerships with orthopedic robotics manufacturers and backward integration into pressure sensor component supply.
Within the integrated ecosystem tier, Stryker Corporation and Zimmer Biomet anchor positions through OR table positioning partnerships and specialized extremity procedure systems. Medline Industries exemplifies the distribution-scale archetype, leveraging supply chain reach across outpatient surgery centers. Ulrich Medical and VBM Medizintechnik GmbH occupy specialist positions in European markets, while Hammarplast Medical AB and Anetic Aid Ltd. represent regional fabrication capabilities. Delfi Medical Innovations Inc. and OHK Medical Devices sit within the focused pure-play segment, emphasizing pneumatic system specialization over portfolio breadth.
| Leading Market Players |
|---|
| Ulrich Medical |
| Hammarplast Medical AB |
| Zimmer Biomet |
| OHK Medical Devices |
| Anetic Aid Ltd. |
| Stryker Corporation |
| VBM Medizintechnik GmbH |
| Medline Industries |
| Delfi Medical Innovations Inc. |
| Others |
Value Chain & Pricing Dynamics
Biomedical engineering talent concentration in the Yangtze River Delta and Baden-Württemberg creates labor-cost differentials that widen pricing-tier spreads between premium pneumatic systems with electronic monitoring and economy mechanical cuffs. FDA Class II validation requirements and ISO 13485 certification timelines further stratify procurement costs across hospital capital committees and ambulatory surgery centers.
Pricing Analysis
Margin tightening in economy-tier mechanical cuffs reflects synthetic rubber feedstock volatility and petroleum-derived elastomer cost compression. Three-tier pricing structure across premium electronic-monitoring systems, standard pneumatic cuffs, and economy windlass devices differentiates on FDA 510(k) clearance status and Bluetooth-enabled EHR integration. Cost-down pressure on disposable single-use variants accelerates as EU MDR extended conformity timelines drive hospital transitions away from reusable systems. Municipal EMS fleets exhibit highest price sensitivity due to grant-dependent procurement cycles, while integrated delivery networks in tertiary orthopedic centers prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Freight cost escalation from Southeast Asian textile clusters compresses landed costs for woven polyester cuff substrates destined for United States and European assembly facilities. Vietnam, Thailand, and China concentrate woven synthetic fabric supply for reusable cuff fabrication, while Japan and Germany anchor electronic pressure sensor component production. Raw material dependencies on petroleum-derived latex blends, high-tensile nylon polymers, and gamma-sterilizable polyester substrates expose manufacturers to commodity price swings. Single-source vulnerability in Vietnamese textile weaving creates procurement continuity risk during regional logistics disruptions. Distribution runs through hospital GPO contracts, surgical pack aggregators, and direct manufacturer agreements with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tourniquet Market represents a consolidation play as FDA Class II validation requirements and EU MDR conformity timelines force undercapitalized mechanical cuff suppliers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into pressure sensor component supply to secure captive sourcing of Bluetooth-enabled transducers for robotic surgery compatibility. Fortify hospital GPO contract positions through bundled OR table ecosystem partnerships that lock out standalone pneumatic system competitors. Prioritize ISO 13485 certification maintenance ahead of EU MDR enforcement windows to capture supply gaps from lagging rivals. For New Entrants and Emerging Players: The price-point gap between premium electronic-monitoring systems and economy windlass devices creates white-space opportunity for mid-tier pneumatic cuffs with stripped-down data capture. Target underpenetrated county-level EMS networks in rural United States regions receiving trauma system modernization grants. Pursue podiatric surgery center expansion with specialized lower-limb systems calibrated for bunionectomy and hammertoe procedures. Lead with direct-to-facility distribution models that bypass traditional surgical pack aggregators. For Investors and Strategic Acquirers: Re-rating potential sits with focused pure-play pneumatic system specialists given FDA 510(k) clearance reciprocity and EU MDR certification arbitrage opportunities. Long-term viability favors manufacturers with demonstrated health information technology interoperability and orthopedic robotics integration capabilities. Monitor hospital unbundling trends from distributor-mediated purchasing as inflection signal for direct contract momentum. Acquisition targets should exhibit quality management certification ahead of regulatory enforcement windows and established pressure sensor R&D pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Electronic pressure-monitoring architectures with redundant sensor validation secure hospital procurement eligibility. |
| ISO 13485 Certification Investment | Quality management certification ahead of EU MDR timelines captures temporary supply gaps from delayed competitors. |
| Orthopedic Robotics Partnership | Integration with robotic positioning systems creates bundled procurement specifications favoring ecosystem providers. |
| Bluetooth-Enabled Data Capture Development | Wireless pressure transducers populate EHR systems for value-based care contracting requirements. |
| Rural EMS Network Direct Contracting | County-level trauma system grants specify electronic pressure-monitoring tourniquets for underpenetrated markets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and EMS procurement officers. FDA 510(k) clearance databases, EU MDR notified body submissions, and ISO 13485 certification registries provided device-level validation tracking. Bottom-up modeling of pneumatic system shipments triangulated against top-down orthopedic procedure volume estimates and trauma protocol standardization trends across military and civilian emergency medical services.
Granularity-level modeling operated at product-type, end-user, material, and application dimensions, with additional disaggregation by certification tier and data-capture capability across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles, defense contract award patterns, and hospital capital expenditure trajectories. Forecast inputs incorporated battlefield trauma doctrine migration timelines, EU MDR conformity assessment completion rates, and robotic surgery adoption curves in tertiary orthopedic centers.
Inputs from FDA, EMA, and notified body databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume estimates. Forecasts reflect assumptions regarding regulatory enforcement consistency, raw material supply continuity, and trauma protocol standardization velocity. Stakeholders should weight assumptions against their own operating context, particularly regarding capital budget cycles and GPO contract renewal timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Security System Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market