
 Global Face Shield Market | 2026-2036
Global Face Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Global Face Shield Market Foresight
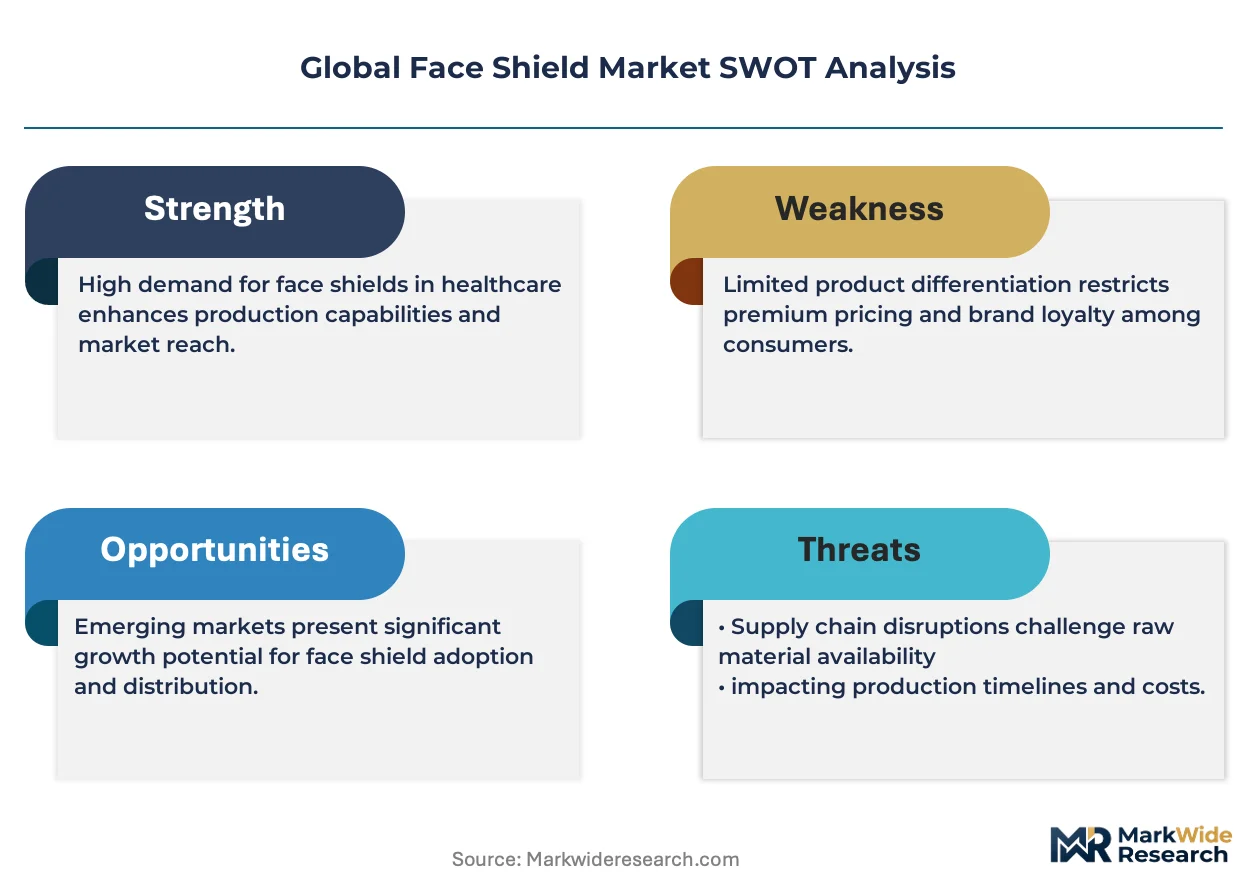
A capital-intensity divergence between automated polycarbonate molding specialists and manual assembly operators is reorganizing competitive tiers in the Global Face Shield Market. 3M leverages integrated resin-to-retail manufacturing to sustain margin control across healthcare and industrial channels. Honeywell International Inc. anchors its position through ANSI Z87.1-certified product lines that dominate North American safety procurement. MSA Safety Inc. competes by specializing in full-face coverage systems for chemical and construction end users.
Face shields are transparent protective barriers typically constructed from polycarbonate, PET, or acrylic sheets with adjustable headgear assemblies, engineered to deflect airborne particles, chemical splashes, and impact hazards from the wearer's facial area. Polycarbonate formulations dominate industrial safety applications due to superior impact resistance and optical clarity under ANSI Z87.1 testing protocols. Reusable face shields command durable goods procurement cycles in construction and laboratory end-user segments, while disposable variants concentrate in healthcare protection where infection control protocols mandate single-use compliance. Anti-fog coatings represent a fast-growing material sub-segment as food manufacturers and medical practitioners prioritize visibility retention during extended wear periods.
FDA enforcement of 21 CFR 878.4040 for surgical apparel and OSHA 29 CFR 1910.133 eye and face protection standards shape product design requirements and market access conditions in the United States. ECHA REACH compliance and CE marking under EU Regulation 2016/425 govern material safety and conformity assessment for European distribution. China's NMPA medical device registration and GB 14866 personal eye-protector standards establish parallel certification pathways for Asia-Pacific market entry. Stakeholders must monitor evolving national stockpile strategies and pandemic preparedness frameworks to anticipate demand surges beyond baseline industrial and healthcare procurement patterns.
Market Dynamics
Polycarbonate resin supply concentration among four Asian petrochemical conglomerates is compressing margin structures for mid-tier face shield assemblers while rewarding manufacturers with captive polymer sourcing or long-term offtake agreements.
Growth Catalysts
- OSHA 29 CFR 1910.133 enforcement:Workplace safety inspections in US manufacturing facilities are accelerating replacement cycles for impact-rated face protection equipment.
- Anti-fog coating chemistry:Hydrophilic nano-layer formulations are penetrating food processing and surgical suites where visibility retention determines compliance.
- German hospital procurement consolidation:Centralized purchasing by university hospital networks is standardizing face shield specifications across outpatient and inpatient settings.
Market Restraints
- Polycarbonate monomer volatility:Bisphenol A feedstock costs fluctuate with crude oil derivatives, squeezing converters without resin hedging programs.
- Chinese mold-making concentration:Tooling fabrication for optical-grade shields clusters in Guangdong and Zhejiang provinces, creating single-source vulnerability.
- Acrylic substitution in low-hazard settings:Impact-inferior acrylic sheets capture price-sensitive construction segments where ANSI Z87.1 certification is not mandated.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO-mandated cleanroom protocols in Active Pharmaceutical Ingredient facilities are creating demand for sterile, disposable face barriers.
- EU Regulation 2016/425 PPE recertification:Module B+C2 conformity assessment requirements are disqualifying non-compliant imports, opening share for certified domestic producers.
- Augmented reality integration:Head-up display compatibility in industrial face shields is converging with smart manufacturing workflows in German automotive assembly plants.
Industry Challenges
- Optical metrology expertise scarcity:ANSI Z87.1 and EN 166 prism deviation testing requires specialized technicians that smaller converters struggle to recruit.
- Multi-jurisdiction certification timelines:Parallel FDA 510(k) and NMPA registration processes for surgical face shields extend product launch windows by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Face Shield Market |
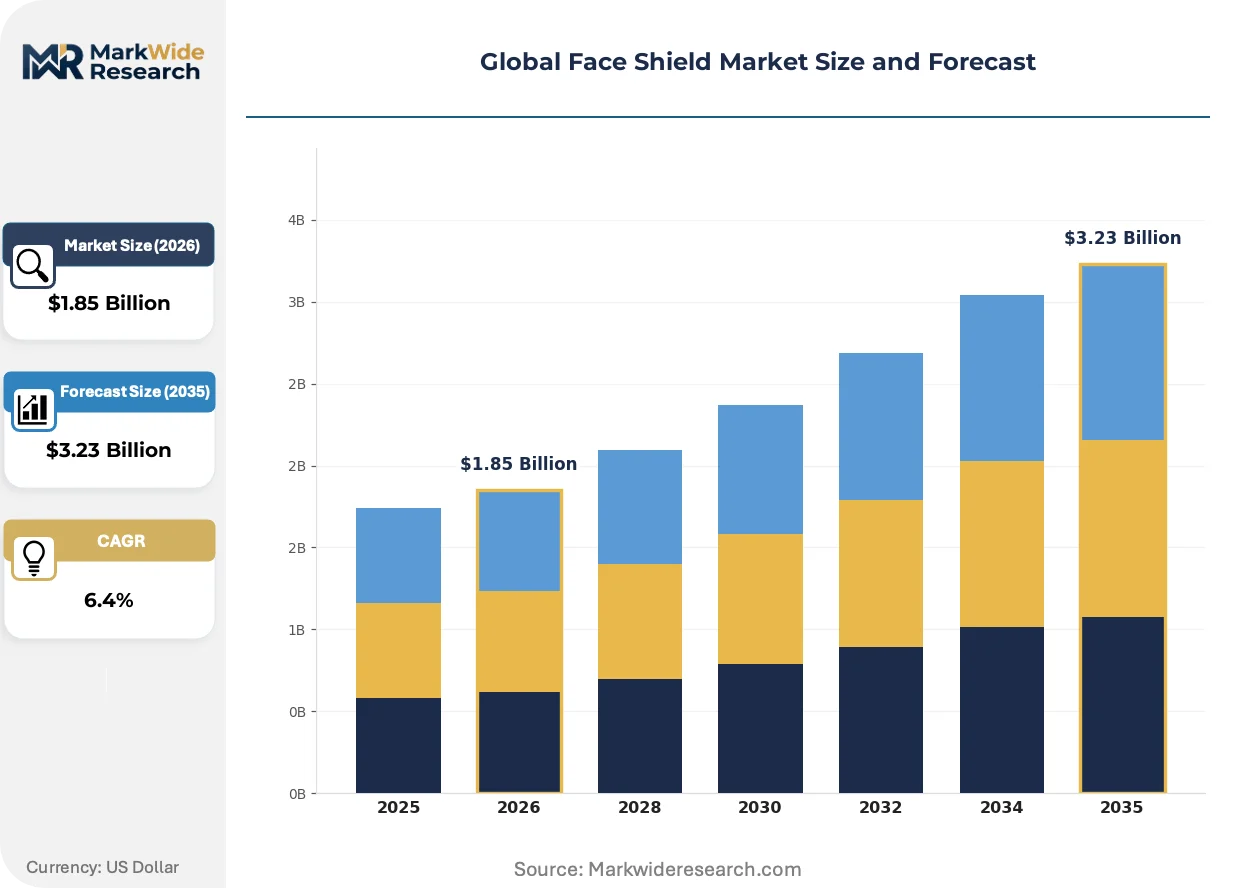
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Anti-Fog, Adjustable, Full Face Coverage Material: Polycarbonate, PET, Acrylic, Polyvinyl Chloride, Thermoplastic Polyurethane Application: Industrial Safety, Healthcare Protection, Food Processing, Laboratory Use, Construction, Personal Care End User: Laboratories, Construction Firms, Food Manufacturers, Medical Practitioners, Chemical Technicians |
| Companies Covered | 3M, Honeywell International Inc., Kimberly-Clark Worldwide, Inc., MSA Safety Inc., Alpha Pro Tech, Lakeland Industries Inc., Prestige Ameritech, Radians Inc., Medline Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Face Shield Market Shifts & Advancements
Material science advances in optical polymers and surface coatings are compressing product lifecycles while regulatory harmonization efforts are reshaping certification economics for cross-border suppliers.
Anti-fog coating deposition via plasma-enhanced chemical vapor deposition is displacing conventional dip-coating methods in premium face shield manufacturing. German automotive suppliers and US surgical device distributors are specifying PECVD-treated shields for extended-wear applications. The process is displacing solvent-based coating houses that lack vacuum deposition capability, consolidating premium supply among integrated optical component manufacturers.
ECHA REACH Annex XVII restrictions on bisphenol A in consumer articles are expanding to professional PPE categories, forcing polycarbonate formulators to validate BPA-free copolymer alternatives. European distributors are demanding full material disclosure documentation ahead of anticipated substance restrictions. Medical-grade shield producers in the Netherlands and Switzerland are accelerating validation of polyester carbonate blends to preempt supply disruption.
Hospital group purchasing organizations are consolidating supplier panels around dual-source qualified vendors, compressing the vendor base from fragmented regional distributors to national contract holders. US health systems are unbundling face shield procurement from broad PPE bundles to secure direct pricing transparency. The shift is most visible in California and Texas, where Kaiser Permanente and HCA Healthcare have established dedicated optical protective equipment sourcing teams.
Global Face Shield Market Segmentation
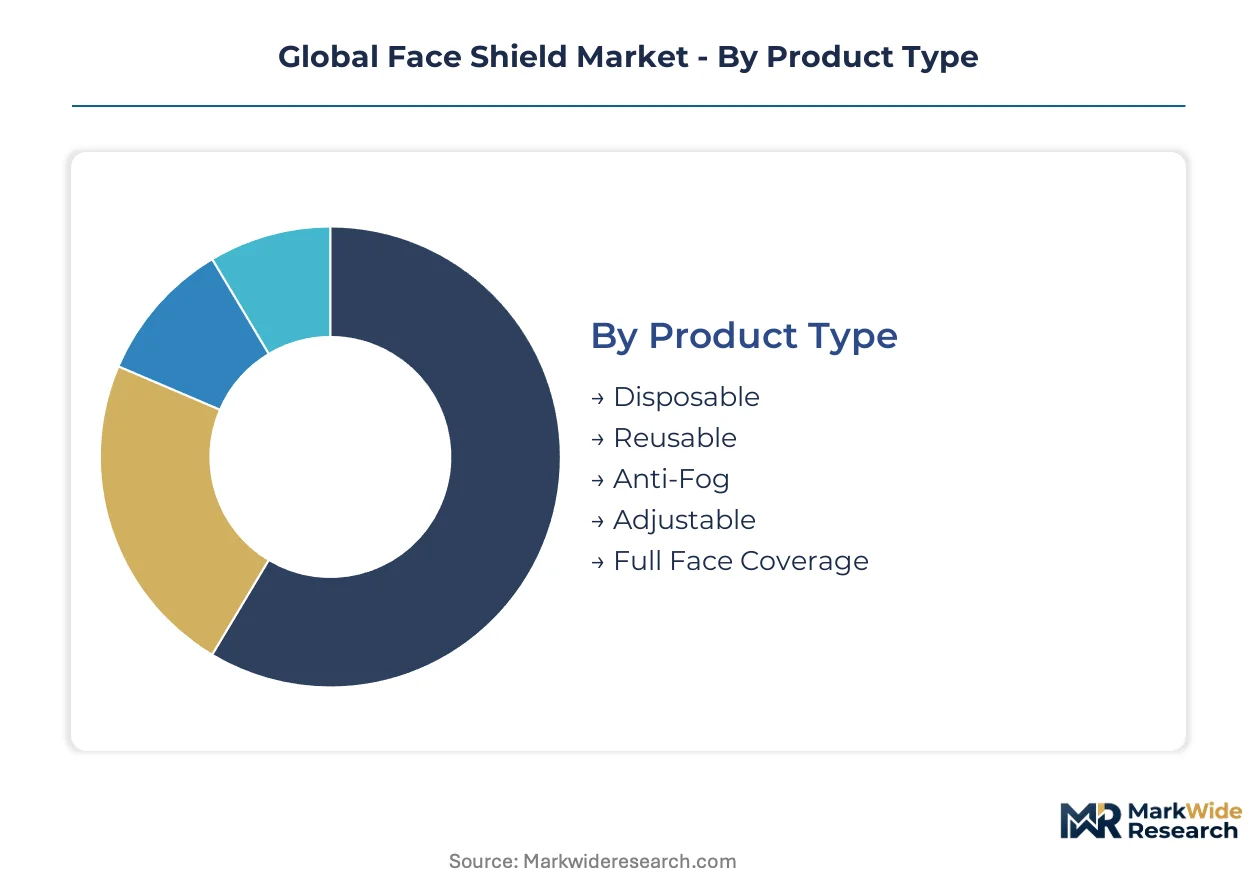
Face shield procurement patterns diverge sharply across material grades and use-case intensity, with substitution pressures from alternative protective equipment reshaping segment economics. Manufacturers must align product architectures to specific certification tiers and replacement-cycle expectations rather than pursuing undifferentiated volume strategies.
Product Type:
Substitution pressure from respirators and safety goggles intensifies in segments lacking distinct functional differentiation, particularly where visibility and comfort specifications overlap with competing protective categories.
- Disposable:Single-use PET or lightweight polycarbonate barriers engineered for infection control compliance in surgical and diagnostic settings. Kaiser Permanente and HCA Healthcare procurement teams in California and Texas are consolidating vendor panels around dual-source qualified suppliers for these items.
- Reusable:Durable polycarbonate assemblies with replaceable visor components designed for extended service life in construction and laboratory environments. German automotive suppliers specify these for assembly-line integration with head-up display compatibility.
- Anti-Fog:Hydrophilic nano-layer coatings applied via plasma-enhanced chemical vapor deposition prevent visibility degradation during extended wear.
- Adjustable:Ratchet suspension systems and pivot mechanisms accommodate diverse facial geometries across industrial user populations.
- Full Face Coverage:Wraparound designs with chin guards and side shields meeting ANSI Z87.1 impact requirements for chemical splash protection.
Reusable systems retain volume leadership in industrial channels; anti-fog variants hold the steepest expansion curve as food processing and surgical visibility requirements tighten.
Material:
Cost-tier stratification separates optical-grade formulations from commodity substitutes, with certification requirements determining acceptable material substitutions across end-use segments.
- Polycarbonate:High-impact thermoplastic with superior optical clarity under ANSI Z87.1 testing protocols, dominating industrial safety and medical-grade applications. Bisphenol A feedstock volatility squeezes converters lacking resin hedging programs or captive polymer sourcing.
- PET:Lightweight polyester sheet offering adequate clarity for short-duration healthcare protection at lower unit economics. Chinese mold-making concentration in Guangdong and Zhejiang provinces creates tooling fabrication bottlenecks for optical-grade PET shields.
- Acrylic:Cost-competitive alternative capturing price-sensitive construction segments where ANSI Z87.1 certification is not mandated, despite inferior impact resistance.
- Polyvinyl Chloride:Flexible formulations suited to disposable medical barriers with lower optical performance requirements.
- Thermoplastic Polyurethane:Elastomeric frame components and gasket materials providing chemical resistance and facial seal integrity.
Polycarbonate maintains premium positioning across certified applications; PET captures the fastest share gains in high-volume disposable healthcare procurement.
Application:
Customer-type concentration drives specification divergence, with hospital networks, industrial contractors, and food processors each imposing distinct performance and documentation requirements.
- Industrial Safety:OSHA 29 CFR 1910.133-mandated impact and chemical splash protection for manufacturing, mining, and energy sector workforces. Workplace safety inspections across US manufacturing facilities are accelerating replacement cycles for impact-rated equipment.
- Healthcare Protection:FDA 21 CFR 878.4040 surgical apparel compliance for hospital networks and outpatient clinics managing infection control protocols. German university hospital network procurement consolidation is standardizing specifications across inpatient and outpatient settings.
- Food Processing:Visibility-retention priorities during extended wear periods in temperature-variable environments.
- Laboratory Use:Chemical resistance and optical clarity requirements for research and diagnostic facilities.
- Construction:Impact protection with dust and debris deflection for outdoor and enclosed-site work.
- Personal Care:Consumer-grade barriers for non-professional use with minimal certification requirements.
Healthcare protection commands the highest certification burden; food processing represents the most rapidly expanding specification tier as visibility coatings penetrate new use cases.
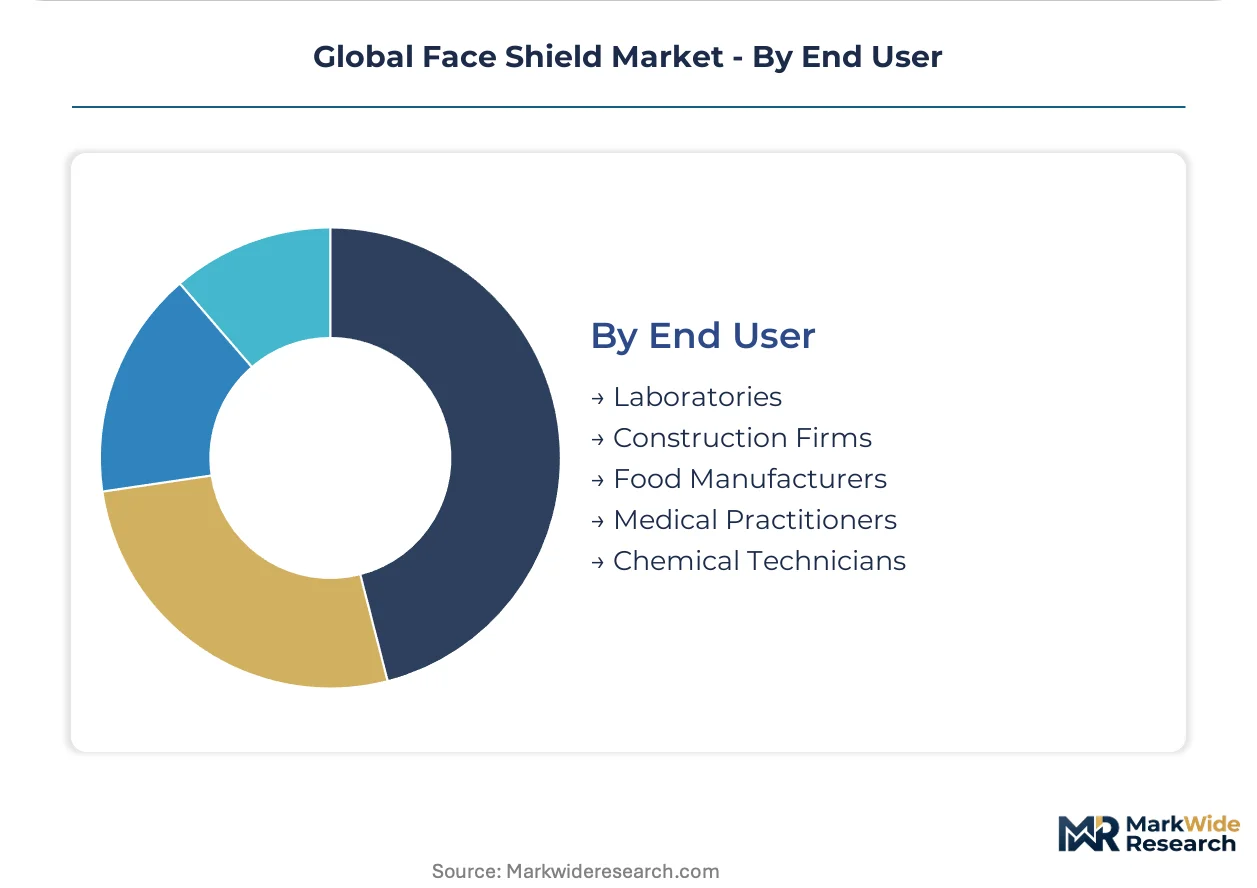
End User:
Geography-specific regulatory frameworks and procurement consolidation patterns determine vendor access conditions across institutional buyer categories.
- Laboratories:Research and diagnostic facilities requiring optical precision and chemical resistance for extended analytical procedures.
- Construction Firms:Project-based procurement of impact-rated equipment subject to OSHA enforcement variability across US states.
- Food Manufacturers:Anti-fog specification dominance in temperature-controlled processing environments.
- Medical Practitioners:Individual and group practice purchasing subject to CDC infection control guideline updates.
- Chemical Technicians:Full-face coverage requirements for splash and vapor exposure scenarios in pharmaceutical and specialty chemical production.
Medical practitioners drive premium pricing for certified surgical shields; chemical technicians generate the most demanding performance specifications for integrated respiratory-face shield systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for face shields varies sharply by geography. German hospital networks and US industrial buyers prioritize certified optical performance over unit cost, while price-sensitive construction segments in emerging markets drive acrylic substitution.
United States
OSHA workplace safety inspections in manufacturing facilities are accelerating replacement cycles for ANSI Z87.1-certified face protection. FDA enforcement of 21 CFR 878.4040 for surgical apparel shapes hospital network procurement specifications. Kaiser Permanente and HCA Healthcare sourcing teams in California and Texas are consolidating vendor panels around dual-source qualified suppliers.
Germany
University hospital network procurement consolidation is standardizing face shield specifications across inpatient and outpatient settings. ECHA REACH Annex XVII restrictions on bisphenol A are forcing polycarbonate formulators to validate BPA-free copolymer alternatives. Automotive suppliers in Bavaria specify plasma-enhanced chemical vapor deposition-treated shields for head-up display compatibility.
China
NMPA medical device registration and GB 14866 personal eye-protector standards establish parallel certification pathways for domestic and export markets. Polycarbonate resin supply concentrates among four Asian petrochemical conglomerates, compressing margin structures for mid-tier assemblers. Mold-making for optical-grade shields clusters in Guangdong and Zhejiang provinces, creating single-source vulnerability.
India
CDSCO-mandated cleanroom protocols in Active Pharmaceutical Ingredient facilities are creating demand for sterile, disposable face barriers. Domestic manufacturing expansion targets import substitution for hospital-grade protective equipment. Pharmaceutical manufacturing corridors in Maharashtra and Gujarat are driving procurement volume concentration.
Switzerland
Medical-grade shield producers are accelerating validation of polyester carbonate blends to preempt BPA-related supply disruption. Swissmedic certification requirements anchor premium positioning for surgical applications. Precision optics clusters in the Basel region support advanced coating deposition capabilities for extended-wear specifications.
Global Face Shield Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the face shield market. Integrated resin-to-retail manufacturers with captive polymer sourcing control margin structures, while manual assembly operators compete on volume in undifferentiated segments. Three archetypes dominate: diversified industrial conglomerates with multi-channel distribution, specialized safety equipment pure-plays with certification depth, and regional converters serving price-sensitive construction end users. Capacity expansion and strategic partnerships represent the dominant competitive moves, with backward integration into optical-grade polymer supply emerging as a margin defense mechanism.
Among diversified industrial conglomerates, 3M and Honeywell International Inc. exemplify archetypes combining regulatory certification breadth with multi-channel reach. MSA Safety Inc. occupies a position within the specialized safety equipment tier, anchoring full-face coverage system expertise for chemical and construction applications. These three entities represent distinct strategic postures: resin-integrated manufacturing, standards-compliant product line dominance, and end-use specialization respectively.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Kimberly-Clark Worldwide, Inc. |
| MSA Safety Inc. |
| Alpha Pro Tech |
| Lakeland Industries Inc. |
| Prestige Ameritech |
| Radians Inc. |
| Medline Industries, Inc. |
| Others |
Supply & Pricing Matrix
ANSI Z87.1 certification tiers gate both supplier qualification and price differentiation simultaneously, with impact-rated polycarbonate assemblies commanding substantial premiums over uncertified acrylic substitutes while resin-integrated manufacturers capture margin control through captive bisphenol A sourcing.
Pricing Analysis
Replacement visor and suspension component sales drive lifetime value for reusable system vendors. Three-tier pricing structure across premium, standard, and economy levels separates PECVD anti-fog treated shields from conventional dip-coated alternatives and uncertified construction-grade barriers. Cost compression in mid-tier PET disposables intensifies because Chinese mold-making concentration eliminates tooling competition. Hospital procurement teams show lowest price sensitivity; construction contractors exhibit highest.
Supply Chain Analysis
China and South Korea anchor polycarbonate resin production for optical-grade shield substrates. German and Swiss converters draw from Asian petrochemical feedstock while maintaining precision coating deposition capabilities. Single-source vulnerability concentrates in Guangdong and Zhejiang mold fabrication clusters. Distribution runs through hospital group purchasing organizations and industrial safety distributors with divergent certification documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA enforcement cycles drive predictable replacement demand surges, positioning the market for recovery-phase volume expansion as inspection intensity normalizes post-pandemic procurement distortions.
For Market Incumbents: Shield margin structures through backward integration into polycarbonate resin supply or long-term offtake agreements with Asian petrochemical conglomerates. Accelerate FDA 510(k) and NMPA dual-registration investments to preempt 14-22 month launch delays that emerging competitors cannot absorb. Prioritize anti-fog coating chemistry R&D to defend premium positioning against solvent-based coating houses lacking PECVD capability. For New Entrants and Emerging Players: Lead with CDSCO-mandated cleanroom protocol compliance in Indian Active Pharmaceutical Ingredient facilities where sterile disposable demand outpaces domestic supply. Target food processing visibility-retention specifications where hydrophilic nano-layer coatings penetrate temperature-variable environments faster than industrial safety channels. Pursue direct hospital system contracting in California and Texas where Kaiser Permanente and HCA Healthcare sourcing teams actively unbundle face shields from broad PPE bundles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core PPE assets with established ANSI Z87.1 certification infrastructure. Long-term viability hinges on regulatory compliance depth rather than undifferentiated volume scale. Monitor ECHA REACH Annex XVII bisphenol A restriction timelines as inflection indicators for polyester carbonate blend validation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive bisphenol A sourcing insulates margin structures from feedstock volatility. |
| Dual FDA-NMPA Registration Investment | Parallel certification pathways compress competitive launch windows by 14-22 months. |
| PECVD Coating Capacity Expansion | Plasma-enhanced deposition displaces solvent-based houses in premium surgical specifications. |
| Hospital System Direct Contracting | Unbundled procurement with Kaiser Permanente and HCA Healthcare secures pricing transparency. |
| BPA-Free Copolymer Validation | Polyester carbonate blend qualification preempts ECHA REACH Annex XVII supply disruption. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, industrial safety directors, and polycarbonate resin procurement leads and secondary sources including FDA 510(k) filings, OSHA enforcement databases, and ECHA REACH substance restriction notices anchors the qualitative findings. Bottom-up demand modeling from end-user replacement cycles and top-down supply-side capacity assessments triangulate volume estimates.
Sensitivity analysis across material grade, certification tier, and geographic regulatory cluster dimensions shapes the analytical framework over the projection horizon. CAGRs derive from segmented demand elasticity coefficients and input cost trajectory assumptions. Modeled inputs include bisphenol A feedstock price volatility indices and hospital group purchasing organization consolidation timelines.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity or accelerated ECHA substance restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding polycarbonate resin supply concentration and dual-source qualification adoption rates. Recalibration cycles align with material shifts in regulatory enforcement patterns and petrochemical feedstock cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market