
 Estonia Property and Casualty Insurance Market | 2026-2036
Estonia Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Estonia Property and Casualty Insurance Market Insights
Comprehensive multi-year coverage tiers is unwinding legacy annual-contract conventions across Estonia's property and casualty sector. IF P&C Insurance leverages its Nordic risk-engineering heritage to dominate commercial property lines. Swedbank P&C Insurance anchors retail distribution through embedded banking channels. ERGO Insurance specializes in agricultural coverage, capitalizing on Estonia's expanding farm consolidation trend.
Property and casualty insurance constitutes risk-transfer contracts indemnifying policyholders against physical asset damage, legal liability exposure, and operational interruption, with premiums calibrated through probabilistic loss modeling and statutory capital adequacy thresholds. Motor insurance and commercial property coverage lead premium generation, reflecting Estonia's dense vehicle ownership and Tallinn's commercial real estate development pipeline. Liability insurance is accelerating fastest among technology startups requiring directors-and-officers protection. Agricultural insurance commands thinner margins but benefits from EU Common Agricultural Policy premium subsidies.
Estonia's Financial Supervision and Resolution Authority enforces Solvency II-aligned capital requirements, while the Estonian Traffic Insurance Fund mandates statutory motor third-party liability coverage. GDPR and the EU AI Act are reshaping cyber liability product structures and algorithmic underwriting transparency standards. Stakeholders must monitor how Estonia's pending natural catastrophe risk pool legislation redistributes flood and storm exposure across domestic carriers.
Market Dynamics
Estonia's alignment with EU Solvency II directives is compressing capital reserve timelines for domestic carriers while accelerating multi-year coverage tier adoption across commercial lines. Small business entrepreneurs are driving demand for operational risk protection as fleet expansion and construction activity concentrate in Tallinn and Tartu.
Growth Catalysts
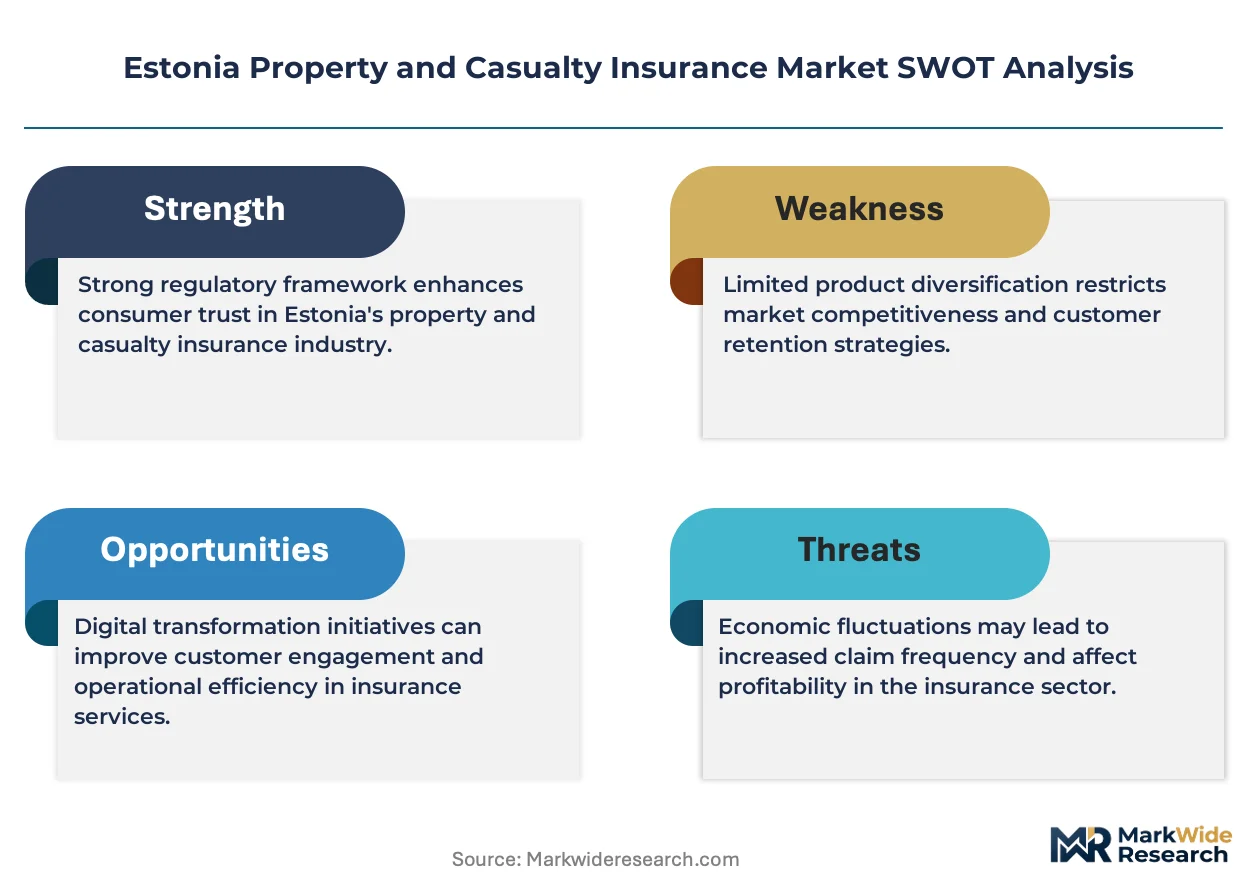
- EU Solvency II Capital Framework:Estonian carriers are restructuring reserve requirements to meet harmonized risk-based capital standards, unlocking capacity for commercial property expansion.
- Technology Startup Liability Demand:Directors-and-officers protection is accelerating fastest among Estonia's emerging tech sector as venture-backed firms scale governance risk exposure.
- Farm Consolidation Trajectory:Agricultural coverage volumes are climbing through EU Common Agricultural Policy premium subsidies supporting Estonia's consolidating farm operations.
Market Restraints
- Thin Agricultural Margins:Crop and livestock lines face structurally compressed underwriting returns despite subsidy support, limiting carrier appetite for rural expansion.
- Cyber Liability Uncertainty:GDPR and the EU AI Act are creating product-structure friction as algorithmic underwriting transparency standards remain partially undefined.
- Natural Catastrophe Exposure Concentration:Pending flood and storm risk pool legislation threatens to redistribute unpriced catastrophe liability across domestic balance sheets.
Strategic Opportunities
- Embedded Banking Distribution:Retail property and casualty penetration can deepen through integration with Estonia's consolidated banking channels.
- Cyber Liability Product Innovation:GDPR compliance mandates and AI Act algorithmic accountability rules are creating tailwinds for specialized technology coverage.
- Multi-Year Contract Structures:Comprehensive coverage tiers are unwinding legacy annual conventions, enabling premium stability and customer retention gains.
Industry Challenges
- Actuarial Talent Scarcity:Probabilistic loss modeling expertise for emerging cyber and AI risk categories remains concentrated among Nordic carriers.
- Legacy System Integration:Domestic insurers face friction modernizing policy administration platforms to support real-time risk-engineering data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Estonia Property and Casualty Insurance Market |
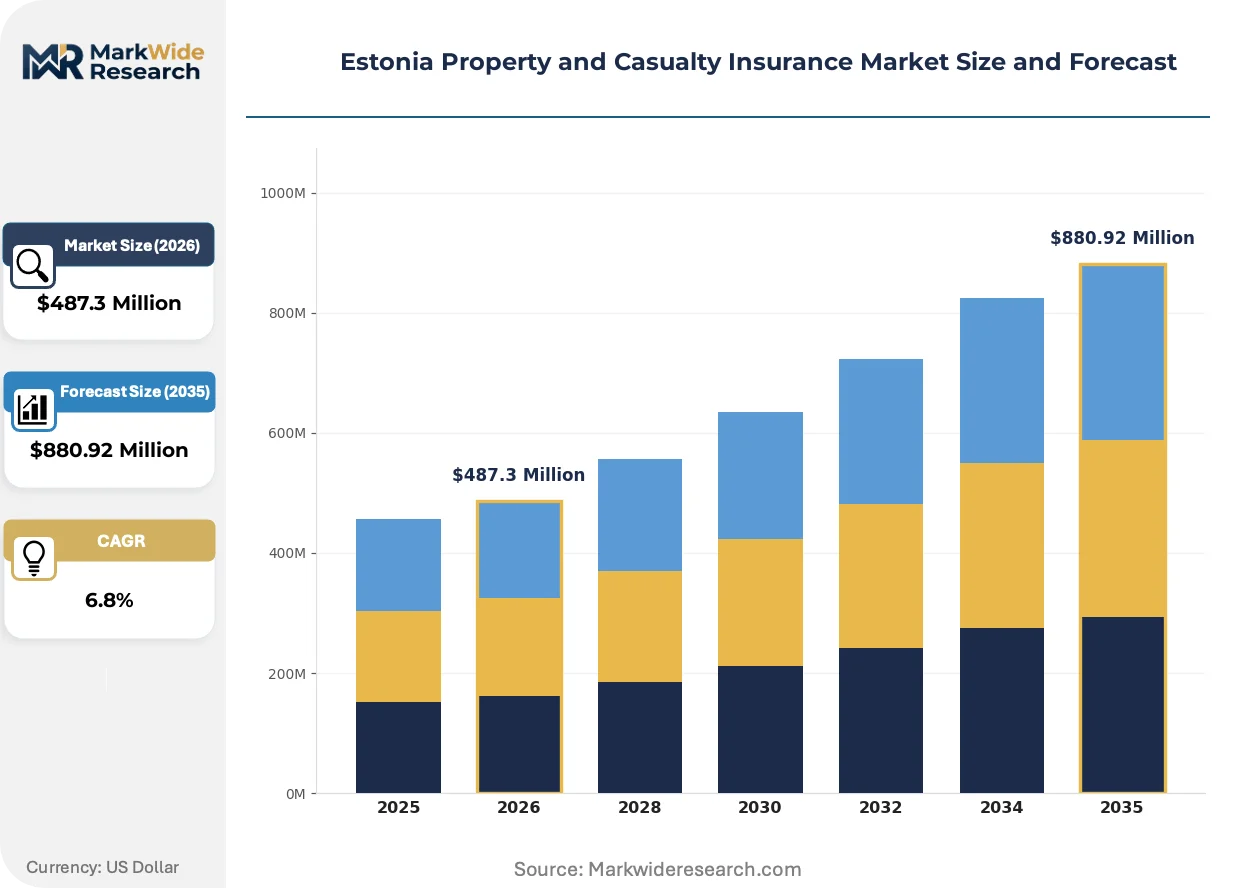
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Property Insurance, Liability Insurance, Marine Insurance, Motor Insurance Client Segment: Individuals, Small Businesses, Large Corporations, Government Entities Coverage Area: Home Coverage, Auto Coverage, Commercial Property, Agricultural Insurance Policy Duration: Short-Term, Long-Term, One-Year, Multi-Year |
| Companies Covered | IF P&C Insurance, ERGO Insurance, Swedbank P&C Insurance, AB Lietuvos draudimas, Compensa Vienna Insurance Group, BTA Baltic Insurance Company, Salva Kindlustus, LHV Kindlustus, Inges Kindlustus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Estonia Property and Casualty Insurance Market Trends and Innovations
Algorithmic underwriting tools are supplanting traditional manual risk assessment across Estonia's property and casualty sector. Carriers are restructuring product architectures around continuous data ingestion rather than static annual renewal cycles.
Telematics-enabled motor pricing is supplanting conventional demographic rating factors in Estonia's vehicle coverage market. Fleet operators in Tallinn are adopting real-time driving behavior monitoring at accelerating pace. This shift is compressing premium variance between high and low-risk policyholders while enabling dynamic coverage adjustments.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated underwriting decisions. Estonian insurers must now maintain explainability documentation for machine learning models used in policy pricing. Commercial lines and cyber liability products face the steepest compliance recalibration as supervisory scrutiny intensifies.
Small business owners are consolidating insurance procurement through bundled operational risk packages rather than discrete single-peril policies. Independent brokers in Tartu are losing ground to direct digital channels and embedded bank offerings. This consolidation is most visible among Estonia's technology services sector, where founders prioritize governance and cyber protection alongside traditional property coverage.
Estonia Property and Casualty Insurance Market Segmentation
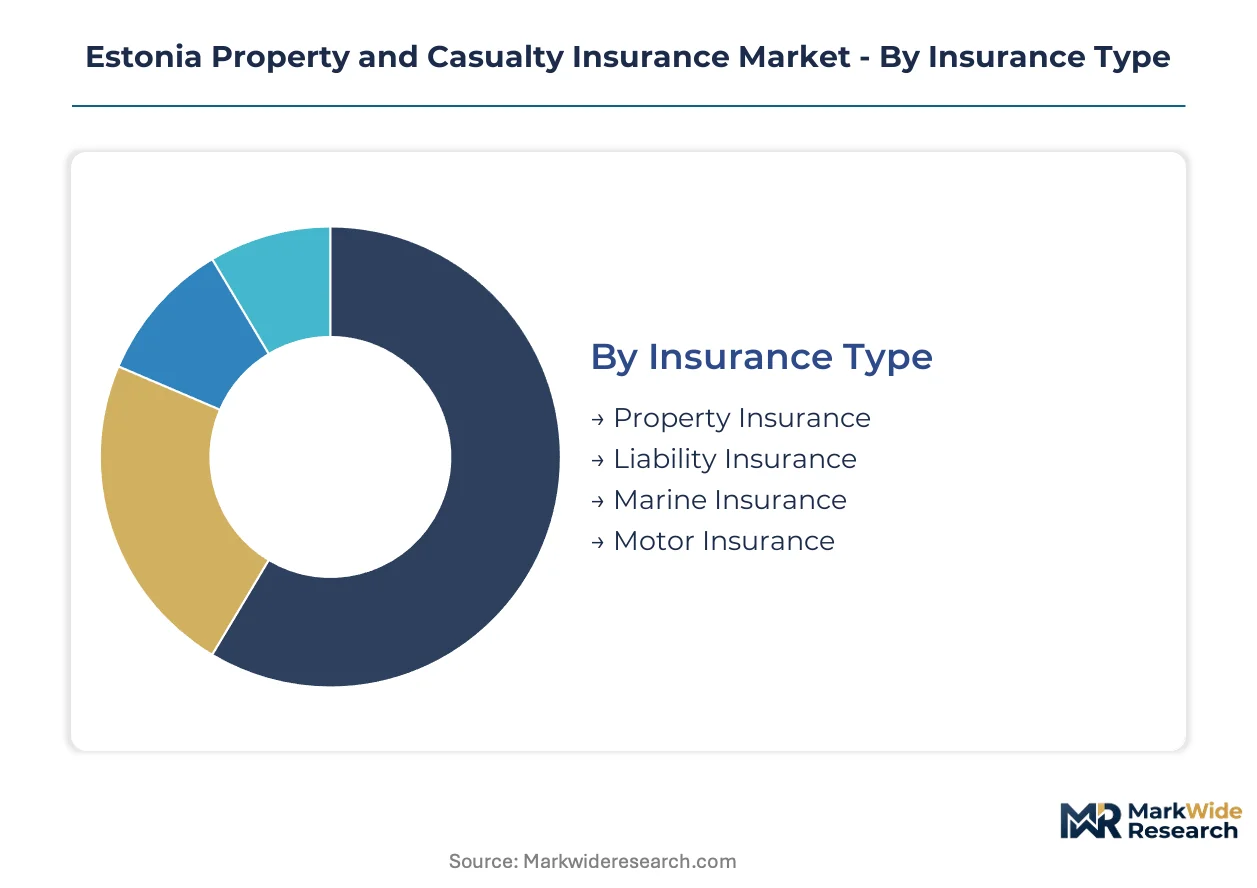
Segmentation in Estonia's property and casualty market reveals how Solvency II capital requirements and Tallinn-Tartu economic concentration reshape carrier product architectures. Each dimension exposes distinct margin pools and distribution friction points.
Insurance Type:
Motor and property lines concentrate premium volume where vehicle fleet density and commercial construction activity overlap.
- Property Insurance:Commercial property policies indemnify physical asset damage from fire, flood, and operational interruption. Tallinn's office development pipeline and Tartu logistics facilities concentrate demand as developers seek construction-phase and completed-operations coverage.
- Motor Insurance:Statutory third-party liability coverage mandated by the Estonian Traffic Insurance Fund dominates premium generation. Fleet operators in Tallinn adopt telematics-enabled pricing as real-time driving behavior monitoring displaces conventional demographic rating factors.
- Liability Insurance:Legal exposure protection spans professional indemnity and product liability. Technology startups scaling governance risk accelerate directors-and-officers procurement.
- Marine Insurance:Hull and cargo coverage serves Estonia's Baltic port operations. Tallinn Harbour throughput volumes determine policy structuring complexity.
Motor Insurance holds installed capacity. Liability Insurance is rotating up the share rankings.
Client Segment:
Distribution economics favor embedded banking channels for high-frequency retail transactions while commercial lines require specialized risk-engineering relationships.
- Individuals:Personal lines span home, auto, and travel coverage. Swedbank P&C Insurance's retail banking integration captures household premium flows through account-linked policy administration.
- Small Businesses:Operational risk bundling consolidates previously discrete single-peril procurement. Tartu-based technology founders prioritize governance and cyber protection alongside traditional property coverage.
- Large Corporations:Complex risk-transfer structures demand Nordic carrier risk-engineering heritage. IF P&C Insurance dominates commercial property lines through centralized account management.
- Government Entities:Public asset coverage and liability pools require statutory procurement frameworks. Municipal infrastructure exposure concentrates in Tallinn and Tartu administrative boundaries.
Individuals hold installed capacity. Small Businesses is rotating up the share rankings.
Coverage Area:
EU Common Agricultural Policy subsidies reshape margin distribution between rural and urban coverage pools.
- Home Coverage:Residential property and contents protection against named perils. Urban concentration in Tallinn owner-occupied stock drives standardization.
- Auto Coverage:Vehicle physical damage and theft protection supplements mandatory liability. Telematics adoption compresses premium variance between risk tiers.
- Commercial Property:Business interruption and asset protection for corporate portfolios. New construction in Tallinn's Ülemiste City district accelerates engineered-risk policy growth.
- Agricultural Insurance:Crop and livestock coverage benefits from CAP premium subsidies. Farm consolidation trends expand average policy size while compressing underwriting margins.
Home Coverage holds installed capacity. Commercial Property is rotating up the share rankings.
Policy Duration:
Multi-year structures unwind legacy annual renewal conventions while introducing actuarial complexity for emerging risk categories.
- One-Year:Traditional annual contract cycles dominate personal lines administration. Regulatory familiarity simplifies capital reserve calibration under Solvency II.
- Multi-Year:Comprehensive coverage tiers enable premium stability and customer retention gains. Commercial property expansion favors extended duration for construction-phase risks.
- Short-Term:Event-specific and travel coverage addresses temporary exposure windows. Digital distribution channels reduce acquisition friction for transactional purchases.
- Long-Term:Extended liability protection spans professional indemnity tail coverage. Technology sector directors-and-officers policies require duration extension as venture-backed firms mature.
One-Year holds installed capacity. Multi-Year is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic carrier balance sheets concentrate in Tallinn and Tartu, where commercial construction and fleet density generate premium volume. Solvency II harmonization is compressing capital timelines across Estonia's insurance sector while redistributing underwriting capacity toward multi-year commercial structures.
Tallinn
Tallinn's Ülemiste City office development and logistics corridor concentrate commercial property demand. Estonia's Financial Supervision and Resolution Authority enforces risk-based capital standards that reshape reserve calibration for Tallinn-domiciled carriers. The capital's technology startup density accelerates directors-and-officers liability procurement among venture-backed firms.
Tartu
Tartu's university-driven research ecosystem and emerging logistics hub status expand operational risk coverage needs. The Estonian Traffic Insurance Fund mandates statutory motor third-party liability, compressing premium variance through telematics adoption among Tartu fleet operators. Agricultural consolidation in surrounding counties channels EU Common Agricultural Policy subsidized coverage through regional broker networks.
Pärnu
Pärnu's coastal tourism economy and port operations generate marine and hospitality liability exposure. Pending natural catastrophe risk pool legislation threatens to redistribute flood and storm liability across carriers writing Pärnu county risks. The city's seasonal business cycle favors short-term event coverage over annual contract structures.
Ida-Viru
Ida-Viru's industrial heritage and energy transition create legacy asset coverage complexity. GDPR and the EU AI Act reshape cyber liability product architectures for regional manufacturing digitization. Narva's border proximity concentrates cross-border motor fleet exposure requiring harmonized Baltic underwriting protocols.
Estonia Property and Casualty Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Estonia's property and casualty sector. Nordic heritage carriers with risk-engineering capabilities dominate commercial property lines, while banking-embedded distributors capture retail household flows. The market structures around three strategic archetypes: integrated Nordic groups, domestic banking subsidiaries, and specialized agricultural underwriters. Competitive moves center on multi-year contract restructuring and embedded distribution partnerships rather than capacity expansion.
Among Nordic-heritage commercial lines specialists, IF P&C Insurance exemplifies risk-engineering depth in Tallinn corporate accounts. Swedbank P&C Insurance anchors retail penetration through banking channel integration. ERGO Insurance occupies the agricultural specialization tier, leveraging EU subsidy structures for farm consolidation coverage. These three carriers represent distinct competitive vectors—engineering heritage, distribution integration, and subsidy-optimized specialization—rather than overlapping strategic positions.
| Leading Market Players |
|---|
| IF P&C Insurance |
| ERGO Insurance |
| Swedbank P&C Insurance |
| AB Lietuvos draudimas |
| Compensa Vienna Insurance Group |
| BTA Baltic Insurance Company |
| Salva Kindlustus |
| LHV Kindlustus |
| Inges Kindlustus |
| Others |
Pricing and Supply Chain Analysis
Solvency II capital adequacy thresholds gate both carrier qualification and premium tier differentiation simultaneously. Estonian insurers must maintain risk-based reserves that compress margin flexibility for smaller domestic players while enabling Nordic-heritage carriers to price extended-duration commercial contracts at structural premiums.
Pricing Analysis
Solvency II dictates the pricing tier structure across Estonia's property and casualty sector. Three-tier pricing stratifies across premium risk-engineered commercial lines, standard retail household coverage, and economy motor third-party liability. Price differentiation stems from certification depth under Finantsinspektsioon supervision and geographic delivery costs between Tallinn-Tartu corridors versus rural counties. Cost compression in agricultural lines is intensifying because EU CAP subsidies cap premium growth while loss ratios climb. Small businesses demonstrate highest price sensitivity as bundled operational risk procurement consolidates previously discrete policies.
Supply Chain Analysis
Actuarial talent concentration in Nordic capitals underwrites Estonia's risk-modeling capacity. Domestic carriers draw from Copenhagen, Stockholm, and Helsinki for probabilistic loss expertise while sourcing core IT infrastructure from Tallinn's technology cluster. Raw material dependencies span proprietary catastrophe datasets, telematics hardware, and cloud compute infrastructure. Single-source vulnerability concentrates in Nordic parent-company reinsurance arrangements. Distribution runs through embedded banking channels, independent broker networks, and direct digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Estonia's property and casualty market operates as a service-attach opportunity where multi-year contract administration and embedded risk-engineering advisory expand faster than standalone premium generation.
For Market Incumbents: Compound defensive positioning through captive reinsurance capacity and proprietary telematics data infrastructure. IF P&C Insurance's Nordic risk-engineering heritage provides template for consolidating Tallinn corporate accounts against Baltic competitor encroachment. Invest in real-time policy administration platforms to reduce legacy system friction. Solvency II reporting automation is the priority capability gap to close. For New Entrants and Emerging Players: Anchor in Tartu's technology startup ecosystem where directors-and-officers coverage demand outpaces incumbent response capacity. Cyber liability product white space offers penetrable entry vector given GDPR and EU AI Act compliance complexity. Pursue direct digital distribution to bypass embedded banking channel control held by Swedbank P&C Insurance. Agricultural coverage subsidies present volume foundation despite compressed margins. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-year commercial property lines as Solvency II reserve requirements extend duration risk. Long-term viability over the next decade favors carriers with Nordic parent-company reinsurance backing and embedded distribution scale. Acquisition target archetype: domestic insurers with established Finantsinspektsioon licensing but underutilized risk-engineering relationships. Monitor Estonia's pending natural catastrophe risk pool legislation as signal for balance sheet redistribution timing.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Contract Restructuring | Premium stability gains through Tallinn construction-phase coverage extension reduce renewal friction. |
| Embedded Banking Partnership | Swedbank P&C Insurance's account-linked policy administration demonstrates retail penetration pathway. |
| Cyber Liability Product Launch | GDPR and EU AI Act mandates create compliance-driven demand from technology startup segment. |
| Telematics Infrastructure Investment | Real-time driving behavior monitoring compresses premium variance for Tallinn fleet operators. |
| Agricultural Consolidation Coverage | EU CAP subsidies support farm consolidation trends expanding average policy size in Tartu counties. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to construct this analysis. Primary interviews captured perspectives from property underwriters at Nordic-heritage carriers, risk managers at Tallinn technology startups, agricultural brokers in Tartu counties, and Finantsinspektsioon supervisory officials. Secondary validation drew from EU Solvency II regulatory filings, Estonian Traffic Insurance Fund statistical releases, EU Common Agricultural Policy implementation reports, and Nordic insurance group annual disclosures. Bottom-up premium volume estimates triangulated against top-down macroeconomic exposure calculations.
Across the analysis window, value projections reflect segmented modeling across insurance type, client segment, coverage area, and policy duration dimensions. CAGRs were derived through regression analysis of historical premium growth correlated with vehicle fleet expansion, commercial construction permitting, and farm consolidation trajectories. Industry-specific forecast inputs incorporated telematics adoption curves and EU AI Act implementation timelines.
Material uncertainties — pending natural catastrophe risk pool legislation, cyber liability claims development, and Solvency II capital requirement recalibration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and loss ratio continuity. Practitioners should keep alternative scenarios live as flood and storm exposure redistribution mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Canada Property and Casualty Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Aviation Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Europe Extended Warranty Market
Insurance
United States Dental Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
Aerospace Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
AI in Insurance Market