
 Titanium Thermos Cup Market | 2026-2036
Titanium Thermos Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Thermos Cup Market Insights
ISO 22000 certification for food-contact material safety is bifurcating the competitive landscape into qualified suppliers and marginal participants. Stanley leverages its North American retail footprint to sustain premium positioning across outdoor and commuter channels. JIZHI TITANIUM INDUSTRY anchors its cost structure through captive titanium sponge sourcing from domestic Chinese producers. Horie differentiates via precision-drawn single-wall construction techniques refined for the Japanese consumer market.
A titanium thermos cup denotes a vacuum-insulated beverage container fabricated from commercially pure titanium or Ti-6Al-4V alloy, typically featuring double-walled construction with evacuated interstitial space and weld-sealed bases to achieve thermal retention exceeding six hours. The double-walled product category dominates value capture due to manufacturing complexity and performance premiums, while collapsible variants occupy a niche among ultralight backpackers prioritizing packability over durability. Online retail channels now lead volume growth as direct-to-consumer brands bypass traditional wholesale markups, though specialty stores retain margin concentration through experiential merchandising and customization services.
China's SAMR enforces GB 4806 series standards for food-contact metals, directly shaping alloy purity requirements and surface treatment protocols for domestic manufacturers. The EU REACH regulation and F-Gas framework indirectly influence thermal insulation technology choices by restricting certain blowing agents used in vacuum panel alternatives. Japan's METI administers JIS standards that govern titanium material grading for consumer goods, creating a compliance threshold for export-oriented suppliers. Stakeholders must monitor evolving chemical migration limits across multiple jurisdictions to anticipate reformulation costs and certification timelines.
Market Dynamics
ISO 22000 certification requirements are splitting qualified suppliers from marginal participants across food-contact titanium manufacturing, reshaping competitive viability and procurement screening protocols.
Growth Catalysts
- Adventure Tourism Expansion:Participation in backcountry trekking and alpine climbing drives specialized gear procurement from outdoor retailers prioritizing weight reduction and thermal performance.
- REACH Chemical Migration Limits:The EU's tightened substance restrictions on heavy metal leaching elevate titanium's substitution appeal against coated stainless alternatives in European consumer markets.
- Baoji Processing Cluster Concentration:China's Shaanxi province hosts integrated titanium sponge-to-finished-goods capacity that compresses lead times for vacuum-insulated vessel fabrication.
Market Restraints
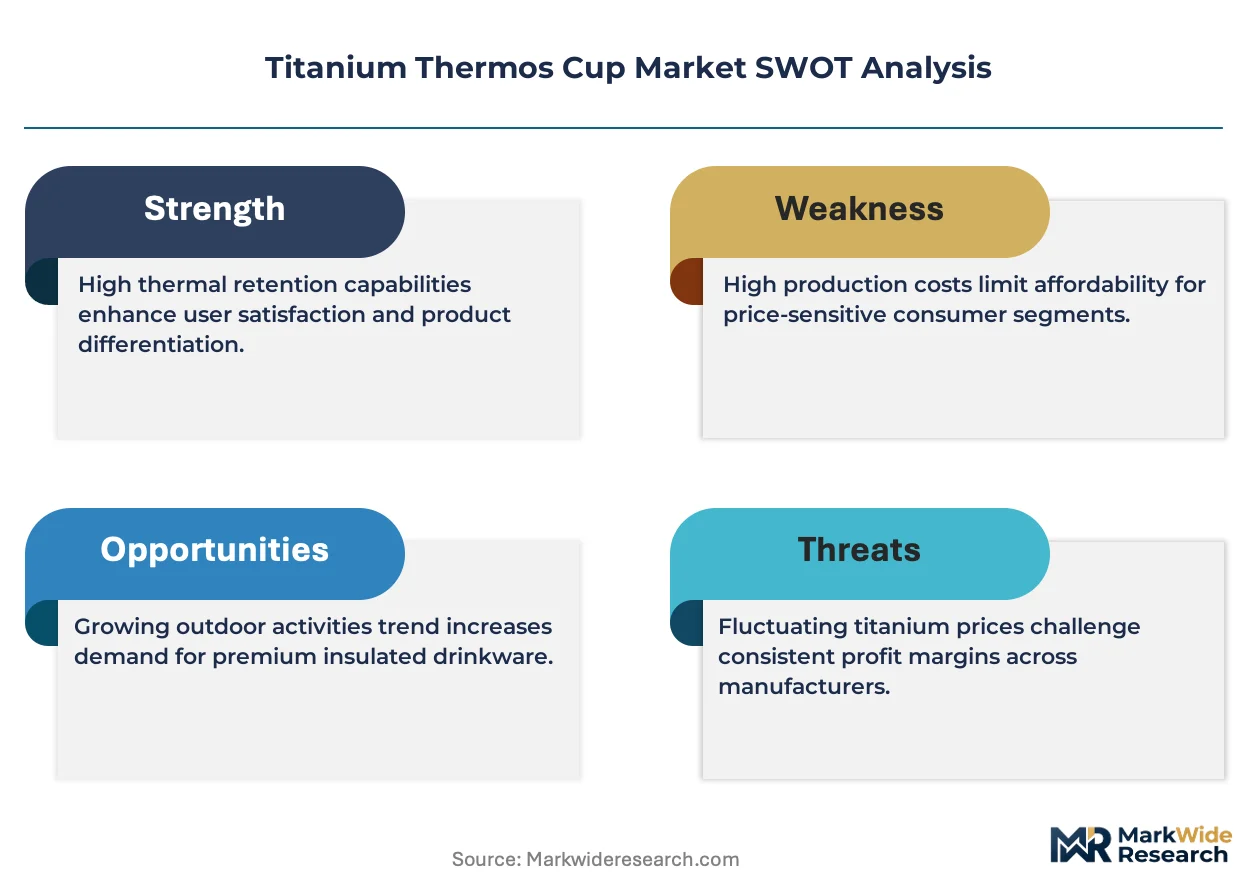
- Sponge Price Volatility:Titanium sponge input costs fluctuate with aerospace demand cycles, squeezing margin predictability for commodity-grade thermos producers lacking long-term supply contracts.
- Single-Source Vacuum Equipment:Specialized electron beam welding systems for double-walled sealing concentrate among Japanese and German equipment builders, creating procurement bottlenecks.
- Coated Aluminum Substitution:Anodized aluminum vessels at one-third the material cost capture price-sensitive commuter segments where thermal retention demands are moderate.
Strategic Opportunities
- India Urban Commuter Segment:Metro rail expansion in Mumbai, Delhi, and Bangalore creates daily-use thermal vessel demand among white-collar workers seeking reusable alternatives to disposable cups.
- GB 4806 Compliance Arbitrage:China's SAMR enforcement of stricter food-contact metal standards positions certified domestic exporters to capture share from uncertified regional competitors in Southeast Asian markets.
- Direct-to-Consumer Channel Migration:Brand-owned e-commerce platforms bypass wholesale markups while capturing first-party consumption data for personalization and subscription offerings.
Industry Challenges
- Vacuum Technician Scarcity:Electron beam welding and leak detection expertise concentrates among aging specialists in Japanese and German industrial centers, constraining quality throughput expansion.
- Dual Certification Timelines:Simultaneous GB 4806, REACH, and FDA compliance documentation extends product launch cycles by 8-14 months for multi-jurisdiction distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Thermos Cup Market |
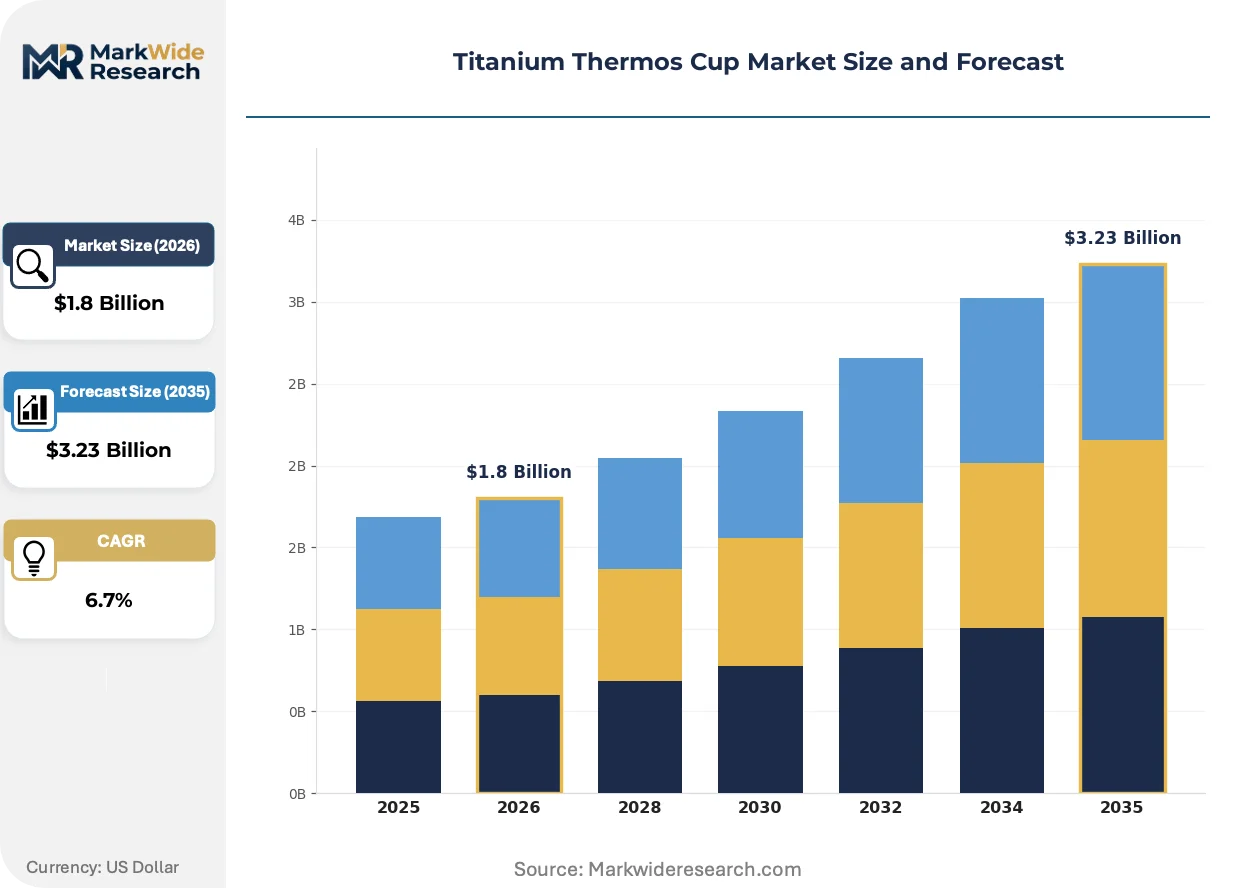
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Walled, Insulated, Collapsible, Standard End User: Outdoor Enthusiasts, Office Workers, Travelers, Athletes Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers Design Feature: Lightweight, Eco-Friendly, Customizable, Non-Stick |
| Companies Covered | Stanley, HEENOOR, SANTECO, Horie, JIZHI TITANIUM INDUSTRY, TAIC, FEIJIAN, Leidfor, Thermos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Thermos Cup Market Trends and Innovations
Material science advances and channel restructuring are compressing traditional manufacturing advantages while elevating performance differentiation as the primary competitive lever.
Laser-welded seamless inner chambers are supplanting traditional rolled-and-seamed construction in premium double-walled vessels. Ultralight backpacking specialists and alpine guides adopt these units despite 40-60% price premiums. The shift is compressing mid-tier supplier margins while rewarding capital-intensive precision fabricators with technical differentiation.
The EU F-Gas Regulation restricts hydrofluorocarbon blowing agents in vacuum panel alternatives, indirectly reinforcing demand for evacuated double-wall construction. Manufacturers face reformulation costs for any hybrid insulation approaches. Asian export-oriented suppliers accelerate pure vacuum technology investment to preempt compliance-driven exclusion from European distribution.
Specialty outdoor retailers now unbundle after-sales repair and recertification services from initial product sales, creating recurring revenue attachments. Direct-to-consumer brands disrupt this model with lifetime warranty replacements that eliminate service infrastructure. North American and Japanese markets exhibit the sharpest channel friction as these models compete for identical buyer segments.
Titanium Thermos Cup Market Segmentation
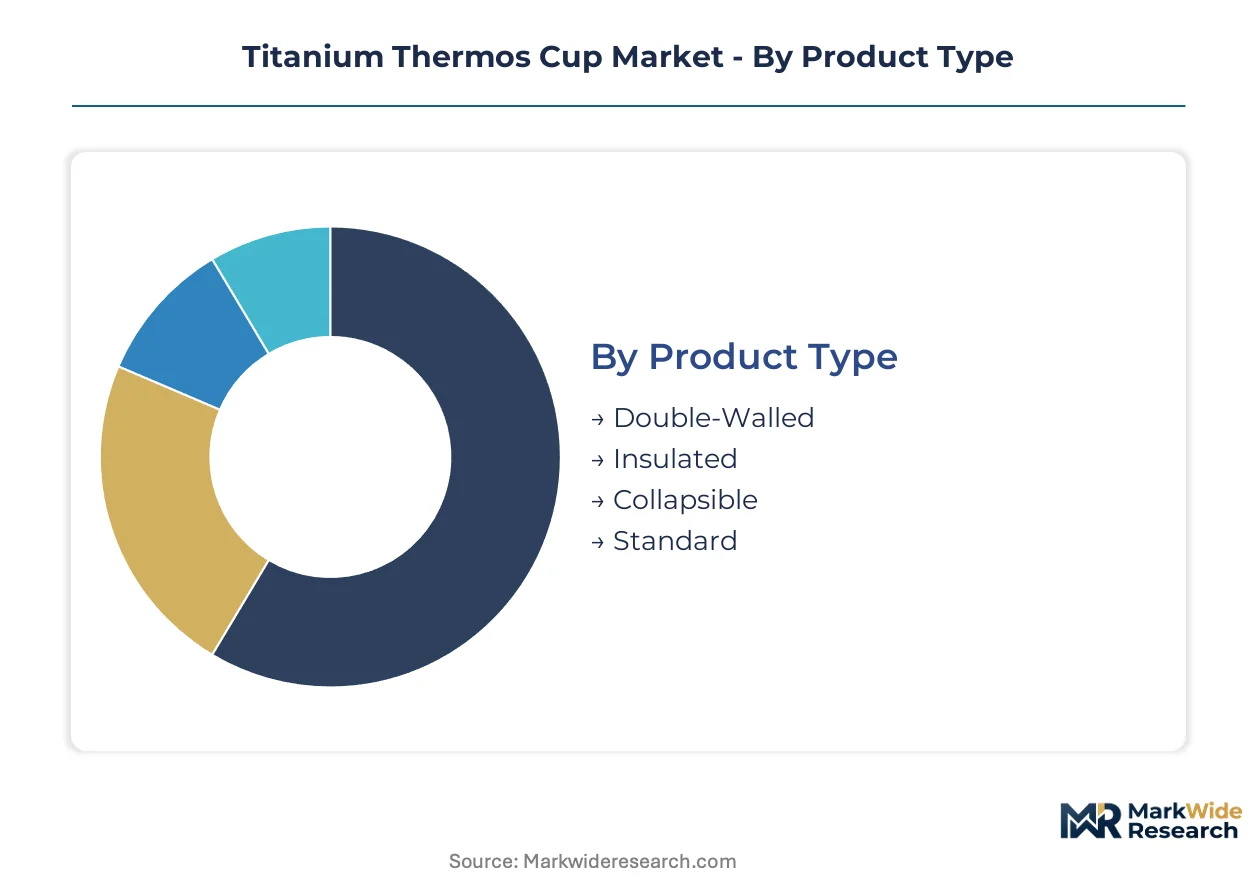
Titanium thermos cup segmentation reveals distinct vulnerability profiles across product architectures and buyer missions. Substitution pressure from coated aluminum and stainless alternatives varies sharply by thermal performance tier and weight sensitivity.
Product Type:
Double-walled evacuated construction faces intensifying substitution pressure from hybrid insulation technologies, while collapsible formats defend niche positions through packability premiums that aluminum cannot replicate.
- Double-Walled:Vacuum-sealed dual-chamber construction utilizing electron beam welding achieves thermal retention exceeding six hours. Demand concentrates among alpine climbers and backcountry guides in Japan and Switzerland where METI and Swissmedic-aligned safety certifications command premium positioning against stainless competitors.
- Insulated:Hybrid vacuum-plus-reflective barrier systems optimize weight-to-performance ratios for extended expeditions. European outdoor retailers prioritize these units as EU F-Gas Regulation restrictions eliminate hydrofluorocarbon panel alternatives.
- Collapsible:Telescoping titanium segments reduce packed volume by 60% for ultralight backpackers.
- Standard:Single-wall uninsulated vessels serve price-conscious commuters with moderate thermal demands.
Double-walled construction anchors the volume base while collapsible formats gain share at the steepest rate among specialized adventure tourism operators.
End User:
Office worker demand concentrates in cost-sensitive volume tiers where anodized aluminum substitution is most acute, while outdoor enthusiast budgets tolerate material premiums that protect titanium positioning.
- Outdoor Enthusiasts:Backcountry trekkers and alpine climbers prioritize weight reduction and corrosion resistance in high-humidity environments. China's Baoji manufacturing cluster ships disproportionately to Japanese and German specialty retailers serving this segment.
- Office Workers:Daily commuters seeking reusable alternatives to disposable cups dominate unit volumes in India and China's metro rail corridors. Price sensitivity here exposes titanium to coated aluminum displacement where thermal retention demands are moderate.
- Travelers:Frequent flyers and rail passengers value TSA-friendly capacities and leak-proof sealing mechanisms.
- Athletes:Endurance sports participants require rapid-cooling single-wall options for electrolyte mixing.
Office workers drive absolute volume shipments while outdoor enthusiasts sustain margin concentration through certification-premium acceptance.
Distribution Channel:
Channel cost structures determine which product tiers reach end buyers, with online retail compression threatening specialty store viability in North American markets.
- Online Retail:Direct-to-consumer platforms bypass wholesale markups while capturing first-party consumption data. Indian urban commuters and Chinese tier-two city buyers increasingly purchase through brand-owned storefronts rather than third-party marketplaces.
- Specialty Stores:Experiential merchandising with customization services sustains premium positioning in Japanese and German mountaineering retail.
- Supermarkets:Mass retail placement reaches price-elastic commuter segments with limited technical specifications.
- Wholesalers:Bulk procurement channels serve corporate gifting and institutional catering accounts.
Online retail channels capture volume leadership while specialty stores defend margin concentration through service attachment.
Design Feature:
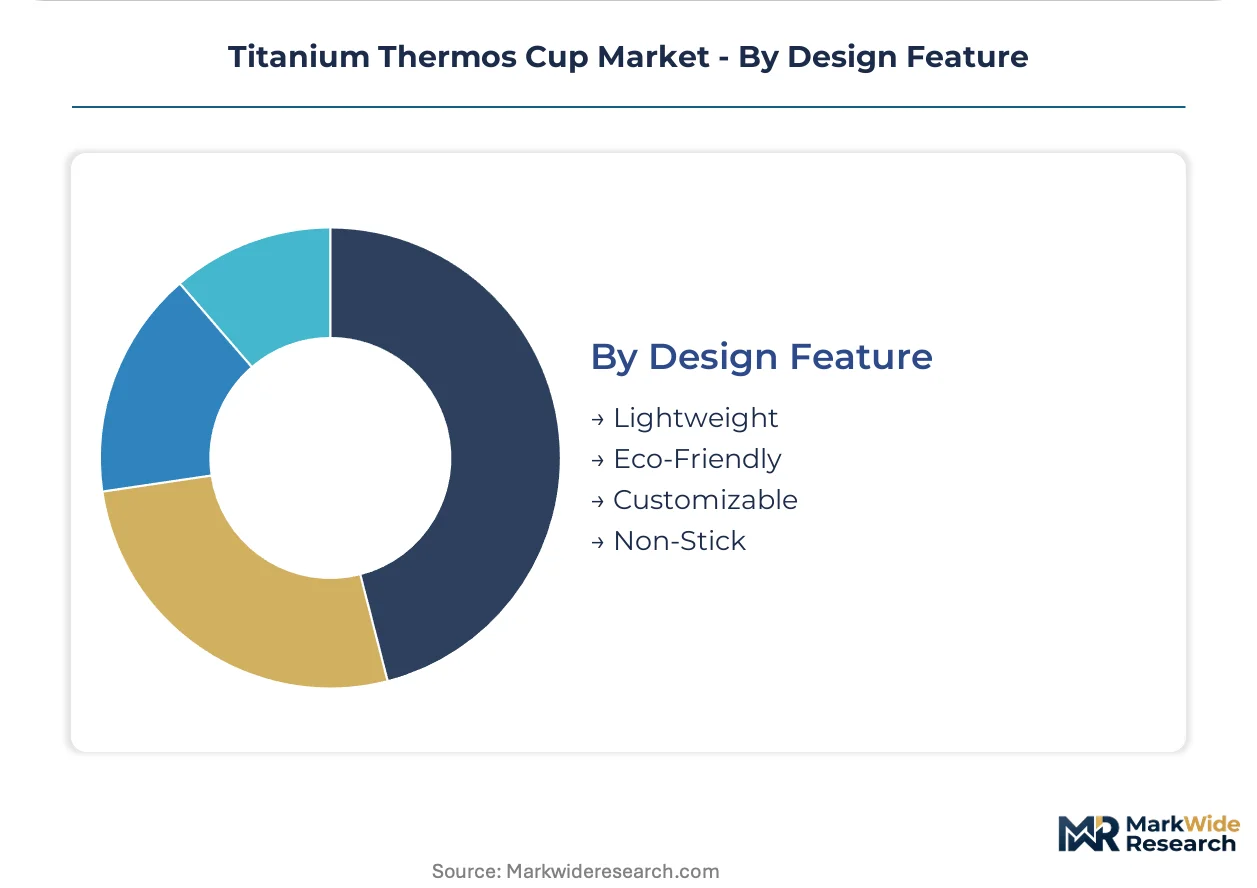
Weight and sustainability positioning create differentiation vectors that aluminum and stainless competitors struggle to replicate at equivalent performance tiers.
- Lightweight:Precision-drawn thin-wall construction below 0.4mm thickness achieves sub-200 gram finished weights. Japanese alpine guides and Swiss SAR operators specify these units for multi-day load-bearing efficiency.
- Eco-Friendly:Uncoated pure titanium eliminates chemical migration risks under China's GB 4806 and EU REACH frameworks. European buyers increasingly screen for SAMR-certified suppliers to preempt regulatory exclusion.
- Customizable:Laser engraving and anodized color treatments serve corporate gifting and expedition team identification.
- Non-Stick:Electropolished interior surfaces reduce beverage residue adhesion for dairy and electrolyte mixing.
Lightweight specifications anchor technical differentiation while eco-friendly positioning gains share fastest among regulatory-sensitive European procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Outdoor enthusiasts cluster in alpine economies and dense urban corridors where weight-sensitive gear commands premium positioning. Japan's METI-certified fabricators and China's Baoji processing cluster anchor supply-side capacity. Regulatory divergence across FDA, REACH, and GB 4806 standards fragments certification requirements.
China
Baoji's titanium sponge-to-finished-goods corridor supplies vacuum-insulated vessels to Japanese and German specialty retailers. SAMR enforces GB 4806 series standards that dictate alloy purity thresholds for food-contact surfaces. The Shaanxi province cluster compresses lead times through captive sponge sourcing from domestic producers.
Japan
Alpine guides and SAR operators in Nagano and Hokkaido drive demand for sub-200 gram precision-drawn vessels. METI administers JIS material grading standards that create export compliance thresholds for foreign suppliers. Osaka-based fabricators refine single-wall construction techniques for domestic ultralight segments.
Germany
EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents reinforce evacuated double-wall demand among Bavarian outdoor retailers. ECHA's REACH framework governs chemical migration limits that elevate titanium substitution against coated stainless alternatives. Munich mountaineering shops sustain premium positioning through experiential merchandising.
United States
North American outdoor retailers leverage direct-to-consumer platforms to bypass wholesale markups in Colorado and Pacific Northwest trekking corridors. FDA food-contact material requirements shape import screening protocols for Asian suppliers. Portland and Denver specialty stores compete with brand-owned e-commerce for identical buyer segments.
India
Mumbai, Delhi, and Bangalore metro expansions generate daily-use thermal vessel demand among white-collar commuters seeking reusable alternatives. BIS standards for food-contact metals remain less stringent than GB or REACH equivalents, exposing the market to coated aluminum displacement. Domestic procurement channels serve institutional gifting accounts through wholesale bulk arrangements.
Titanium Thermos Cup Market Competitive Landscape
Player mix skews toward vertically integrated titanium processors and brand-licensed outdoor specialists. The vendor base concentrates around three tiers: captive-sponge fabricators with cost structure advantages, precision-drawn specialists serving alpine segments, and brand aggregators leveraging North American retail footprints. Strategic moves center on backward integration into sponge supply and direct-to-consumer channel migration to capture first-party data.
Within the precision-fabrication tier, Horie exemplifies Japanese single-wall construction specialization refined for domestic alpine demand. JIZHI TITANIUM INDUSTRY anchors cost positioning through upstream control over domestic sponge sourcing. Stanley occupies a position as a brand aggregator leveraging established North American retail distribution. These three archetypes represent the dominant competitive vectors: technical differentiation, supply chain control, and channel scale.
| Leading Market Players |
|---|
| Stanley |
| HEENOOR |
| SANTECO |
| Horie |
| JIZHI TITANIUM INDUSTRY |
| TAIC |
| FEIJIAN |
| Leidfor |
| Thermos |
| Others |
Pricing and Supply Chain Analysis
Long-term sponge supply offtakes with aerospace-indexed pricing lock in both raw material access and cost visibility for Baoji-based fabricators serving Japanese and German specialty retailers. These contracts insulate qualified suppliers from titanium sponge volatility while marginal participants absorb spot market swings that compress margins on commodity-grade double-walled vessels.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked indexation dominate procurement between Chinese sponge producers and vacuum vessel fabricators. Price differentiation rests on ISO 22000 certification tier and electron beam welding precision grade. Pricing pressure stems from coated aluminum substitution in Indian commuter segments where thermal retention demands are moderate. Office workers exhibit highest price sensitivity; alpine guides and SAR operators accept premiums for METI-certified sub-200 gram specifications.
Supply Chain Analysis
Specialized electron beam welding equipment from Japanese and German builders creates a chokepoint constraining quality throughput expansion for double-walled sealing. Raw material sourcing draws from Chinese sponge producers, Japanese precision alloy specialists, and Ukrainian titanium feedstock processors. Single-source equipment vulnerability concentrates fabrication capacity among aging technician pools in Osaka and Munich. Distribution runs through brand-owned direct-to-consumer platforms and Japanese mountaineering specialty retailers with experiential service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales repair and recertification services now expand faster than hardware shipments as specialty retailers unbundle maintenance from initial sales. This service-attach layer offers recurring revenue that direct-to-consumer lifetime warranty models disrupt but cannot fully replicate.
For Market Incumbents: Secure captive sponge sourcing through backward integration into domestic Chinese producers or long-term offtakes with Baoji processors. Lock in electron beam welding technician pipelines through apprenticeship partnerships with Osaka and Munich industrial centers to defend against quality throughput constraints from aging specialist pools. For New Entrants and Emerging Players: Repair network density in North American trekking corridors offers a service-layer gap where incumbent specialty retailers under-serve remote backcountry users. Target Colorado and Pacific Northwest alpine guides with mobile recertification units and expedition-season maintenance subscriptions as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Precision-drawn single-wall specialists with JIS certification and Japanese domestic distribution relationships represent the optimal acquisition target archetype. These fabricators command durable positioning against commodity-grade Chinese exports. Monitor electron beam welding equipment lead times as an inflection indicator for supply-constrained premium tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sponge Supply | Captive sourcing from Baoji producers insulates margin predictability against aerospace demand cycles. |
| Direct-to-Consumer Platform Launch | Brand-owned e-commerce captures first-party consumption data for personalization in Indian commuter segments. |
| ISO 22000 Certification Investment | Food-contact safety qualification bifurcates competitive viability between qualified and marginal suppliers. |
| After-Sales Service Network Expansion | Repair and recertification attachments defend specialty retail margins against warranty-disruption models. |
| Ultralight Precision Product Line Introduction | Sub-200 gram specifications capture alpine guide demand with 40-60% price premiums over standard tiers. |
Research Methodology
Desk research of customs trade databases, SAMR certification registries, and METI JIS standard filings preceded structured interviews with vacuum equipment engineers, specialty outdoor retail buyers, titanium sponge procurement managers, and electron beam welding technicians. Primary fieldwork with Baoji fabricators and Osaka precision metalworkers was cross-validated against secondary data from ECHA REACH substance restriction updates and EU F-Gas Regulation implementation guidance. Bottom-up shipment analysis by product architecture and end-use mission was triangulated against top-down value estimates from channel margin structures.
Variance decomposition across product type, end user mission, distribution channel, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories weighted by certification-premium pricing tiers across the projection horizon. Forecast inputs incorporated sponge price cycle assumptions, electron beam welding capacity constraints, and channel migration rates from specialty retail to direct-to-consumer platforms.
Forecasts assume regulatory continuity in SAMR GB 4806 enforcement, ECHA REACH chemical migration limits, and METI JIS material grading standards; material policy shifts would require re-modeling alloy purity thresholds and surface treatment protocols. Practitioners should keep alternative scenarios live as EU F-Gas Regulation restrictions on hybrid insulation technologies and Indian BIS standard tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Washing Machine Cleaner Market
Household Items
US Hand Dryers Market
Household Items
Hands-Free Faucet Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Luxury Massage Chair Market
Household Items
Replacement Sheets Market
Household Items
Powered Lawn Mowers Market
Household Items
Electric Soap Dispenser Market
Household Items
Flatware Market
Household Items
Sanitary Metal Ware Market
Household Items
Insulated Drinkware Market
Household Items
Kick Bucket Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Lunch Box Market
Household Items
Hangers Market