
 Insulated Drinkware Market | 2026-2036
Insulated Drinkware Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Drinkware Market Analytics
Modular lid systems and interchangeable accessories is realigning how consumers evaluate insulated drinkware purchases. YETI leverages its premium brand architecture to command shelf positioning in specialty retail. Hydro Flask sustains R&D intensity around color coatings and powder-finish durability. Stanley anchors volume through heritage positioning in foodservice and institutional channels.
Insulated drinkware comprises vessels engineered with vacuum-sealed or double-wall construction to maintain beverage temperature, typically fabricated from 18/8 stainless steel with copper-lined vacuum chambers achieving thermal retention for six to twelve hours. The primary commercial purpose spans portable hydration, food temperature preservation, and reduction of disposable container dependency across consumer and institutional settings. Stainless steel dominates material value due to recyclability and dent resistance, while vacuum insulation leads feature-based premiumization. Tumblers capture the fastest-growing product configuration as commuter-oriented formats displace traditional mugs in workplace and vehicle contexts.
REACH compliance in Europe governs chemical migration limits from coatings and seals, while FDA regulations in the United States dictate food-contact material safety for stainless steel and polypropylene components. China's GB standards enforce nickel and chromium leaching thresholds that shape export manufacturing protocols. Stakeholders must monitor evolving extended producer responsibility frameworks that could mandate take-back programs and recycled content minimums.
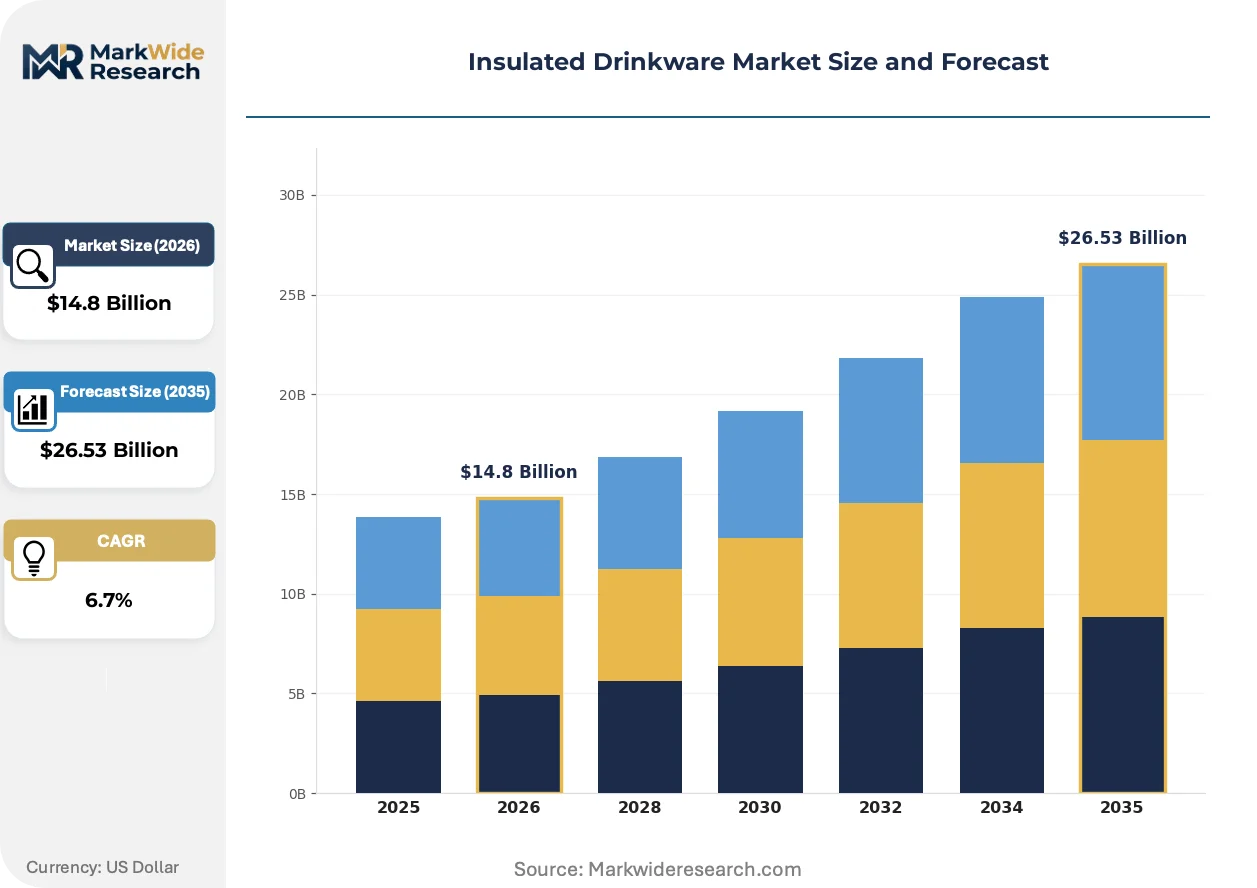
Market Dynamics
Stainless steel vacuum insulation technology is displacing single-use alternatives across consumer and institutional channels, while REACH compliance in Europe and FDA food-contact regulations in the United States reshape manufacturing protocols and material sourcing requirements.
Growth Catalysts
- Outdoor Recreation Expansion:Camping and hiking participation in the United States, Germany, and China is pulling demand for portable temperature-retention vessels into premium price tiers.
- Extended Producer Responsibility Frameworks:EU Green Deal mandates and emerging take-back programs across European member states are accelerating brand investment in recyclable stainless steel formats.
- Commuter Format Migration:Workplace beverage consumption patterns favor tumbler configurations with vehicle-cup-holder compatibility over traditional handled mugs.
Market Restraints
- Nickel Price Volatility:18/8 stainless steel input costs fluctuate with London Metal Exchange nickel pricing, compressing margin buffers for mid-tier manufacturers.
- Coating Compliance Burden:ECHA REACH chemical migration limits for powder finishes and seals extend product development timelines by eight to fourteen months.
- Copper Supply Concentration:Vacuum chamber lining material depends on Chilean and Peruvian mining output, exposing producers to geopolitical supply interruptions.
Strategic Opportunities
- Institutional Channel Penetration:Foodservice operations in Germany and China remain underpenetrated for branded vacuum-insulated formats, presenting volume expansion potential.
- Interchangeable Accessory Ecosystems:Modular lid systems converging with hydration-tracking sensor technology open recurring revenue streams through attach-rate expansion.
- China GB Standard Alignment:Export manufacturers certifying to nickel and chromium leaching thresholds gain preferential access to domestic Chinese distribution networks.
Industry Challenges
- Vacuum Seal Technician Scarcity:Specialized welding and chamber-assembly skills required for copper-lined construction outpace vocational training program output in manufacturing clusters.
- Cross-Border Certification Parallel Processing:Simultaneous FDA, REACH, and GB standard compliance creates documentation complexity and testing cost duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Drinkware Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Glass, Plastic, Aluminum Product Type: Tumblers, Water Bottles, Mugs, Flasks End User: Consumers, Outdoor Enthusiasts, Athletes, Businesses Feature: Vacuum Insulation, Double Wall, BPA-Free, Leak Proof |
| Companies Covered | Thermos, Contigo, YETI, KINGSTAR, Everich, Stanley, CamelBak, Gint, Hydro Flask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Drinkware Market Evolving Landscape
Product architecture is fragmenting into configurable systems while regulatory pressure on material safety intensifies, and buyer procurement patterns favor direct-channel relationships over wholesale intermediation.
Copper-lined vacuum chamber construction is modularizing across manufacturer product lines. Outdoor enthusiasts and commuter segments adopt interchangeable base-vessel and lid-component configurations at accelerating rates. This technology is modularizing the traditional integrated-vessel value chain, enabling component-level margin capture and repair-service revenue streams previously inaccessible to drinkware producers.
REACH chemical migration limits govern coatings and polypropylene seals in European markets. Manufacturers reformulate powder-finish chemistries and substitute fluoropolymer alternatives to maintain market access. Premium-positioned brands with in-house coating R&D capabilities absorb compliance costs more efficiently than contract-manufacturing-dependent competitors.
Direct-to-consumer channel relationships are compressing wholesale intermediary roles across United States and German markets. Specialty outdoor retailers and workplace procurement platforms consolidate supplier relationships around fewer vendors with configurable product ecosystems. This concentration is most visible in corporate gifting and employee wellness program verticals, where bulk customization requirements favor manufacturers with in-house decoration and laser-etching capabilities.
Insulated Drinkware Market Segmentation
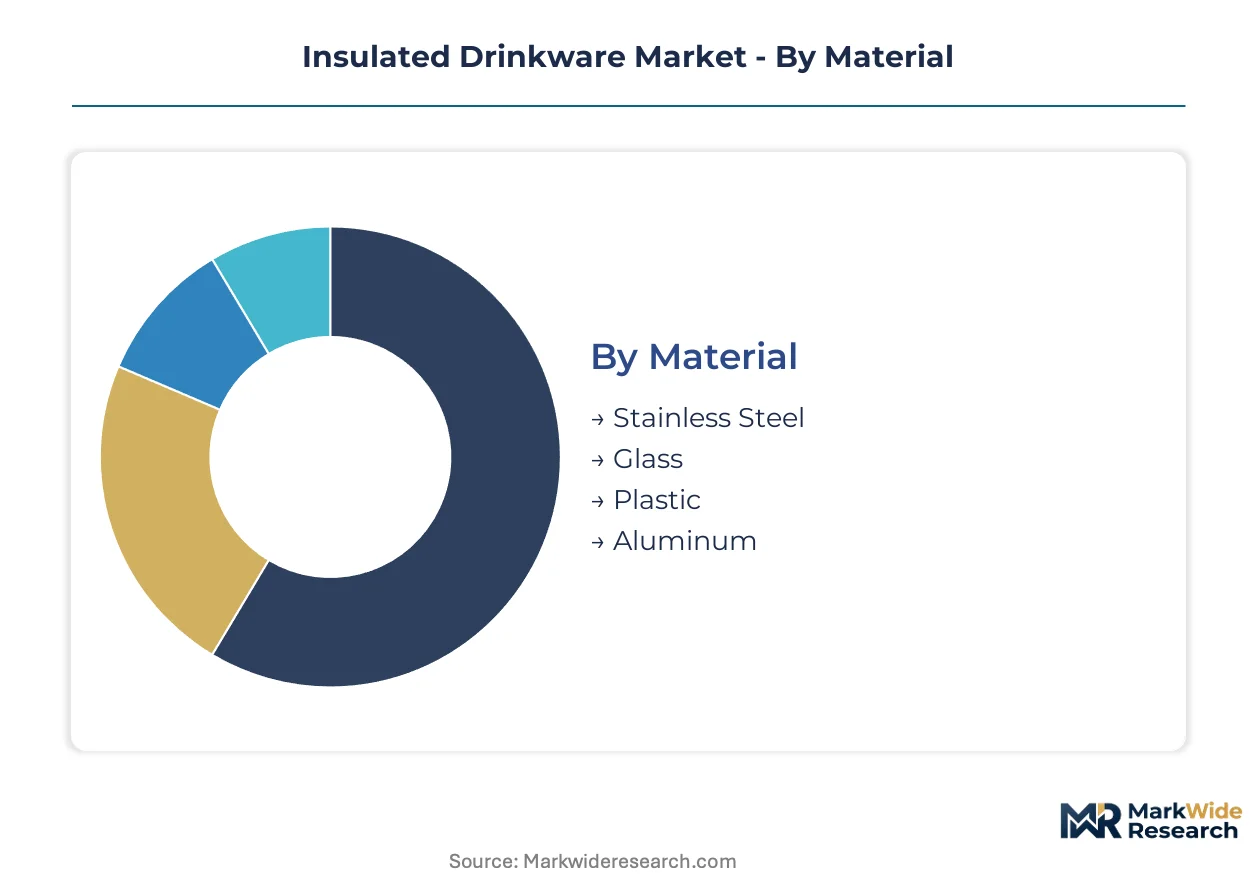
Insulated drinkware segmentation reveals how capital allocation, manufacturing complexity, and end-use requirements fragment production economics across material grades and product architectures. Buyers prioritize thermal performance specifications, durability thresholds, and regulatory compliance differently depending on consumption context.
Material:
Capital intensity escalates sharply from polymer extrusion to vacuum-chamber fabrication, with copper-lined stainless steel demanding specialized welding infrastructure and clean-room assembly environments.
- Stainless Steel:18/8 austenitic grade with copper-lined vacuum chambers dominates premium positioning due to dent resistance and infinite recyclability. Demand concentrates in the United States and Germany where FDA and REACH compliance elevate sourcing standards for food-contact applications.
- Glass:Borosilicate double-wall construction with silicone sleeve protection occupies the aesthetic-driven segment. Adoption clusters in urban China where domestic GB standards for thermal shock resistance shape manufacturing protocols and domestic distribution access.
- Plastic:Tritan copolyester and polypropylene variants serve price-sensitive institutional procurement with lower thermal retention but reduced unit cost.
- Aluminum:Lightweight anodized formats target cycling and ultralight backpacking segments where gram-counting overrides thermal duration specifications.
Most installed capacity flows through Stainless Steel. Expansion is steepest in Glass as Chinese domestic demand for aesthetic hydration formats accelerates.
Product Type:
Volume economics favor standardized cylindrical formats with interchangeable lid ecosystems, while ergonomic complexity increases tooling amortization per SKU.
- Tumblers:Tapered vehicle-cup-holder-compatible cylinders with splash-resistant sliding lids now dominate workplace and commuter contexts. German foodservice operations and United States corporate wellness programs drive specification standardization around 20-30 ounce capacities.
- Water Bottles:Narrow-mouth cylindrical formats with carry-loop integration anchor outdoor recreation and athletic hydration. Chinese manufacturing clusters supply global demand with GB-certified nickel leaching compliance as a competitive differentiator.
- Mugs:Handled configurations with wider bases retain institutional coffee service positioning despite declining commuter relevance.
- Flasks:Curved hip-flask geometries with captive screw caps persist in spirits and hot-beverage outdoor consumption niches requiring concealment and portability.
Production runs concentrate in Tumblers where lid standardization enables component-level margin capture. Water Bottles gain share fastest as athletic participation and outdoor recreation participation expand across target geographies.
End User:
Procurement authority and customization requirements fragment pricing power, with institutional buyers demanding volume discounts and decoration services while consumers prioritize brand signaling and color availability.
- Consumers:Individual purchasers evaluate color coatings, powder-finish durability, and brand heritage markers. Direct-to-consumer channel relationships in the United States and Germany compress wholesale intermediary margins for manufacturers with in-house laser-etching capabilities.
- Outdoor Enthusiasts:Camping and hiking participants prioritize thermal retention duration and impact resistance over unit cost. Participation growth in the United States, Germany, and China pulls demand into premium price tiers with modular accessory compatibility requirements.
- Athletes:Hydration-tracking integration and quick-access straw lids dominate specification requirements for training and competition contexts.
- Businesses:Corporate gifting and employee wellness programs consolidate supplier relationships around configurable product ecosystems with bulk customization and logo decoration services.
Revenue concentration sits with Consumers. Steepest expansion trajectory belongs to Outdoor Enthusiasts as participation rates climb across developed and emerging markets simultaneously.
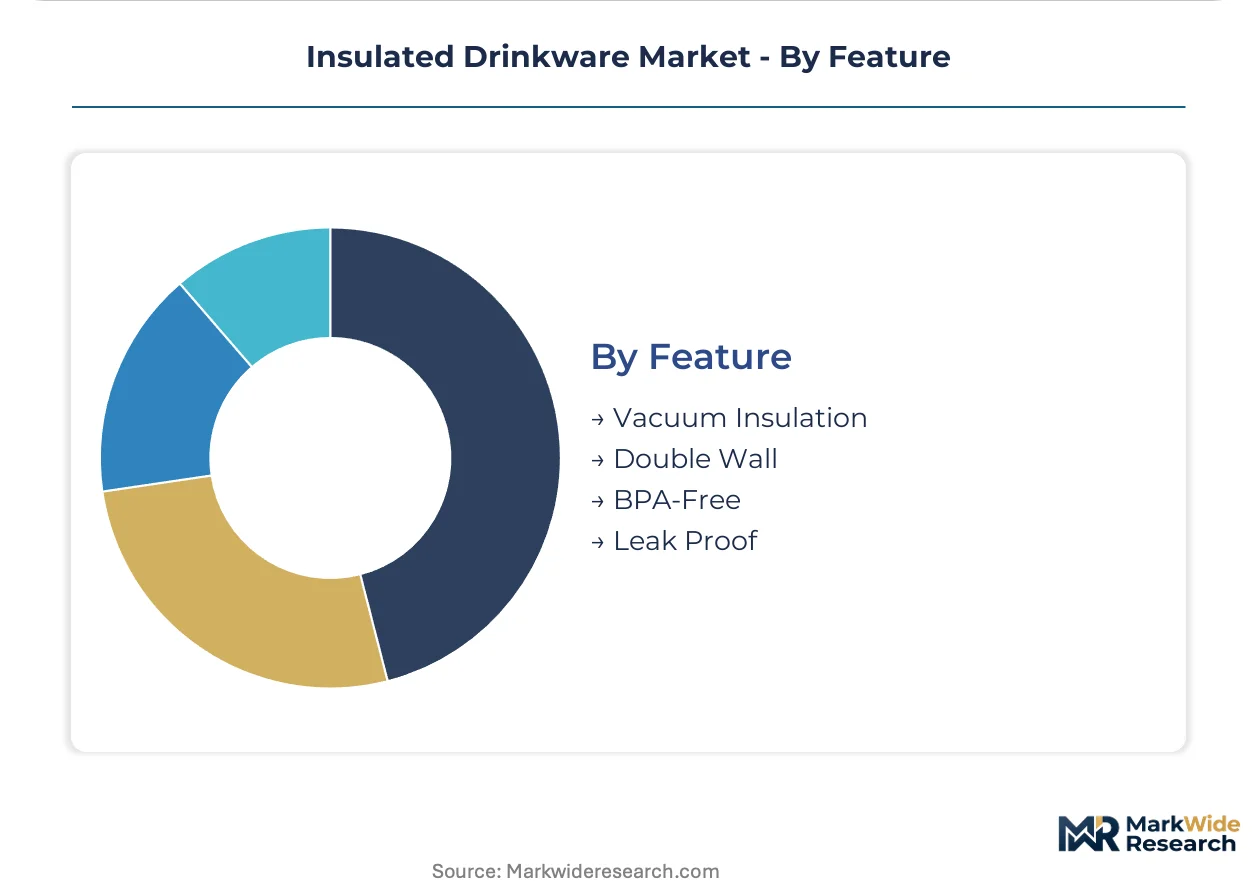
Feature:
Certification burden and testing cost duplication intensify for multi-feature configurations requiring simultaneous FDA, REACH, and GB standard compliance.
- Vacuum Insulation:Copper-lined double-wall construction with evacuated air chambers achieves six-to-twelve hour thermal retention. REACH chemical migration limits for chamber seals and powder finishes extend development timelines eight to fourteen months for European market access.
- Double Wall:Non-evacuated air-gap construction reduces material cost and assembly complexity while sacrificing thermal duration performance. Demand concentrates in price-tiered retail channels where unit economics override performance specifications.
- BPA-Free:Tritan and polypropylene seal formulations eliminate bisphenol migration concerns for health-conscious segments and pediatric applications.
- Leak Proof:Silicone gasket and threaded seal engineering prevents liquid escape during transport and inversion, critical for commuter and athletic use cases.
Technology investment concentrates in Vacuum Insulation where copper supply concentration and welding technician scarcity constrain capacity expansion. BPA-Free certification is climbing fastest as regulatory scrutiny intensifies across all target geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vacuum-insulated vessel manufacturing originated in early twentieth-century Germany and Japan, where precision metalworking traditions enabled the first commercial double-wall constructions. Contemporary demand concentrates in countries with strong outdoor recreation cultures and stringent food-contact material regulations.
United States
National park visitation and hiking participation drive premium vessel procurement across Colorado, Utah, and Pacific Northwest trail systems. FDA food-contact regulations govern stainless steel and polypropylene component safety for domestic distribution. Austin, Texas and Seattle, Washington host brand headquarters and laser-etching customization facilities serving corporate gifting verticals.
China
Domestic GB standards for nickel and chromium leaching thresholds shape manufacturing protocols for both export and internal consumption. Yangtze River Delta manufacturing clusters in Zhejiang and Jiangsu provinces supply global vacuum-chamber assembly capacity. Shanghai and Shenzhen distribution networks prioritize aesthetic-driven borosilicate glass formats for urban commuter segments.
Germany
ECHA REACH chemical migration limits extend product development timelines for powder finishes and silicone seals entering European markets. Bavarian and North Rhine-Westphalia industrial zones concentrate precision welding infrastructure for copper-lined chamber fabrication. Berlin and Munich specialty retailers consolidate supplier relationships around modular lid-system vendors.
Japan
METI efficiency standards and JIS thermal performance certifications elevate barrier-to-entry for imported vessels. Osaka and Nagoya manufacturing heritage sustains artisanal vacuum-chamber construction techniques. Tokyo and Kyoto urban consumers prioritize compact flask geometries for rail-commute portability.
Australia
TGA-aligned material safety expectations and extreme climate conditions drive demand for extended thermal retention durations. Melbourne and Sydney corporate wellness programs standardize tumbler configurations for workplace hydration initiatives. Queensland and Western Australia outdoor recreation participation pulls premium stainless steel formats into camping and four-wheel-drive expedition contexts.
Insulated Drinkware Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating durability and thermal retention certification tiers, with brand heritage and direct-channel capabilities determining pricing power. The vendor base stratifies into three tiers: heritage metalworkers with century-plus positioning, venture-backed outdoor-lifestyle specialists, and contract-manufacturing-dependent private-label suppliers. Consolidation pressure intensifies as specialty retailers reduce supplier counts and institutional buyers demand configurable product ecosystems. Dominant competitive moves include backward integration into laser-etching decoration capabilities and geographic expansion into underpenetrated foodservice channels.
Within the heritage-positioned tier, Thermos and Stanley exemplify century-plus brand equity leveraged across institutional and consumer channels. YETI occupies the premium-lifestyle archetype with specialty retail shelf positioning and direct-channel relationships. Hydro Flask represents the color-innovation specialist segment with sustained investment in powder-finish R&D. KINGSTAR, Everich, and Gint anchor the contract-manufacturing tier supplying private-label and white-label programs across North American and European distribution networks.
| Leading Market Players |
|---|
| Thermos |
| Contigo |
| YETI |
| KINGSTAR |
| Everich |
| Stanley |
| CamelBak |
| Gint |
| Hydro Flask |
| Others |
Value Network & Pricing Analysis
Corporate wellness program procurement in the United States and Germany anchors volume purchasing for branded vacuum-insulated formats, creating contract-based pricing power for manufacturers with in-house laser-etching and bulk customization capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage-positioned stainless steel vessels from mid-tier powder-coated alternatives and private-label polymer formats. Price differentiation hinges on REACH certification tier and thermal retention duration certification. Cost compression in the mid-tier segment is intensifying because London Metal Exchange nickel volatility squeezes margin buffers for contract-manufacturing-dependent suppliers. Institutional buyers in foodservice channels exhibit highest price sensitivity, while outdoor enthusiasts demonstrate lowest sensitivity due to modular accessory ecosystem requirements.
Supply Chain Analysis
Copper supply for vacuum chamber linings rests on Chilean and Peruvian mining output, exposing producers to geopolitical interruption risk. Raw material dependencies span 18/8 stainless steel from Chinese and Indian mills, copper foil from South American concentrate, and polypropylene seals from South Korean petrochemical complexes. Single-source vulnerability concentrates in precision welding equipment for copper-lined chamber fabrication, where German and Japanese machinery suppliers dominate installed capacity. Distribution runs through direct-to-consumer channels and specialty outdoor retailers, with wholesale intermediary roles compressing in United States and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Europe run eight to fourteen months longer than FDA pathways in the United States, creating margin capture opportunities for dual-certified manufacturers.
For Market Incumbents: Lock in copper supply agreements with Chilean concentrate producers to defend against nickel price volatility and welding technician scarcity threatening capacity expansion. Deepen backward integration into laser-etching decoration capabilities to capture corporate gifting verticals consolidating supplier relationships. Prioritize GB standard certification for preferential access to Chinese domestic distribution networks.
For New Entrants and Emerging Players: The mid-tier price-point gap between YETI-premium and private-label economy tiers offers white-space entry through modular lid-system specialization targeting German foodservice operations and Chinese urban commuter segments. Target underpenetrated institutional channels in Bavarian and North Rhine-Westphalia industrial zones with configurable product ecosystems. Lead with hydration-tracking sensor integration as a differentiated go-to-market angle for athletic and corporate wellness verticals.
For Investors and Strategic Acquirers: Specialty outdoor retailers are the most active acquirer in this space, consolidating supplier counts around vendors with configurable product ecosystems and direct-channel capabilities. Long-term viability centers on copper-lined vacuum chamber fabrication expertise and REACH-compliant coating R&D infrastructure. Watch nickel price volatility and ECHA extended producer responsibility framework implementation as inflection indicators for margin compression and consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser-Etching | Captures corporate gifting verticals consolidating around fewer suppliers with in-house decoration. |
| GB Standard Certification | Unlocks preferential distribution access in Yangtze River Delta manufacturing clusters and Shanghai networks. |
| Modular Lid-System Development | Enables component-level margin capture and recurring revenue through hydration-tracking sensor attach-rates. |
| Copper Supply Agreement | Mitigates Chilean and Peruvian mining concentration risk threatening vacuum chamber fabrication capacity. |
| REACH-Compliant Coating R&D | Absorbs ECHA chemical migration compliance costs more efficiently than contract-manufacturing competitors. |
Research Methodology
Coverage spans the United States, China, Germany, Japan, and Australia, with primary inputs from each market combining executive interviews with brand managers, category buyers at specialty outdoor retailers, procurement leads at corporate wellness programs, and precision welding technicians at manufacturing clusters. Secondary validation draws from FDA food-contact filings, ECHA REACH substance registrations, Chinese GB standard documentation, and customs trade records for stainless steel and copper inputs. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Yangtze River Delta and Zhejiang manufacturing zones.
Granularity-level modeling disaggregates volume and value across material grade, product architecture, end-user segment, and thermal performance certification tier throughout the forecast period. The analytical framework derives CAGRs from segment-level demand elasticity coefficients and supply capacity expansion schedules. Industry-specific forecast inputs include London Metal Exchange nickel price scenarios and outdoor recreation participation indices from national park visitation data.
Caveats apply where London Metal Exchange nickel volatility, ECHA extended producer responsibility mandate timing, or copper supply interruptions from Chilean and Peruvian mining operations could materially shift the outlook. A small set of triggers—regulatory certification timeline extensions, specialty retailer supplier consolidation acceleration, and welding technician training program output—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Electric Brooms Market
Household Items
Silicone Soap Mold Market
Household Items
India POU Water Purifiers Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Indoor Humidifier Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Knife Market
Household Items
Soap Dispenser Market
Household Items
Thermos Bottle Market
Household Items
Knife Set Market
Household Items
Hand-Held Vacuum Cleaner Market
Household Items
Hand Dryer Market
Household Items
Europe Heated Mattress Pads Market
Household Items
Integrated Smart Toilet Market
Household Items
Manual Bottle Opener Market
Household Items
Europe Digital Showers Market