
 Hands-Free Faucet Market | 2026-2036
Hands-Free Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
Hands-Free Faucet Market Foresight
Healthcare facilities is bifurcating demand away from traditional residential channels as infection control protocols harden across hospital networks. Kohler Co. leverages its broad plumbing portfolio to serve both premium residential and institutional buyers. Sloan Valve Company dominates in commercial restrooms with sensor-activated flush valves and faucets engineered for high-traffic environments. Jaquar Group anchors its position across Asia-Pacific through localized manufacturing and pricing calibrated to emerging-market budgets.
A hands-free faucet employs infrared proximity sensors, piezoelectric triggers, or voice-recognition modules to activate water flow without manual contact, typically operating on battery or hardwired power with flow rates between 0.5 and 2.2 gallons per minute depending on aerator specification. The primary purpose is hygiene protection in settings where pathogen transmission poses operational risk, plus water conservation through precise flow duration control. Infrared Sensors leads product type revenue due to mature supply chains and installer familiarity, while Voice-Activated Faucets represents the fastest-expanding segment as smart home ecosystems penetrate luxury residential and high-end hospitality. Commercial end users command the largest absolute spend, though Healthcare posts the steepest growth trajectory as facilities retrofit aging infrastructure.
EPA WaterSense certification shapes product development timelines in the United States by mandating maximum flow thresholds, while EU Ecodesign directives and the F-Gas Regulation indirectly influence component sourcing for sensor-cooled electronics. China's GB standards and MIIT efficiency labels govern domestic manufacturing and import eligibility for foreign brands. Stakeholders must monitor how tightening water-efficiency thresholds in multiple jurisdictions will force sensor recalibration and aerator redesign without degrading user experience.
Market Dynamics
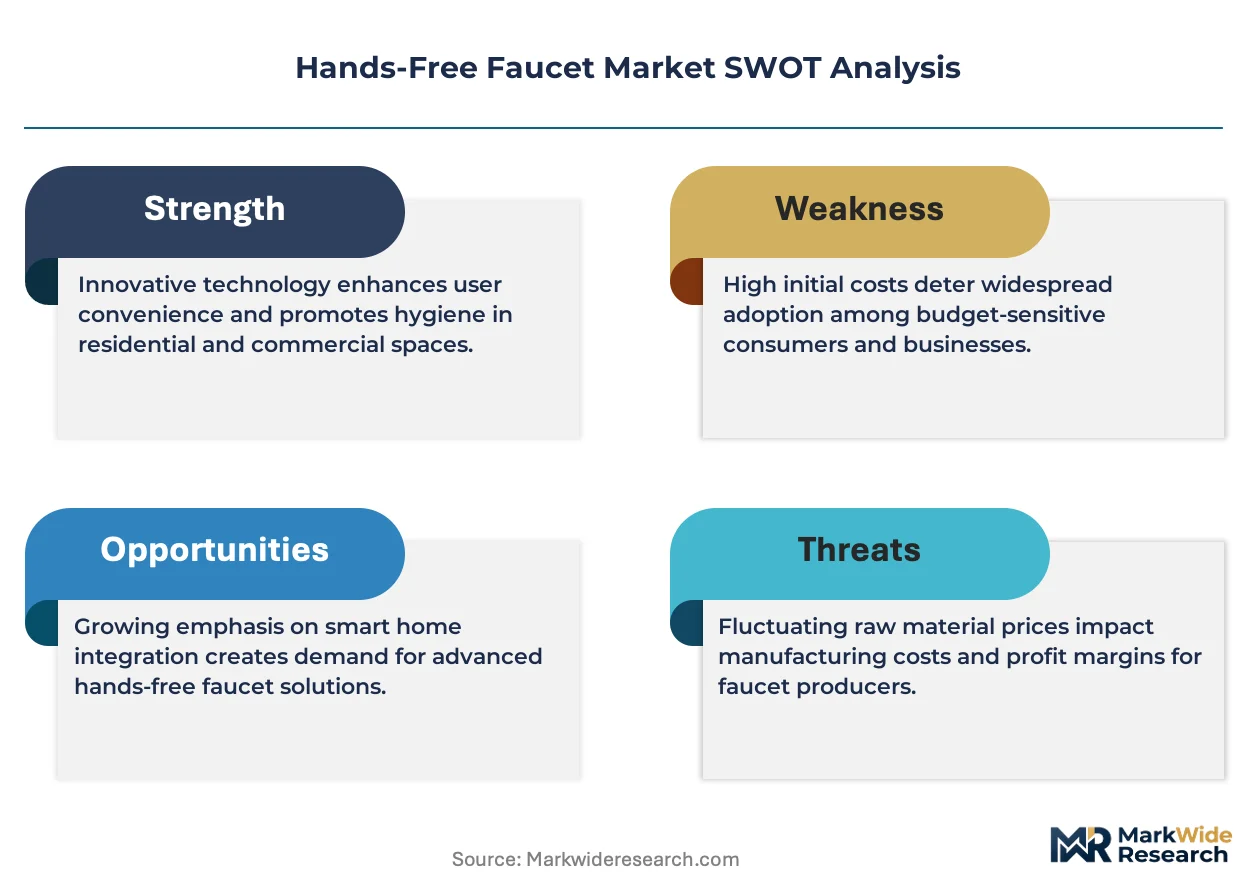
Healthcare infection control mandates are compressing replacement cycles for manual fixtures across hospital networks, while EPA WaterSense flow-rate thresholds force sensor recalibration and aerator redesign without degrading user experience.
Growth Catalysts
- EPA WaterSense Specifications:Maximum flow thresholds accelerate fixture replacement timelines in commercial restrooms across the United States.
- Healthcare Infection Control:Hospital networks harden pathogen transmission protocols, retrofitting aging infrastructure with infrared proximity sensors.
- Smart Building Integration:Voice-recognition modules penetrate luxury residential and high-end hospitality segments in Germany and China.
Market Restraints
- Sensor Component Concentration:Infrared emitter supply clusters in East Asian manufacturing hubs, exposing procurement to geopolitical friction.
- Battery Replacement Burden:Battery-powered units require maintenance cadences that strain facility management budgets in high-traffic environments.
- EU F-Gas Regulation:Cooling requirements for sensor electronics face component sourcing constraints under tightening fluorinated gas phase-down schedules.
Strategic Opportunities
- India Commercial Real Estate:Underpenetrated touchless fixture penetration in new office construction offers first-mover positioning for localized pricing strategies.
- Voice-Activated Convergence:Integration of voice-recognition modules with building automation systems opens premium specification channels.
- China Dual Carbon Goals:MIIT efficiency labels and provincial water conservation mandates create regulatory tailwinds for sensor-activated retrofit programs.
Industry Challenges
- Certification Timeline Compression:Multiple jurisdictional efficiency mandates force simultaneous recalibration for EPA WaterSense, EU Ecodesign, and China GB standards.
- Legacy Plumbing Integration:Sensor-activated valves require electrical rough-in modifications that complicate retrofit economics in aging commercial buildings.
- Installer Skill Fragmentation:Shortage of technicians trained in both plumbing and low-voltage sensor wiring extends project completion windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hands-Free Faucet Market |
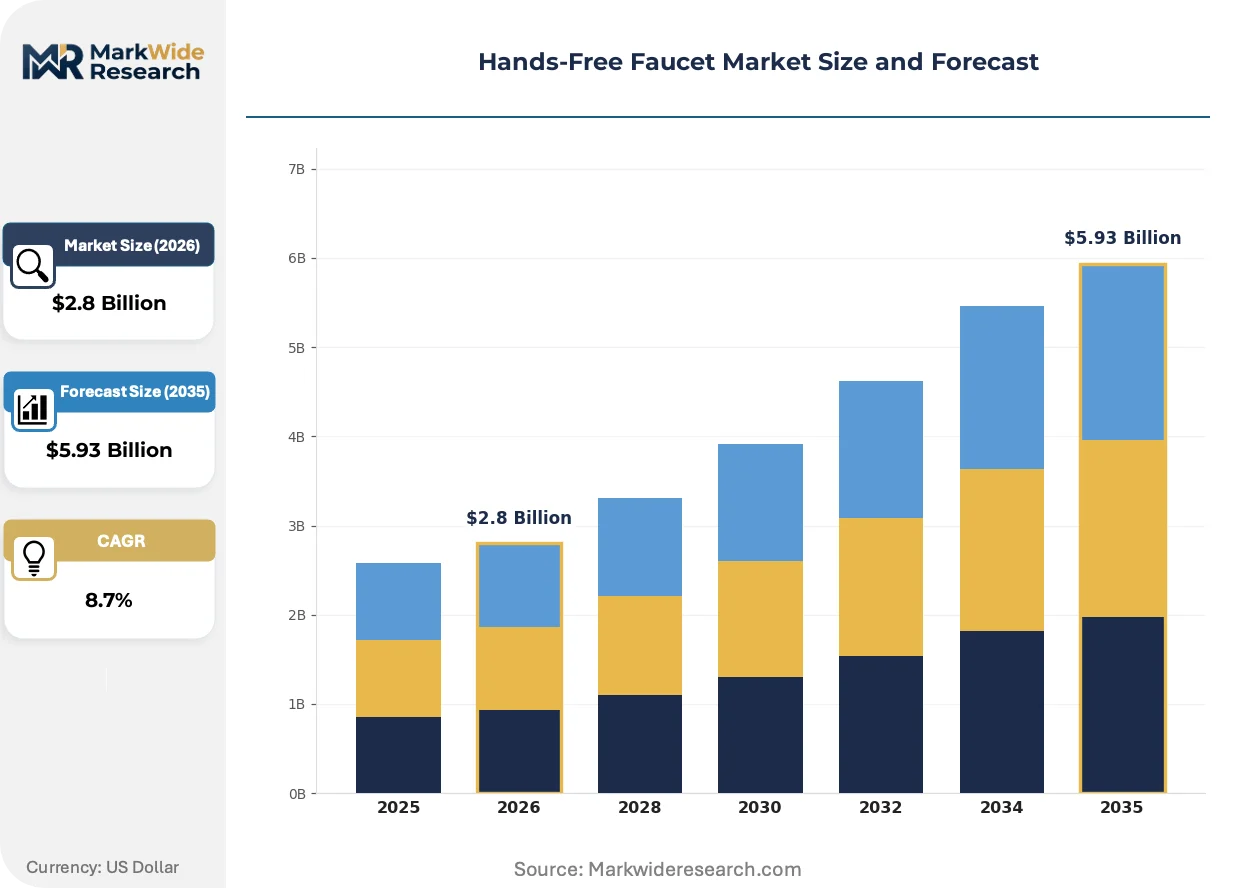
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Touchless Faucets, Foot Pedal Faucets, Voice-Activated Faucets End User: Residential, Commercial, Healthcare, Educational Institutions Installation Type: Wall-Mounted, Deck-Mounted, Countertop, Standalone Distribution Channel: Online Retailers, Home Improvement Stores, Wholesale Distributors, Specialty Stores |
| Companies Covered | Kohler Co., Moen Incorporated, Delta Faucet Company, Sloan Valve Company, Masco Corporation, Zurn Elkay Water Solutions Corporation, Jaquar Group, Hansgrohe SE, TOTO Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hands-Free Faucet Market Shifts & Advancements
Voice-recognition activation is penetrating fixture specification channels alongside tightening water-efficiency mandates, while procurement patterns shift toward bundled smart building systems.
Solid-state infrared proximity sensors with integrated ambient light compensation are supplanting legacy photodiode arrays in high-traffic commercial installations. Airport authorities and hospital facility managers specify these units for reduced false-trigger rates and extended calibration intervals. The technology is supplanting battery-dependent architectures by enabling hardwired power integration with lower standby consumption profiles.
EU Ecodesign directives tighten maximum flow-rate thresholds for public sanitary tapware, forcing manufacturers to redesign aerator geometries while maintaining perceived water pressure. The regulation compresses product development timelines and invalidates existing stock for cross-border shipment. German commercial restroom specifiers now require dual certification against both Ecodesign and national DVGW hygiene standards.
Facility management departments consolidate fixture procurement through building automation integrators rather than traditional plumbing distributors. The channel shift bundles sensor faucets with HVAC and lighting controls under single-source maintenance contracts. This pattern concentrates most visibly in United States healthcare systems pursuing enterprise-wide infection control standardization.
Hands-Free Faucet Market Segmentation
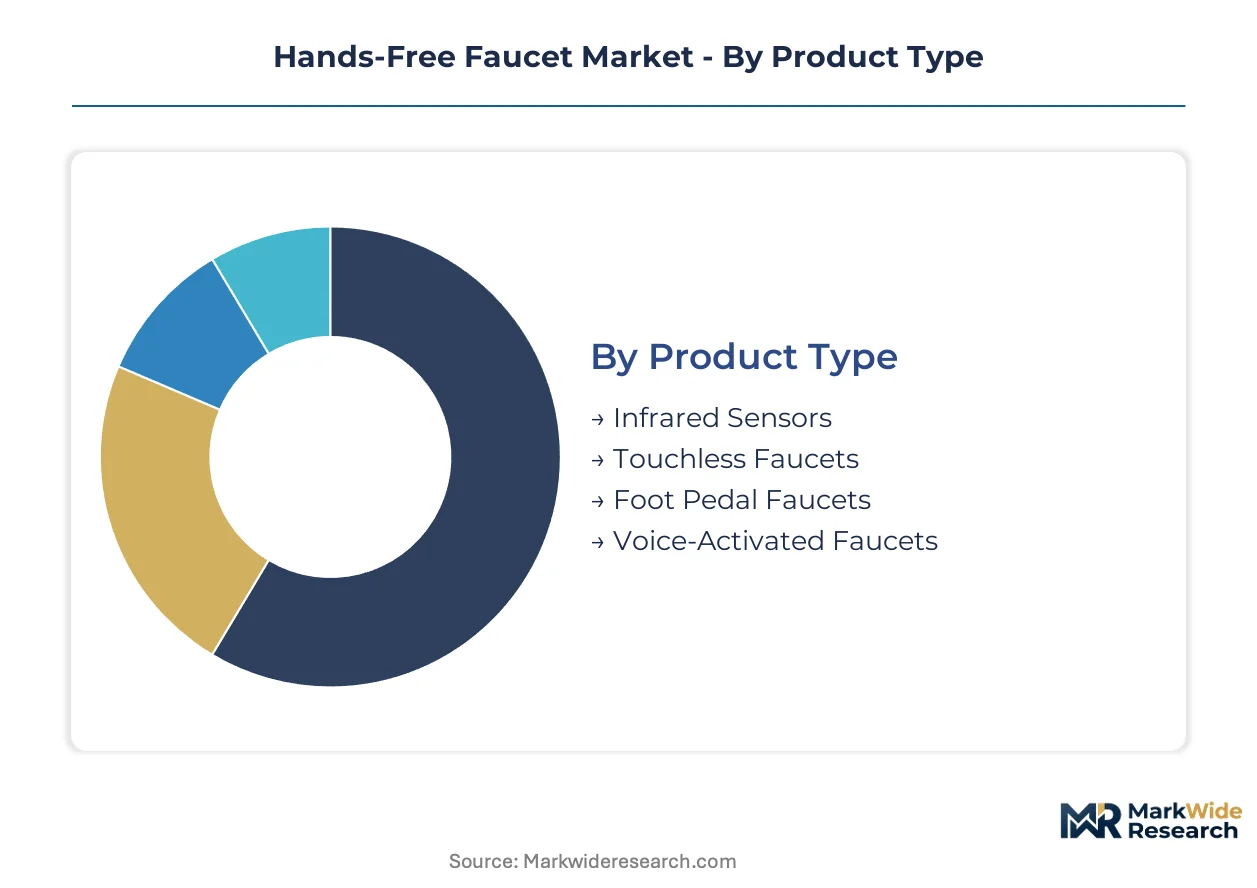
Segmentation in the hands-free faucet market reveals how specification channels bifurcate between infection-control mandates in healthcare and smart-home integration in residential. Each dimension shapes procurement patterns, installer skill requirements, and margin structures differently.
Product Type:
Channel mix varies sharply: infrared sensors dominate wholesale distributor and home improvement store volumes, while voice-activated units concentrate in specialty stores and direct-to-builder online channels.
- Infrared Sensors:Solid-state proximity arrays with ambient light compensation detect hand presence through infrared reflection, typically hardwired with 0.5-2.2 GPM flow control. Demand concentrates in United States hospital networks retrofitting aging manual fixtures under tightened infection protocols. EPA WaterSense certification timelines accelerate replacement cycles.
- Voice-Activated Faucets:Microphone modules integrated with building automation systems or smart home hubs enable hands-free activation through spoken commands. Germany and China luxury residential specifiers drive adoption as smart building integration becomes a premium differentiator in high-end hospitality.
- Touchless Faucets:Capacitive or wave-sensor mechanisms offer mid-tier price positioning with simpler electronics than voice systems.
- Foot Pedal Faucets:Mechanical or electronic foot-press activation serves industrial and food-service environments where hand contamination is constant.
By volume, Infrared Sensors leads. By growth pace, Voice-Activated Faucets is ahead.
End User:
Cost tiers separate procurement: healthcare commands premium pricing for infection-grade certification, while educational institutions operate on constrained capital budgets favoring standard-tier specifications.
- Healthcare:Hospital, clinic, and long-term care facilities mandate touchless fixtures under Joint Commission and CDC infection control guidelines. United States health systems consolidate enterprise-wide procurement through building automation integrators, bundling faucets with HVAC and lighting controls.
- Commercial:Office buildings, airports, and retail restrooms specify high-traffic-rated units with extended calibration intervals and vandal-resistant housings.
- Residential:New construction and kitchen/bath renovation projects drive demand, split between premium smart-home integration and standard retrofit models.
- Educational Institutions:K-12 schools and universities balance hygiene protocols against maintenance budget constraints, favoring battery-powered units where electrical rough-in is unavailable.
Commercial commands the largest absolute spend. Healthcare posts the steepest expansion trajectory.
Installation Type:
Volume concentration tracks new construction versus retrofit economics: deck-mounted units dominate residential replacement, while wall-mounted specifications rise in commercial new builds.
- Deck-Mounted:Faucets install through pre-drilled sink or countertop holes, requiring minimal plumbing modification. Residential channel dominance stems from compatibility with standard three-hole sink configurations.
- Wall-Mounted:Concealed rough-in plumbing and electrical integration suits commercial restroom designs prioritizing cleaning access and vandal resistance. German and United States airport authorities specify these for high-traffic concourses.
- Countertop:Vessel-sink applications in hospitality and premium residential require taller spout profiles with extended reach.
- Standalone:Floor-mounted or pedestal-integrated units serve specialized commercial and healthcare applications where conventional mounting is impractical.
Deck-Mounted leads in unit volume. Wall-Mounted gains share fastest in commercial specification.
Distribution Channel:
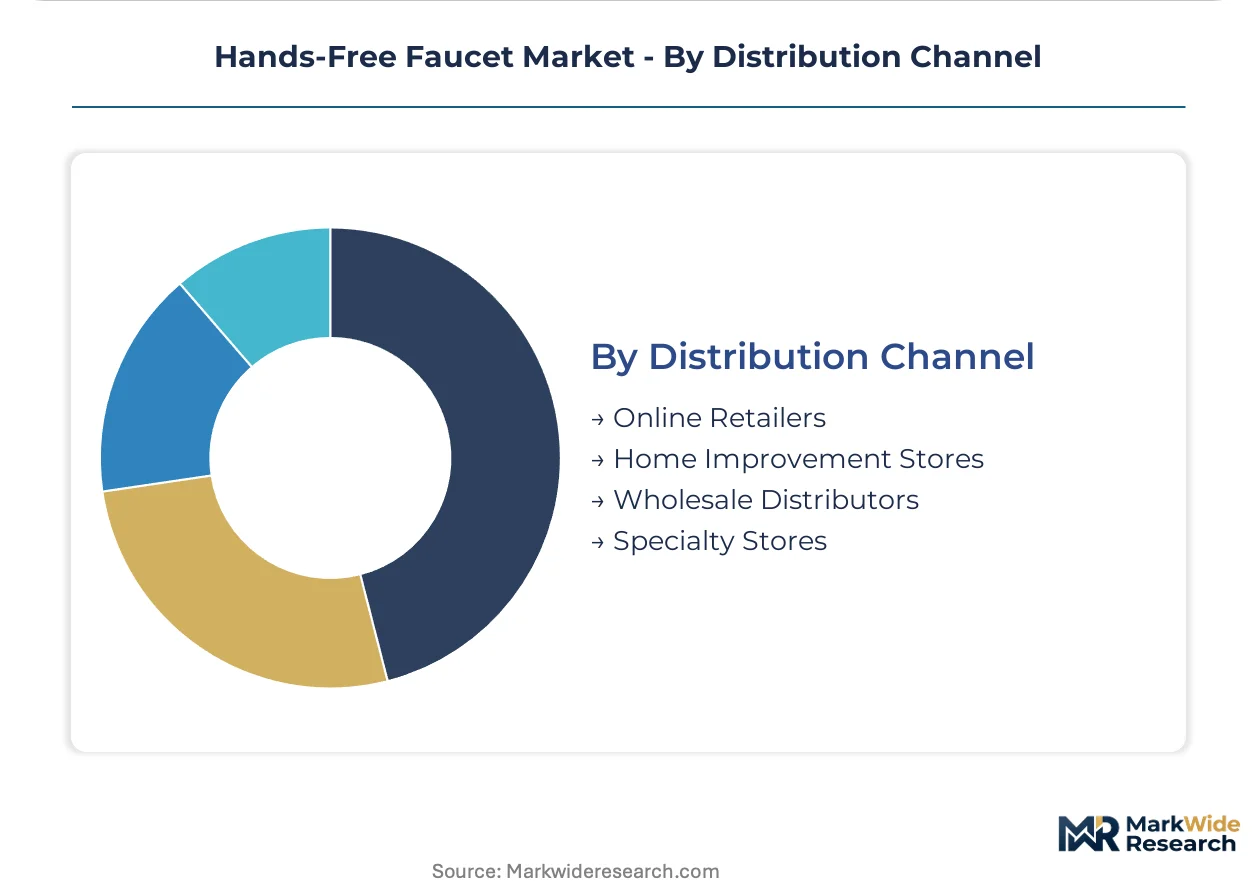
Customer type determines channel selection: facility management departments consolidate through wholesale distributors, while residential consumers fragment across online and retail touchpoints.
- Wholesale Distributors:Plumbing and HVAC wholesalers serve commercial contractors and facility managers with bulk pricing, technical support, and specification assistance. United States healthcare systems leverage these relationships for enterprise standardization.
- Home Improvement Stores:Big-box retailers capture residential renovation demand through in-stock availability and installer referral networks.
- Online Retailers:E-commerce platforms aggregate long-tail SKU availability and comparison shopping, growing fastest in voice-activated and specialty finishes.
- Specialty Stores:Kitchen and bath showrooms serve premium residential and hospitality specifiers with curated assortments and design consultation.
Wholesale Distributors handle the largest transaction value. Online Retailers expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor component manufacturers export infrared emitter assemblies to United States healthcare retrofit contractors, while Chinese fixture assemblers supply battery-powered units to Southeast Asian commercial developers.
United States
Hospital networks in Texas and Florida accelerate manual fixture replacement under Joint Commission infection protocols. EPA WaterSense maximum flow thresholds force simultaneous aerator redesign and sensor recalibration for cross-border eligibility. Chicago O'Hare and Atlanta Hartsfield-Jackson airport authorities specify wall-mounted vandal-resistant units for concourse modernization.
Germany
Commercial restroom specifiers in Frankfurt and Munich mandate dual Ecodesign-DVGW certification for public tapware. EU F-Gas Regulation phase-down schedules constrain cooling component sourcing for sensor electronics. Bavarian industrial clusters around Augsburg produce solid-state infrared arrays with integrated ambient light compensation for export markets.
China
Provincial water conservation mandates in Jiangsu and Zhejiang accelerate sensor-activated retrofit programs in aging office buildings. MIIT efficiency labels govern domestic manufacturing and determine import eligibility for foreign brands. Pearl River Delta fixture assemblers supply voice-activated modules to luxury hospitality developers in Shenzhen and Guangzhou.
India
Underpenetrated touchless fixture penetration in Bangalore and Hyderabad commercial new construction creates first-mover positioning for localized pricing strategies. Bureau of Indian Standards plumbing codes gradually incorporate sensor-activation requirements for institutional buildings. Mumbai facility management departments consolidate procurement through building automation integrators rather than traditional plumbing distributors.
Japan
Tokyo and Osaka hospitality operators specify voice-recognition modules as premium differentiators in luxury hotel renovations. METI energy efficiency guidelines tighten standby power consumption thresholds for sensor electronics. Nagoya industrial corridors supply precision infrared components to domestic faucet manufacturers and export customers.
Hands-Free Faucet Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and channel access, producing a tiered structure where scale-driven portfolios face precision-engineering boutiques. The vendor base separates into three archetypes: diversified plumbing conglomerates with broad residential-institutional coverage, commercial restroom specialists with high-traffic engineering expertise, and regional fabricators with localized pricing and assembly advantages. Competitive moves concentrate on portfolio diversification through adjacent fixture categories and backward integration into sensor component supply.
Among United States-based plumbing conglomerates, Kohler Co. and Masco Corporation exemplify scale-driven diversification across premium residential and institutional specification channels. Sloan Valve Company occupies a position within the commercial restroom specialist archetype, anchoring high-traffic engineering expertise. Jaquar Group represents the regional fabricator model with Asia-Pacific manufacturing concentration and emerging-market pricing calibration.
| Leading Market Players |
|---|
| Kohler Co. |
| Moen Incorporated |
| Delta Faucet Company |
| Sloan Valve Company |
| Masco Corporation |
| Zurn Elkay Water Solutions Corporation |
| Jaquar Group |
| Hansgrohe SE |
| TOTO Ltd. |
| Others |
Supply & Pricing Matrix
Component-scale economies in solid-state infrared sensor manufacturing concentrate procurement leverage among East Asian electronics clusters, compressing price floors for voice-activated modules while elevating margins for legacy infrared arrays. This scale asymmetry shapes how Sloan Valve and Kohler tier their fixture portfolios across healthcare and commercial specification channels.
Pricing Analysis
Technology-generation pricing gaps separate solid-state infrared proximity sensors from legacy photodiode arrays and emerging voice-recognition modules. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EPA WaterSense and EU Ecodesign compliance commanding tier-one positioning. Pricing pressure stems from MIIT efficiency label acceleration in China, which forces aerator redesign costs onto manufacturers. Educational institutions exhibit highest price sensitivity due to capital budget constraints, while United States hospital networks prioritize infection-grade certification over unit cost.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Shenzhen port clusters expose infrared emitter assemblies to container availability volatility on transpacific trade lanes. Manufacturing gravity centers on China, South Korea, and Japan for sensor electronics, with German Augsburg industrial clusters supplying solid-state arrays. Raw material dependencies include gallium arsenide substrates, piezoelectric ceramics, and voice-recognition chipsets. Single-source vulnerability concentrates in East Asian infrared emitter supply. Distribution runs through plumbing-HVAC wholesalers serving commercial contractors and building automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EPA WaterSense, EU Ecodesign, and China GB standards creates a defensive moat: certification timelines and sensor recalibration requirements lock in incumbent relationships with hospital networks and airport authorities.
For Market Incumbents: Fortify backward integration into solid-state infrared component supply to offset East Asian emitter concentration risk. Expand captive production of ambient light compensation arrays in Bavarian industrial corridors. Certification investment in dual Ecodesign-DVGW compliance protects German market share against emerging Asian competitors. For New Entrants and Emerging Players: EPA WaterSense fast-track certification opens procurement doors to United States healthcare systems retrofitting aging infrastructure. White-space concentration appears in India's underpenetrated commercial real estate sector, where localized pricing strategies can displace premium imports. Direct-to-builder online channels offer lowest-friction go-to-market entry for voice-activated residential specifications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among building automation integrators bundling sensor faucets with HVAC and lighting controls under single-source maintenance contracts. Long-term viability favors acquisition targets with established hospital system relationships and sensor electronics engineering depth. Watch for inflection when provincial water conservation mandates in China accelerate retrofit program funding.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Component Backward Integration | Captive supply of infrared arrays insulates against East Asian geopolitical friction and emitter shortages. |
| Dual Certification Investment | Simultaneous EPA WaterSense and EU Ecodesign compliance accelerates cross-border eligibility timelines. |
| Building Automation Partnership | Integration with HVAC and lighting controls consolidates procurement through facility management departments. |
| Voice-Recognition Module Development | Smart home ecosystem penetration in Germany and China luxury residential opens premium specification channels. |
| India Commercial Real Estate Expansion | Localized pricing strategies capture first-mover positioning in underpenetrated Bangalore and Hyderabad office construction. |
Research Methodology
A spread of perspectives from hospital facility managers, commercial restroom specifiers, plumbing-HVAC wholesale distributors, and sensor electronics engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA WaterSense certification databases, EU Ecodesign directive filings, China MIIT efficiency label registries, and building automation integrator procurement records. Bottom-up fixture shipment data triangulated against top-down healthcare capital expenditure tracking.
Segmentation dimensions modeled include product type, end-user vertical, installation configuration, and distribution channel across the projection horizon. CAGRs derived from installed base replacement cycle analysis, new construction permit flows, and regulatory mandate acceleration curves. Voice-recognition module adoption curves and infrared sensor price elasticity informed scenario-weighted outcomes.
Underlying assumptions cover EPA WaterSense threshold enforcement consistency, EU F-Gas Regulation phase-down adherence, and China provincial water conservation mandate implementation, with deviation risk concentrated in geopolitical supply disruption and installer skill shortage persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Insulated Water Bottles Market
Household Items
Copper Water Bottle Market
Household Items
Enameled Cookware Market
Household Items
Hand Wash Station Market
Household Items
India Non-Stick Cookware Market
Household Items
Air Freshener Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
US Flashlights Market
Household Items
Japan Digital Showers Market
Household Items
Brazil Cookware Market
Household Items
Europe Hand Dryers Market
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Latex Mattress Market
Household Items
Knife Market
Household Items
Italy Digital Showers Market
Household Items
Germany Induction Hobs Market