
 Flatware Market | 2026-2036
Flatware Market Size, Share, and Industry Trends Forecast 2026-2036
Flatware Market Foresight
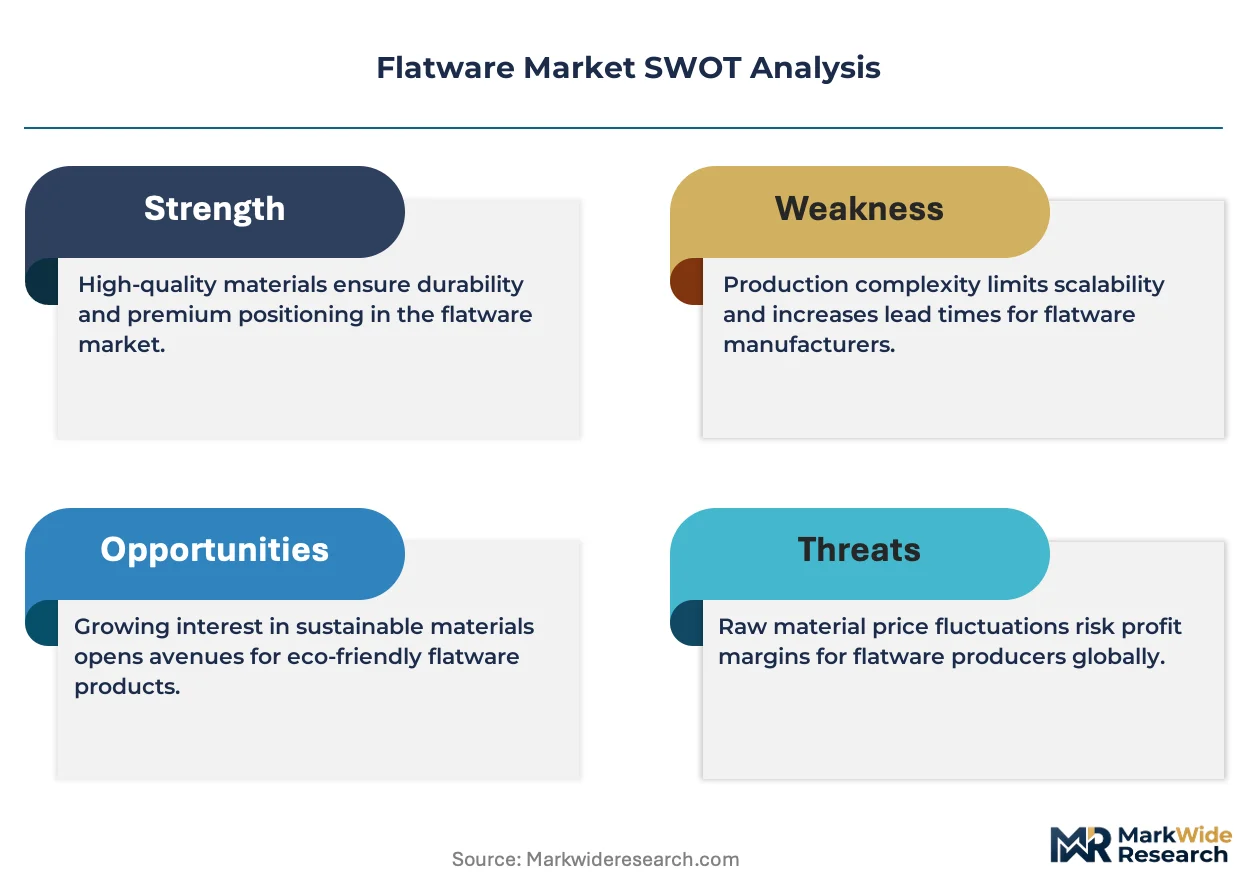
Hospitality procurement is realigning away from budget plastic sets toward premium stainless steel and silver-plated collections as hotels and catering companies upgrade tableware standards post-pandemic. WMF leverages its German manufacturing heritage to dominate European foodservice supply chains with forged stainless steel programs. Christofle anchors ultra-luxury hospitality channels in the Middle East and Asia through its silver-plated heritage craftsmanship. Tramontina competes aggressively on cost-engineered stainless steel for Latin American and North American institutional buyers.
Flatware denotes eating and serving utensils engineered from metals, polymers, or natural composites, with 18/10 stainless steel specifying 18% chromium and 10% nickel content for corrosion resistance and luster retention in commercial dishwashing environments. Stainless steel commands the largest material share due to durability and unit economics in high-turnover foodservice settings. Serving sets and salad servers represent the fastest-expanding product type category as experiential dining and shared-plate formats gain traction in restaurants. Plastic and bamboo segments occupy niche positions where disposability regulations permit single-use alternatives for outdoor and institutional catering.
REACH restricts nickel migration thresholds in metal food-contact articles across the European Union, compelling suppliers to certify 18/10 and 18/0 grades through ECHA-recognized laboratories. The FDA maintains food-contact substance notification requirements for novel coatings and alloys in the United States, adding compliance duration to product development cycles. ISO 8442 cutlery performance standards govern blade hardness, corrosion testing, and handle attachment durability, shaping procurement specifications for institutional buyers. Stakeholders must monitor tightening state-level plastic bans in the United States and emerging extended producer responsibility frameworks in Europe that could alter material mix strategies and supplier qualification costs.
Market Dynamics
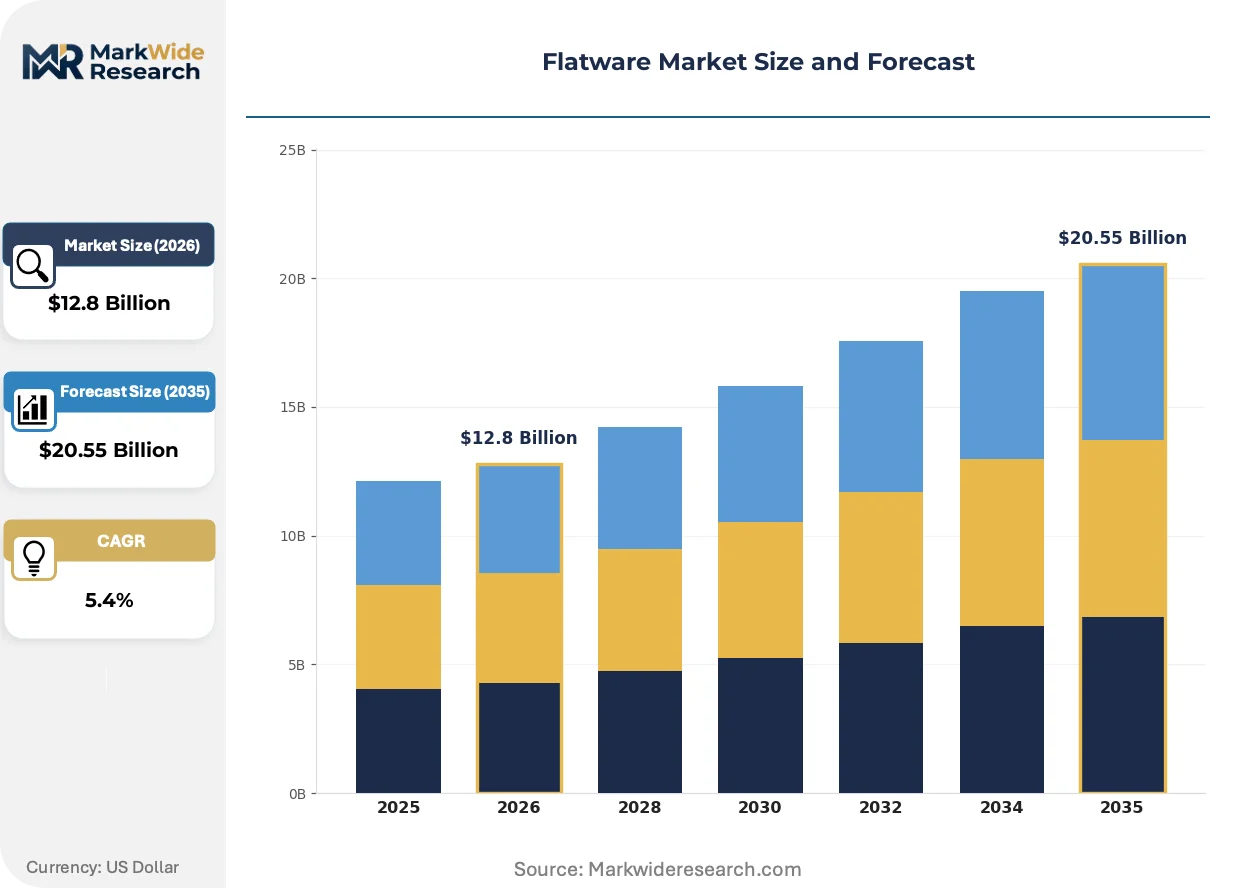
Hospitality procurement is realigning toward premium stainless steel collections as hotels and catering companies upgrade tableware standards post-pandemic, while REACH compliance across the European Union and evolving food-contact material rules in North America reshape supplier qualification requirements.
Growth Catalysts
- 18/10 Stainless Steel Migration:Hotels and catering companies are upgrading from budget plastic to forged stainless steel collections, driven by durability demands in commercial dishwashing environments and luster retention requirements.
- REACH Nickel Thresholds:ECHA-recognized laboratory certification is becoming mandatory for metal food-contact articles across the European Union, creating qualified supplier premiums for compliant manufacturers.
- Experiential Dining Formats:Shared-plate restaurants and experiential dining concepts are expanding demand for serving sets and salad servers as tableware becomes part of the culinary presentation.
Market Restraints
- Nickel Price Volatility:18/10 grade production depends on nickel input costs, which fluctuate with mining supply disruptions and battery sector competition for the same metal.
- Chinese Manufacturing Concentration:Domestic manufacturing scale and export infrastructure in China create supply concentration risk for buyers seeking geographic diversification.
- Plastic Substitution Ceiling:State-level plastic bans in the United States and emerging extended producer responsibility frameworks in Europe are compressing the addressable market for single-use alternatives.
Strategic Opportunities
- Latin American Institutional Expansion:Cost-engineered stainless steel programs for North American institutional buyers can extend into Brazilian and Mexican foodservice chains with localized forging partnerships.
- ISO 8442 Certification Differentiation:Blade hardness and corrosion testing standards are creating procurement specification tiers that certified suppliers can exploit in institutional RFP processes.
- Middle East Ultra-Luxury Channels:Silver-plated heritage craftsmanship anchors hospitality supply chains in Dubai and Riyadh, where premium positioning commands sustained margins.
Industry Challenges
- FDA Notification Timelines:Food-contact substance notification requirements for novel coatings and alloys in the United States add compliance duration to product development cycles, compressing innovation windows.
- Legacy Plastic Inventory Stranding:Distributors and institutional buyers face write-downs as tightening regulations accelerate obsolescence of non-compliant stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatware Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Silver Plated, Plastic, Bamboo, Titanium, Ceramic Product Type: Knives, Forks, Spoons, Serving Sets, Teaspoons, Salad Servers Application: Retail, Foodservice, Catering, Hospitality, Educational Institutes, Event Management Customer Type: Households, Restaurants, Hotels, Cafes, Catering Companies, Institutional Buyers |
| Companies Covered | Villeroy & Boch, Georg Jensen, WMF, Robert Welch, Rösle, Oneida, Christofle, Tramontina, Zwilling J.A. Henckels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatware Market Shifts & Advancements
Material science advances and regulatory stringency are compressing the viable supplier base while experiential dining formats expand product category boundaries beyond traditional cutlery.
Laser-surface texturing is consolidating grip performance and aesthetic differentiation into single-process manufacturing. High-turnover foodservice operators in Germany and France are adopting textured handles at scale, collapsing the traditional separation between functional and decorative finishing steps.
REACH nickel migration thresholds are compelling alloy reformulation across European supply chains. ECHA-recognized laboratories now certify 18/0 grades as compliant alternatives, shifting procurement specifications away from nickel-dependent compositions in institutional contracts.
Shared-plate formats are reconfiguring unit economics for serving utensils. Restaurants in Shanghai and Singapore are specifying salad servers and serving sets as core tableware rather than accessories, expanding average contract values for hospitality suppliers.
Flatware Market Segmentation
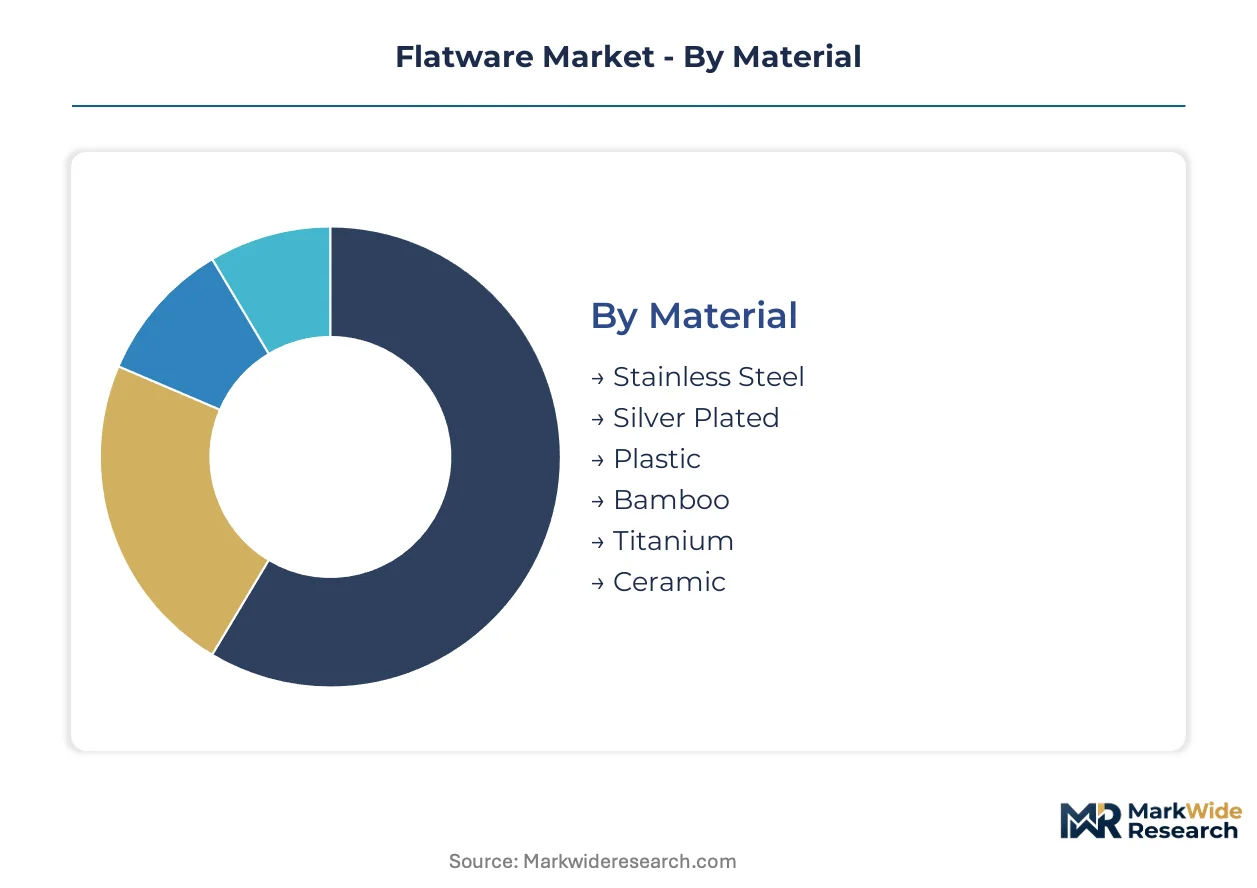
Flatware procurement specifications diverge sharply across end-use environments, with material composition and product type determining compliance pathways and unit economics. The segmentation framework reveals how hospitality buyers prioritize durability certifications while retail channels weight aesthetic differentiation and price accessibility.
Material:
Material selection determines whether flatware operates as standalone tableware or integrates into broader foodservice equipment ecosystems through dishwasher compatibility and regulatory certification.
- Stainless Steel:18/10 and 18/0 chromium-nickel alloys deliver corrosion resistance for commercial dishwashing cycles. Hotels in Germany and France specify forged grades from WMF and Zwilling J.A. Henckels to meet ISO 8442 blade hardness standards.
- Silver Plated:Heritage craftsmanship from Christofle and Puiforcat anchors ultra-luxury hospitality supply chains in Dubai and Riyadh. Silver-plated collections command sustained margins where premium positioning outweighs maintenance costs.
- Plastic:Polypropylene and melamine formulations serve outdoor catering and institutional settings where disposability regulations still permit single-use alternatives.
- Bamboo:Compressed natural fiber composites target eco-conscious retail segments in Scandinavia and California before state-level plastic bans accelerate obsolescence.
- Titanium:Lightweight aerospace-grade alloys penetrate premium outdoor recreation and specialty medical foodservice niches requiring non-reactive surfaces.
- Ceramic:Glazed porcelain and stoneware handles differentiate gift retail assortments through tactile warmth and artisanal positioning.
Volume placements concentrate in Stainless Steel; the faster expansion belongs to Titanium as weight-sensitive applications multiply.
Product Type:
Product type segmentation tracks the shift from individual place settings toward shared-plate formats that elevate serving utensils to core tableware status.
- Knives:Forged blade construction with Rockwell hardness above 52 HRC satisfies institutional procurement specifications. French and German foodservice distributors prioritize serrated dinner knives with full-tang handles.
- Forks:Tine geometry and handle balance determine dishwasher rack compatibility. North American casual dining chains specify medium-weight forks at 45-gram thresholds.
- Spoons:Soup and dessert spoon profiles vary by regional service conventions, with deeper bowls preferred in Asian markets.
- Serving Sets:Salad servers and carving utensils are gaining table presence as experiential dining formats expand in Shanghai and Singapore restaurants.
- Teaspoons:Specialty coffee culture drives demand for demitasse and stirring spoon variants in Milan and Melbourne café supply chains.
- Salad Servers:Oversized paired utensils are specified as core tableware rather than accessories, expanding contract values for hospitality suppliers.
Production volumes skew toward Knives and Forks; Serving Sets are climbing the fastest as shared-plate formats proliferate.
Application:
Application segmentation separates high-turnover commercial environments from lower-frequency retail and institutional procurement cycles.
- Retail:Department store and e-commerce channels prioritize gift packaging and seasonal collections. Italian design houses like Alessi drive aesthetic differentiation through museum collaborations.
- Foodservice:Quick-service and fast-casual operators specify cost-engineered grades with 90-day replacement cycles. Tramontina dominates Latin American foodservice procurement.
- Catering:Rental and event supply companies balance durability against loss rates, favoring mid-weight stainless with laser-etched inventory codes.
- Hospitality:Hotels upgrade post-pandemic toward 18/10 collections that withstand 3,000+ commercial wash cycles.
- Educational Institutes:K-12 and university foodservice programs face budget constraints that sustain demand for 18/0 grades and plastic alternatives where permitted.
- Event Management:Wedding and corporate rental specialists source mixed-material collections for themed table settings.
Contract values peak in Hospitality; Catering applications are gaining share fastest as experiential events rebound.
Customer Type:
Customer type segmentation distinguishes individual consumption from procurement decisions made by professional purchasing departments with formal certification requirements.
- Households:Direct-to-consumer channels emphasize design heritage and warranty terms. Zwilling J.A. Henckels and Villeroy & Boch compete on brand recognition.
- Restaurants:Independent operators and chains specify through group purchasing organizations that negotiate volume rebates on certified grades.
- Hotels:Procurement departments align tableware standards with star ratings, mandating REACH-compliant documentation for European properties.
- Cafes:Specialty coffee operators source demitasse spoons and cake forks through roaster co-branding programs.
- Catering Companies:Event rental specialists balance acquisition cost against loss tolerance and inventory tracking complexity.
- Institutional Buyers:Hospital, prison, and military foodservice programs specify through competitive bidding processes governed by ISO 8442 performance standards.
Order frequency concentrates in Restaurants; Hotels are expanding specification fastest as post-pandemic upgrade cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing scale for forged stainless steel exports, while Germany, the United States, France, and the UAE concentrate premium hospitality consumption. This production-consumption divide shapes trade flows and supplier qualification requirements across distinct regulatory environments.
China
Guangdong and Zhejiang provinces host forging clusters supplying 18/10 and 18/0 grades to North American and European foodservice distributors. The State Administration for Market Regulation enforces GB standards for food-contact metal articles. Yangjiang City anchors cutlery manufacturing through vertically integrated stainless steel processing and export logistics infrastructure.
Germany
Hotels in Bavaria and North Rhine-Westphalia specify REACH-certified forged collections from domestic heritage manufacturers. ECHA nickel migration thresholds compel laboratory documentation for all metal food-contact imports. Solingen maintains its blade-making tradition through ISO 8442-certified production for institutional procurement channels.
United States
Fast-casual chains and hotel groups drive stainless steel replacement cycles across Texas, California, and Florida markets. FDA food-contact substance notifications delay novel alloy introductions by 12-18 months. Chicago and New York City foodservice distributors consolidate purchasing through group buying organizations negotiating volume rebates.
France
Parisian hospitality procurement prioritizes silver-plated heritage craftsmanship for ultra-luxury positioning. ANSM enforces nickel release testing for metal articles in contact with food. The Christofle manufacturing base in Yvelines supplies Dubai and Riyadh hotel developments through established Middle East distribution partnerships.
United Arab Emirates
Dubai and Abu Dhabi hotel developments anchor regional demand for premium tableware collections meeting MOHAP food-contact material registrations. Import regulations require conformity assessment documentation for all metal utensils entering Saudi and UAE markets. Jebel Ali Free Zone concentrates redistribution logistics for African and South Asian hospitality projects.
Flatware Market Competitive Landscape
Top-tier vendors anchor heritage craftsmanship and forged stainless steel certification, while mid-scale fabricators compete on cost-engineered grades for institutional buyers. The vendor base stratifies across three tiers: ultra-luxury silver-plated specialists, ISO-certified forged stainless steel manufacturers, and volume-driven commodity suppliers. Two dominant competitive moves are reshaping positioning: strategic partnerships between European heritage brands and Middle Eastern hospitality developers, and backward integration into captive stainless steel forging capacity.
Within the heritage-manufacturer tier, WMF and Christofle exemplify divergent positioning archetypes—German forged stainless steel certification against French silver-plated craftsmanship. Zwilling J.A. Henckels occupies a position bridging premium consumer retail and institutional foodservice supply. Tramontina represents the scale-driven Latin American fabricator archetype competing on cost-engineered programs for North American buyers.
| Leading Market Players |
|---|
| Villeroy & Boch |
| Georg Jensen |
| WMF |
| Robert Welch |
| Rösle |
| Oneida |
| Christofle |
| Tramontina |
| Zwilling J.A. Henckels |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap forging specialists in Solingen and Yangjiang anchor supply discipline through generational capital structures that resist short-term price wars. Their patient ownership models sustain ISO 8442 certification investments while commodity-grade competitors slash quotes to capture institutional tenders.
Pricing Analysis
Margin tightening in economy-grade stainless traces to nickel price volatility and battery-sector competition for the same metal inputs. Three-tier pricing structure across heritage-certified, ISO-compliant, and commodity grades separates Christofle silver-plated collections from WMF forged programs and Tramontina cost-engineered lines. Price differentiation hinges on REACH certification documentation and dishwasher-cycle durability ratings. Cost-down pressure accelerates as Chinese export mills absorb currency adjustments to defend volume placements. Quick-service chains exhibit highest price sensitivity; Dubai hotel developers show lowest.
Supply Chain Analysis
Skilled forging workforce availability in Guangdong, Solingen, and Yangjiang constrains capacity expansion despite automated polishing investments. Raw material flows draw from Indonesian nickel laterite, South African chromium, and Brazilian iron ore feedstocks. Single-source vulnerability concentrates in Yangjiang's vertically integrated forging clusters, where port congestion disrupts European lead times. Distribution runs through Hamburg and Jebel Ali Free Zone redistribution hubs serving foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH nickel migration thresholds construct a cost-of-compliance moat that rewards ECHA-certified incumbents while stranding plastic-alternative inventory. This regulatory barrier elevates qualified supplier premiums and compresses the viable vendor base.
For Market Incumbents: Cement REACH documentation advantages through captive laboratory partnerships in Germany and France. Expand Yangjiang forging capacity to capture nickel-price dips before battery-sector demand spikes. Defend against Christofle's Middle East ultra-luxury positioning by securing Dubai hotel development partnerships with bundled maintenance programs.
For New Entrants and Emerging Players: FDA food-contact substance notification requirements in the United States open a window for alloy-innovation specialists with pre-submission regulatory expertise. Target Latin American institutional buyers through Brazilian forging joint ventures that bypass Chinese tariff exposure. Lead with ISO 8442 blade-hardness certification as procurement gatekeeper in European hospital and prison foodservice RFPs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Yangjiang forging assets with dormant EU export certifications awaiting laboratory renewal. Long-term viability centers on nickel-input hedging capabilities and hospitality channel relationships. Watch nickel LME inventory drawdowns as inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | ECHA-recognized laboratory partnerships unlock European hospitality procurement tiers. |
| Backward Integration into Forging | Captive Yangjiang capacity insulates margin from nickel price volatility. |
| Middle East Distribution Partnership | Jebel Ali Free Zone logistics anchor Dubai and Riyadh hotel supply chains. |
| Laser-Surface Texturing Adoption | Single-process grip finishing collapses German and French production steps. |
| Serving Set Category Expansion | Shared-plate format penetration in Shanghai restaurants expands contract values. |
Research Methodology
Trade flow databases, ECHA regulatory filings, and hospitality procurement records formed the secondary backbone for this analysis. Primary interviews with foodservice distribution managers, hotel procurement directors, forging plant engineers, and regulatory compliance officers supplied operational validation. Bottom-up unit economics triangulated against top-down sector spending estimates across the analysis window.
Historical trendline analysis anchored volume and value projections across material grade, product type, and customer type segmentation dimensions. CAGRs derived from fitted growth curves incorporating nickel price cycles, REACH enforcement intensity, and hospitality capital expenditure patterns. Industry-specific inputs included commercial dishwasher replacement cycle data and group purchasing organization contract renewal schedules.
Caveats apply where nickel supply disruptions, REACH threshold tightening, or state-level plastic ban accelerations could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and hospitality upgrade cycle durability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Candle Air Fresheners Market
Household Items
Microwave Safe Utensils Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Luxury Massage Chair Market
Household Items
US Air Fresheners Market
Household Items
Global Paper Towels Market
Household Items
Knife Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Global Sports Bottle Market
Household Items
Chest Freezers Market
Household Items
Portable Humidifiers Market
Household Items
Russia Residential Water Heaters Market
Household Items
Cast Iron Cookware Market
Household Items
Party Supplies Market
Household Items
Moving Supplies Market
Household Items
Smart Drying Racks Market