
 Middle East and Africa B2B Air Care Market | 2026-2036
Middle East and Africa B2B Air Care Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa B2B Air Care Market Foresight
UAE-based manufacturing capacity for commercial-grade air care systems is hardening as Gulf producers expand solvent-free formulation lines. S.C. Johnson & Son Inc. leverages its regional distribution partnerships to anchor supply across Saudi Arabian hospitality corridors. Reckitt Benckiser Group plc sustains institutional penetration through concentrated refills designed for high-traffic healthcare environments. Henkel AG & Co. KGaA competes on professional-grade dispensing technology calibrated for Middle Eastern climate conditions.
Middle East and Africa B2B air care encompasses engineered scent delivery, air purification, and climate-controlled humidity management for commercial and institutional environments, typically operating through HVAC-integrated diffusion or standalone electromechanical units with particulate filtration thresholds below 2.5 microns. The category serves odor control, pathogen mitigation, and occupant wellbeing objectives in enclosed public spaces. Air Fresheners dominate current value flows due to low capital requirements and rapid deployment in retail and hospitality settings, while Air Purifiers represent the fastest-expanding product class as healthcare facilities and educational institutions upgrade ventilation infrastructure. The Service Type dimension shows Maintenance capturing recurring revenue pools as equipment fleets mature across South Africa and Nigeria.
MOHAP in the UAE and South Africa's National Regulator for Compulsory Specifications enforce volatile organic compound limits and electrical safety standards that filter non-compliant imports from Asian suppliers. REACH-aligned substance restrictions in Gulf Cooperation Council markets are elevating formulation costs for legacy solvent-based products. Facility managers and procurement officers must track regulatory harmonization between national standards and emerging Gulf technical regulations to avoid stranded inventory positions.
Market Dynamics
MOHAP's indoor air quality mandates are compressing upgrade cycles across UAE commercial real estate, forcing facility managers to replace legacy solvent-based systems before end-of-life. This regulatory compression is redistributing capital toward HVAC-integrated diffusion platforms and away from standalone units.
Growth Catalysts
- Green building certification:South Africa's Green Star rating system is mandating air quality monitoring in new commercial developments, creating specification pull for integrated humidity management systems.
- MOHAP VOC limits:The UAE's tightening volatile organic compound thresholds are filtering non-compliant imports and opening procurement lanes for regional solvent-free formulation producers.
- Hospitality corridor expansion:Dubai and Cape Town hotel construction pipelines are specifying ambient scenting as standard guest experience infrastructure, not optional amenity.
Market Restraints
- Input cost volatility:Essential oil feedstock prices fluctuate with climate stress on Somali and Kenyan agricultural supply zones, squeezing margin on natural formulation lines.
- Supply concentration risk:Electromechanical diffusion hardware concentrates in East Asian manufacturing clusters, exposing procurement timelines to Red Sea shipping disruption.
- Technical limitation:Particulate filtration below 2.5 microns in high-dust Gulf climates requires accelerated filter replacement cycles that inflate total cost of ownership.
Strategic Opportunities
- Nigerian commercial property:Lagos office stock lacks air quality infrastructure relative to tenant expectations, creating first-mover advantage for service-integrated equipment leasing.
- Healthcare ventilation mandates:South Africa's National Regulator for Compulsory Specifications is expanding electrical safety standards to clinic networks, accelerating replacement demand.
- IoT-HVAC convergence:Sensor-enabled diffusion systems that adjust scent intensity to occupancy density are opening subscription revenue pools in Saudi Arabian mall operators.
Industry Challenges
- Certification timeline compression:Gulf Cooperation Council REACH alignment is requiring dual-track testing for legacy formulations, straining R&D bandwidth at mid-tier suppliers.
- Integration complexity:Facility management software in South African property portfolios lacks API compatibility with new-generation air quality monitoring hardware, forcing manual bridging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa B2B Air Care Market |
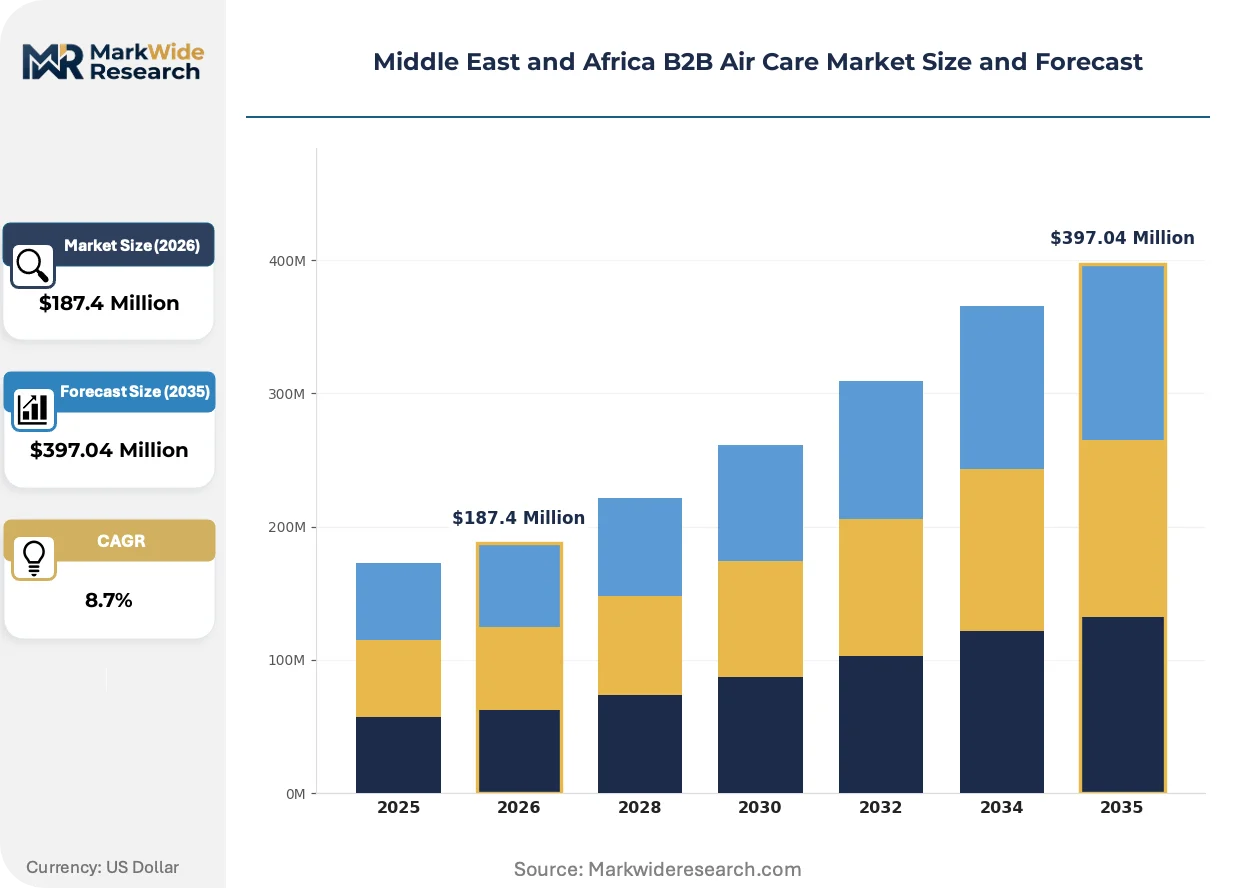
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Purifiers, Dehumidifiers, Air Fresheners, HVAC Systems Service Type: Installation, Maintenance, Consulting, Training End User: Commercial Spaces, Healthcare Facilities, Educational Institutions, Hospitality Distribution Channel: Direct Sales, Wholesale, Online, Retail |
| Companies Covered | S.C. Johnson & Son Inc., Reckitt Benckiser Group plc, The Procter & Gamble Company, Henkel AG & Co. KGaA, CAR-FRESHNER (Little Trees), Air Delights, Inc., Rubbermaid Commercial Products, Zep Inc., The Claire Manufacturing Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa B2B Air Care Market Shifts & Advancements
Scent delivery architecture is fragmenting from centralized HVAC diffusion toward distributed node networks, compressing installation lead times and opening retrofit markets previously blocked by ductwork access constraints.
Ultrasonic micro-diffusion is decentralizing fragrance deployment in Saudi Arabian hospitality settings. Boutique hotel operators in Jeddah are installing battery-powered tabletop units that bypass mechanical infrastructure entirely. This shift is decentralizing procurement authority from central engineering departments to individual property general managers, compressing decision cycles but fragmenting vendor relationships.
REACH-aligned substance restrictions across Gulf Cooperation Council markets are elevating formulation costs for legacy solvent-based air care products. Industrial buyers are responding by consolidating supplier relationships with regional manufacturers possessing in-house compliance laboratories. Healthcare facilities in the UAE face the steepest cost adjustment, as patient safety protocols prohibit rapid formulation switching.
Facility managers in Dubai's commercial towers are unbundling equipment ownership from maintenance service, preferring operating leases with performance guarantees over capital purchase. This shift displaces traditional distributor margins on hardware sale and concentrates value capture with service-integrated providers capable of remote diagnostics. The pattern is most visible in premium office stock seeking Green Star alignment.
Middle East and Africa B2B Air Care Market Segmentation
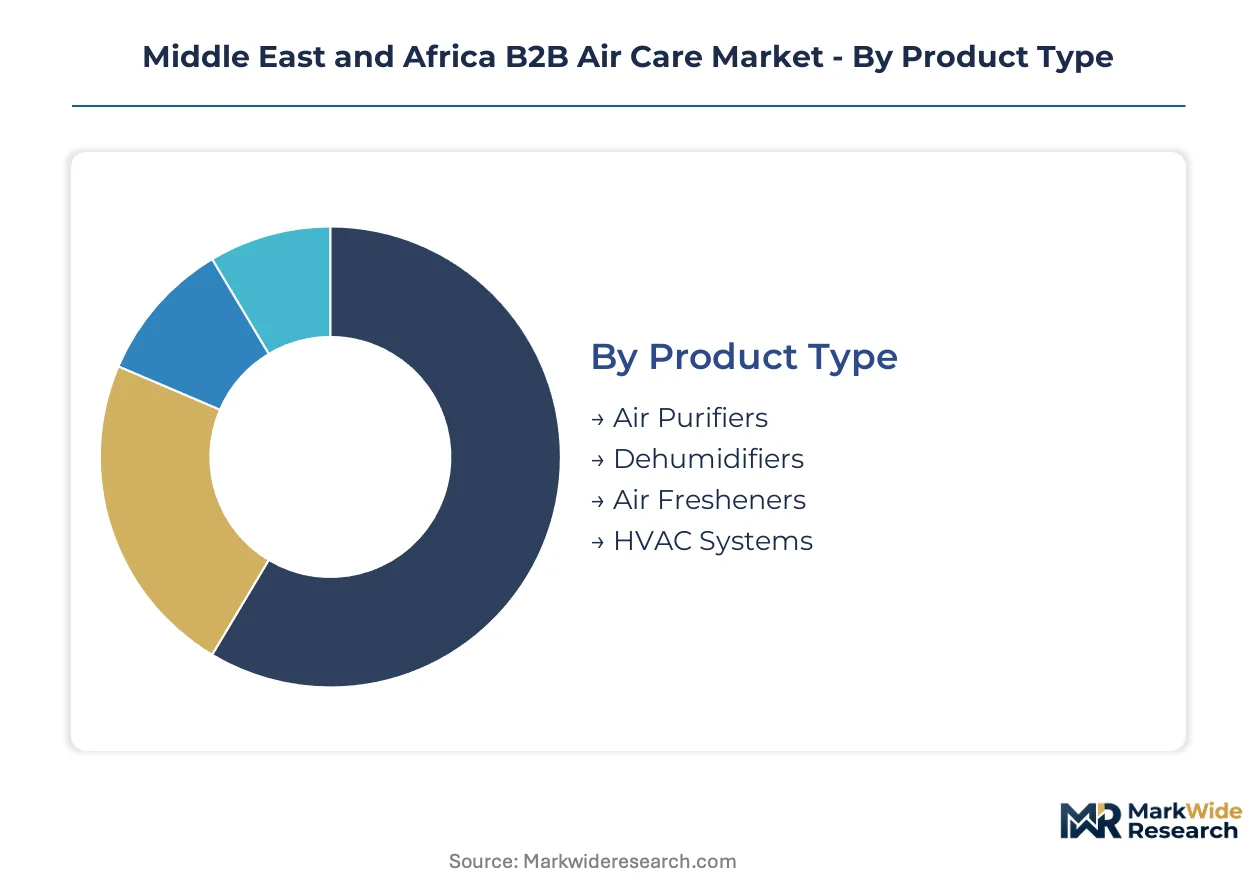
Segmentation in Middle East and Africa B2B air care reveals divergent procurement logics across product architecture, service integration, and facility type. Procurement officers weight capital intensity against regulatory compliance timelines differently across Dubai hospitality towers and Lagos office developments.
Product Type:
Technology sophistication and particulate filtration thresholds differentiate equipment classes across commercial and institutional deployments.
- Air Purifiers:Electromechanical units with HEPA or activated carbon filtration targeting particulate matter below 2.5 microns. Healthcare facilities in South Africa and educational institutions in the UAE are upgrading ventilation infrastructure to meet tightening indoor air quality mandates, driving specification pull for integrated purification systems.
- Air Fresheners:Solvent-based or natural formulation dispensing systems, including aerosol, gel, and HVAC-integrated diffusion technologies. Hospitality corridors across Dubai and Cape Town specify ambient scenting as standard guest experience infrastructure, with low capital requirements enabling rapid deployment in retail and hotel settings.
- Dehumidifiers:Climate-controlled humidity management units addressing Gulf coastal moisture conditions and seasonal variations in Nigerian commercial property.
- HVAC Systems:Centralized building ventilation platforms with integrated air quality monitoring and automated filtration cycling.
Mature deployment sits with Air Fresheners. Newer deployment is concentrated in Air Purifiers.
Service Type:
Revenue model architecture shifts from transactional hardware sale toward recurring service relationships as equipment fleets mature.
- Maintenance:Recurring service contracts covering filter replacement, calibration, and compliance documentation. South African property portfolios and Nigerian commercial developments are unbundling equipment ownership from service provision, concentrating value capture with providers capable of remote diagnostics and performance guarantees.
- Installation:Project-based deployment of diffusion hardware and ventilation infrastructure, with lead times compressed by distributed node networks bypassing ductwork constraints.
- Consulting:Regulatory compliance advisory and Green Star alignment services for facility managers navigating MOHAP VOC limits and Gulf Cooperation Council REACH alignment.
- Training:Operator certification programs for electromechanical system management in healthcare and hospitality environments.
Revenue concentration is shifting toward Maintenance as installed bases expand. Installation captures project-based volume in new construction pipelines.
End User:
Facility type dictates specification intensity, with healthcare and hospitality driving premium equipment deployment.
- Healthcare Facilities:Hospitals and clinic networks requiring pathogen mitigation and patient safety protocols. South Africa's National Regulator for Compulsory Specifications is expanding electrical safety standards to clinic networks, accelerating replacement demand for compliant ventilation infrastructure.
- Hospitality:Hotels and resorts deploying ambient scenting for guest experience differentiation. Dubai and Cape Town construction pipelines specify integrated diffusion as standard infrastructure, not optional amenity.
- Commercial Spaces:Office towers and retail developments in Lagos and Johannesburg seeking Green Star certification and tenant-aligned air quality infrastructure.
- Educational Institutions:Schools and universities upgrading ventilation systems to meet occupancy density and health protocol requirements.
Specification pull from Healthcare Facilities is climbing the fastest. Commercial Spaces represent the largest addressable volume base.
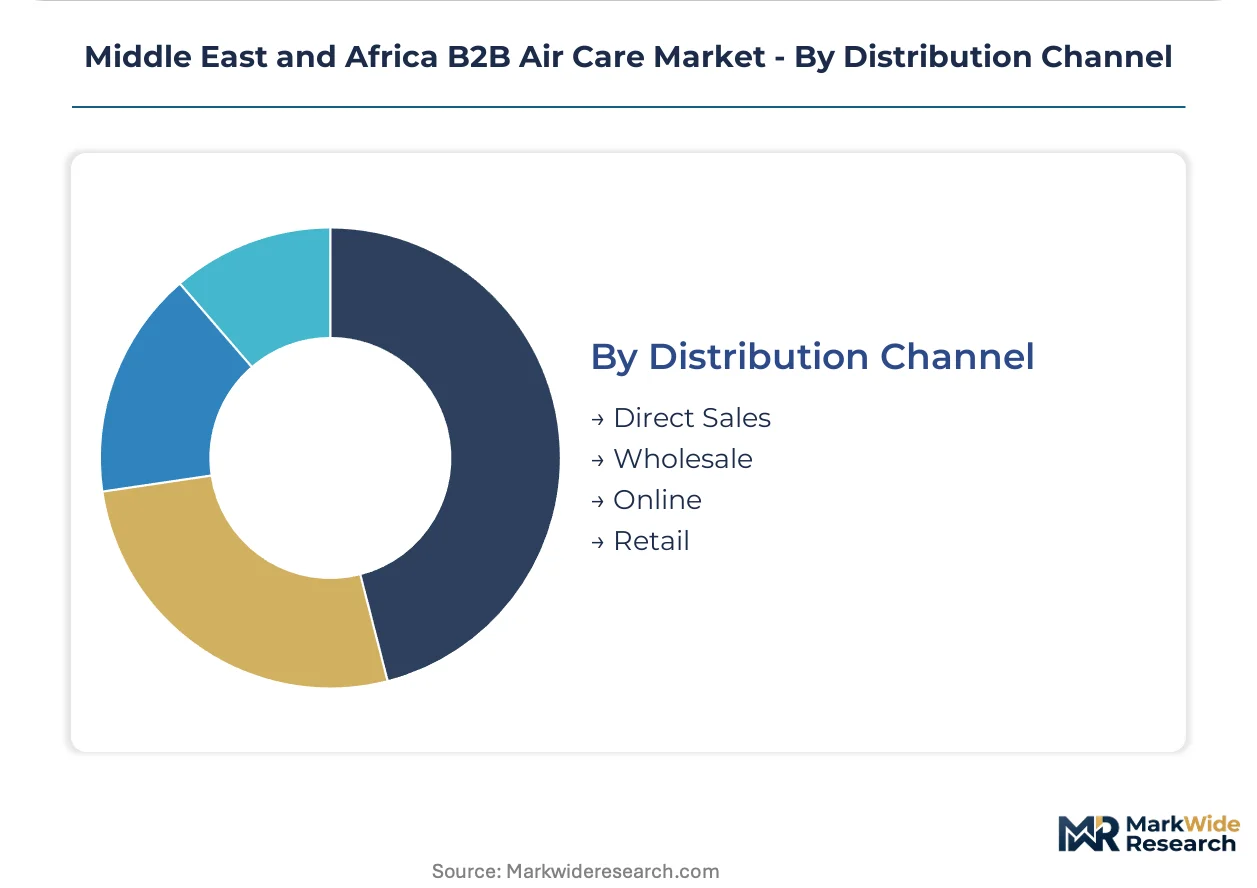
Distribution Channel:
Channel structure reflects procurement authority fragmentation and service integration requirements.
- Direct Sales:Manufacturer-to-facility relationships for large-scale hospitality and healthcare deployments. S.C. Johnson and Reckitt Benckiser anchor supply across Saudi Arabian corridors through direct institutional partnerships.
- Wholesale:Distributor networks serving mid-tier commercial property and retail installations with consolidated procurement timelines.
- Online:Digital procurement platforms capturing replacement consumables and small-format equipment orders.
- Retail:Bricks-and-mortar channels for standalone units and consumer-grade diffusion products.
Direct Sales dominates premium hospitality and healthcare procurement. Wholesale channels fragment across mid-market commercial property.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Somali frankincense harvesting and Kenyan eucalyptus cultivation anchor essential oil feedstock flows into Middle East and Africa B2B air care formulation. Climate stress on these agricultural zones compresses raw material availability timelines for regional manufacturers.
United Arab Emirates
Dubai hospitality towers and Abu Dhabi healthcare complexes drive specification pull for HVAC-integrated diffusion systems. MOHAP's volatile organic compound thresholds filter non-compliant imports and open procurement lanes for regional solvent-free producers. Jebel Ali industrial corridors host expanding manufacturing capacity for commercial-grade electromechanical units.
Saudi Arabia
Riyadh mall operators and Jeddah boutique hoteliers deploy sensor-enabled scent systems adjusting intensity to occupancy density. The Saudi Food and Drug Authority aligns with Gulf Cooperation Council REACH substance restrictions, elevating compliance documentation requirements. Eastern Province petrochemical complexes supply feedstock for regional formulation diversification.
South Africa
Johannesburg commercial property portfolios and Cape Town hotel construction pipelines mandate air quality infrastructure for Green Star certification. The National Regulator for Compulsory Specifications expands electrical safety standards to clinic networks, accelerating replacement demand. Durban manufacturing zones concentrate maintenance service providers with remote diagnostic capabilities.
Nigeria
Lagos office stock lacks air quality infrastructure relative to tenant expectations, creating first-mover advantage for service-integrated equipment leasing. The country's national environmental regulator enforces indoor air quality guidelines in federal buildings, compressing upgrade cycles. Abuja government complexes pilot performance-guaranteed operating leases unbundling ownership from maintenance.
Egypt
Cairo healthcare facilities and Alexandria hospitality developments upgrade ventilation infrastructure to meet occupancy density protocols. The country's national standards body harmonizes electrical safety requirements with Gulf technical regulations, straining certification timelines for imported equipment. Suez Canal logistics corridors expose procurement timelines to Red Sea shipping disruption.
Middle East and Africa B2B Air Care Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue IoT-enabled service integration and solvent-free formulation specialization. Market structure concentrates around multinational chemical conglomerates with regional distribution partnerships and mid-tier regional manufacturers with in-house compliance laboratories. Three archetypes dominate: hospitality-focused scent specialists, healthcare-certified purification providers, and facility management-integrated service operators. Competitive moves center on strategic partnerships with property developers and geographic expansion through distributor network consolidation.
Within the multinational tier, S.C. Johnson & Son Inc. and Reckitt Benckiser Group plc exemplify scale-driven positioning anchored across Saudi Arabian hospitality corridors and UAE healthcare networks. Henkel AG & Co. KGaA occupies a specialist position in professional-grade dispensing technology calibrated for Middle Eastern climate conditions. These three entities represent divergent strategic emphases: Johnson anchors supply through institutional partnerships, Reckitt sustains penetration through concentrated refill formats, and Henkel competes on electromechanical calibration expertise.
| Leading Market Players |
|---|
| S.C. Johnson & Son Inc. |
| Reckitt Benckiser Group plc |
| The Procter & Gamble Company |
| Henkel AG & Co. KGaA |
| CAR-FRESHNER (Little Trees) |
| Air Delights, Inc. |
| Rubbermaid Commercial Products |
| Zep Inc. |
| The Claire Manufacturing Company |
| Others |
Supply & Pricing Matrix
Essential oil feedstock costs from Somali frankincense harvesting and Kenyan eucalyptus cultivation cascade through formulation tiers, compressing margins on natural product lines while elevating price floors for solvent-free alternatives that comply with MOHAP volatile organic compound thresholds.
Pricing Analysis
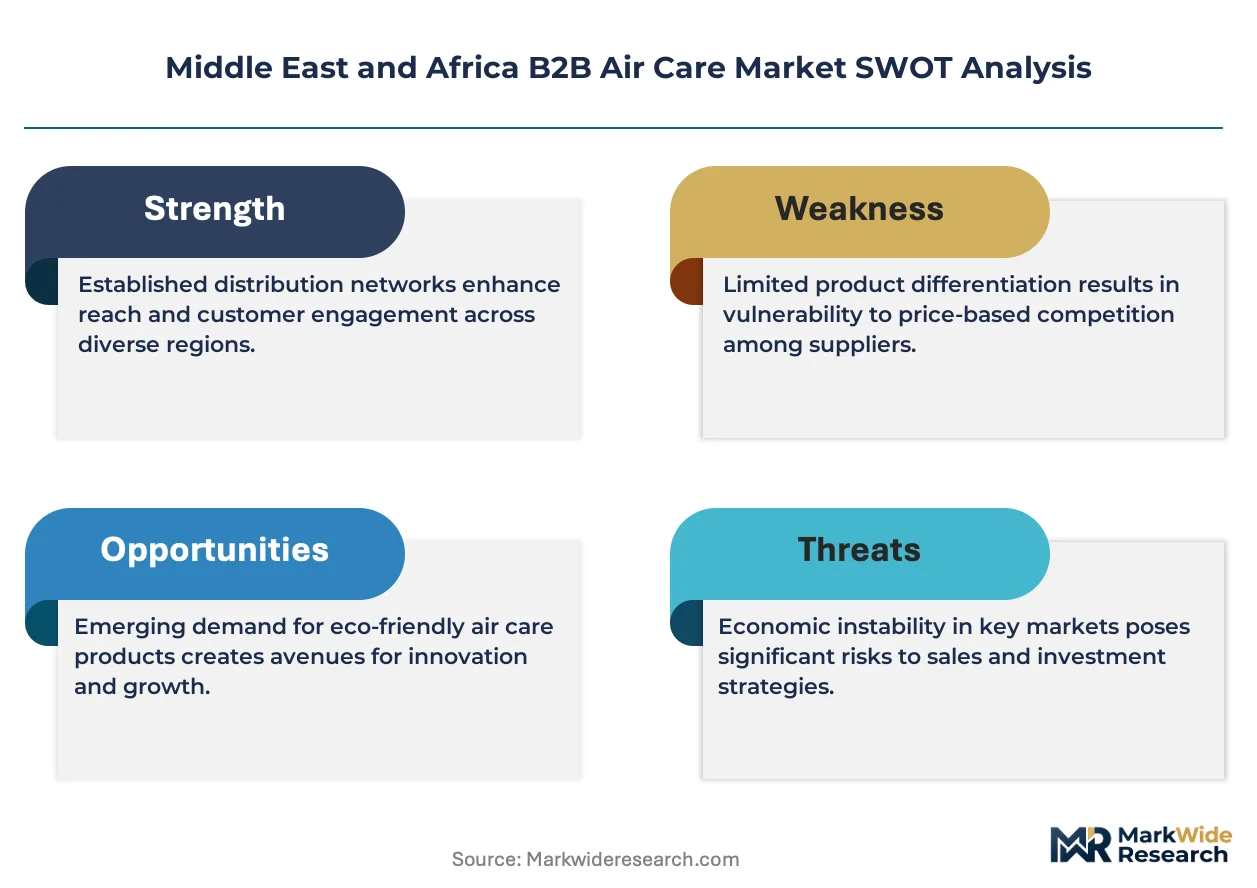
Warranty and service bundling separates capital purchase arrangements from performance-guaranteed operating leases across Dubai commercial towers and Saudi Arabian mall portfolios. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade against MOHAP compliance timelines and HVAC integration complexity. Pricing pressure stems from accelerated filter replacement cycles in high-dust Gulf climates inflating total cost of ownership. Healthcare facilities exhibit lowest price sensitivity due to patient safety protocols prohibiting rapid formulation switching, while Lagos office developments show highest sensitivity as tenant-funded upgrades compete with base rent economics.
Supply Chain Analysis
Workforce availability constraints in East Asian electromechanical manufacturing clusters and Jebel Ali industrial corridors compress production timelines for diffusion hardware. Supply concentrates in China, South Korea, and the UAE for electromechanical units, while essential oil formulation draws from Somali and Kenyan agricultural zones. Single-source vulnerability sits with Red Sea shipping corridors exposing procurement timelines to disruption. Distribution runs through direct institutional partnerships for premium hospitality and healthcare deployments, with wholesale networks fragmenting across mid-market commercial property.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over solvent-free formulation laboratories and remote diagnostic service platforms determines margin capture against compliance-driven upgrade cycles.
For Market Incumbents: Deploy captive supply of essential oil feedstocks through backward integration into Somali and Kenyan agricultural zones to defend margin position against climate-driven input volatility. Anchor channel control through exclusive service-integrated leasing arrangements with Dubai hospitality towers and Riyadh mall operators, locking out mid-tier competitors lacking remote diagnostic capabilities. Certification investment in Gulf Cooperation Council REACH alignment laboratories creates switching costs for healthcare facilities facing patient safety protocol constraints. For New Entrants and Emerging Players: The premium-to-economy price gap in Nigerian commercial property offers first-mover positioning through service-integrated equipment leasing targeting Lagos office stock lacking air quality infrastructure. IoT-enabled sensor diffusion systems adjusting scent intensity to occupancy density capture subscription revenue pools in Saudi Arabian retail corridors underserved by incumbent hardware-sale models. Partner with facility management software providers to bridge API compatibility gaps in South African property portfolios, converting integration complexity into competitive differentiation. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional manufacturers with in-house compliance laboratories in South Africa and the UAE, where Gulf technical regulation harmonization strains R&D bandwidth at mid-tier suppliers. Long-term viability over the analysis window hinges on service-integrated business models displacing transactional hardware sale as Dubai commercial towers unbundle ownership from maintenance. Watch for MOHAP enforcement intensity as inflection indicator accelerating compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive sourcing from Somali frankincense zones hedges climate-driven input volatility. |
| Service-Integrated Equipment Leasing | Operating lease models with remote diagnostics capture recurring revenue from Lagos office developments. |
| IoT-HVAC Convergence Platform | Sensor-enabled diffusion systems open subscription pools in Saudi Arabian mall operators. |
| Compliance Laboratory Investment | In-house Gulf Cooperation Council REACH testing accelerates formulation approval timelines. |
| Green Star Certification Advisory | Consulting services for Johannesburg commercial property align air quality infrastructure with rating mandates. |
Research Methodology
Document review covered MOHAP regulatory filings, South Africa National Regulator for Compulsory Specifications standards, Gulf Cooperation Council technical regulations, and trade customs data, complemented by interviews with facility management directors, hospitality procurement officers, healthcare biomedical engineers, and commercial property portfolio managers. Secondary validation drew from SEC filings of multinational chemical conglomerates, Green Star certification databases, and hospitality construction pipeline disclosures. Bottom-up equipment deployment modeling triangulated against top-down market sizing across product type, service integration, and facility category dimensions.
Segment-level outputs across the analysis window reflect equipment fleet maturity curves, regulatory compliance timeline compression, and hospitality construction pipeline specifications. The analytical framework modeled product type segmentation against service integration intensity, end-use facility requirements, and distribution channel structure. CAGRs were derived from installed base expansion rates, replacement cycle acceleration, and unbundling of ownership from maintenance service. Forecast inputs incorporated MOHAP enforcement trajectory, Green Star certification adoption curves, and Red Sea logistics corridor stability.
Inputs from MOHAP, South Africa's National Regulator for Compulsory Specifications, and Gulf Cooperation Council regulatory bodies were available through the study window; gaps in real-time hospitality construction pipeline data and essential oil harvest yield projections introduce uncertainty bands around equipment deployment forecasts. Material deviation in MOHAP enforcement intensity, Red Sea shipping disruption duration, or Green Star certification mandate expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Showers Market
Household Items
Gas Hobs Market
Household Items
Smart Pool Skimmer Market
Household Items
Toilet Deodorant Market
Household Items
Infuser Water Bottles Market
Household Items
Kitchen Towel Market
Household Items
Smart Memory Foam Market
Household Items
Porcelain Tableware Market
Household Items
Mirror Holder Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Luxury Massage Chair Market
Household Items
Hands-Free Faucet Market
Household Items
Electric Tealight Candles Market
Household Items
Cookware Market
Household Items
Dishwashing Products Market