
 North America Abrasives Market | 2026-2036
North America Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Abrasives Market Analytics
Market Context
Industrial supply distribution is tilting toward direct OEM partnerships and specialized distributor networks. 3M Company leverages its vertical integration across coated abrasives to sustain pricing power in automotive finishing. Saint-Gobain anchors North American production through bonded abrasive manufacturing scale in the United States. Norton Abrasives competes on brand recognition and technical service density across metalworking job shops.
Technical Definition and Segment Structure
North America abrasives comprise hard mineral particles bonded to backing materials or formed into grinding wheels, with specifications spanning grit sizes from ultrafine 1200-mesh to coarse 24-mesh for material removal and surface conditioning. Coated abrasives lead value contribution due to breadth across woodworking and automotive refinishing, while super abrasives command premium positioning in precision aerospace grinding. Bonded abrasives occupy mature, high-volume territory in construction and metal fabrication. Application demand in metalworking outpaces construction growth because of reshoring momentum and capital equipment refresh cycles.
Regulatory Framework
OSHA enforces permissible exposure limits on respirable crystalline silica from abrasive operations, while EPA National Emission Standards for Hazardous Air Pollutants constrain coating and curing processes in abrasive manufacturing. NHTSA fuel economy mandates indirectly shape demand through lightweighting trends that require specialized abrasive solutions for advanced materials. Stakeholders must monitor evolving silica rulemakings and state-level California Air Resources Board protocols that frequently prefigure federal standards.
Market Dynamics
OSHA silica exposure limits and EPA air quality standards are compressing permissible thresholds for abrasive dust emissions, forcing capital retooling across bonded abrasive manufacturing facilities and accelerating filtration technology deployment in metalworking operations.
Growth Catalysts
- Automotive Lightweighting Mandates:NHTSA fuel economy standards are driving specialized abrasive demand for advanced material machining in aluminum and carbon fiber composite processing across Michigan and Ohio manufacturing corridors.
- Reshoring Capital Investment:Tier suppliers are expanding precision grinding capacity in Mexico's manufacturing belt, generating pull-through demand for coated abrasives in automotive finishing operations.
- OSHA Enforcement Intensification:Tighter permissible exposure limits on respirable crystalline silica are compelling abrasive users to upgrade to engineered lower-dust formulations and automated grinding systems.
Market Restraints
- Raw Material Concentration Risk:Fused alumina and silicon carbide supply concentrates in limited domestic smelting capacity, exposing abrasive manufacturers to energy cost volatility and import dependency.
- Technical Substitution Pressure:Laser cutting and waterjet machining are displacing conventional abrasive grinding in thick-section metal fabrication, constraining volume growth in bonded abrasive wheels.
- Regulatory Compliance Friction:EPA National Emission Standards for Hazardous Air Pollutants extend coating and curing process timelines, lengthening new product qualification cycles for abrasive manufacturers.
Strategic Opportunities
- Underpenetrated Aerospace Super Abrasives:Canadian aerospace manufacturing clusters in Quebec and Ontario present expansion white space for diamond and CBN precision grinding solutions in turbine blade machining.
- California Air Resources Board Prefiguration:CARB protocols on volatile organic compound emissions from abrasive coatings frequently anticipate federal standards, creating first-mover certification advantages for compliant suppliers.
- Digital Grinding Parameter Optimization:Convergence of sensor telemetry and machine learning is enabling predictive abrasive wear monitoring, opening subscription-based service models for high-volume metalworking job shops.
Industry Challenges
- Specialized Technician Scarcity:Precision grinding operations require certified operators proficient in CNC programming and geometric dimensioning, with training pipeline gaps acute across the Great Lakes industrial belt.
- Legacy Equipment Integration Complexity:Automated abrasive systems must interface with decades-old grinding infrastructure prevalent in tier-two metal fabrication facilities, complicating retrofit deployments and extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Abrasives Market |
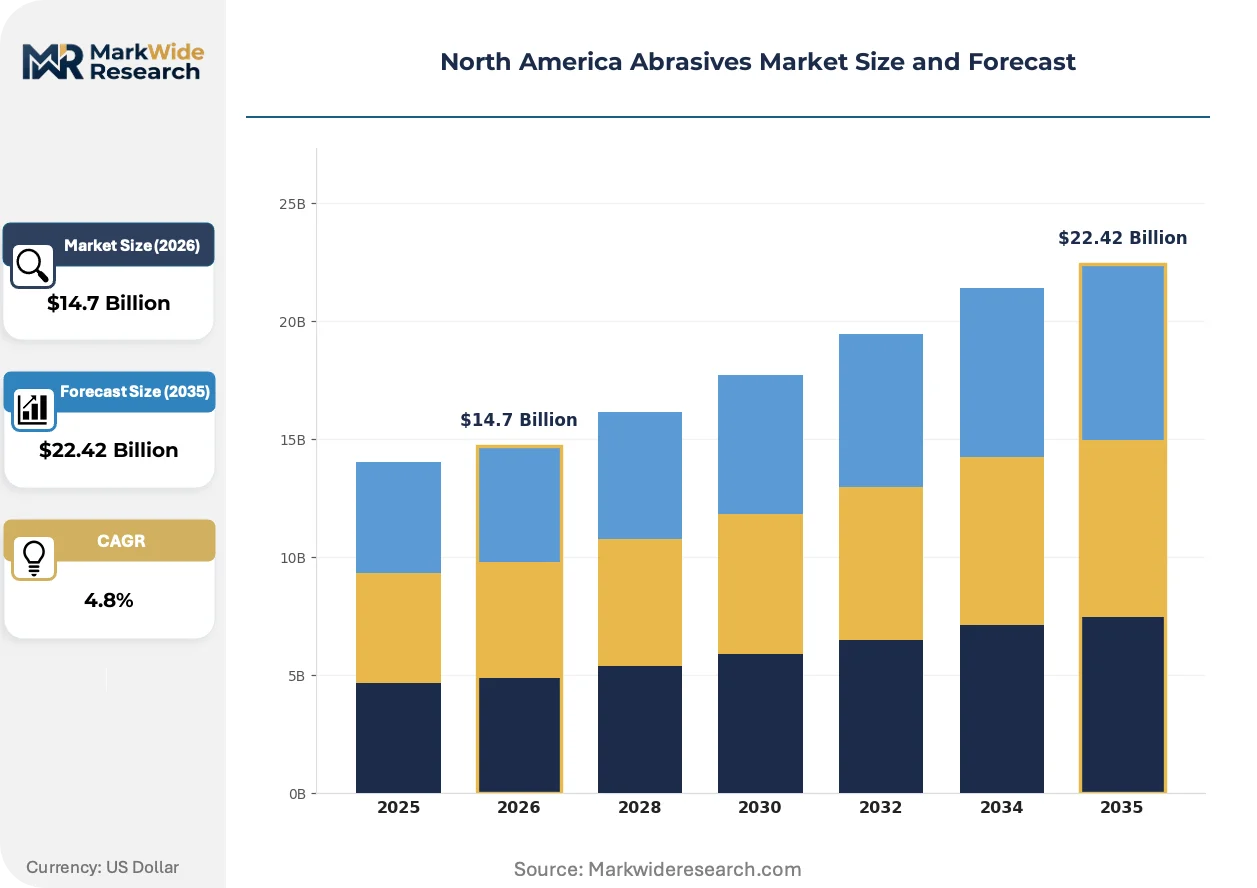
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bonded Abrasives, Coated Abrasives, Non-Woven Abrasives, Super Abrasives Application: Metalworking, Automotive, Construction, Woodworking End User: Aerospace, Electronics, Plastics, Marine Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | 3M Company, Saint-Gobain, Stanley Black & Decker, Robert Bosch GmbH, Norton Abrasives, Tyrolit Group, Flexovit USA, Asahi Diamond Industrial Europe, Carborundum Universal Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Abrasives Market Evolving Landscape
Digital process control and engineered grain structures are compressing traditional abrasive consumption models, while regulatory pressure on workplace exposure is accelerating filtration and closed-loop system adoption across North American manufacturing.
Engineered ceramic alumina grains with precisely controlled fracture properties are extending cut rates and wheel life in high-pressure grinding applications. Automotive OEMs in Michigan and Ohio are specifying these formulations for powertrain component machining. The technology is virtualizing conventional fused alumina supply relationships by enabling direct specification of grain chemistry rather than commodity purchasing.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is tightening volatile organic compound thresholds in abrasive coating operations. Manufacturers are reformulating resin bond systems and investing in thermal oxidizer upgrades to maintain production permits. Bonded abrasive facilities in the United States are consolidating coating operations to capture scale efficiencies in emissions control infrastructure.
Metalworking buyers are consolidating supplier relationships and demanding technical service density over transactional purchasing. Large automotive tier suppliers are reducing abrasive vendor counts from dozens to strategic partnerships with application engineering support. This concentration is most visible across Illinois and Indiana stamping and machining operations, where procurement teams prioritize joint process development over price-only negotiations.
North America Abrasives Market Segmentation
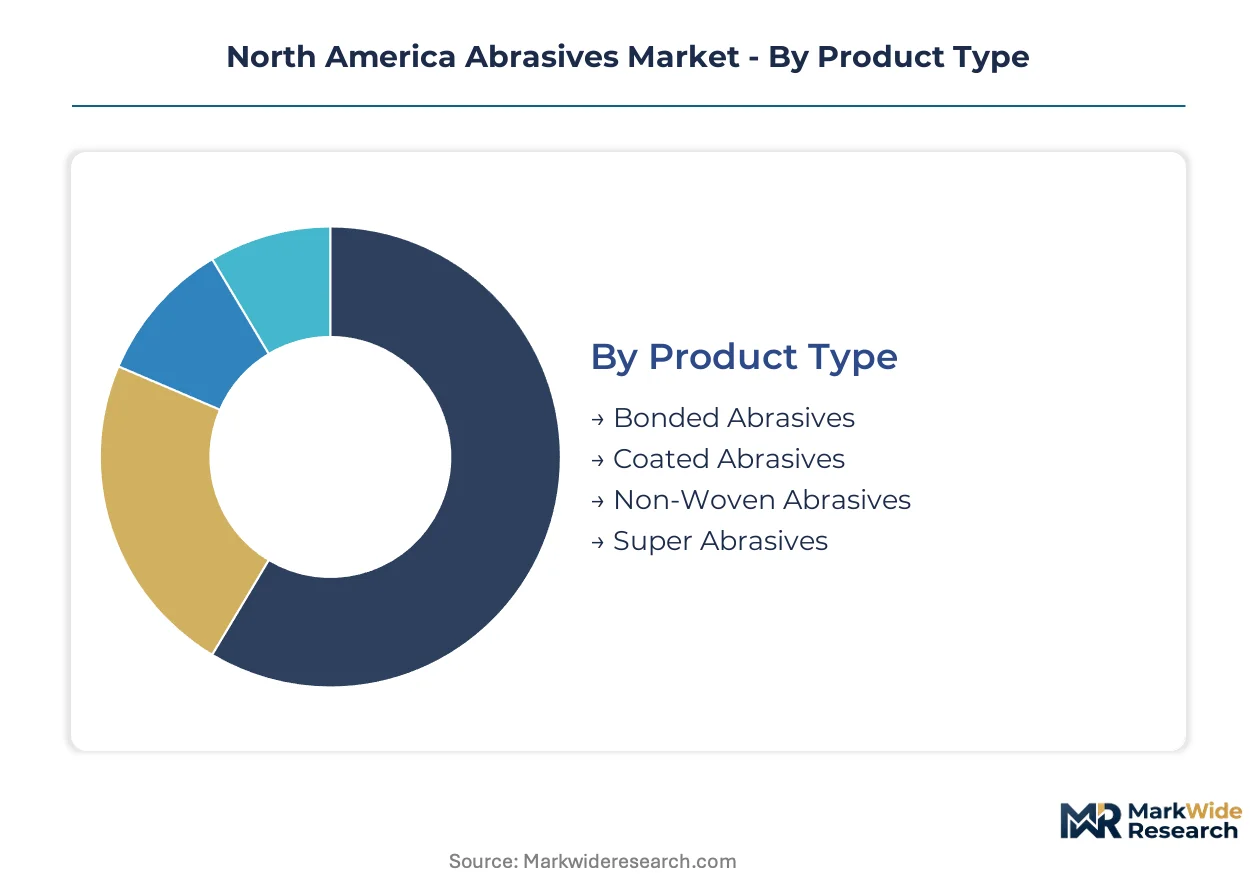
Abrasives procurement patterns diverge sharply by product physics and customer operational tempo. Cycle times range from daily consumable replenishment in automotive finishing to multi-year super abrasive wheel specifications in aerospace precision grinding.
Product Type:
Inventory velocity separates segments dramatically—coated abrasives turn monthly in high-volume automotive plants while super abrasive wheels sit on capital equipment for years.
- Coated Abrasives:Aluminum oxide or silicon carbide grains adhere to paper, cloth, or film backings in grit sequences from 24 to 1200. Michigan and Ohio automotive OEMs specify these for powertrain component finishing, with OSHA silica enforcement accelerating shifts to engineered ceramic alumina formulations that extend cut rates.
- Bonded Abrasives:Vitrified or resin bonds fuse abrasive grains into grinding wheels and cutting discs. Great Lakes metal fabrication shops consume these in high-volume structural steel processing, though laser cutting displacement constrains growth in thick-section applications.
- Non-Woven Abrasives:Nylon fiber matrices impregnated with abrasive grain enable conformable surface conditioning without substrate damage.
- Super Abrasives:Diamond and cubic boron nitride crystals bonded to precision substrates command premium positioning in aerospace turbine blade machining across Quebec and Ontario manufacturing clusters.
Bonded abrasives dominate installed base across construction and metal fabrication. Super abrasives are where expansion concentrates as reshoring drives precision grinding capital investment.
Application:
Margin structure inverts between segments—commoditized construction abrasives compete on freight logistics while automotive finishing commands application engineering premiums.
- Metalworking:Precision grinding, deburring, and surface preparation across CNC machining centers and manual bench operations. Illinois and Indiana stamping houses are consolidating supplier relationships toward technical service partnerships rather than transactional purchasing.
- Automotive:OEM paint preparation, powertrain component machining, and composite finishing for lightweighting mandates. NHTSA fuel economy standards pull specialized demand for aluminum and carbon fiber processing abrasives across Michigan manufacturing corridors.
- Construction:Concrete surface preparation, masonry cutting, and weld cleanup in commercial and infrastructure projects.
- Woodworking:Furniture manufacturing and millwork finishing, with coated abrasives specified for lacquer sanding sequences.
Metalworking anchors volume consumption across the Great Lakes industrial belt. Automotive finishing is climbing the fastest as tier suppliers expand Mexican manufacturing capacity.
End User:
Specification authority varies—electronics buyers delegate abrasive selection to contract manufacturers while aerospace OEMs retain direct certification control.
- Aerospace:Turbine blade grinding, airframe component finishing, and composite machining with stringent geometric tolerances. Canadian clusters in Montreal and Toronto drive super abrasive demand for nickel alloy precision work.
- Electronics:Semiconductor wafer dicing and printed circuit board depaneling with ultrafine grit requirements.
- Plastics:Injection mold polishing and thermoformed part finishing where non-woven abrasives prevent substrate glazing.
- Marine:Hull surface preparation and fiberglass finishing in Gulf Coast and Pacific Northwest shipyards.
Aerospace commands specification authority through OEM direct relationships. Electronics is gaining share fastest as reshoring revives domestic semiconductor packaging capacity.
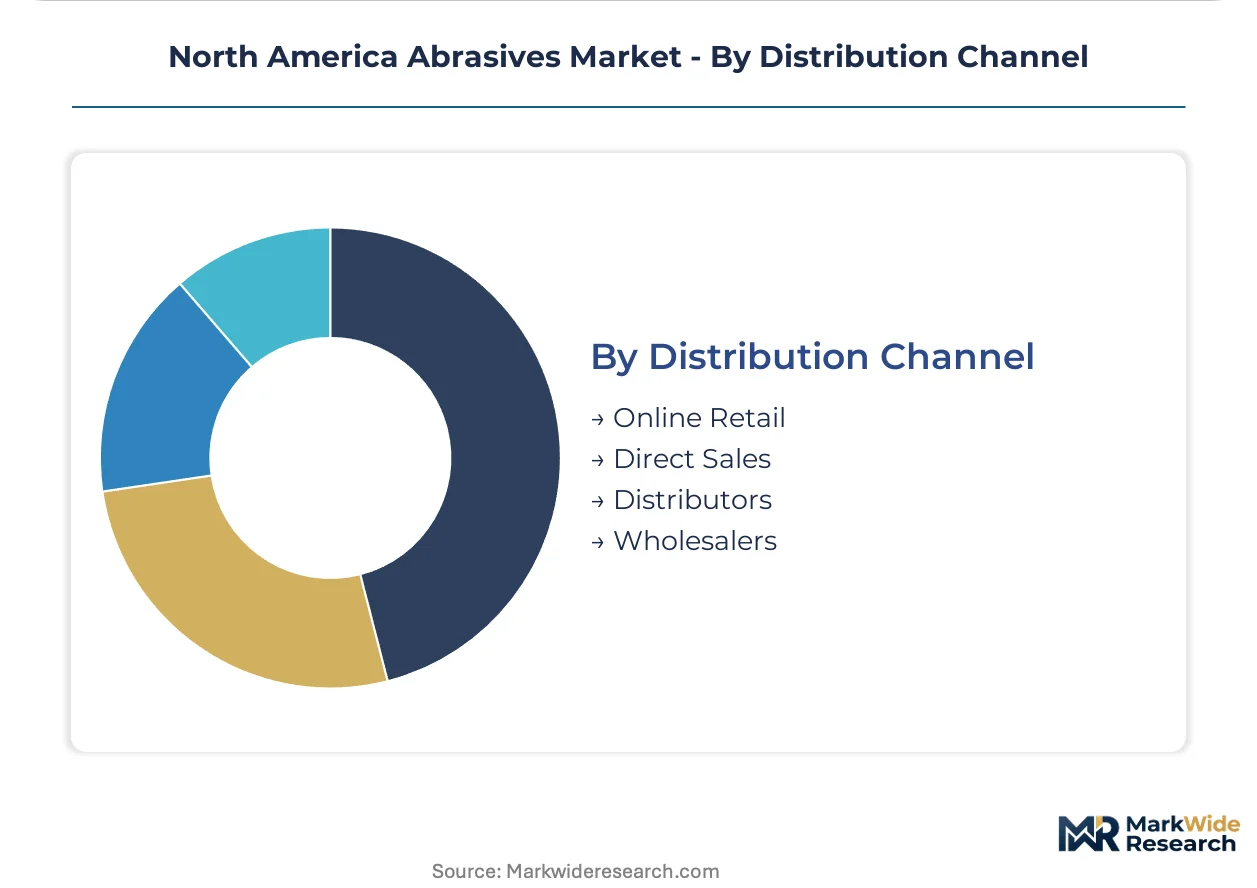
Distribution Channel:
Channel economics fragment by customer scale—direct sales capture engineering-intensive accounts while distributors serve fragmented job shop demand.
- Direct Sales:Application engineering teams embedded at major automotive tier suppliers and aerospace OEMs. Large metalworking operations across Ohio and Illinois are reducing vendor counts from dozens to strategic partnerships with joint process development.
- Distributors:Local inventory and technical service density for metalworking job shops and construction contractors. Saint-Gobain and 3M maintain authorized networks with grinding parameter training.
- Online Retail:Standardized SKU availability for small shop and maintenance-repair-operations purchasing.
- Wholesalers:Bulk volume aggregation for construction supply houses and industrial distributors serving secondary markets.
Distributors dominate reach into fragmented metal fabrication. Direct sales is where expansion concentrates as procurement teams consolidate strategic supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where OSHA enforcement drives premium formulations, while Mexico captures volume growth through tier supplier expansion without equivalent regulatory premium capture.
United States
Automotive OEMs in Michigan and Ohio specify engineered ceramic alumina grains for powertrain machining under NHTSA fuel economy mandates. EPA National Emission Standards for Hazardous Air Pollutants constrain coating operations at bonded abrasive facilities. The Great Lakes industrial belt spanning Illinois, Indiana, and Ohio anchors metalworking consumption as procurement teams consolidate supplier relationships toward technical service partnerships.
Canada
Aerospace manufacturing clusters in Quebec and Ontario generate super abrasive demand for turbine blade precision grinding in nickel alloy applications. Health Canada workplace exposure guidelines align with tightening silica thresholds. Montreal and Toronto manufacturing corridors concentrate diamond and cubic boron nitride specification authority through OEM direct relationships.
Mexico
Tier suppliers expanding precision grinding capacity across the Bajío Region and Nuevo León generate pull-through demand for coated abrasives in automotive finishing. Mexican federal labor authorities are harmonizing occupational exposure standards with US OSHA benchmarks. The manufacturing corridor from Querétaro to Guanajuato concentrates foreign direct investment in automotive component machining operations.
North America Abrasives Market Competitive Landscape
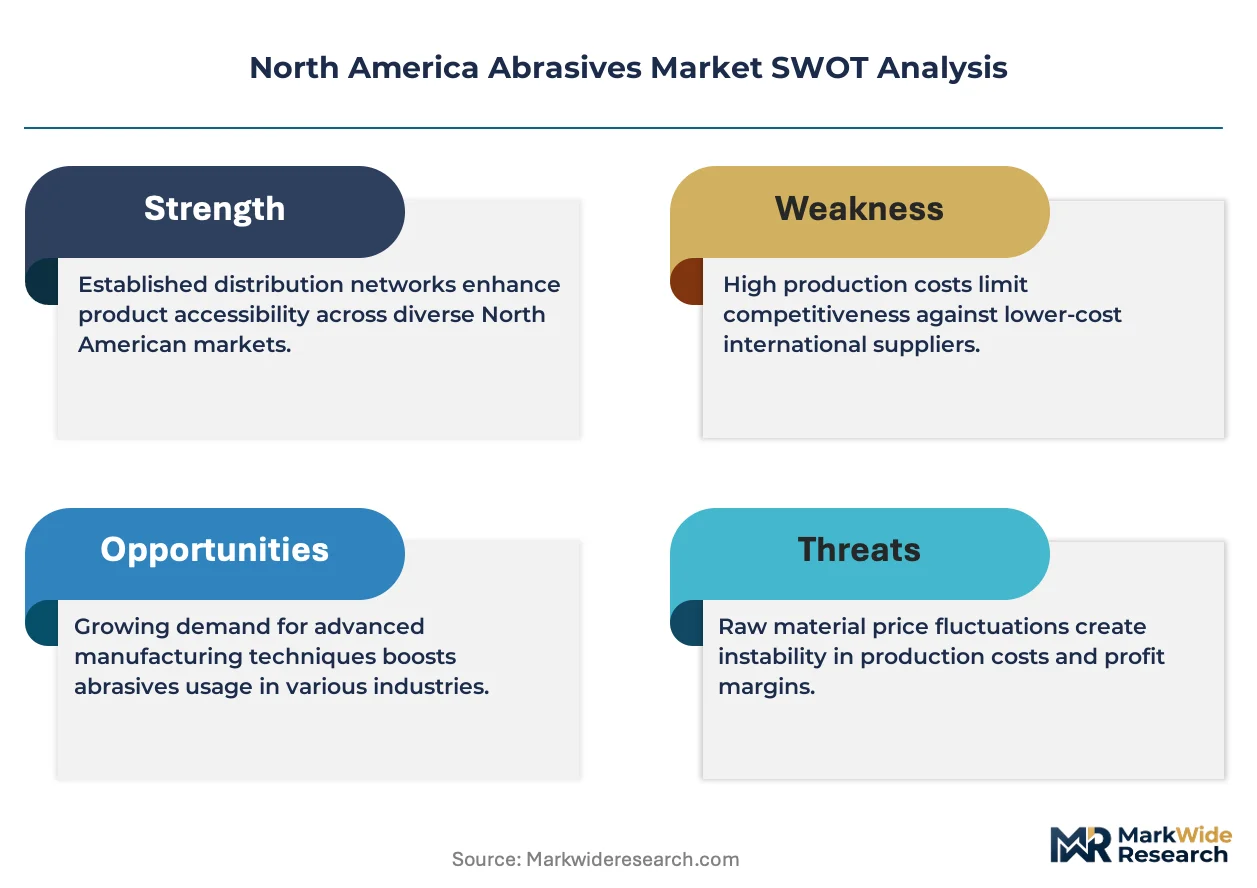
Platform integrators command the system tier; component specialists sit upstream in fragmented supply relationships. The vendor base clusters around three strategic archetypes: diversified materials conglomerates with captive abrasive divisions, pure-play abrasive manufacturers with technical service density, and industrial tool platforms distributing abrasives as consumable attachments. Competitive moves concentrate on strategic partnerships with automotive tier suppliers and filtration technology licensing for regulatory compliance.
Among diversified materials conglomerates, 3M Company and Saint-Gobain occupy positions that exemplify vertical integration from grain production through application engineering. Norton Abrasives represents the pure-play specialist archetype with brand recognition density across metalworking job shops. These three anchors illustrate how pricing power accrues to players controlling either upstream grain chemistry or downstream technical service embedding.
| Leading Market Players |
|---|
| 3M Company |
| Saint-Gobain |
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Norton Abrasives |
| Tyrolit Group |
| Flexovit USA |
| Asahi Diamond Industrial Europe |
| Carborundum Universal Ltd. |
| Others |
Value Network & Pricing Analysis
The Great Lakes industrial belt spanning Michigan, Ohio, and Illinois concentrates abrasive manufacturing capacity, with fused alumina smelters and bonded abrasive coating operations anchoring downstream pricing power for automotive OEMs and tier suppliers across the North American manufacturing corridor.
Pricing Analysis
Configured-to-order pricing for engineered ceramic alumina grains commands 15-40% premiums over standard fused alumina formulations in automotive powertrain machining. Three-tier pricing structure across premium, standard, and economy levels stratifies by grain chemistry precision and technical service bundling. Cost compression in commodity bonded abrasives is intensifying because laser cutting displacement erodes thick-section grinding volumes. Small metalworking job shops exhibit highest price sensitivity, while aerospace OEMs prioritize geometric tolerance certification over unit cost.
Supply Chain Analysis
Upstream feedstock for fused alumina and silicon carbide concentrates in limited United States smelting capacity, supplemented by Chinese and Brazilian import flows. Abrasive grain production draws from bauxite refining and petroleum coke processing, with resin bond systems depending on phenolic resin and ceramic frit supply. Single-source vulnerability in domestic smelting exposes manufacturers to energy cost volatility. Distribution runs through authorized distributor networks for fragmented job shops and direct application engineering teams for consolidated automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA silica enforcement and EPA National Emission Standards for Hazardous Air Pollutants constitute a regulatory inflection accelerating capital retooling and premium formulation demand across North American abrasive operations.
For Market Incumbents: Pre-empt technical substitution pressure from laser cutting and waterjet machining by deepening application engineering embedding at automotive tier suppliers. Invest in captive ceramic alumina grain production to defend margin position against commodity fused alumina price volatility. Accelerate filtration technology licensing to capture regulatory compliance spending across metalworking operations.
For New Entrants and Emerging Players: Establish a beachhead in Canadian aerospace super abrasives, where diamond and CBN precision grinding for turbine blade machining remains underpenetrated relative to Quebec and Ontario manufacturing scale. Target technical service partnerships with mid-tier metal fabrication shops across Illinois and Indiana as procurement teams consolidate vendor relationships. Lead with digital grinding parameter optimization platforms to differentiate from incumbent transactional supply.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play abrasive specialists with technical service density over diversified materials conglomerates facing capital allocation trade-offs. Long-term viability hinges on grain chemistry control and regulatory compliance solution bundling. The signal to watch is CARB protocol prefiguration of federal volatile organic compound standards, which will compress qualification timelines for first-mover suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Alumina Grain Production | Captures margin from engineered grain chemistry specifications by Michigan automotive OEMs. |
| Filtration Technology Licensing Partnership | Monetizes OSHA silica compliance spending across Great Lakes metalworking operations. |
| Aerospace Super Abrasive Expansion | Penetrates Quebec and Ontario turbine blade machining clusters with diamond and CBN solutions. |
| Digital Grinding Parameter Platform Launch | Enables subscription revenue from predictive wear monitoring at high-volume job shops. |
| CARB-First Certification Investment | Accelerates federal qualification timelines for volatile organic compound-compliant coating systems. |
Research Methodology
A standing panel of abrasive plant managers, automotive tier supplier procurement leads, metalworking job shop owners, and distributor technical service directors provided ongoing calibration across primary fieldwork. Secondary validation drew from OSHA enforcement databases, EPA National Emission Standards for Hazardous Air Pollutants filings, United States Geological Survey mineral commodity summaries, and automotive OEM supplier quality manuals. Bottom-up segment sizing triangulated against top-down industry association aggregates.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with CAGRs derived from segment-level growth rate synthesis. Modeled dimensions span product type, application, end user, and distribution channel, with regional regulatory stringency and reshoring capital investment velocity as industry-specific forecast inputs.
Sensitivities concentrate around OSHA silica rulemaking evolution, energy cost volatility in domestic smelting, and laser cutting substitution rates in thick-section metal fabrication. Cross-checking against United States Geological Survey abrasive mineral consumption benchmarks and automotive production databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Artificial Abrasives Market
Abrasives
RDP Powder Market
Abrasives
Grinding Wheels Market
Abrasives
Fine Sandpaper Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Concrete Densification and Polishing Material Market
Abrasives
Abrasive Tools Market
Abrasives
Glass Abrasives Market
Abrasives
Tungsten Carbide Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Liquid Sandpaper Market
Abrasives
Carbide Tools Market
Abrasives
Chemical Deflasher Market
Abrasives
Sandblaster Market
Abrasives
Vitrified Bonded Grinding Wheels Market