
 Throat Lozenges Market | 2026-2036
Throat Lozenges Market Size, Share, and Industry Trends Forecast 2026-2036
Throat Lozenges Market Analysis
Plant-based extraction and clean-label formulation is tilting manufacturing priorities across the throat lozenges industry. Ricola AG leverages its Swiss alpine herb supply chain to anchor premium positioning in European pharmacies. Haleon plc sustains broad shelf presence through deep distribution partnerships with supermarket chains across North America. Procter & Gamble Company competes on brand recognition and pediatric safety credentials in the medicated segment.
Throat lozenges are compressed or molded solid dosage forms containing demulcents, antiseptics, anesthetics, or herbal extracts that dissolve slowly in the oral cavity to soothe pharyngeal mucosa, typically weighing 2–5 grams with dissolution times of 5–15 minutes depending on base composition. The medicated category dominates pharmacy channel value due to higher price points and clinical endorsement, while sugar-free variants lead growth as diabetic and dental-conscious consumers shift purchasing patterns. Herbal formulations occupy a maturing but defensible niche in European markets where traditional medicine acceptance runs deep.
The FDA's OTC monograph system governs active ingredient limits and labeling claims for medicated lozenges sold in the United States, while the EMA coordinates national regulators like Germany's BfArM to harmonize self-medication standards across European markets. India's CDSCO and FSSAI impose dual oversight on ayurvedic and allopathic throat lozenge classifications, creating compliance complexity for exporters. Stakeholders must monitor evolving botanical substantiation requirements and sugar reduction mandates as these regulatory threads reshape formulation R&D priorities and market access pathways.
Market Dynamics
Pharmacy chains and health-conscious consumers are expanding procurement of sugar-free formulations, while the FDA's OTC monograph reform and EMA's evolving self-medication guidelines tighten active ingredient disclosure requirements across manufacturing footprints.
Growth Catalysts
- Regulatory harmonization:The EMA coordinates national regulators like Germany's BfArM to streamline self-medication standards, reducing compliance fragmentation for cross-border throat lozenge distribution.
- Sugar-free formulation demand:Diabetic and dental-conscious consumers in the United States are shifting purchasing patterns toward non-glycemic alternatives, compressing traditional sucrose-based product cycles.
- Herbal extraction infrastructure:Swiss alpine herb supply chains enable premium positioning in European pharmacies through authenticated botanical sourcing and clean-label substantiation.
Market Restraints
- Active ingredient cost volatility:Menthol and benzocaine supply concentrates in limited chemical manufacturing clusters, exposing formulators to input price swings and qualification delays.
- Dual regulatory friction:India's CDSCO and FSSAI impose overlapping oversight on ayurvedic versus allopathic throat lozenge classifications, complicating export compliance for foreign entrants.
- Substitution by liquid alternatives:Throat sprays and medicated mouthwashes from Haleon plc and similar manufacturers capture symptomatic relief occasions with faster onset claims.
Strategic Opportunities
- Pediatric safety credentialing:Choking-resistant geometries and child-proof packaging innovations open pharmacy shelf space in Germany where parental purchase criteria prioritize safety engineering.
- Direct-to-consumer channel expansion:Subscription models for seasonal lozenge packs bypass traditional wholesale markups, capturing recurring revenue from urban United States households with chronic throat irritation patterns.
- Botanical substantiation mandates:The EU Green Deal's clean-label incentives reward manufacturers with verified alpine herb traceability, creating margin premiums for compliant Swiss and Austrian supply networks.
Industry Challenges
- Formulation scientist scarcity:The convergence of pharmaceutical compliance and food-grade manufacturing expertise creates recruitment bottlenecks in quality assurance and regulatory affairs functions.
- Dissolution standardization delays:Inconsistent pharmacopeial methods across the United States Pharmacopeia and European Pharmacopoeia prolong equivalence testing timelines for multi-territory launches.
- Legacy equipment retrofit costs:Compressor and molding lines require capital-intensive upgrades to handle sugar-free base matrices with altered flow properties and compression characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Throat Lozenges Market |
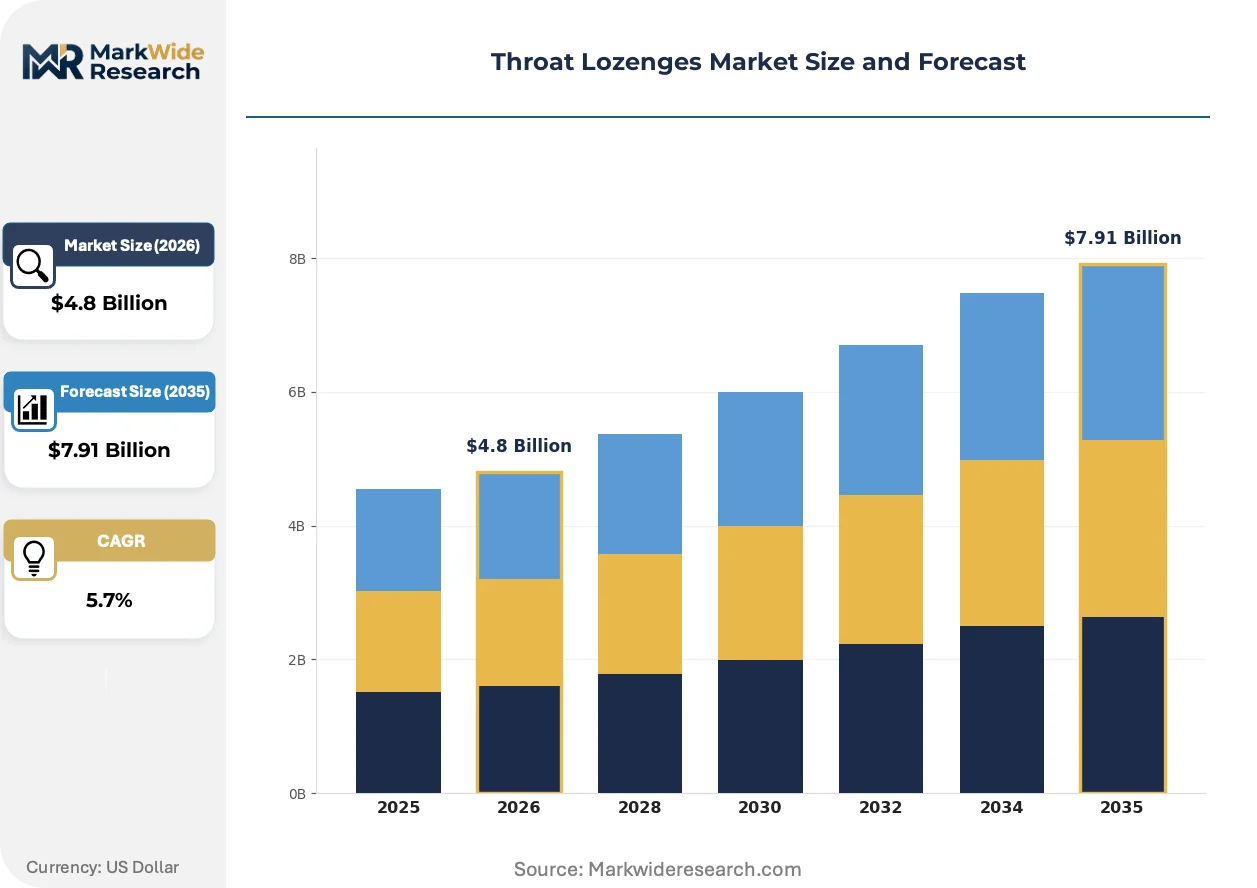
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Sugar-Free, Medicated, Non-Medicated Distribution Channel: Online, Pharmacies, Supermarkets, Convenience Stores End User: Adults, Children, Geriatric, Athletes Flavor: Honey, Lemon, Mint, Cherry |
| Companies Covered | Pfizer Inc., Ricola AG, Reckitt Benckiser Group plc, Bliss GVS Pharma Ltd, Mondelēz International, Inc., Haleon plc, Procter & Gamble Company, Sanofi SA, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Throat Lozenges Market Emerging Trajectories
Clean-label substantiation and extraction transparency are reshaping how throat lozenge manufacturers communicate efficacy, compressing the gap between traditional herbal positioning and pharmaceutical-grade clinical validation.
Plant-based extraction methods are migrating from solvent-based systems to supercritical CO2 and aqueous processes. Premium pharmacy buyers in Germany and Switzerland now demand chromatographic fingerprinting of active botanical constituents. This shift is compressing reliance on undisclosed proprietary blends that previously dominated European herbal lozenge positioning.
REACH and the EU Green Deal are tightening botanical sourcing disclosure requirements for consumer health products. Manufacturers must now document alpine herb cultivation elevations, harvest windows, and drying protocols to maintain CE-marked self-medication status. The medicated herbal segment is responding by consolidating supply partnerships with Swiss and Austrian agricultural cooperatives possessing multi-decade traceability records.
Pharmacy procurement patterns are fragmenting as diabetic consumers bypass sugar-containing SKUs entirely. United States supermarket chains now allocate dedicated planogram space to polyol-based formulations, displacing traditional sucrose products from prime shelf positions. This rotation is most visible in urban markets where dental-conscious millennials represent the dominant household purchase decision-makers for seasonal respiratory care.
Throat Lozenges Market Segmentation
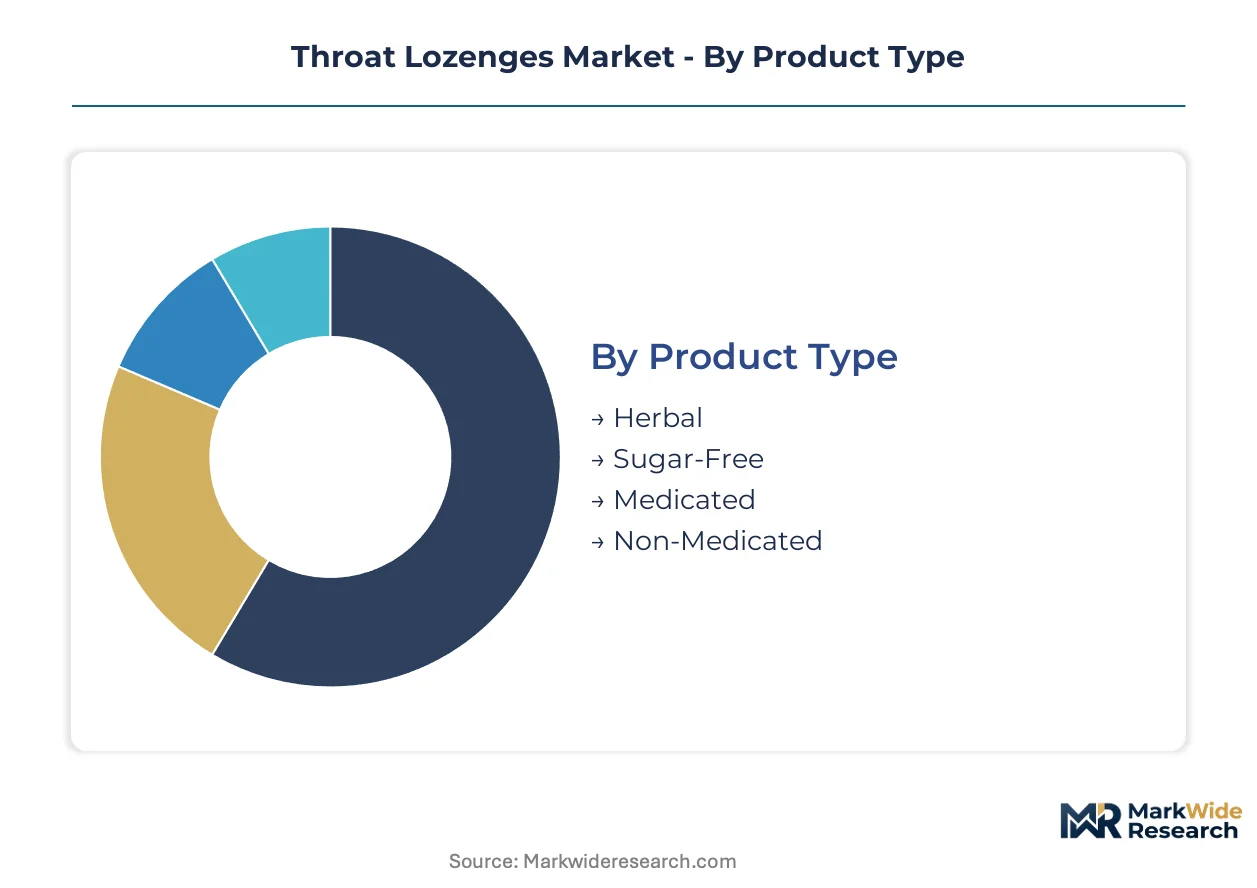
Throat lozenge manufacturers configure production lines and inventory buffers around distinct consumption occasions that span symptomatic relief, preventive care, and lifestyle wellness. Segment-specific formulation requirements create divergent margin profiles and regulatory compliance burdens across the value chain.
Product Type:
After-sales service intensity varies sharply across product types, with medicated variants requiring pharmacovigilance reporting and sugar-free lines demanding stability monitoring through shelf life.
- Medicated:Compressed lozenges containing benzocaine, menthol, or dextromethorphan deliver targeted symptomatic relief with dissolution-controlled release kinetics. Pharmacy procurement in Germany and the United States concentrates here due to clinical endorsement and insurance-adjacent purchasing patterns. The FDA's OTC monograph compliance adds documentation overhead that smaller formulators struggle to absorb.
- Sugar-Free:Polyol-based matrices using sorbitol, xylitol, or isomalt replace sucrose to serve diabetic and dental-conscious consumers. United States supermarket chains now allocate prime planogram space to these variants as millennial households prioritize non-glycemic respiratory care. Formulation complexity rises with hygroscopic base materials requiring moisture-barrier packaging.
- Herbal:Alpine herb extracts from Swiss and Austrian supply chains target European consumers with traditional medicine acceptance. Chromatographic fingerprinting requirements under REACH documentation protocols elevate substantiation costs.
- Non-Medicated:Demulcent-only formulations using pectin or glycerin serve wellness-oriented consumers seeking soothing without pharmacological intervention. Clean-label positioning competes in direct-to-consumer channels.
By volume, medicated leads. By growth pace, sugar-free is ahead.
Distribution Channel:
Cost tier stratification separates pharmacy-premium positioning from mass-market velocity plays, with channel selection directly determining formulation sophistication and margin extraction potential.
- Pharmacies:Brick-and-mortar and digital pharmacy networks command highest price realization through pharmacist recommendation leverage and insurance-adjacent purchasing. Germany's BfArM-regulated self-medication standards create credentialing barriers that filter out commodity suppliers. Cold-chain-adjacent storage requirements for certain botanical extracts add operational complexity.
- Supermarkets:High-velocity shelf rotation in seasonal respiratory aisles demands promotional calendar alignment and slotting fee absorption capacity. United States retail consolidation into Kroger-Albertson footprints concentrates buyer power.
- Online:Direct-to-consumer and marketplace channels enable subscription model experimentation for chronic throat irritation sufferers. Fulfillment economics favor lightweight, stable formulations with extended ambient stability.
- Convenience Stores:Impulse-driven single-serve and travel-pack formats prioritize shelf-ready packaging and extended ambient shelf life over formulation sophistication.
Pharmacies dominate value capture. Online channels are expanding most quickly.
End User:
Application-specific requirements drive divergent safety engineering and dosing specifications, with pediatric and geriatric segments imposing stringent choking-resistance and packaging protocols.
- Adults:The broadest addressable population consumes across all product types and channels, with occupational voice strain and seasonal respiratory patterns driving repeat purchase behavior. Formulation flexibility permits full range of actives and bases.
- Children:Choking-resistant geometries and child-proof packaging innovations open pharmacy shelf space where parental purchase criteria prioritize safety engineering over price. Germany's stringent juvenile product standards exceed baseline EU requirements.
- Geriatric:Xerostomia-compromised populations require modified dissolution profiles and moisture-retentive bases. Polypharmacy interaction concerns elevate pharmacist consultation frequency.
- Athletes:Clean-label, banned-substance-certified formulations serve competitive and recreational participants with anti-doping compliance documentation requirements. Sugar-free positioning aligns with glycemic management protocols.
Adults represent the volume anchor. Athletes show the steepest expansion trajectory.
Flavor:
Maturity gradients separate established flavor profiles with proven acceptance from emerging variants requiring consumer education investment.
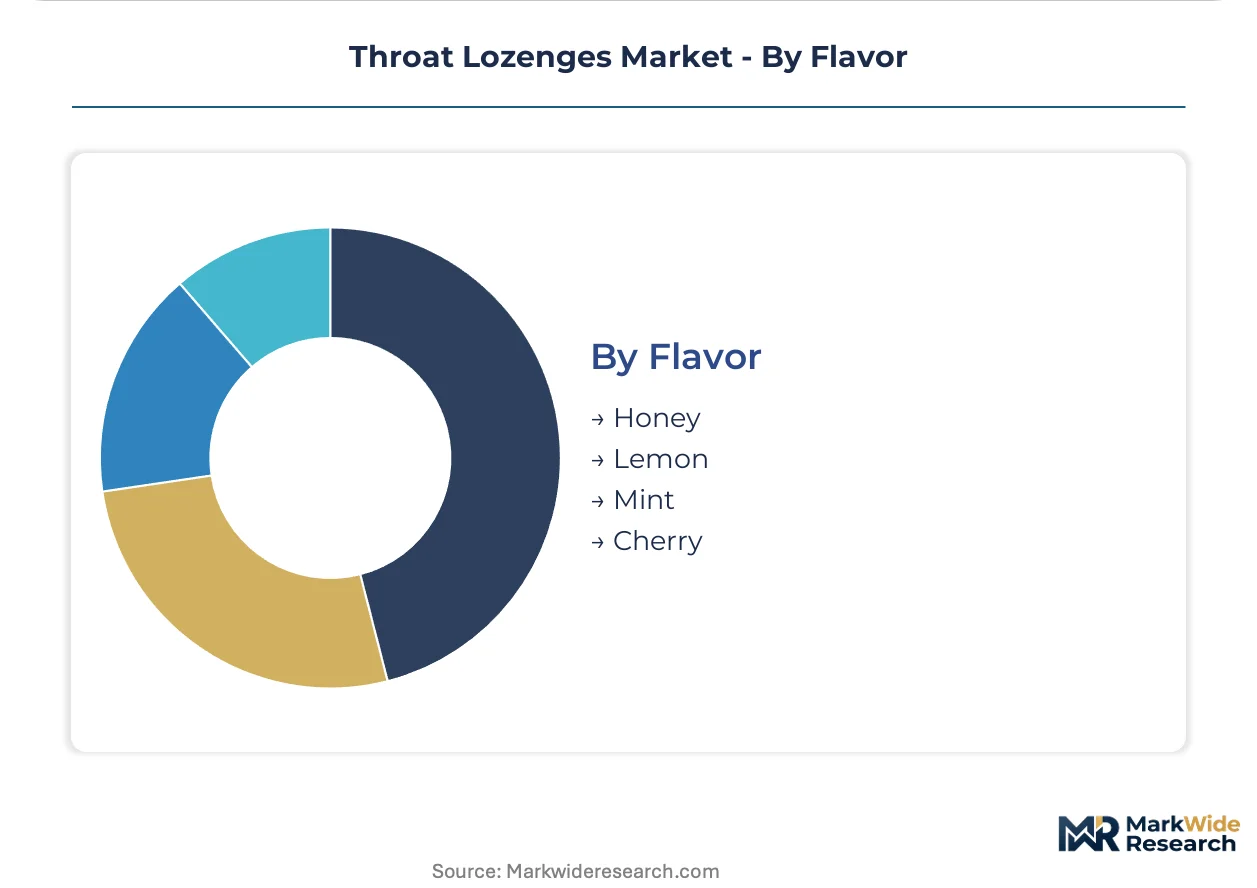
- Mint:Menthol-dominant taste profiles deliver immediate sensory feedback that reinforces efficacy perception across medicated and non-medicated categories. Cooling sensation chemistry permits formulation standardization.
- Honey:Natural positioning resonates with clean-label seekers and traditional remedy adherents, though botanical authentication requirements elevate sourcing costs. Indian ayurvedic formulations leverage domestic apiculture networks.
- Lemon:Citrus acidity masks bitter active ingredients while reinforcing vitamin C association in consumer cognition. Seasonal cold-and-flu alignment drives promotional concentration.
- Cherry:Pediatric preference concentration and cough suppressant taste-masking utility sustain niche positioning despite higher flavor raw material costs.
Mint dominates absolute volume. Honey is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss alpine herb exports supply premium formulation demand across German pharmacies, while Indian ayurvedic manufacturers ship botanical lozenges to Middle Eastern and Southeast Asian markets. United States-based formulators source menthol actives from domestic chemical clusters to serve pharmacy and supermarket channels.
United States
Diabetic consumers and dental-conscious millennials drive sugar-free procurement through Kroger-Albertson retail footprints and CVS-Walgreens pharmacy networks. The FDA's OTC monograph reform tightens benzocaine and menthol labeling claims, forcing documentation upgrades across manufacturing footprints. New Jersey and North Carolina chemical corridors concentrate active ingredient production for lozenge formulators.
Germany
Self-medication culture and pharmacist recommendation power sustain premium medicated lozenge velocity in Apotheke channels. The BfArM coordinates with EMA to harmonize botanical substantiation requirements for herbal throat lozenges under evolving self-medication guidelines. Bavaria's alpine-adjacent regions host extraction facilities serving Swiss and Austrian herb supply networks.
India
Ayurvedic remedy adherence and expanding pharmacy retail chains drive dual-format demand for allopathic and traditional throat lozenges. CDSCO and FSSAI impose overlapping classification oversight, complicating export compliance for foreign entrants targeting Indian consumers. Maharashtra's Mumbai-Pune industrial corridor concentrates contract manufacturing for domestic and export lozenge production.
Switzerland
Authenticated botanical sourcing and clean-label positioning command pharmacy price premiums across European markets. Swissmedic maintains stringent self-medication standards that filter out commodity suppliers lacking traceability documentation. Alpine agricultural cooperatives in Graubünden and Valais supply cultivated herb raw materials to extraction facilities.
United Kingdom
Supermarket pharmacy consolidation and Boots-Walgreens Alliance retail presence shape mass-market lozenge distribution patterns. The MHRA aligns with EMA post-Brexit transition protocols for OTC product registration and labeling compliance. Greater London and Manchester distribution hubs handle import logistics for European-manufactured lozenge formulations.
Throat Lozenges Market Vendor Landscape
Channel-controlling players compete with product-specialist players across pharmacy, supermarket, and direct-to-consumer routes. The vendor base spans multinational consumer health conglomerates with deep distribution partnerships and mid-cap herbal specialists with authenticated supply chains. Three archetypes dominate: alpine-heritage botanical brands, broad-portfolio consumer health giants, and private-label contract manufacturers. Competitive moves concentrate on portfolio diversification into sugar-free matrices and geographic expansion through regulatory harmonization.
Within the alpine-heritage tier, Ricola AG exemplifies authenticated botanical positioning through Swiss agricultural cooperative partnerships. Haleon plc and Procter & Gamble Company occupy scale-driven positions across North American pharmacy and supermarket channels. These three entities represent distinct competitive vectors: heritage sourcing credibility, distribution depth, and pediatric safety credentialing.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Ricola AG |
| Reckitt Benckiser Group plc |
| Bliss GVS Pharma Ltd |
| Mondelēz International, Inc. |
| Haleon plc |
| Procter & Gamble Company |
| Sanofi SA |
| GlaxoSmithKline plc |
| Others |
Supply Flow & Price Mechanics
New Jersey's chemical manufacturing corridor concentrates menthol and benzocaine production capacity, anchoring cost structures for North American lozenge formulators while Swiss alpine herb networks command premium positioning in European pharmacy channels through authenticated botanical sourcing.
Pricing Analysis
Current-generation sugar-free polyol formulations command 15-30% price premiums over prior-generation sucrose-based matrices, while next-generation chromatographically-fingerprinted herbal extracts target ultra-premium pharmacy tiers. Three-tier pricing structure across premium, standard, and economy levels separates authenticated Swiss herb lozenges from mass-market medicated variants and private-label contract offerings. Pricing pressure stems from Kroger-Albertson retail consolidation and slotting fee absorption demands in United States supermarket channels. Dental-conscious millennials exhibit lowest price sensitivity for sugar-free positioning, while convenience store impulse buyers drive economy-tier velocity.
Supply Chain Analysis
Contract manufacturing concentrates among Maharashtra's Mumbai-Pune industrial corridor facilities, Swiss extraction specialists in Graubünden, and North Carolina pharmaceutical packaging operations. Active ingredient sourcing draws from domestic United States chemical clusters for menthol, Austrian alpine cooperatives for botanical raw materials, and Indian apiculture networks for honey-based formulations. Single-source vulnerability concentrates in Swiss herb supply chains where multi-decade agricultural partnerships resist rapid scaling. Distribution runs through pharmacy wholesale networks in Germany, retail consolidation platforms in the United States, and direct-to-consumer fulfillment centers serving subscription model subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label substantiation mandates and sugar-reduction regulatory pressure are disrupting formulation economics faster than legacy manufacturers can retrofit production infrastructure, compressing competitive timelines for compliance-capable entrants.
For Market Incumbents: Insulate pharmacy channel positioning through backward integration into authenticated herb supply partnerships in Swiss and Austrian alpine regions, while accelerating compressor line upgrades to handle hygroscopic polyol base matrices. Haleon plc and similar broad-portfolio players face margin compression from direct-to-consumer subscription competitors bypassing traditional wholesale markups. For New Entrants and Emerging Players: India's underpenetrated ayurvedic-allopathic dual format market offers white-space expansion through CDSCO-FSSAI compliance specialization, while Germany's pediatric safety-credentialed pharmacy tier rewards choking-resistant geometry innovations. Target direct-to-consumer subscription models for chronic throat irritation sufferers in urban United States households, leveraging lightweight stable formulations with extended ambient shelf life for fulfillment economics advantage. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because botanical substantiation mandates and OTC monograph reforms are filtering out commodity suppliers incapable of documentation overhead absorption. Acquisition targets should display Swiss or Austrian agricultural cooperative partnerships with multi-decade traceability records, or polyol formulation expertise with moisture-barrier packaging integration. Monitor FDA OTC monograph reform implementation timelines and EU Green Deal clean-label incentive program rollouts as inflection indicators for margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sugar-Free Formulation Scale-Up | Polyol matrix production expansion captures diabetic and dental-conscious consumer procurement shifts in United States retail channels. |
| Alpine Herb Supply Partnership | Authenticated botanical sourcing with chromatographic fingerprinting secures pharmacy price premiums under REACH documentation protocols. |
| Direct-to-Consumer Channel Launch | Subscription models bypass Kroger-Albertson wholesale markups while capturing recurring revenue from chronic irritation sufferers. |
| Pediatric Safety Certification Investment | Choking-resistant geometries and child-proof packaging open Germany's BfArM-regulated Apotheke shelf space against parental purchase criteria. |
| Regulatory Harmonization Compliance | FDA OTC monograph and EMA self-medication guideline alignment reduces multi-territory launch friction for medicated variants. |
Methodological Framework
A spread of perspectives from brand managers at consumer health conglomerates, category buyers at United States supermarket chains, pharmacy procurement directors in Germany, regulatory affairs specialists navigating CDSCO-FSSAI dual oversight, and Swiss alpine herb agricultural cooperative representatives converged on the working assumptions underlying demand projections. Primary interview insights were validated against FDA OTC monograph filings, EMA self-medication guideline documentation, Indian customs export records for ayurvedic lozenges, Nielsen retail audit data from seasonal respiratory aisles, and SEC 10-K disclosures from listed consumer health entities. Bottom-up volume builds across product type, distribution channel, and end-user segments were triangulated against top-down market sizing from trade association aggregates.
Demand-supply-balance dynamics across the analysis window were modeled through segmented elasticity functions capturing diabetic consumer switching behavior, pharmacy recommendation influence coefficients, and seasonal respiratory incidence patterns. Segmentation dimensions included medicated versus non-medicated classification, sugar-free versus traditional sucrose base matrices, pharmacy versus supermarket versus online channel routing, and adult versus pediatric versus geriatric end-user safety requirements. CAGRs were derived from regression-adjusted trend extrapolation incorporating regulatory timeline assumptions and raw material cost trajectory scenarios specific to menthol, benzocaine, and alpine herb input markets.
Practitioners should monitor FDA OTC monograph reform implementation pace, EU Green Deal botanical substantiation mandate enforcement intensity, and Indian dual-regulatory classification clarification timelines for early signals of forecast revision necessity. Quarterly review of Swiss herb harvest yield reports, United States polyol commodity price indices, and pharmacy chain private-label expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
South America Dietary Supplement Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Aquatic Feed Supplement Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Nutrition Therapy Market