
 France Flexible Plastic Packaging Market | 2026-2036
France Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Flexible Plastic Packaging Market Insights
CE marking under the EU Packaging and Packaging Waste Directive is redrawing competitive access in the French flexible plastic packaging sector. Amcor Plc leverages its European film manufacturing footprint to sustain compliance leadership across recycled content thresholds. Berry Global anchors its position through vertical control over blown film extrusion for healthcare-grade pouches. Constantia Flexibles specializes in pharmaceutical barrier laminates, navigating France's stringent ANSM material safety protocols.
Flexible plastic packaging denotes polymer-based materials—typically polyethylene, polypropylene, or multi-layer laminates below 250 microns—that conform to product geometry through heat-sealing, forming, or shrinking, primarily serving shelf-life extension and logistics efficiency in consumer goods distribution. Polyethylene films dominate volume throughput for fresh produce and bakery applications, while laminated pouches capture margin concentration in retort-ready meals and pharmaceutical sachets where oxygen transmission rates below 0.1 cc/m²/day command price premiums. Shrink sleeves represent the fastest-expanding format among beverage multipacks, displacing corrugated secondary packaging in French supermarket distribution.
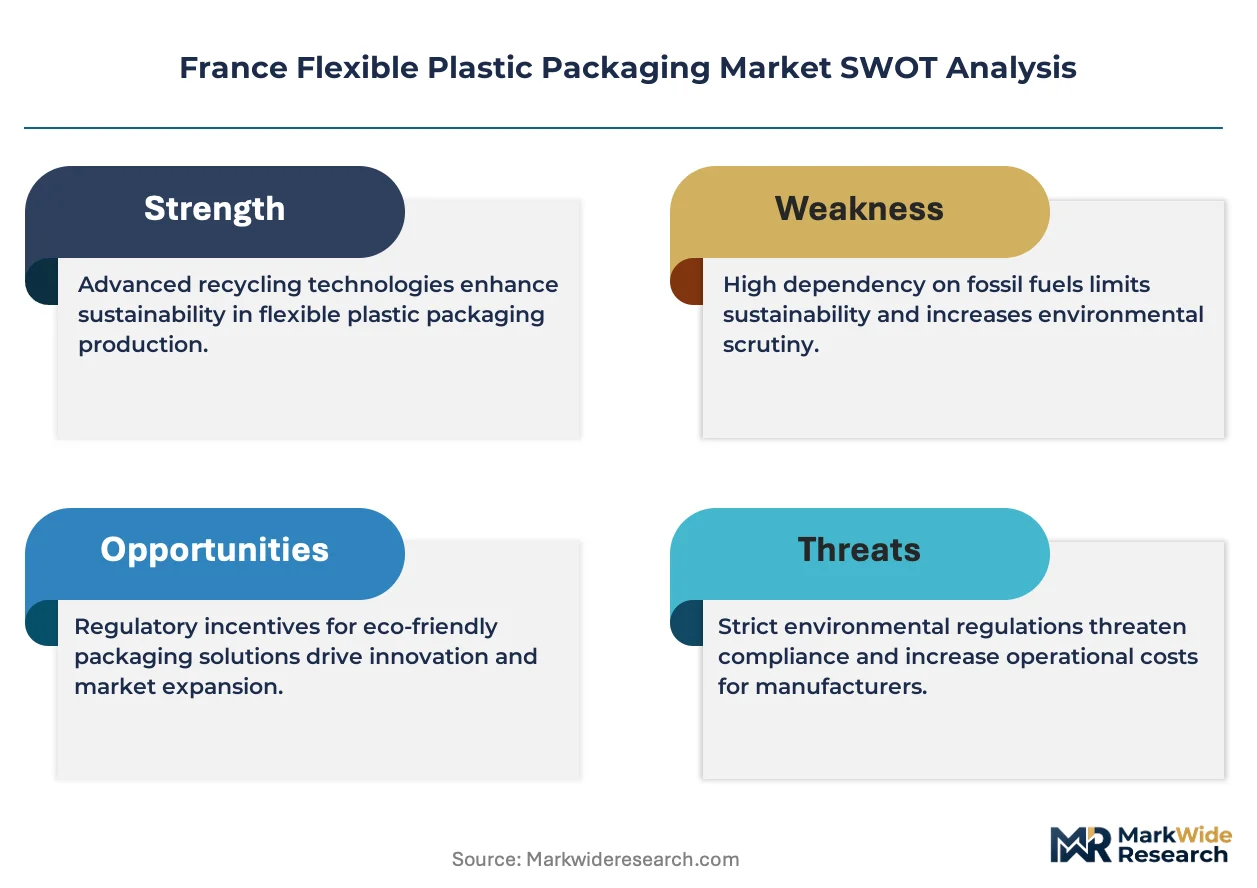
France's anti-waste law for a circular economy (AGEC) and the EU Green Deal mandate 30% recycled content in plastic packaging, compelling converters to redesign multi-layer structures or forfeit market access. ANSM oversight of pharmaceutical contact materials adds a parallel compliance layer that favors established players with documented migration testing. Stakeholders must monitor whether mechanical recycling infrastructure investments in Normandy and the Grand Est region keep pace with regulatory timelines, or whether chemical recycling partnerships become the viable compliance pathway for complex laminates.
Market Dynamics
The EU Green Deal and France's AGEC law are forcing converters to redesign multi-layer films for mechanical recyclability, collapsing legacy barrier structures that relied on incompatible polymer combinations. This regulatory compression is restructuring supplier relationships and capital allocation across the Île-de-France packaging cluster.
Growth Catalysts
- Retailer sustainability mandates:Carrefour and E.Leclerc now require 30% recycled content in private-label packaging, pulling mono-material polyethylene films into fresh produce and bakery applications.
- ANSM pharmaceutical protocols:France's national drug safety agency maintains stringent migration testing standards that favor domestic converters with documented compliance histories, insulating certified suppliers from price-based competition.
- Normandy mechanical recycling infrastructure:New sorting and reprocessing capacity in the Grand Est region is reducing transport costs for post-industrial film scrap, improving recycled resin economics for converters serving Paris logistics corridors.
Market Restraints
- Ethylene feedstock volatility:Naphtha-linked polyethylene resin costs swing with European refinery utilization rates, compressing converter margins when oil benchmarks spike above threshold levels.
- Blown film equipment concentration:German and Austrian extrusion machinery suppliers control 70% of installed capacity in France, creating capex bottlenecks and extended lead times for domestic expansion projects.
- Aluminum foil substitution in high-barrier segments:Metallized films and vacuum-deposited oxide coatings are losing share to thinner aluminum laminates in pharmaceutical sachets where absolute oxygen barrier performance dominates specification.
Strategic Opportunities
- Chemical recycling partnerships:Pyrolysis-based feedstock recovery offers a compliance pathway for complex multi-layer structures that mechanical sorting cannot process, with pilot investments emerging in the Port of Le Havre industrial zone.
- Shrink sleeve beverage multipacks:Format conversion from corrugated secondary packaging to printed PETG sleeves is accelerating in French supermarket distribution, creating demand for high-definition gravure and digital printing capacity.
- Healthcare-grade pouch expansion:Sterile barrier requirements for single-use medical devices are pulling fluoropolymer-coated films into new applications beyond traditional pharmaceutical sachets.
Industry Challenges
- Migration testing backlog:ANSM certification queues for new laminate structures now extend 14-18 months, delaying product launches for converters without established regulatory dossiers.
- Legacy extrusion line retrofit costs:Converting mono-material production to handle 30% recycled content requires screw and die modifications that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Flexible Plastic Packaging Market |
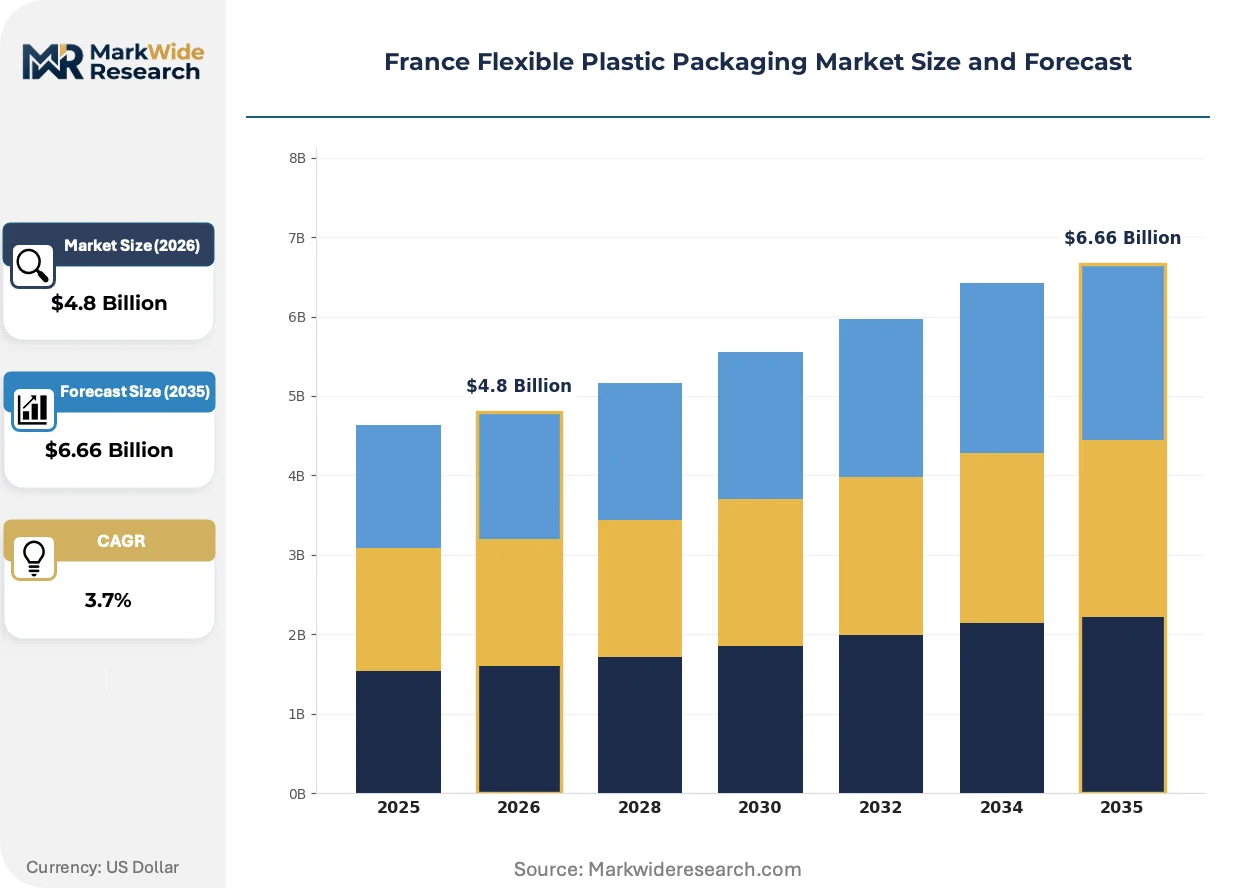
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Films, Polypropylene Bags, Laminated Pouches, Shrink Sleeves Application: Food Packaging, Beverage Packaging, Healthcare Packaging, Personal Care Packaging End User: FMCG, Pharmaceuticals, Cosmetics, Electronics Distribution Channel: Online Retail, Supermarkets, Specialized Stores, Direct Sales |
| Companies Covered | Amcor Plc, Constantia Flexibles, Berry Global, Mondi Plc, Sealed Air, Sonoco Products, Coveris, Industrial Packaging Solutions, Colly and Martin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Flexible Plastic Packaging Market Trends and Innovations
Digital printing and mono-material barrier engineering are converging to collapse traditional gravure-dominated production cycles while meeting AGEC recyclability mandates. These shifts are compressing minimum order quantities and accelerating format proliferation.
Mono-material polyethylene barrier films with plasma-deposited silicon oxide coatings are decomposing the historical trade-off between oxygen transmission performance and mechanical recyclability. Dairy processors in Brittany and Normandy are adopting these structures for extended-shelf-life milk pouches at commercial scale. The technology is decomposing converter reliance on ethylene vinyl alcohol coextrusion, which previously dominated high-barrier applications but fails AGEC sorting requirements.
France's anti-waste law for a circular economy mandates 30% recycled content thresholds with 2025 enforcement timelines, forcing reformulation of legacy multi-layer structures. Converters without chemical recycling partnerships face exclusion from retailer-approved supplier lists. Pharmaceutical barrier laminates remain partially exempt under ANSM safety protocols, creating a two-tier compliance environment where healthcare applications lag food packaging conversion.
Supermarket private-label buyers now specify recycled content and recyclability credentials as primary selection criteria, displacing historical price-tonnage procurement models. This shift concentrates volume with converters holding Ere certification and documented post-consumer resin supply chains. The Île-de-France dairy and processed food cluster exhibits the most aggressive qualification timelines, with major producers requiring full format conversion by 2026.
France Flexible Plastic Packaging Market Segmentation
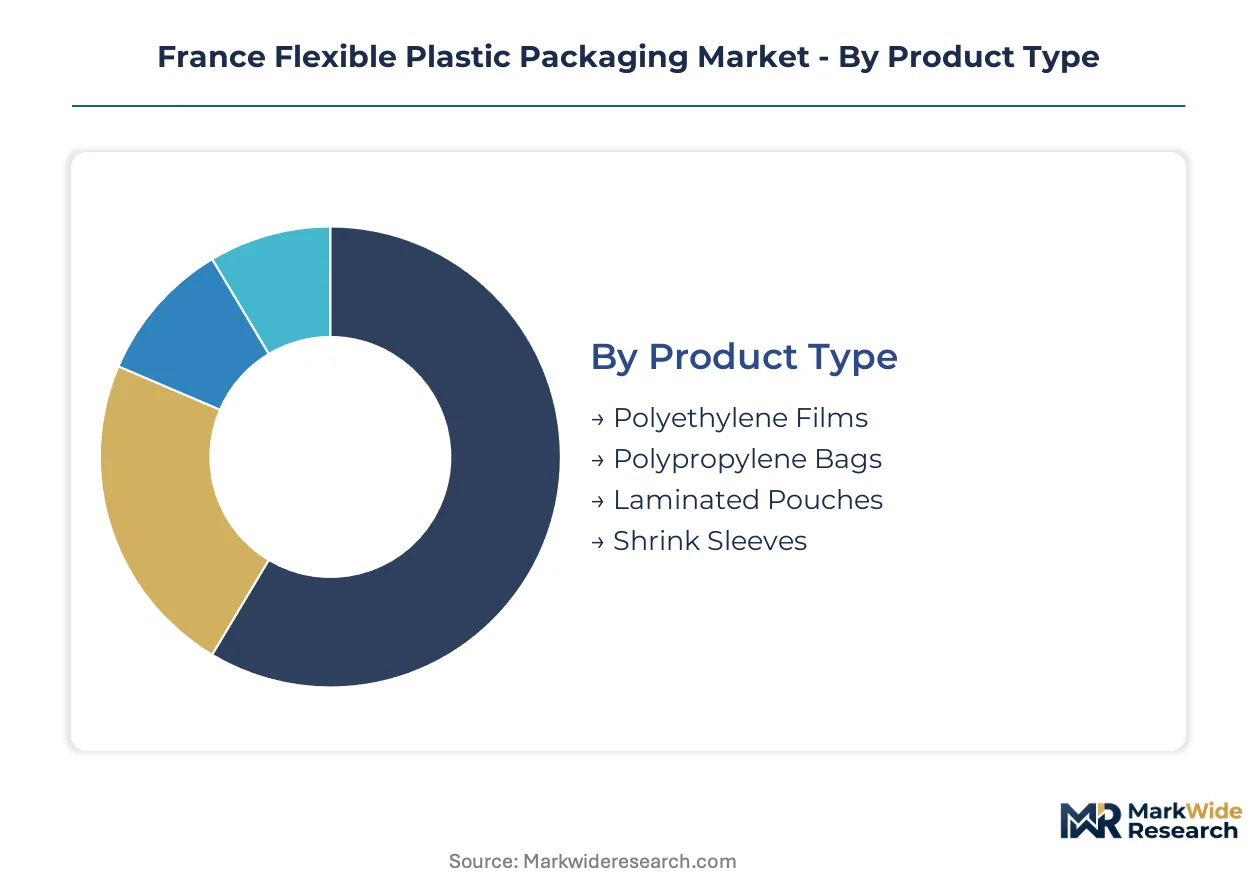
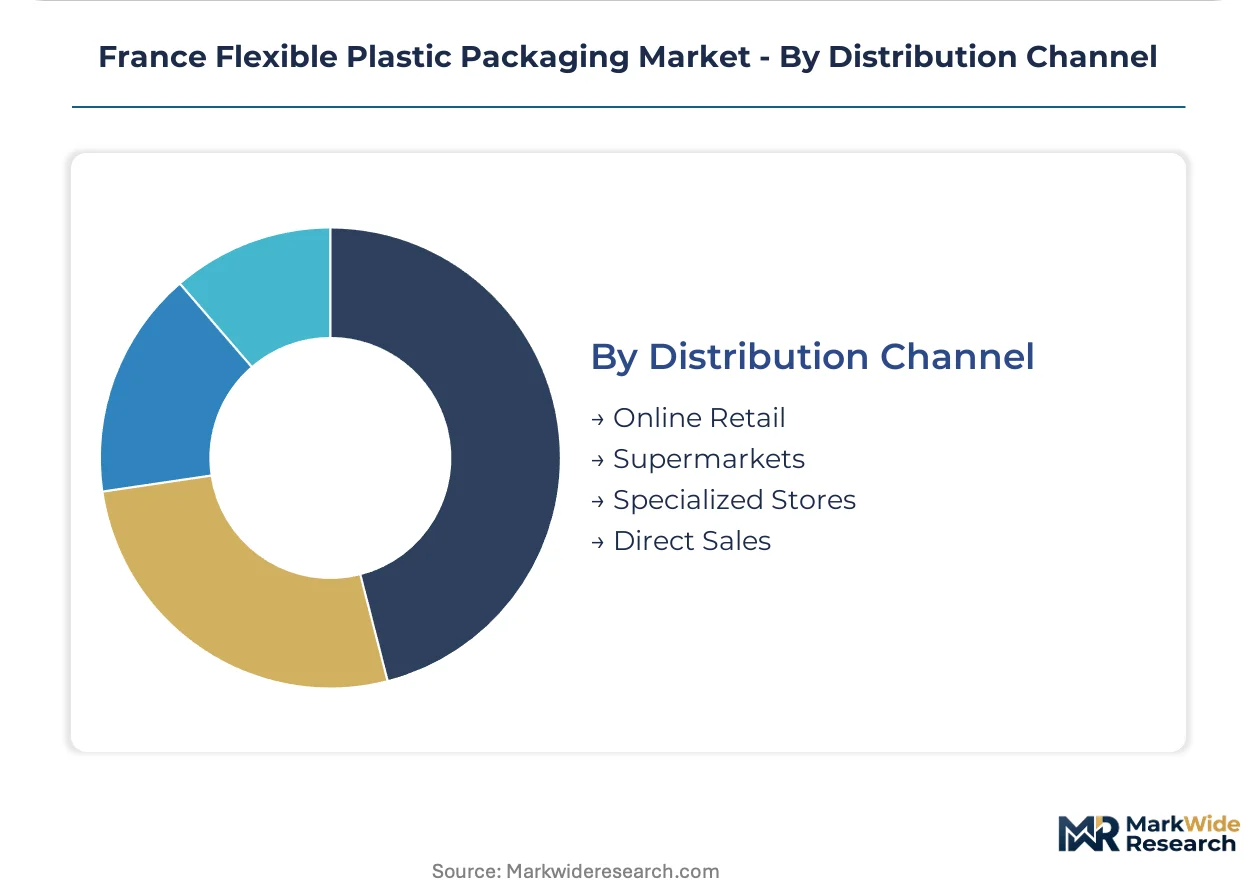
Channel configuration in French flexible packaging diverges sharply by product format. Supermarket private-label mandates and pharmaceutical direct procurement create parallel demand tracks that reshape converter priorities across each segment category.
Product Type:
Channel mix splits between high-volume retail supply and specialized healthcare logistics, with each format optimizing for distinct handling requirements.
- Polyethylene Films:Mono-material LDPE and LLDPE structures dominate fresh produce and bakery applications. Carrefour and E.Leclerc procurement teams now specify 30% recycled content minimums, pulling these films through supermarket distribution channels in Île-de-France.
- Laminated Pouches:Multi-layer barrier structures with aluminum or oxide coatings serve retort-ready meals and pharmaceutical sachets. ANSM migration testing requirements limit qualified suppliers, concentrating demand through direct sales channels to dairy processors and drug manufacturers.
- Polypropylene Bags:Biaxially oriented PP structures handle dry goods and snack foods. These flow primarily through mass retail distribution with shorter specification cycles than healthcare-grade formats.
- Shrink Sleeves:PETG and OPS films displace corrugated secondary packaging for beverage multipacks. Digital printing compatibility accelerates format adoption in supermarket private-label programs.
Polyethylene films dominate installed base. Shrink sleeves are where expansion concentrates.
Application:
Margin structure varies dramatically by end-use, with healthcare applications commanding price premiums that subsidize commodity food packaging investments.
- Food Packaging:AGEC law mandates drive mono-material conversion across dairy, meat, and bakery segments. Brittany and Normandy processors lead adoption of recyclable barrier films for extended-shelf-life applications.
- Healthcare Packaging:Sterile barrier requirements for medical devices and pharmaceutical sachets maintain multi-layer structures despite recyclability pressure. ANSM oversight preserves legacy specifications longer than food applications.
- Beverage Packaging:Shrink sleeve format conversion accelerates in carbonated soft drink and bottled water multipacks. High-definition gravure printing requirements favor converters with in-house prepress capabilities.
- Personal Care Packaging:Stand-up pouches and sachets for cosmetics and toiletries face less regulatory pressure than food or pharma, permitting continued use of decorative multi-layer films.
Food packaging commands volume concentration. Healthcare packaging is where margin protection concentrates.
End User:
Procurement sophistication tiers separate multinational FMCG operators from fragmented cosmetics and electronics assemblers.
- FMCG:Nestlé, Danone, and L'Oréal procurement teams drive sustainability qualification programs. These buyers consolidate volume with converters holding Ere certification and documented post-consumer resin supply chains.
- Pharmaceuticals:Sanofi and Pierre Fabre maintain stringent material safety protocols that favor established domestic converters. Direct sales relationships bypass distributor markups for high-volume sterile barrier applications.
- Cosmetics:L'Oréal and smaller fragrance houses prioritize aesthetic differentiation over recyclability, sustaining demand for metallized and holographic film effects.
- Electronics:Anti-static and moisture-barrier films for component shipping represent a price-sensitive segment with limited sustainability requirements.
FMCG dominates procurement volume. Pharmaceuticals anchor margin stability.
Distribution Channel:
Channel power concentration in French retail reshapes converter customer service investments and inventory positioning.
- Supermarkets:Carrefour, E.Leclerc, and Intermarché private-label mandates now specify recycled content and recyclability credentials as primary selection criteria. These retailers consolidate flexible packaging procurement through approved supplier lists.
- Direct Sales:Pharmaceutical and medical device manufacturers bypass intermediaries for sterile barrier materials. ANSM documentation requirements favor long-term converter relationships over spot purchasing.
- Online Retail:E-commerce fulfillment demands drive demand for lightweight protective films and mailer pouches. Channel growth lags supermarket and direct sales in absolute volume.
- Specialized Stores:Organic food retailers and pharmacy chains require smaller batch sizes with faster format changes, favoring converters with digital printing capabilities.
Supermarkets control volume allocation. Direct sales secure margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's AGEC law and EU Green Deal recyclability mandates are redrawing procurement geography across French sub-regions. Converter capacity and retailer distribution networks are concentrating in logistics corridors serving Paris, Lyon, and Atlantic port zones.
Île-de-France
Carrefour and E.Leclerc headquarters procurement teams mandate 30% recycled content in private-label packaging. ANSM pharmaceutical oversight maintains strict migration testing for sterile barrier materials. The Paris logistics corridor hosts major dairy and processed food producers driving mono-material film adoption.
Auvergne-Rhône-Alpes
Lyon's chemical industry cluster supplies specialty resins for high-barrier pharmaceutical laminates. The EU Packaging and Packaging Waste Directive enforces CE marking compliance across converter operations. Grenoble-based research institutes pilot plasma-deposited silicon oxide coatings for recyclable barrier films.
Brittany
Dairy processors lead adoption of extended-shelf-life milk pouches using mono-material polyethylene structures. France's anti-waste law accelerates format conversion away from ethylene vinyl alcohol coextrusion. Saint-Brieuc and Lorient converters serve cooperative dairy networks with AGEC-compliant packaging.
Normandy
New mechanical recycling infrastructure reduces transport costs for post-industrial film scrap. The Grand Est region's sorting capacity improves recycled resin economics for converters. Le Havre's port industrial zone hosts emerging chemical recycling pilot investments for complex multi-layer structures.
Provence-Alpes-Côte d'Azur
Cosmetics manufacturers in Grasse sustain demand for metallized and holographic decorative films. Less stringent recyclability pressure permits continued multi-layer use in personal care applications. Marseille's port facilitates resin import logistics for regional converter operations.
France Flexible Plastic Packaging Market Competitive Landscape
Player mix skews toward multinational converters with integrated film manufacturing and established regulatory dossiers. Three archetypes dominate: diversified packaging conglomerates with European extrusion footprints, healthcare-specialized laminators with ANSM certification histories, and regional mid-caps serving supermarket private-label programs. Competitive moves center on chemical recycling partnerships for complex laminate compliance and digital printing capacity additions for shrink sleeve format conversion.
Among diversified packaging conglomerates, Amcor Plc and Berry Global exemplify scale-driven archetypes with broad European manufacturing presence. Constantia Flexibles occupies a specialized position within pharmaceutical barrier laminates, anchoring the healthcare-grade tier where ANSM documentation requirements limit qualified supplier pools. These three entities represent distinct competitive vectors: extrusion scale, vertical film control, and regulatory-specialized barrier engineering.
| Leading Market Players |
|---|
| Amcor Plc |
| Constantia Flexibles |
| Berry Global |
| Mondi Plc |
| Sealed Air |
| Sonoco Products |
| Coveris |
| Industrial Packaging Solutions |
| Colly and Martin |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Packaging and Packaging Waste Directive gates both supplier qualification and price differentiation in French flexible plastic packaging. Certification tier separates converters who command premium positioning from commodity suppliers locked in volume-based competition.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ANSM pharmaceutical-grade status, Ere recyclability certification, and generic industrial film grades. Price differentiation hinges on documented migration testing histories and post-consumer resin supply chain verification. Cost compression in standard-grade polyethylene films is intensifying because retailer recycled-content mandates force converters to absorb resin reformulation expenses. Supermarket private-label buyers exhibit highest price sensitivity, while pharmaceutical direct purchasers prioritize compliance documentation over unit cost.
Supply Chain Analysis
Inventory positioning and lead-time management dominate converter operational priorities. Raw material supply concentrates in Germany, Belgium, and the Netherlands for specialty resins and extrusion equipment. The sector draws from naphtha-linked polyethylene feedstocks, aluminum foil laminates, and silicon oxide coating precursors. Single-source vulnerability runs through German and Austrian blown film machinery suppliers controlling seventy percent of installed French capacity. Distribution runs through approved supplier lists maintained by Carrefour and E.Leclerc procurement teams, with direct sales channels serving pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's flexible plastic packaging sector faces high-growth disruption as AGEC law mandates and EU Green Deal recyclability thresholds force structural conversion of legacy multi-layer films.
For Market Incumbents: Fortify market position through backward integration into mechanical recycling infrastructure in Normandy and Grand Est regions. Secure chemical recycling partnerships at Port of Le Havre to process complex laminates that mechanical sorting cannot handle. Prioritize ANSM certification dossier maintenance to preserve pharmaceutical barrier laminate margins against emerging competitors lacking migration testing histories. For New Entrants and Emerging Players: Differentiate on digital printing capabilities for shrink sleeve beverage multipacks where format conversion accelerates. Target cosmetics and personal care segments where decorative multi-layer films face less regulatory pressure than food or pharmaceutical applications. Pursue specialized store channels requiring smaller batch sizes and faster format changes than supermarket private-label programs permit. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap converters holding Ere certification and established post-consumer resin supply chains. Long-term viability centers on chemical recycling infrastructure access and ANSM regulatory dossier depth. Watch for mechanical recycling capacity utilization rates as the inflection signal determining whether complex laminates achieve compliance through chemical or mechanical pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis-based feedstock recovery enables AGEC compliance for multi-layer pharmaceutical laminates. |
| Digital Printing Capacity Addition | High-definition gravure and digital systems capture shrink sleeve format conversion in beverage multipacks. |
| ANSM Certification Investment | Documented migration testing histories preserve access to sterile barrier medical device applications. |
| Backward Integration into Recycling | In-house post-industrial scrap reprocessing reduces resin cost volatility for polyethylene film production. |
| Mono-Material Barrier Engineering | Plasma-deposited silicon oxide coatings decompose historical trade-offs between oxygen barrier and recyclability. |
Research Methodology
Desk research of EU regulatory filings, ANSM documentation databases, and French customs trade data preceded structured interviews with converter operations managers, supermarket procurement leads, pharmaceutical packaging engineers, and blown film machinery distributors. Primary fieldwork with dairy processors in Brittany and Normandy validated secondary estimates of mono-material adoption timelines. Bottom-up volume triangulation across product format categories was cross-checked against top-down value estimates derived from resin consumption patterns.
Variance decomposition across product type, application, end user, and distribution channel dimensions informed the analytical framework. CAGRs were derived from segmented growth rate assumptions applied across the projection horizon. Industry-specific forecast inputs included retailer recycled-content mandate compliance timelines and mechanical recycling infrastructure capacity buildouts in Normandy and Grand Est regions.
Decision-makers should treat outputs as directional under base assumptions of AGEC law enforcement timelines and mechanical recycling capacity expansion; material deviation in chemical recycling cost curves or naphtha price volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
China Flexible Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
Hygiene Breathable Films Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Converted Flexible Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Flexible Paper for Food & Beverages Packaging Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
Flexible Film Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
ASEAN Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Confectionery Flexible Packaging Market