
 UK Flexible Plastic Packaging Market | 2026-2036
UK Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
UK Flexible Plastic Packaging Market Insights
The UK Plastic Packaging Tax is pivoting investment toward recycled-content infrastructure and compliance systems. Berry Global leverages vertical integration across film extrusion and converting to manage input cost volatility. Mondi PLC anchors its position through specialty kraft-plastic hybrid solutions that navigate recyclability mandates. Amcor PLC sustains R&D intensity in mono-material flexible structures that simplify post-consumer sorting streams.
UK flexible plastic packaging comprises polymer-based films, laminates, and formed substrates—typically 10–250 microns thick—engineered for barrier protection, shelf-life extension, and logistical efficiency across supply chains. Polyethylene dominates material tonnage due to cost-performance balance in food-contact applications, while pouches within product forms capture margin pools through premium ready-meal and pet-food conversions. Food Packaging anchors application volume, though Healthcare Packaging differentiates via sterilization-grade barrier specifications and regulatory validation requirements.
HM Revenue & Customs administers the Plastic Packaging Tax, while the Environment Agency enforces extended producer responsibility frameworks that reshape cost allocation across value chains. BSI standards for recycled content verification and DEFRA's packaging waste regulations collectively elevate compliance expenditure for importers and domestic converters. Stakeholders must monitor forthcoming modulated fee structures under the UK EPR scheme to calibrate portfolio exposure between virgin-dependent and circular-ready product lines.
Market Dynamics
The UK Plastic Packaging Tax is compressing virgin polymer demand while forcing converters to reconfigure supply chains around recycled-content verification systems. This fiscal mechanism now functions as the primary market architect, redistributing margin pools toward circular-ready infrastructure and away from legacy linear models.
Growth Catalysts
- DEFRA's packaging waste regulations:Extended producer responsibility frameworks are accelerating capital deployment into domestic recycling infrastructure. Brand owners face escalating compliance costs that favor flexible formats with demonstrable recyclability pathways.
- Pouch-based ready-meal conversions:Food manufacturers are migrating shelf-stable proteins and prepared vegetables from rigid trays to high-barrier laminates. This format shift reduces transport cube and refrigeration intensity across retail distribution networks.
- Midlands packaging corridor concentration:England's central belt hosts clustered film extrusion, printing, and converting capabilities that minimize logistics friction between raw material intake and finished goods dispatch.
Market Restraints
- Post-consumer recycled polyethylene flake scarcity:UK mechanical recycling capacity lags tax-threshold demand, forcing converters to import certified material at volatile premiums.
- Multilayer laminate incompatibility with existing sortation:Current near-infrared detection systems cannot discriminate complex barrier films, consigning substantial tonnage to energy recovery rather than closed-loop processing.
- Natural gas feedstock exposure:Domestic polymer production remains tethered to North Sea and continental pipeline supply, transmitting energy cost shocks directly into resin pricing.
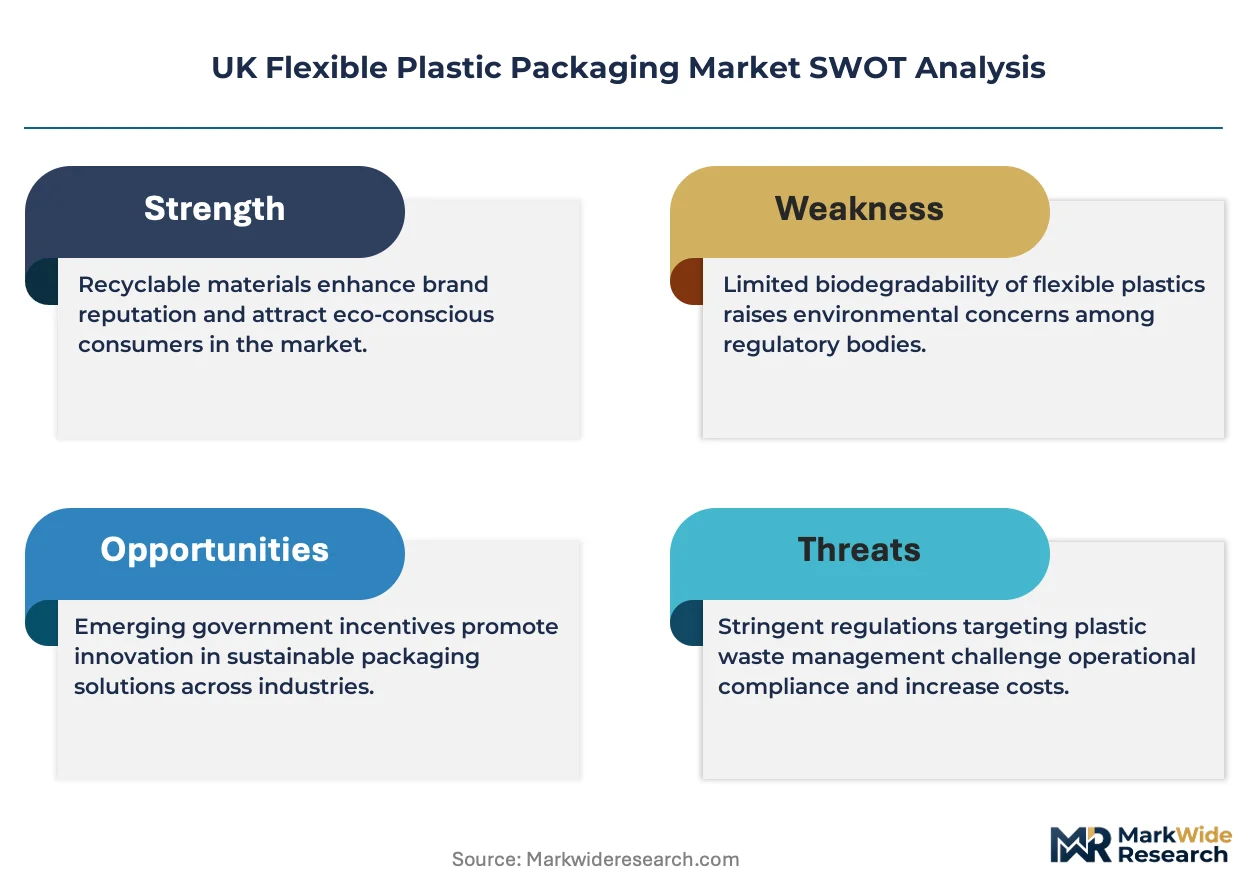
Strategic Opportunities
- Mono-material polyethylene pouches for pet-food:High-margin premium segments are adopting simplified polymer structures that satisfy retailer recyclability pledges without sacrificing oxygen barrier performance.
- Healthcare sterilization-grade barriers:Regulatory validation requirements create defensive moats for converters capable of ISO 13485-certified cleanroom production of pharmaceutical and medical device packaging.
- Digital watermark integration:HolyGrail 2.0 pilot deployments in UK supermarkets are demonstrating automated sortation of flexible packaging via embedded machine-readable markers.
Industry Challenges
- Recycled-content mass-balance certification:BSI PAS 2050 and ISO 14021 verification protocols demand specialized audit capabilities that smaller converters struggle to resource internally.
- Legacy gravure print line retrofitting:Water-based ink transitions for food-contact compliance require substantial drying system modifications and extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Flexible Plastic Packaging Market |
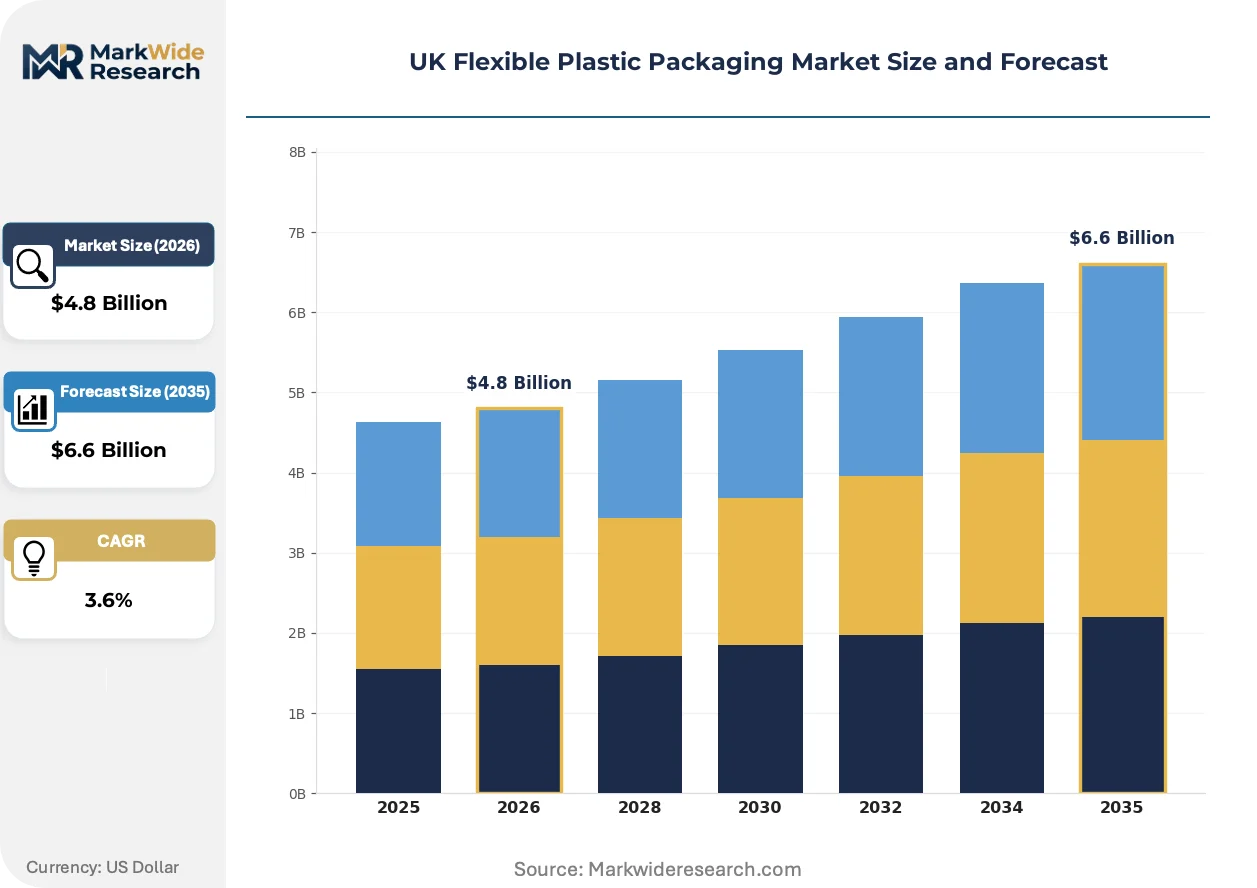
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.6 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polyester Application: Food Packaging, Healthcare Packaging, Personal Care Packaging, Industrial Packaging Product Form: Bags, Pouches, Films, Wraps End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products |
| Companies Covered | Berry Global, Sirane Limited, Amcor PLC, Surepak Innovative Packaging Solutions, Constantia Flexibles, Tyler Innovative Packaging, PB Polybags Co. UK, ALPA Group, Mondi PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Flexible Plastic Packaging Market Trends and Innovations
Material science advances and fiscal policy are converging to restructure competitive advantage around circularity credentials rather than scale economics alone. The market is witnessing accelerated substitution of complex laminates with sortation-compatible alternatives.
Mono-material polyethylene structures are absorbing functionality previously delivered by aluminum oxide or ethylene vinyl alcohol barrier layers. Major retailers are mandating these formats for private-label ready-meals, compressing development cycles from eighteen months to under nine. The technology is absorbing capital from multilayer legacy assets as converters bet on simplified polymer streams.
HM Revenue & Customs' Plastic Packaging Tax enforcement is tightening documentation requirements for imported packaging components. Domestic converters are responding by captive sourcing of certified recycled flake and vertical integration into compounding operations. Healthcare and food-contact segments face the steepest compliance cost escalations due to stringent migration testing protocols.
Retailer consolidation is compressing supplier negotiation leverage across the UK grocery channel. Buying desks at Tesco, Sainsbury's, and Morrisons are unbundling packaging procurement from finished goods contracts, forcing converters to bid directly against Asian imports on specification-driven tenders. This disintermediation is most visible in ambient sauce and condiment pouches, where price transparency has eroded traditional relationship-based contracting.
UK Flexible Plastic Packaging Market Segmentation
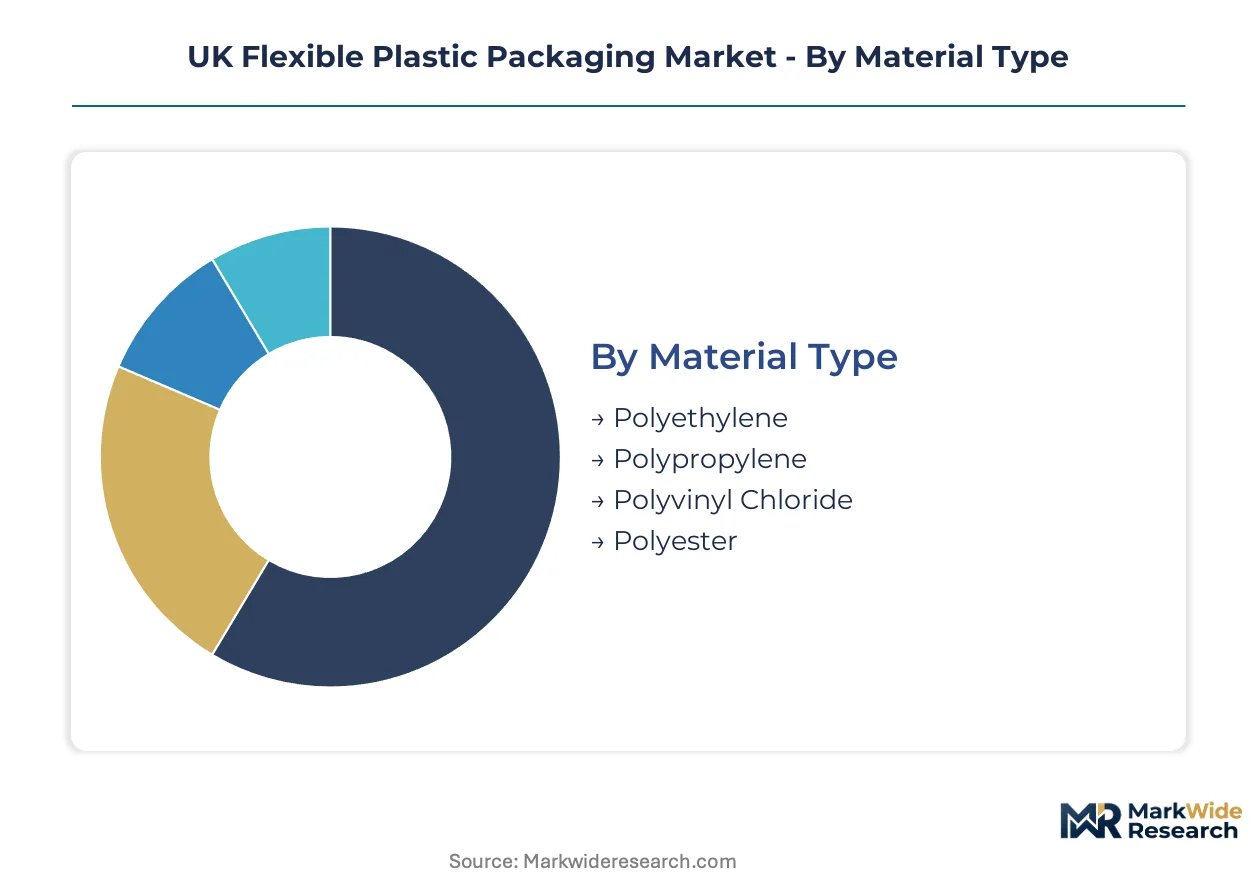
Segmentation in UK flexible plastic packaging reveals how material specifications, regulatory compliance tiers, and format economics intersect to determine margin capture. Understanding these axes helps stakeholders align product portfolios with the Plastic Packaging Tax's recycled-content thresholds and retailer recyclability mandates.
Material Type:
Polymer selection governs barrier performance, heat-seal characteristics, and sortation compatibility in UK recycling infrastructure.
- Polyethylene:Linear low-density and high-density grades dominate food-contact applications due to cost-performance balance and established mechanical recycling pathways. DEFRA's packaging waste regulations favor this polymer for mono-material pouch conversions in England's Midlands packaging corridor, though post-consumer recycled flake scarcity elevates input costs.
- Polypropylene:Cast and oriented films deliver superior clarity and moisture barrier for premium ready-meal lids and pharmaceutical blister lidding. Biaxially oriented variants capture margin in healthcare sterilization-grade specifications where ISO 13485 validation creates defensive positioning.
- Polyvinyl Chloride:Shrinking presence in food-contact segments due to migration testing complexity and retailer sustainability pledges; residual demand concentrates in industrial shrink-wrap applications with lower regulatory scrutiny.
- Polyester:Metallized and clear grades serve high-barrier snack and pet-food segments; incompatibility with polyethylene recycling streams limits adoption in tax-compliant formats despite excellent oxygen barrier performance.
Polyethylene leads on scale; polypropylene leads on momentum.
Application:
End-use requirements dictate validation intensity, barrier complexity, and compliance cost allocation across the value chain.
- Food Packaging:Ambient, chilled, and frozen subsegments drive volume through pouch-based ready-meal conversions and modified-atmosphere tray lidding. Retailer consolidation at Tesco, Sainsbury's, and Morrisons compresses supplier leverage while mandating demonstrable recyclability pathways.
- Healthcare Packaging:Sterilization-grade barriers for pharmaceutical and medical device applications command premium pricing through regulatory validation moats. ISO 13485-certified cleanroom production requirements limit qualified supplier pools.
- Personal Care Packaging:Sachets and flow-wrap formats for cosmetics and toiletries face pressure from water-based ink transitions and gravure line retrofitting costs for food-contact compliance migration.
- Industrial Packaging:Stretch film and shrink-wrap applications tolerate higher recycled-content inclusion with less stringent migration testing, capturing cost advantage under Plastic Packaging Tax thresholds.
Food Packaging anchors volume concentration; Healthcare Packaging sustains margin defense.
Product Form:
Format engineering determines cube efficiency, shelf-life extension, and post-consumer sortation compatibility.
- Pouches:Stand-up and flat formats absorb functionality from rigid trays in ready-meal and pet-food segments, reducing transport cube and refrigeration intensity. Mono-material polyethylene structures are climbing the fastest as retailers mandate simplified polymer streams.
- Films:Cast, blown, and oriented substrates serve as primary web for lamination or single-ply barrier applications; digital watermark integration in HolyGrail 2.0 pilots targets automated sortation of flexible packaging.
- Bags:Wicketed and loose-fill formats for ambient groceries and produce retain commodity positioning with limited differentiation beyond recycled-content certification.
- Wraps:Cling film and stretch wrap applications in food service and industrial logistics face substitution pressure from paper-based alternatives in premium retail channels.
Pouches command strategic investment; films retain infrastructure lock-in.
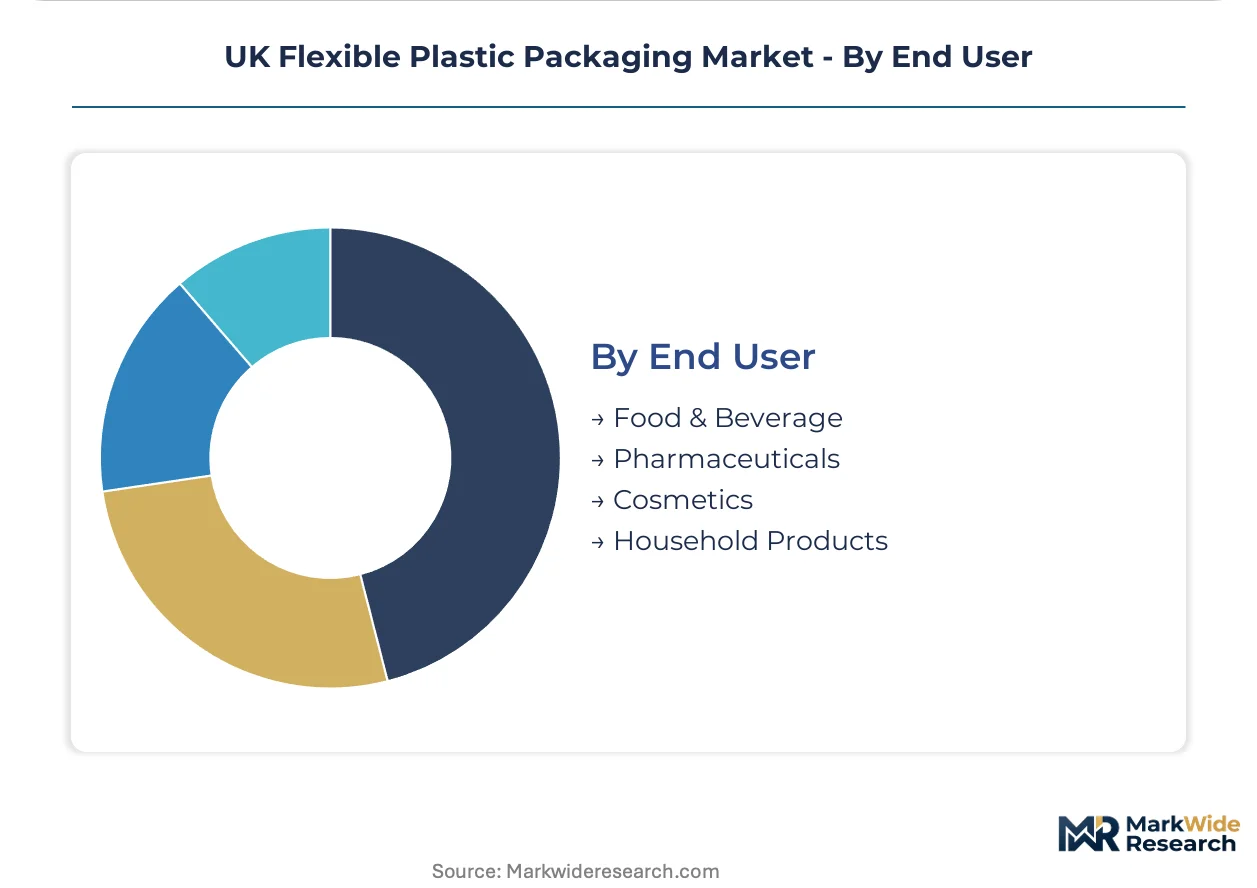
End User:
Customer procurement sophistication and compliance burden vary sharply across sector concentration and regulatory exposure.
- Food & Beverage:Manufacturers of shelf-stable proteins, prepared vegetables, and ambient sauces drive pouch conversion demand while facing direct retailer sustainability audit requirements. Extended producer responsibility frameworks escalate compliance cost allocation to brand owners.
- Pharmaceuticals:Drug packaging and medical device manufacturers impose sterilization-grade barrier specifications and batch-level traceability that smaller converters struggle to resource.
- Cosmetics:Premium and mass-market beauty brands demand high-impact printing and shaped pouch differentiation, though sustainability pledges are accelerating format simplification trials.
- Household Products:Detergent and cleaning product manufacturers prioritize cost minimization in refill pouch formats, tolerating lower barrier performance for non-sensitive chemistries.
Food & Beverage concentrates procurement volume; Pharmaceuticals sustain specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer technologists and converting specialists concentrate in England's central belt, anchoring the UK's flexible packaging capacity. The Midlands packaging corridor draws film extrusion, printing, and laminating operations into tight geographic clusters. Regional disparities in recycling infrastructure and regulatory enforcement intensity shape investment flows across the constituent nations.
England — Midlands
Food manufacturers operating from Birmingham and Leicester drive pouch conversion demand for ready-meal lines. HM Revenue & Customs administers Plastic Packaging Tax compliance audits that elevate documentation burdens for converters in Derbyshire and Nottinghamshire. The M1 corridor hosts clustered film extrusion and converting capabilities that minimize logistics friction between raw material intake and finished goods dispatch.
England — Greater London and Southeast
Pharmaceutical packaging demand from Slough and Cambridge science parks sustains sterilization-grade barrier specifications. The Environment Agency enforces extended producer responsibility frameworks that reshape cost allocation for brand owners headquartered in the capital. Dartford and Thurrock host import-dependent converting operations tethered to continental European resin supply chains.
Scotland
Whisky and seafood exporters in the Highlands and Grampian regions generate specialized barrier film requirements for premium food products. Scottish Environment Protection Agency oversight of packaging waste regulations runs parallel to UK-wide DEFRA frameworks. Glasgow and Edinburgh host smaller-scale converting operations serving local food manufacturing and personal care formulators.
Wales
Industrial stretch-wrap and shrink-film applications in South Wales manufacturing corridors tolerate higher recycled-content inclusion with less stringent migration testing. Natural Resources Wales coordinates with HM Revenue & Customs on Plastic Packaging Tax enforcement at ports handling Irish Sea freight. Newport and Cardiff host converting operations serving automotive component suppliers and building materials distributors.
Northern Ireland
Cross-border food supply chains with the Republic of Ireland create dual-jurisdiction compliance complexity for flexible packaging users. The Northern Ireland Environment Agency applies UK packaging waste regulations while Irish Sea trade protocols affect resin sourcing economics. Belfast and Londonderry host converting capacity serving local dairy and meat processing operations with limited export orientation.
UK Flexible Plastic Packaging Market Competitive Landscape
The competitive structure tilts toward integrated multinational groups with captive resin sourcing and regional mid-cap specialists with format-specific expertise. Berry Global, Amcor PLC, and Mondi PLC anchor the top tier through scale advantages in film extrusion and converting. Mid-cap domestic players occupy niche positions in healthcare sterilization barriers and retail-ready pouch formats. Capacity expansion into certified recycled-content compounding and strategic partnerships with retailer buying desks represent the dominant competitive moves reshaping supplier relationships.
Among UK-based and European-anchored specialists, Sirane Limited and PB Polybags Co. UK occupy positions within the regional mid-cap tier serving food-contact and industrial applications. Tyler Innovative Packaging and Surepak Innovative Packaging exemplify format-focused operations concentrated in England's central belt. Constantia Flexibles and ALPA Group represent continental European groups with UK converting footprint, while Berry Global, Amcor PLC, and Mondi PLC anchor multinational presence through integrated film and converting assets. These named entities illustrate the market's bifurcation between scale-driven polymer processors and agility-focused regional converters.
| Leading Market Players |
|---|
| Berry Global |
| Sirane Limited |
| Amcor PLC |
| Surepak Innovative Packaging Solutions |
| Constantia Flexibles |
| Tyler Innovative Packaging |
| PB Polybags Co. UK |
| ALPA Group |
| Mondi PLC |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap converters in England's Midlands packaging corridor anchor supply-side discipline through generational capital allocation that resists short-term pricing pressure from Asian import competition. This ownership pattern preserves relationship-based contracting with Tesco and Sainsbury's buying desks while funding gradual backward integration into certified recycled-content compounding.
Pricing Analysis
Bundled procurement contracts that combine film extrusion, printing, and converting services command modest premiums over unbundled component sourcing from separate specialists. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification status and volume scale commitments. Cost compression in standard-grade polyethylene pouches is intensifying because retailer sustainability audits now disqualify non-compliant suppliers. Small-format pet-food converters exhibit the highest price sensitivity, while pharmaceutical barrier film buyers prioritize validation reliability over unit cost.
Supply Chain Analysis
BSI PAS 2050 certification gates supplier qualification for tax-compliant recycled-content verification, forcing converters to document mass-balance protocols through specialized audit firms. Raw material sourcing draws from Saudi ethane-based polyethylene, Belgian mechanical recycling flake, and domestic North Sea natural gas feedstock. Single-source vulnerability concentrates in imported post-consumer recycled flake where UK mechanical recycling capacity lags demand. Distribution runs through the M1 corridor's clustered converting operations before final dispatch to retailer regional distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Flexible Plastic Packaging Market functions as a stable compounder where regulatory compliance costs create durable competitive moats that compound returns for prepared operators. DEFRA's extended producer responsibility frameworks ensure steady demand migration toward circular-ready formats.
For Market Incumbents: Acquire mechanical recycling assets in the Midlands corridor to secure captive supply of BSI-certified recycled flake and neutralize input cost volatility from Asian import competition. Invest in mono-material polyethylene R&D to defend pouch market share against aluminum-based substitute formats. Prioritize ISO 13485 cleanroom certification for healthcare barrier production to sustain margin pools. For New Entrants and Emerging Players: The Plastic Packaging Tax in the UK opens a window for specialized audit service providers that can deliver BSI PAS 2050 mass-balance certification to smaller converters lacking internal compliance resources. Target industrial stretch-wrap segments in South Wales manufacturing corridors where migration testing requirements remain less stringent. Pursue direct partnerships with Morrisons and Aldi buying desks for private-label ambient sauce pouch contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among non-certified mid-cap converters facing imminent compliance cost escalations that will force distressed sales to integrated multinationals. The five-to-ten-year viability window favors operators with captive recycled-content supply and retailer sustainability audit credentials. Monitor HolyGrail 2.0 digital watermark deployment velocity as the signal indicating which converting technologies will capture automated sortation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Assets | Captive supply of BSI-certified flake insulates margins from import volatility. |
| Mono-Material Pouch Development | Simplified polymer structures satisfy Tesco recyclability mandates without barrier sacrifice. |
| Healthcare Cleanroom Certification | ISO 13485 validation creates defensive moats against commodity polyethylene competition. |
| Digital Watermark Integration | HolyGrail 2.0 pilot participation positions converters for automated sortation premiums. |
| Retailer Buying Desk Partnerships | Direct contracts with Sainsbury's procurement disintermediate legacy distributor relationships. |
Research Methodology
Multiple input streams — primary interviews with polymer technologists and converting specialists, secondary validation through HM Revenue & Customs enforcement disclosures and DEFRA regulatory filings, and trade flow analysis from UK customs records — were reconciled through bottom-up and top-down triangulation. Conversations with film extrusion plant managers, procurement leads at ready-meal manufacturers, sustainability officers at major retailers, and compliance auditors at BSI certification bodies informed operational assumptions. Secondary sources included Environment Agency enforcement data, British Plastics Federation industry surveys, and SEC filings from listed packaging multinationals.
Data-stream reconciliation across material type, product form, application segment, and geographic production cluster enabled granular volume and value modeling throughout the forecast period. The analytical framework incorporated polymer grade tier, end-use regulatory exposure, format recyclability compatibility, and regional infrastructure maturity as segmentation dimensions. CAGRs were derived from trend extrapolation of historical conversion rates, tax-threshold compliance trajectories, and retailer sustainability pledge implementation timelines. Industry-specific inputs included post-consumer recycled flake import dependence ratios and Midlands packaging corridor capacity utilization estimates.
Revisions become necessary when HM Revenue & Customs tightens documentation requirements beyond current BSI protocols, when HolyGrail 2.0 digital watermark deployment accelerates automated sortation economics, or when natural gas feedstock shocks transmit into resin pricing volatility that alters converter margin structures. A model refresh is warranted upon material change in DEFRA's modulated fee structures under extended producer responsibility implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Russia Flexible Plastic Packaging Market
Flexible Packaging
Flexible Packaging Paper Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Indonesia Flexible Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Latin America Flexible Plastic Packaging Market
Flexible Packaging
Mexico Flexible Plastic Packaging Market
Flexible Packaging
Asia-Pacific Flexible Plastic Packaging Market
Flexible Packaging
Indonesia Flexible Plastic Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Flexible Bottle Market
Flexible Packaging
Morocco Flexible Packaging Market