
 Global Temperature Control Units (TCU) Market | 2026-2036
Global Temperature Control Units (TCU) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Temperature Control Units (TCU) Market Outlook
The EU Green Deal is consolidating demand for low-GWP refrigerant systems across European process industries. Toshiba Machine leverages its precision compressor technology to anchor market position in high-stability pharmaceutical applications. Mokon Systems competes through specialized oil-cooled architectures for polymer processing, while Carel Industries extends its digital control portfolio into cloud-connected TCU management platforms.
Temperature Control Units are closed-loop thermal management systems that regulate process fluid temperatures within ±0.1°C tolerance using compressor-based or heat-exchange architectures, primarily maintaining optimal reaction conditions in extrusion, molding, and chemical synthesis operations. Water-cooled configurations dominate large-scale chemical installations where facility chilled water infrastructure exists, while PID control technology leads unit shipments due to its proven stability in continuous manufacturing environments. Oil-cooled systems occupy a narrower but defensible niche in high-temperature polymer applications where thermal fluid degradation risks exclude water-based alternatives.
The US EPA SNAP program and Japan METI refrigerant transition guidelines are reshaping product certification requirements, with both agencies restricting high-GWP working fluids in new industrial equipment. China's GB standards for energy-efficient refrigeration systems and the EU F-Gas Regulation collectively compress the allowable refrigerant portfolio, forcing manufacturers to redesign heat-exchange circuits around approved alternatives. Stakeholders must monitor refrigerant phase-down schedules and regional certification divergence when configuring global product platforms.
Market Dynamics
The EU F-Gas Regulation is forcing a refrigerant transition across European chemical plants, compressing allowable working fluids and triggering equipment redesign cycles while pharmaceutical manufacturers simultaneously expand bioreactor temperature management installations.
Growth Catalysts
- Bioreactor expansion:Pharmaceutical manufacturers are scaling temperature control infrastructure for cell culture and fermentation processes, with single-use bioreactor adoption driving demand for precise thermal stability systems.
- REACH compliance:The EU's chemical safety framework is accelerating equipment replacement cycles as processors retrofit legacy units to meet evolving substance restrictions and environmental performance thresholds.
- Precision engineering clusters:Germany's concentration of high-specification manufacturing is concentrating premium water-cooled unit procurement, with localized supply chains reducing lead times for custom-configured systems.
Market Restraints
- Refrigerant cost volatility:Hydrofluorocarbon phase-down schedules under the EU F-Gas Regulation are compressing supply of legacy working fluids, forcing processors to absorb premium pricing for approved low-GWP alternatives.
- Copper supply concentration:Heat-exchanger manufacturing depends on concentrated Chilean and Peruvian copper output, exposing TCU producers to concentrate supply disruptions and London Metal Exchange price swings.
- Temperature ceiling limitations:Water-based systems face thermal degradation barriers above 200°C, excluding them from high-temperature polymer applications where oil-cooled architectures dominate despite higher maintenance burdens.
Strategic Opportunities
- Cloud-connected platforms:Digital control integration with predictive maintenance algorithms is opening recurring revenue streams as processors seek to minimize unplanned downtime in continuous manufacturing environments.
- India's PLI scheme:Production-linked incentives for pharmaceutical and chemical manufacturing are attracting greenfield facility investments requiring new temperature control infrastructure across Maharashtra and Gujarat industrial corridors.
- Japan METI guidelines:Refrigerant transition timelines are creating certified equipment upgrade windows as domestic processors align with national decarbonization roadmaps for industrial refrigeration systems.
Industry Challenges
- Refrigerant certification timelines:EPA SNAP and Japan METI approval pathways for alternative working fluids extend 18-36 months, delaying product launches and compressing competitive windows for redesigned heat-exchange circuits.
- Legacy system integration:Brownfield chemical plants require custom interface engineering to connect modern PID-controlled TCUs with existing distributed control systems, extending commissioning cycles and eroding margin on retrofit projects.
- Specialized technician scarcity:Low-GWP refrigerant handling certification and precision compressor maintenance skills are concentrating in regional training centers, constraining field service expansion and aftermarket revenue capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Temperature Control Units (TCU) Market |
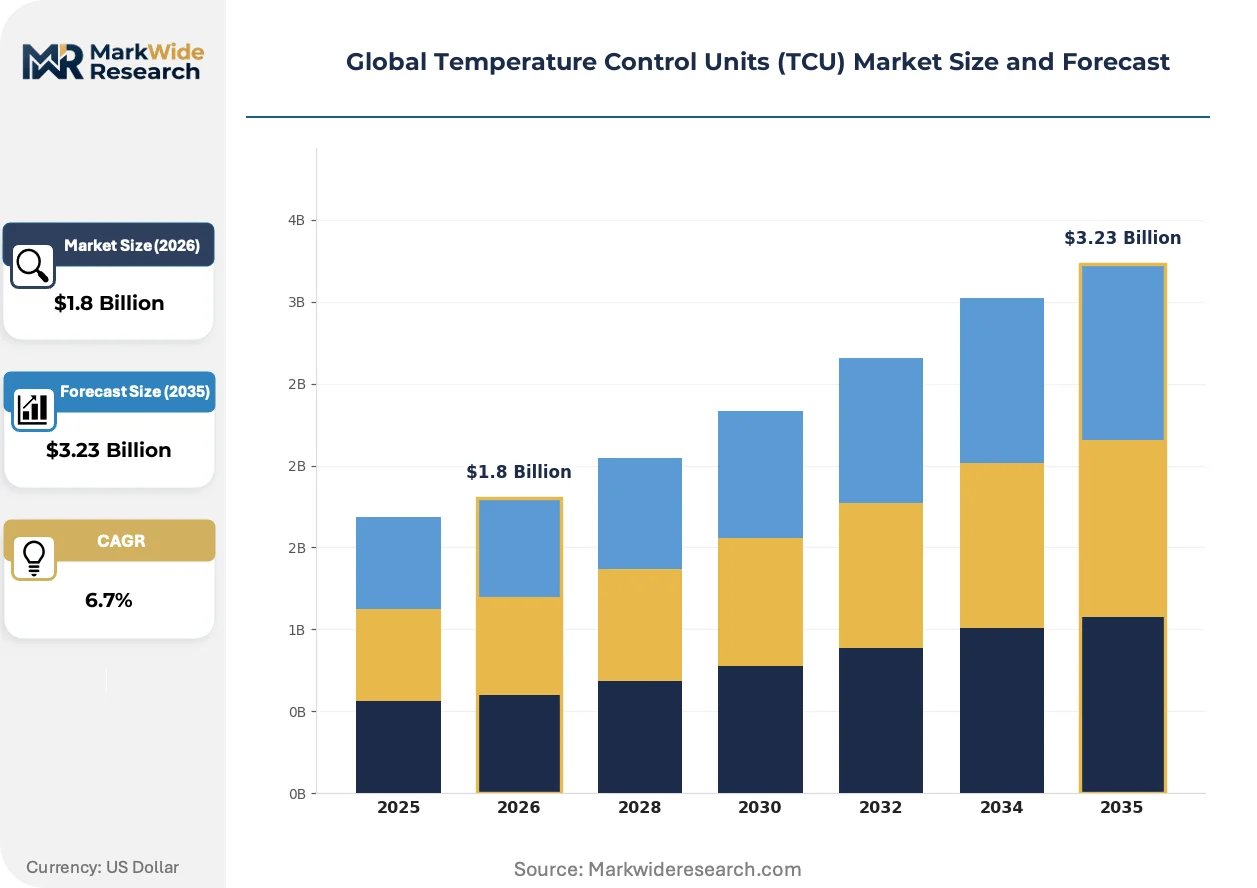
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Oil-Cooled, Hybrid Industry Vertical: Pharmaceuticals, Chemicals, Food Processing, Plastics Capacity: Small Scale, Medium Scale, Large Scale, High Capacity Control Technology: PID Control, PLC Control, Digital Control, Manual Control |
| Companies Covered | Toshiba Machine, Mokon Systems, Carel Industries, Advantage Engineering, Temptek, WIKA Instrument, Thermal Care Inc., ACS Group, HB-Therm GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Temperature Control Units (TCU) Market Strategic Shifts
Refrigerant chemistry transitions and digital control architectures are compressing traditional equipment design cycles while reshaping how processors procure and operate thermal management systems across pharmaceutical and chemical operations.
Variable-speed compressor technology is consolidating market share in pharmaceutical applications requiring ±0.1°C stability. Biologics manufacturers are specifying these units for cell culture processes where thermal drift compromises batch yields. The technology is consolidating demand around suppliers with in-house precision compressor capabilities, marginalizing fixed-speed alternatives in high-value segments.
The EU F-Gas Regulation mandates an 80% hydrofluorocarbon phase-down by 2030, forcing heat-exchange circuit redesigns around CO2, ammonia, and hydrofluoroolefin alternatives. Chemical processors in Germany and the Netherlands face accelerated retrofit obligations as national implementation exceeds baseline EU timelines. Equipment vendors are responding with modular refrigerant platforms enabling field conversion as approval pathways mature.
Service unbundling is fragmenting traditional procurement patterns as processors separate capital equipment acquisition from long-term maintenance contracts. Pharmaceutical multinationals in Switzerland and Ireland are piloting performance-based thermal management agreements where vendors guarantee uptime in exchange for per-batch fees. This model shifts balance-sheet classification and compresses vendor working capital cycles while aligning incentives around operational outcomes rather than hardware specifications.
Global Temperature Control Units (TCU) Market Segmentation
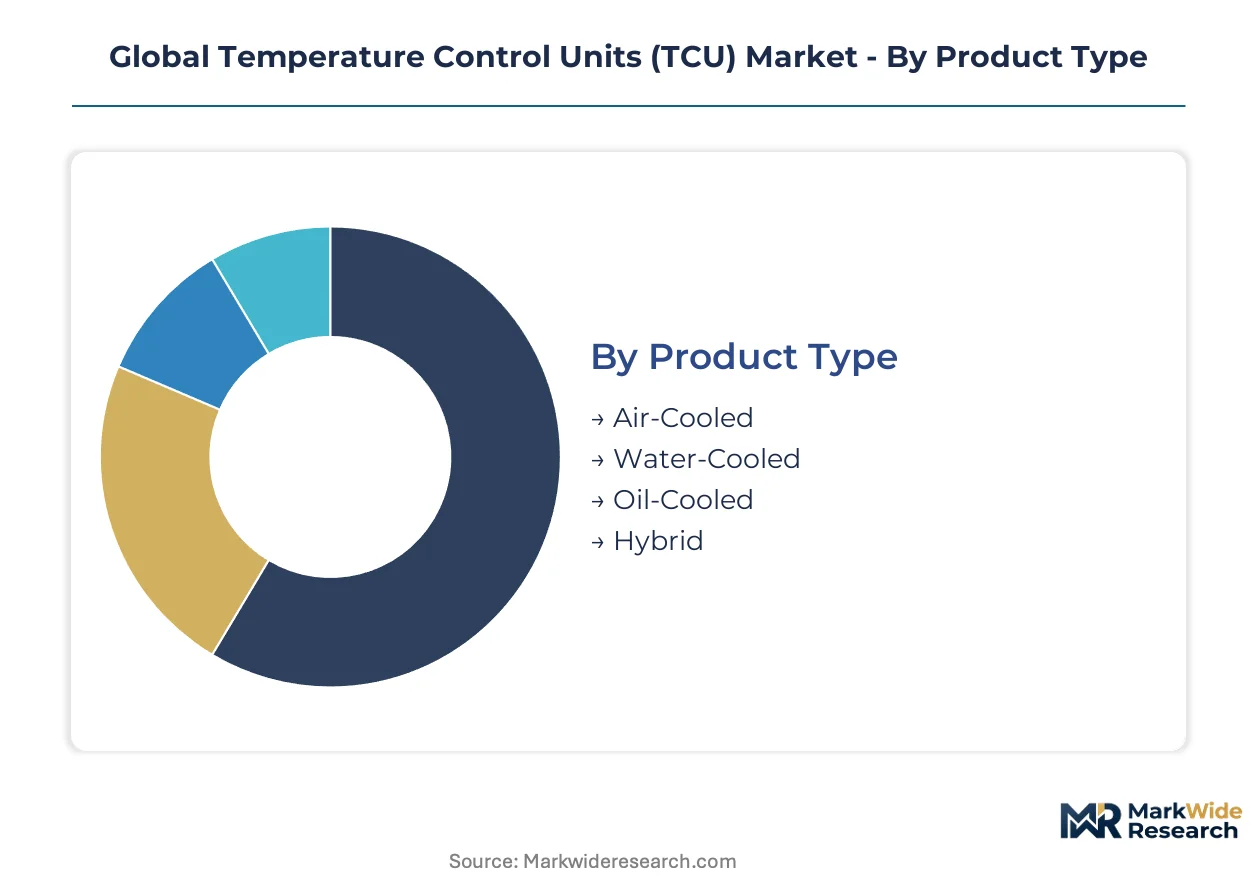
TCU procurement patterns diverge sharply across cooling architectures and control sophistication, with regulatory refrigerant mandates and bioreactor thermal stability requirements reshaping upgrade priorities. Pharmaceutical and chemical end-users are reconfiguring capital allocation around precision control capabilities and low-GWP refrigerant compatibility.
Product Type:
Replacement cycles are accelerating as EU F-Gas Regulation deadlines force equipment turnover across European chemical installations, compressing the window for legacy refrigerant system operation.
- Water-Cooled:These units leverage facility chilled water infrastructure to achieve higher heat rejection capacity with lower compressor load. Demand concentrates in Germany's precision engineering clusters, where pharmaceutical multinationals specify premium configurations for bioreactor temperature management within ±0.1°C tolerance.
- Oil-Cooled:Thermal fluid architectures operate above 200°C without degradation risks that exclude water-based alternatives. Polymer processors in high-temperature extrusion applications favor these systems despite elevated maintenance burdens and specialized technician requirements.
- Air-Cooled:Self-contained refrigeration circuits eliminate dependence on facility water infrastructure, suiting distributed manufacturing footprints and mobile process configurations.
- Hybrid:Dual-mode architectures switch between air and water rejection based on ambient conditions and facility load, optimizing energy consumption across seasonal variation.
Volume placements concentrate in water-cooled configurations; the faster expansion belongs to hybrid systems as processors seek operational flexibility under volatile energy pricing.
Industry Vertical:
Cost tier differentiation separates validated pharmaceutical systems from standard industrial equipment, with certification overhead creating substantial price stratification across end-use categories.
- Pharmaceuticals:Cell culture and fermentation processes demand continuous thermal stability where drift compromises batch yields. Single-use bioreactor adoption is driving specification of variable-speed compressor units with cloud-connected predictive maintenance platforms.
- Chemicals:Synthesis operations and reactor temperature management require robust heat-exchange capacity across aggressive process fluids. REACH compliance obligations are accelerating replacement of legacy units that fail evolving substance restriction thresholds.
- Food Processing:Pasteurization and crystallization applications prioritize sanitary design and rapid temperature transition capabilities.
- Plastics:Extrusion and molding operations favor oil-cooled architectures for high-temperature polymer processing where water-based systems face thermal ceiling constraints.
Revenue concentration sits with pharmaceutical applications; plastics processing is climbing the fastest as polymer capacity expands across India's PLI-supported industrial corridors.
Capacity:
Customer type segmentation separates batch pharmaceutical manufacturers from continuous chemical processors, with scale requirements dictating compressor architecture and heat-exchange surface area.
- Large Scale:Multi-reactor chemical installations specify centralized TCU farms with redundant capacity and distributed control integration. Brownfield plants in the Netherlands face extended commissioning cycles as custom interface engineering connects modern PID systems to legacy distributed control architectures.
- Medium Scale:Flexible batch operations balance capital efficiency against thermal load variability, favoring modular configurations with field-expandable capacity.
- Small Scale:Pilot plant and R&D applications prioritize rapid reconfiguration and compact footprint over absolute efficiency metrics.
- High Capacity:Integrated petrochemical and specialty chemical complexes demand custom-engineered solutions with specialized metallurgy for corrosive process streams.
Margin capture is strongest in high capacity systems; small scale units are gaining share fastest through distributed biologics manufacturing and contract research organization expansion.
Control Technology:
Supply concentration in precision compressor manufacturing is elevating the strategic importance of control system integration, with digital platforms enabling recurring revenue through predictive maintenance subscriptions.
- PID Control:Proportional-integral-derivative algorithms deliver proven stability in continuous manufacturing environments through decades of industrial validation. Pharmaceutical manufacturers in Switzerland and Ireland specify these systems for cell culture processes where thermal drift directly impacts batch economics.
- Digital Control:Cloud-connected architectures with predictive maintenance algorithms are opening performance-based thermal management agreements. Vendors guarantee uptime in exchange for per-batch fees, shifting balance-sheet classification and compressing working capital cycles.
- PLC Control:Programmable logic controllers offer robust integration with existing plant automation hierarchies and familiar troubleshooting protocols for maintenance technicians.
- Manual Control:Basic thermostat and relay architectures persist in cost-sensitive applications with limited precision requirements and low utilization rates.
Shipment volumes favor PID configurations; digital control platforms are expanding most quickly as pharmaceutical multinationals pilot outcome-based service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor concentration drives German procurement intensity for precision water-cooled units serving pharmaceutical bioreactor installations. The EU F-Gas Regulation compresses refrigerant options across European chemical processing, while India's PLI scheme accelerates greenfield capacity in western industrial corridors.
Germany
Precision engineering clusters in Baden-Württemberg and Bavaria concentrate premium TCU demand for bioreactor temperature management within ±0.1°C tolerance. The EU F-Gas Regulation mandates 80% hydrofluorocarbon phase-down by 2030, forcing heat-exchange circuit redesigns. BASF and Bayer facilities in Ludwigshafen and Leverkusen face accelerated retrofit timelines exceeding baseline EU requirements.
United States
Pharmaceutical multinationals in Massachusetts and North Carolina expand cell culture infrastructure requiring variable-speed compressor stability. The EPA SNAP program restricts high-GWP working fluids in new industrial equipment certification pathways. Biologics manufacturing corridors around Boston and Research Triangle Park specify cloud-connected predictive maintenance platforms.
India
Production-linked incentives for pharmaceutical and chemical manufacturing attract greenfield investments across Maharashtra and Gujarat industrial corridors. The BIS energy efficiency framework and CDSCO validation requirements shape equipment specifications. Contract research organizations in Hyderabad and Ahmedabad drive small-scale unit procurement for distributed biologics manufacturing.
China
GB standards for energy-efficient refrigeration systems compress allowable refrigerant portfolios alongside national dual carbon goals. Yangtze River Delta chemical complexes retrofit legacy installations to meet evolving environmental performance thresholds. Shanghai and Ningbo processors balance REACH-equivalent substance restrictions with continuous manufacturing scale requirements.
Japan
Domestic pharmaceutical manufacturers align equipment upgrades with METI refrigerant transition timelines for industrial refrigeration decarbonization. Osaka and Nagoya industrial zones concentrate demand for validated systems serving fermentation processes. Precision compressor technology suppliers anchor market position through in-house capabilities for high-stability applications.
Global Temperature Control Units (TCU) Market Competitive Environment
The competitive structure tilts toward precision compressor specialists with in-house manufacturing capabilities. Market concentration elevates around suppliers delivering ±0.1°C stability for bioreactor applications, while regional fabricators compete on retrofit responsiveness. Two dominant archetypes emerge: integrated precision engineering conglomerates and specialized thermal management independents. Capacity expansion and refrigerant platform modularization constitute the primary competitive vectors as vendors prepare for low-GWP transition windows.
Among precision engineering conglomerates, Toshiba Machine exemplifies the integrated archetype through captive compressor technology development. Specialized independents including Mokon Systems and Carel Industries occupy positions emphasizing application-specific architectures and digital control platform extension respectively. HB-Therm GmbH represents the German Mittelstand fabrication model with regional proximity to Ruhr chemical processing demand. These three company types illustrate the competitive spectrum without exhaustively mapping market share distribution.
| Leading Market Players |
|---|
| Toshiba Machine |
| Mokon Systems |
| Carel Industries |
| Advantage Engineering |
| Temptek |
| WIKA Instrument |
| Thermal Care Inc. |
| ACS Group |
| HB-Therm GmbH |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by restricting refrigerant portfolios to approved low-GWP alternatives, compressing vendor margins on legacy system retrofits while elevating certified equipment premiums. Pharmaceutical manufacturers absorb these cost premiums for validated bioreactor systems, whereas chemical processors face sharper trade-offs between compliance timelines and capital allocation.
Pricing Analysis
Outcome-based thermal management agreements anchor value-based pricing, with vendors guaranteeing uptime in exchange for per-batch fees rather than hardware markups. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical systems with FDA-tier certification from industrial-grade equipment and basic retrofit configurations. Cost compression in standard-tier units is intensifying because REACH compliance obligations accelerate replacement cycles without corresponding budget expansion. Contract research organizations in distributed biologics manufacturing exhibit highest price sensitivity, while single-use bioreactor adopters in Switzerland and Ireland demonstrate lowest sensitivity due to batch yield economics.
Supply Chain Analysis
Precision compressor manufacturing rests on concentrated Japanese and German specialty engineering capabilities, with variable-speed technology suppliers anchoring market position through captive in-house production. Heat-exchanger fabrication draws from Chilean and Peruvian copper concentrate, Taiwanese electronic control components, and Italian precision valve assemblies. Single-source vulnerability concentrates in low-GWP refrigerant supply chains where EU F-Gas phase-down schedules compress allowable working fluid portfolios faster than alternative production scales. Distribution runs through authorized regional service networks with certified technician training requirements, constraining aftermarket expansion for unqualified entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation creates a cost-of-compliance barrier-to-entry moat, elevating incumbent advantages through refrigerant certification investments that new entrants cannot replicate within viable commercialization windows.
For Market Incumbents: Anchor market position through backward integration into precision compressor manufacturing and cloud-connected predictive maintenance platforms. Toshiba Machine exemplifies this defensive posture through captive compressor technology development. Capacity addition in Baden-Württemberg precision engineering clusters reduces lead times for custom-configured pharmaceutical systems. Certification investment in EPA SNAP and Japan METI approval pathways extends competitive exclusion windows against emerging modular refrigerant platform entrants. For New Entrants and Emerging Players: Small-scale contract research organizations in India's PLI-supported industrial corridors represent the most penetrable buyer archetype underserved by incumbent service networks. White-space targets include aftermarket retrofit responsiveness for brownfield chemical plants in the Netherlands facing extended commissioning cycles, and cloud-connected platform unbundling for pharmaceutical multinationals piloting performance-based agreements. Go-to-market angle should emphasize rapid technician certification deployment through regional training center partnerships rather than hardware specification competition. For Investors and Strategic Acquirers: EPA SNAP approval pathway completion for CO2-based heat-exchange circuits is the leading indicator that refrigerant platform modularization has achieved commercial viability, signaling acquisition timing for precision engineering independents. Long-term viability across the analysis window favors suppliers with in-house compressor capabilities and established pharmaceutical validation relationships. Acquisition target archetype: German Mittelstand fabricators with regional proximity to Ruhr chemical processing demand and unexploited digital control platform extension potential. Watch Japan METI guideline acceleration as inflection signal for certified equipment upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Modularization | Enables field conversion to low-GWP alternatives as EPA SNAP and METI pathways mature. |
| Backward Integration into Compressor Manufacturing | Toshiba Machine anchors pharmaceutical market position through captive precision technology. |
| Cloud-Connected Predictive Maintenance Launch | Carel Industries extends digital control portfolio into recurring revenue subscription models. |
| Regional Training Center Partnership Network | Addresses specialized technician scarcity constraining field service expansion in Europe. |
| Performance-Based Thermal Management Agreement Pilot | Swiss and Irish pharmaceutical multinationals shift vendor incentives toward uptime outcomes. |
Study Parameters
Document review covered SEC 10-K filings from precision engineering conglomerates, EU F-Gas Regulation implementation reports, and Japan METI refrigerant transition guidelines, complemented by interviews with plant engineers at BASF and Bayer facilities, procurement leads at pharmaceutical multinationals, and aftermarket service heads at regional TCU distributors. Secondary validation incorporated customs and trade data for copper concentrate flows, ACC and Cefic chemical industry reports, and BIS energy efficiency framework documentation. Bottom-up unit shipment estimates triangulated against top-down capital expenditure analysis across pharmaceutical and chemical manufacturing verticals.
Market size and growth trajectory outputs derived from segmented modeling across cooling architecture, control technology sophistication, industry vertical, and regional regulatory cluster dimensions. CAGRs were computed from annual progression analysis of installed base expansion, replacement cycle acceleration, and greenfield capacity absorption. Industry-specific forecast inputs included single-use bioreactor adoption rates in cell culture processes and EU F-Gas phase-down schedule compliance deadlines.
Revisions become necessary when refrigerant certification timelines extend beyond modeled windows, copper supply disruptions from Chilean and Peruvian concentrate output exceed baseline assumptions, or pharmaceutical batch economics shift thermal stability tolerance requirements. A small set of named triggers warrants ongoing watch: EPA SNAP approval pathway acceleration, India PLI scheme capacity absorption rates, and precision compressor manufacturing capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Global Thick Film Heater Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
North America Industrial Embedded Systems Market